
 Chronic Disease Management Service Market | 2026-2036
Chronic Disease Management Service Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Disease Management Service Market Insights
Buyer concentration is expanding as large health systems and Medicare Advantage plans consolidate purchasing power for outsourced chronic care services. Optum, Inc. leverages its vertically integrated payer-provider model to capture bundled payment contracts across multiple states. Epic Systems anchors hospital-centric deployments with embedded care management workflows. Cognizant competes through scaled remote monitoring infrastructure serving regional payer networks.
Chronic disease management service encompasses coordinated, technology-enabled care programs designed to reduce acute exacerbations and hospitalization risk for patients with diabetes, cardiovascular disease, COPD, and other persistent conditions. These services integrate biometric data streams from wearable devices and telemedicine platforms with clinical decision support to enable proactive intervention. Telehealth and remote monitoring segments lead current revenue generation due to pandemic-accelerated infrastructure investment and sustained reimbursement alignment. Data analytics capabilities differentiate margin pools as payers demand population-level outcome validation and risk-stratification precision from vendor partners.
FDA digital health pre-certification and CMS reimbursement codes for remote therapeutic monitoring directly shape market access and service design requirements for technology-enabled chronic care. HIPAA security standards and state-level telehealth parity laws create compliance complexity that favors vendors with established regulatory operations. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classifications and state Medicaid program expansions of community health worker reimbursement to anticipate competitive positioning requirements.
Market Dynamics
Medicare Advantage penetration is concentrating purchasing power among vertically integrated payers, forcing chronic care vendors to demonstrate measurable hospitalization reductions through biometric-validated outcomes rather than process metrics alone.
Growth Catalysts
- FDA Digital Health Pre-Certification:The FDA's streamlined pathway for software-as-medical-device review accelerates time-to-market for algorithm-driven care protocols, reducing clinical validation costs for remote monitoring platforms.
- Remote Therapeutic Monitoring Reimbursement:CMS-established billing codes now compensate providers for asynchronous data review and care coordination, creating sustainable revenue streams beyond synchronous telehealth encounters.
- Wearable Biometric Proliferation:Continuous glucose monitors and connected inhalers generate real-world data streams that enable predictive risk stratification, embedding chronic disease management into daily patient routines.
Market Restraints
- State Telehealth Parity Fragmentation:Inconsistent reimbursement mandates across state Medicaid programs create operational complexity for multi-state service deployments, favoring vendors with established regulatory infrastructure.
- Interoperability Technical Debt:Legacy EHR systems lacking FHIR-compliant APIs require expensive middleware development, delaying data integration timelines for smaller chronic care platforms.
- Specialist Workforce Scarcity:Certified diabetes educators and cardiac rehabilitation nurses face supply constraints in rural service areas, capping program enrollment velocity regardless of technology readiness.
Strategic Opportunities
- Community Health Worker Expansion:State Medicaid programs in Texas and California now reimburse non-clinical care coordinators for home-based patient engagement, opening lower-cost service delivery models.
- Behavioral Health Integration:CMS guidelines permitting collaborative care model billing for comorbid depression and chronic disease creates reimbursement pathways for combined mental-physical health interventions.
- AI-Augmented Clinical Decision Support:Machine learning algorithms processing continuous vital sign streams enable automated escalation protocols, reducing clinician monitoring burden while maintaining safety thresholds.
Industry Challenges
- Data Privacy Architecture Complexity:HIPAA security rule requirements for business associate agreements and encryption standards demand specialized compliance infrastructure that strains mid-sized vendor resources.
- Outcome Measurement Standardization:Payer contracts require disparate quality metrics—HEDIS, STAR ratings, proprietary risk scores—forcing vendors to maintain multiple reporting systems without unified industry benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Disease Management Service Market |
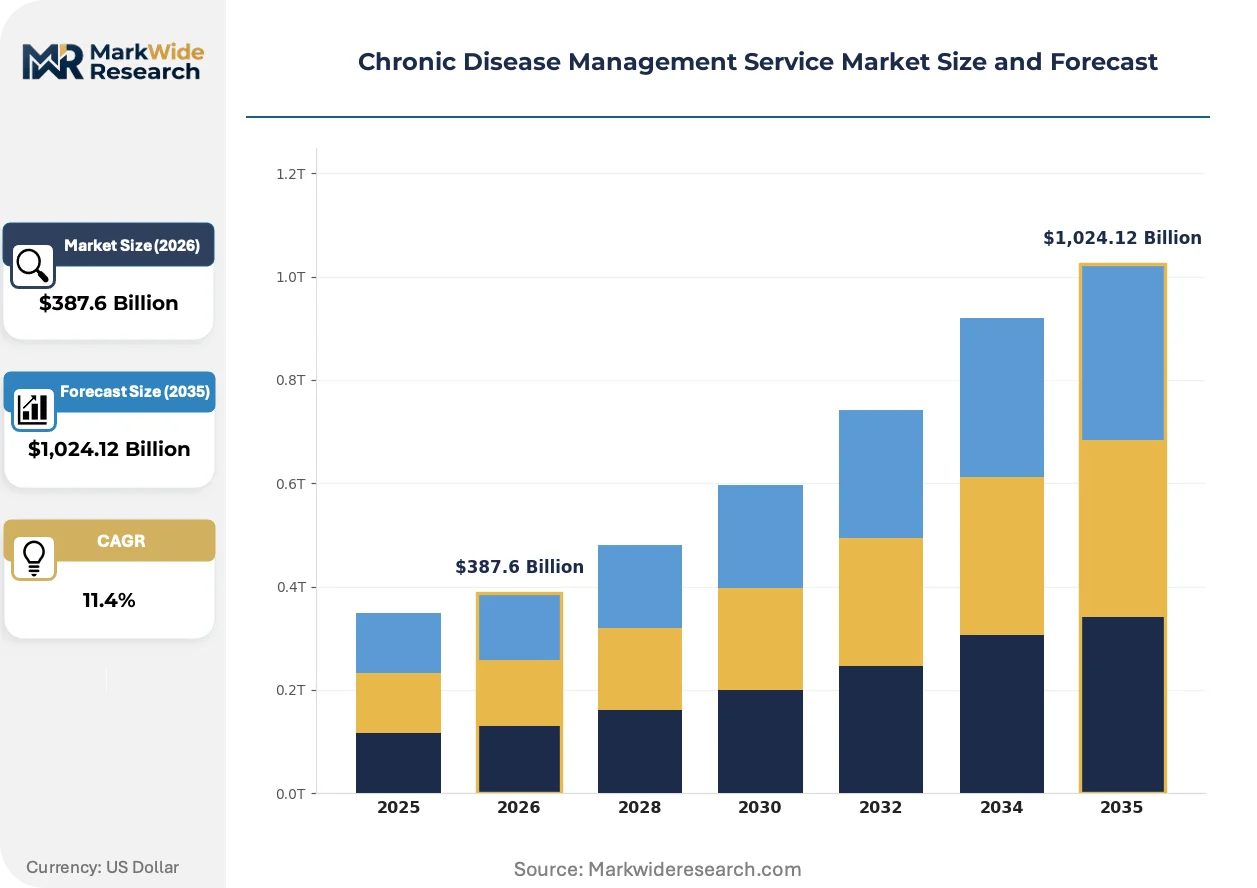
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Telehealth, In-Person Consultation, Remote Monitoring, Personalized Care Technology: Wearable Devices, Mobile Apps, Telemedicine Platforms, Data Analytics End User: Patients, Healthcare Providers, Insurance Companies, Pharmacies Delivery Model: Subscription-Based, Fee-for-Service, Bundled Payment, Pay-as-You-Go |
| Companies Covered | Optum, Inc., ExlService Holdings, Inc., NXGN Management, LLC., Infosys Limited, Cognizant, Epic Systems, IBM, HealthSnap, Veradigm LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Disease Management Service Market Trends and Innovations
Digital therapeutic platforms are embedding prescription-grade interventions directly into chronic care workflows, blurring historical boundaries between medical devices and service delivery while demanding new regulatory navigation capabilities from vendors.
Continuous glucose monitoring paired with automated insulin dosing algorithms is electrifying diabetes management protocols, with endocrinology practices and Medicare Advantage plans accelerating adoption to reduce hypoglycemic emergency admissions. The technology compresses traditional care intervals from quarterly visits to real-time algorithmic adjustments, reallocating clinician capacity toward complex case escalation.
The FDA's Software Precertification Pilot Program is restructuring validation requirements for algorithm-based chronic disease tools, permitting post-market surveillance to substitute for pre-market clinical trials in certain risk categories. This regulatory pathway most benefits cardiovascular risk prediction platforms, which now face compressed development timelines and reduced capital requirements for 510(k) clearance.
Employer-sponsored health plans are unbundling chronic care from traditional medical carrier contracts, contracting directly with specialized vendors for diabetes reversal and musculoskeletal programs. Direct purchasing concentrates in self-insured Fortune 500 employers, who demand guaranteed medical cost reduction contracts rather than per-member-per-month fees.
Chronic Disease Management Service Market Segmentation
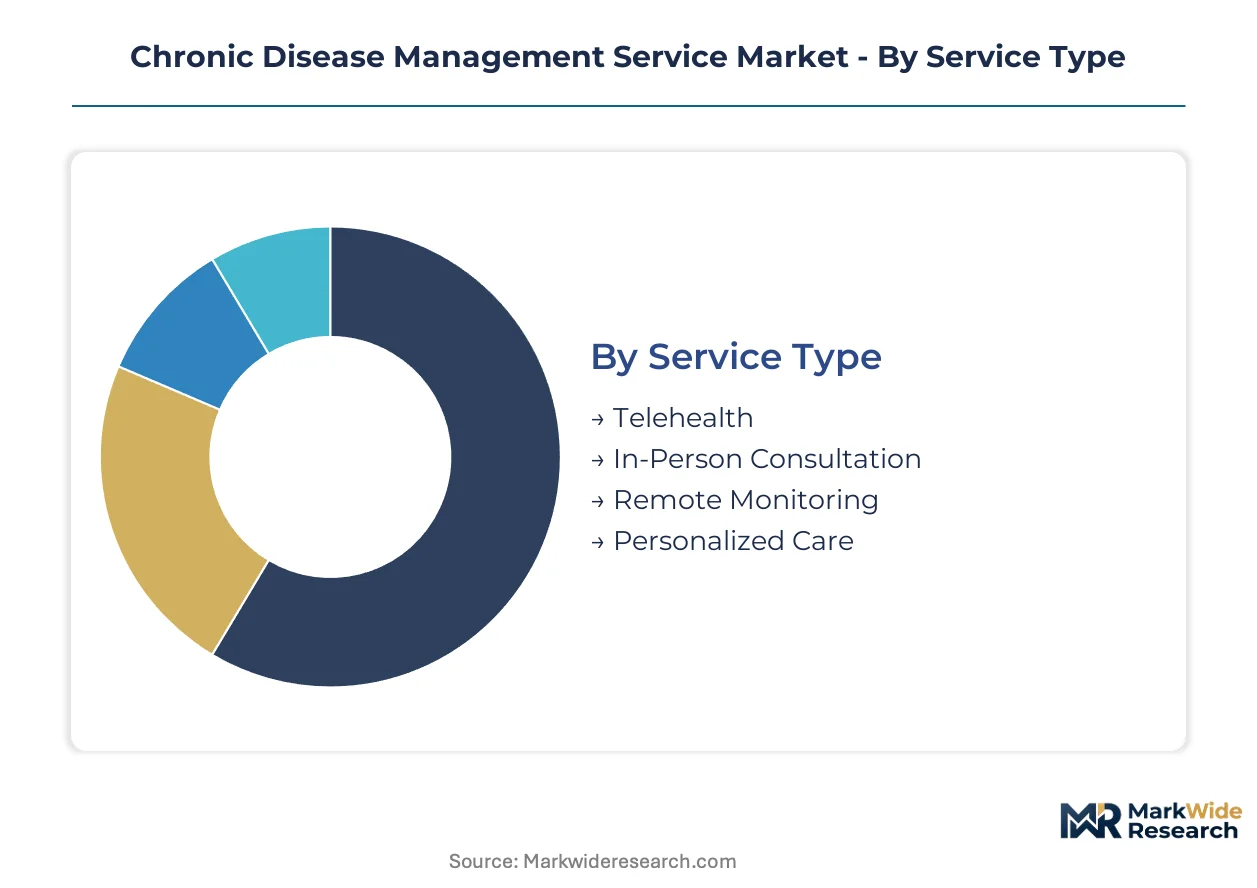
Chronic disease management service segmentation reveals divergent capital requirements across delivery modalities. Technology-enabled segments demand substantial upfront platform investment while traditional service models prioritize workforce scale over infrastructure spend.
Service Type:
Remote Monitoring and Personalized Care command the heaviest capital deployment for sensor hardware and algorithm development, whereas Telehealth and In-Person Consultation rely more heavily on variable labor costs.
- Telehealth:Synchronous video consultation platforms integrate with existing EHR workflows to deliver real-time specialist access. Demand concentrates in Medicare Advantage networks across Florida and Arizona, where rural patient dispersion makes virtual encounters cost-competitive against travel burdens.
- In-Person Consultation:Face-to-face clinical encounters remain essential for complex case triage and physical examination requirements. Cardiology and endocrinology practices in urban hospital systems anchor volume, constrained by specialist availability in secondary markets.
- Remote Monitoring:Continuous biometric data streams from connected devices enable predictive intervention protocols.
- Personalized Care:Algorithm-tailored treatment plans adapt to individual patient trajectories and comorbidity profiles.
Remote Monitoring absorbs the bulk of installed capacity; Personalized Care is expanding most quickly.
Technology:
Hardware-intensive segments require manufacturing partnerships and FDA clearance timelines, while software-only platforms face lower barriers to deployment but higher customer acquisition costs.
- Wearable Devices:Continuous glucose monitors and connected inhalers generate real-world evidence streams for predictive analytics. Deployment concentrates in diabetes management programs where hypoglycemic event reduction justifies device subsidy models.
- Mobile Apps:Patient-facing applications deliver medication reminders, symptom tracking, and educational content with minimal infrastructure overhead. Direct-to-consumer channels and employer wellness programs drive adoption velocity.
- Telemedicine Platforms:Integrated video, scheduling, and documentation systems enable scalable virtual care delivery.
- Data Analytics:Population health engines process claims and biometric data for risk stratification and outcome measurement.
Wearable Devices capture the largest share of hardware investment; Data Analytics is climbing the fastest as payers demand validated outcome metrics.
End User:
Purchasing sophistication varies sharply across stakeholder types, with Insurance Companies demanding population-level ROI documentation while individual Patients prioritize convenience and out-of-pocket cost.
- Patients:Individual consumers select services based on ease of use, out-of-pocket expense, and condition-specific feature depth. Direct-to-consumer diabetes reversal programs and musculoskeletal therapy platforms anchor this segment's expansion.
- Healthcare Providers:Hospital systems and physician practices adopt chronic care management for quality metric improvement and shared savings eligibility. Epic-embedded workflows dominate hospital-centric procurement decisions.
- Insurance Companies:Payers contract for risk-bearing chronic care services with guaranteed medical cost reduction terms.
- Pharmacies:Retail pharmacy chains leverage existing patient touchpoints for medication adherence programs and chronic condition screening.
Healthcare Providers account for the majority of contracted service volume; Insurance Companies are gaining share fastest through value-based arrangement expansion.
Delivery Model:
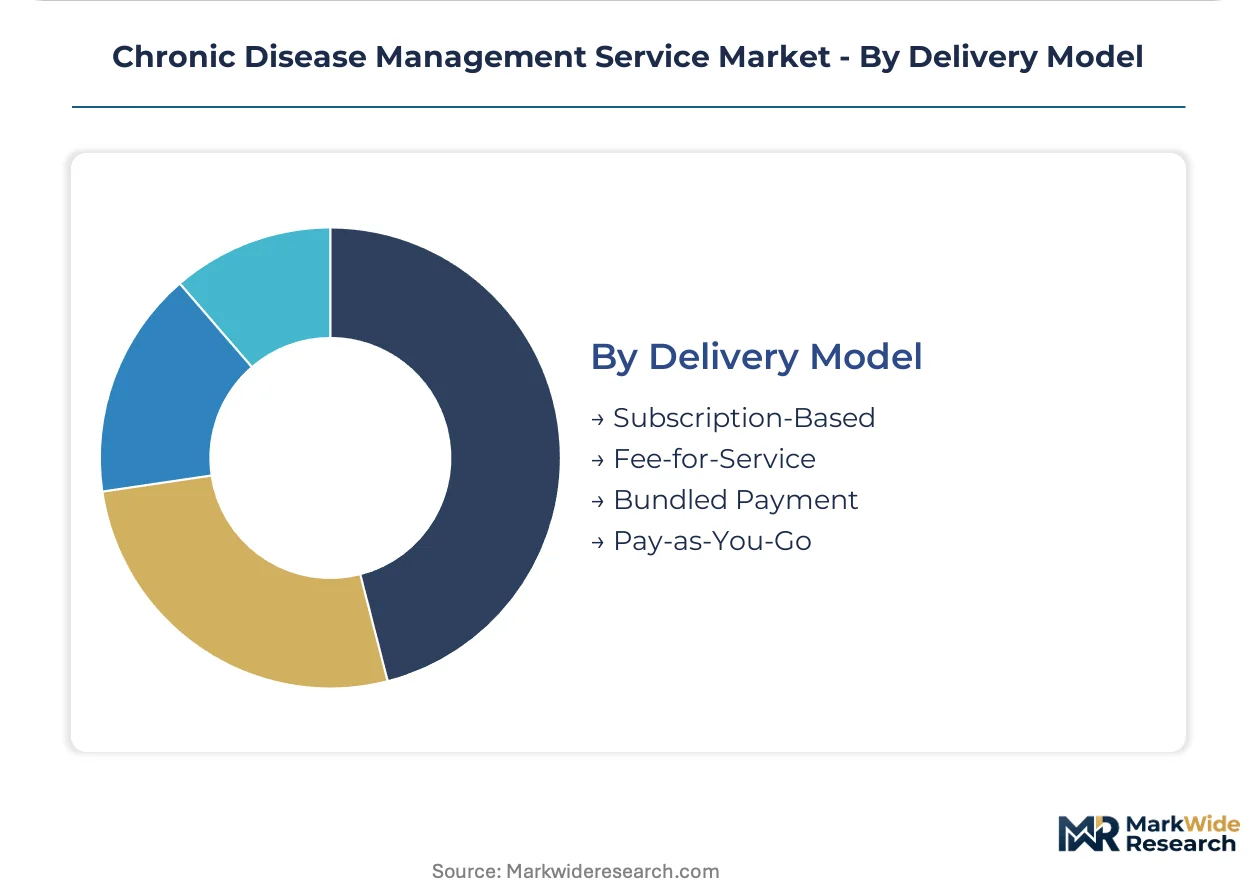
Revenue predictability and working capital requirements diverge across pricing structures, with Subscription-Based models requiring patient retention investment and Bundled Payment arrangements demanding robust cost accounting infrastructure.
- Subscription-Based:Recurring monthly or annual fees provide predictable revenue streams and lower customer acquisition cost amortization. Employer-sponsored chronic disease programs and direct-to-consumer wellness platforms favor this structure for budget certainty.
- Fee-for-Service:Per-encounter billing aligns with traditional reimbursement patterns but creates utilization volume dependency. Medicare remote therapeutic monitoring codes have partially revived this model for asynchronous data review.
- Bundled Payment:Single prospective payments for defined episodes or condition management periods transfer utilization risk to vendors.
- Pay-as-You-Go:Usage-based pricing minimizes patient commitment but complicates provider capacity planning.
Subscription-Based models dominate current revenue composition; Bundled Payment is expanding most rapidly as Medicare Advantage penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems and Medicare Advantage plans concentrate purchasing power for outsourced chronic care services, driving vendor consolidation around biometric-validated outcome models rather than traditional process metrics.
United States
Medicare Advantage penetration and value-based contracting accelerate program enrollment across Florida and Arizona networks. FDA digital health pre-certification streamlines software-as-medical-device pathways for algorithm-driven care protocols. The Boston-Cambridge corridor anchors digital therapeutic development clusters where remote monitoring platforms secure 510(k) clearance.
Germany
Statutory health insurance funds expand reimbursement for integrated care programs targeting diabetes and cardiovascular disease. EMA guidance on software-as-medical-device classification shapes validation requirements for predictive analytics platforms. The Rhine-Ruhr metropolitan region concentrates telemedicine infrastructure deployment serving dispersed rural populations in North Rhine-Westphalia.
United Kingdom
NHS England long-term plan commitments drive procurement of remote patient monitoring for COPD and heart failure cohorts. MHRA recognition of FDA-cleared digital therapeutics accelerates market access for US-developed platforms. London health systems anchor pilot programs for AI-augmented clinical decision support in diabetes management.
Japan
Aging demographics and specialist workforce scarcity expand demand for technology-enabled chronic care in rural prefectures. PMDA streamlined review pathways for SaMD reduce clinical validation timelines for cardiovascular risk prediction tools. The Kansai region around Osaka concentrates hospital system adoption of continuous glucose monitoring paired with automated insulin dosing.
Australia
Primary health networks expand chronic disease management item numbers to include asynchronous remote monitoring review. TGA software as medical device guidance aligns with FDA pre-certification principles for algorithm-based interventions. New South Wales and Victoria health districts pilot bundled payment models for diabetes and cardiovascular program enrollment.
Chronic Disease Management Service Market Competitive Landscape
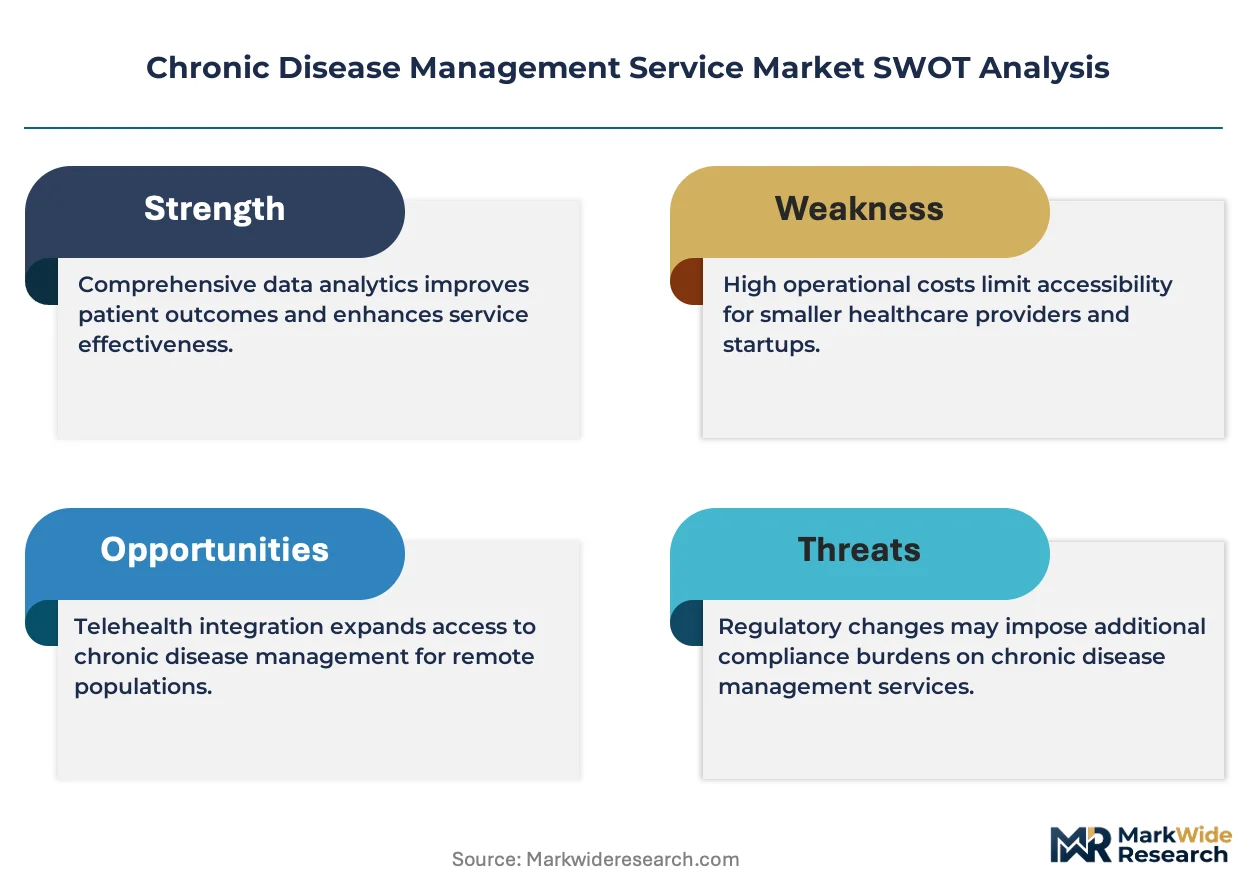
United States vendors anchor one tier; Indian IT services specialists hold another. Market structure reflects consolidation around vertically integrated payer-provider models alongside fragmentation among technology-enabled service platforms. Three archetypes dominate: payer-owned care management organizations, EHR-embedded workflow providers, and scaled remote monitoring infrastructure operators. M&A activity concentrates on digital therapeutic capabilities; strategic partnerships link wearable device manufacturers with analytics platforms.
Among US-based integrated care organizations, Optum, Inc. exemplifies the payer-provider archetype through bundled payment contract capture. Cognizant and Infosys Limited occupy positions within the IT services tier, supplying scaled infrastructure to regional payer networks. Epic Systems anchors the EHR-embedded workflow segment, representing hospital-centric deployment patterns.
| Leading Market Players |
|---|
| Optum, Inc. |
| ExlService Holdings, Inc. |
| NXGN Management, LLC. |
| Infosys Limited |
| Cognizant |
| Epic Systems |
| IBM |
| HealthSnap |
| Veradigm LLC |
| Others |
Pricing and Supply Chain Analysis
Certified diabetes educators and cardiac rehabilitation nurses concentrated in the United States Northeast and West Coast create labor-cost differentials that widen pricing-tier spreads between premium algorithm-driven platforms and basic telehealth offerings.
Pricing Analysis
High-volume asynchronous monitoring services compete on operational efficiency while premium AI-augmented decision support commands margin premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared digital therapeutic bundles from basic remote monitoring subscriptions. Price differentiation hinges on biometric sensor integration depth and outcome guarantee terms. Cost compression in the standard tier is intensifying because Medicare Advantage plans consolidate purchasing power around bundled payment contracts. Employer-sponsored plans exhibit lowest price sensitivity; individual patients through direct-to-consumer channels show highest elasticity.
Supply Chain Analysis
FDA 510(k) clearance and HIPAA business associate certification gate upstream component sourcing for chronic care platforms. Hardware supply concentrates in Taiwan, South Korea, and the United States for continuous glucose monitor sensors and connected inhaler assemblies. Algorithm development draws from cloud infrastructure provisioned through domestic data centers to satisfy patient privacy requirements. Single-source vulnerability in FDA-cleared sensor modules creates supply continuity exposure during regulatory inspection backlogs. Distribution runs through hospital system procurement committees and Medicare Advantage plan vendor panels rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist workforce scarcity props pricing power for vendors with certified care coordinator networks, as training pipeline constraints limit rapid capacity expansion regardless of technology deployment readiness.
For Market Incumbents: Deploy backward integration into wearable device manufacturing to capture hardware margins and secure sensor supply continuity. Optum's bundled payment contract capture demonstrates how payer-owned infrastructure resists margin compression from Medicare Advantage consolidation. Cognizant's scaled remote monitoring operations illustrate defensive positioning through workforce density in regional markets.
For New Entrants and Emerging Players: CMS remote therapeutic monitoring reimbursement codes in the United States open a window for asynchronous care coordination platforms targeting rural Medicare Advantage networks. State Medicaid community health worker expansion in Texas and California presents the most penetrable white-space for lower-cost non-clinical engagement models. A go-to-market angle anchored in guaranteed medical cost reduction contracts rather than per-member-per-month fees differentiates against incumbent pricing structures.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-augmented clinical decision support platforms given FDA Software Precertification Pilot Program acceleration of algorithm-based tool validation. Long-term viability over the next decade rests on demonstrating biometric-validated hospitalization reductions rather than process metric compliance. Acquisition targets should demonstrate embedded Epic Systems workflow integration or established Medicare Advantage plan contracts. The signal to watch as inflection indicator is CMS expansion of reimbursement codes for automated escalation protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification Pathway | Accelerates 510(k) timelines for cardiovascular risk prediction algorithms. |
| Epic Systems Workflow Integration | Embeds care management protocols directly into hospital EHR deployments. |
| Community Health Worker Network Buildout | Captures Texas and California Medicaid reimbursement for home-based engagement. |
| Continuous Glucose Monitor Manufacturing Partnership | Secures sensor supply for diabetes management program scaling. |
| Medicare Advantage Bundled Payment Contracting | Locks in multi-year revenue with utilization risk transfer to vendor. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this chronic disease management service analysis. Primary interviews with Medicare Advantage plan contracting officers, hospital system care management directors, FDA regulatory affairs specialists, and remote monitoring platform executives combined with secondary validation from CMS reimbursement code databases, FDA 510(k) clearance records, and state Medicaid program expansion announcements. Bottom-up service deployment modeling and top-down payer spending analysis provided triangulation across independent estimation approaches.
Segmentation-level granularity modeled service type, technology platform, end-user archetype, and delivery model dimensions across the projection horizon. CAGRs derived from fitted growth curves applied to biometric device shipment data and telehealth encounter volume trajectories. Forecast inputs incorporated Medicare Advantage penetration assumptions, FDA pre-certification pathway expansion timelines, and state-level telehealth parity law adoption patterns without specifying annual milestones.
The model assumes a particular technology adoption path; alternative pathways for AI-augmented clinical decision support would alter the outlook if FDA guidance shifts toward more stringent pre-market validation requirements. Forecasts reflect assumptions about sustained CMS reimbursement alignment for remote therapeutic monitoring and continued Medicare Advantage plan consolidation. A model refresh is warranted upon material change in FDA software-as-medical-device classification guidance or CMS establishment of new billing codes for automated care escalation protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Assisted Living Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Blood Bank Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Audiology Services Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Canada Senior Living Market