
 Prostate Cancer Minimally Invasive Surgery Market | 2026-2036
Prostate Cancer Minimally Invasive Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Prostate Cancer Minimally Invasive Surgery Market Outlook
Buyer concentration is rebalancing as ambulatory surgical centers fragment demand previously held by large hospital networks, while integrated delivery networks consolidate procurement power for high-cost robotic platforms. Intuitive Surgical anchors the robotic-assisted segment through installed base expansion and surgeon training ecosystems. Medtronic competes with advanced energy devices and navigation systems for laparoscopic prostatectomy. Johnson & Johnson Services leverages its Ethicon surgical portfolio to sustain presence across open and minimally invasive modalities.
Prostate cancer minimally invasive surgery encompasses robot-assisted, laparoscopic, and image-guided ablative interventions that excise or destroy malignant tissue through small incisions or percutaneous access, typically employing 5-12 mm ports, thermal or cryogenic energy delivery, and real-time imaging feedback to preserve neurovascular bundles and urinary continence. The primary commercial purpose centers on reducing blood loss, hospital stay duration, and recovery time versus open radical prostatectomy while maintaining oncologic control. Robotic-assisted surgery occupies the dominant margin pool due to system placement contracts and recurring instrument revenue. Laparoscopic surgery retains significant volume in cost-constrained settings where capital expenditure for robotic platforms proves prohibitive. Laser surgery and cryoablation segments are gaining traction for focal therapy applications in localized disease.
FDA premarket notification pathways and the EU MDR clinical evidence requirements shape product development timelines and market access costs for novel surgical devices. The EPA regulates medical waste streams from disposable robotic instruments, while OSHA bloodborne pathogen standards influence operating room workflow design and protective equipment specifications. Stakeholders must monitor evolving CMS reimbursement decisions for outpatient robotic prostatectomy and focal ablation codes, as these determinations will dictate capital deployment priorities across hospital and ambulatory settings.
Market Dynamics
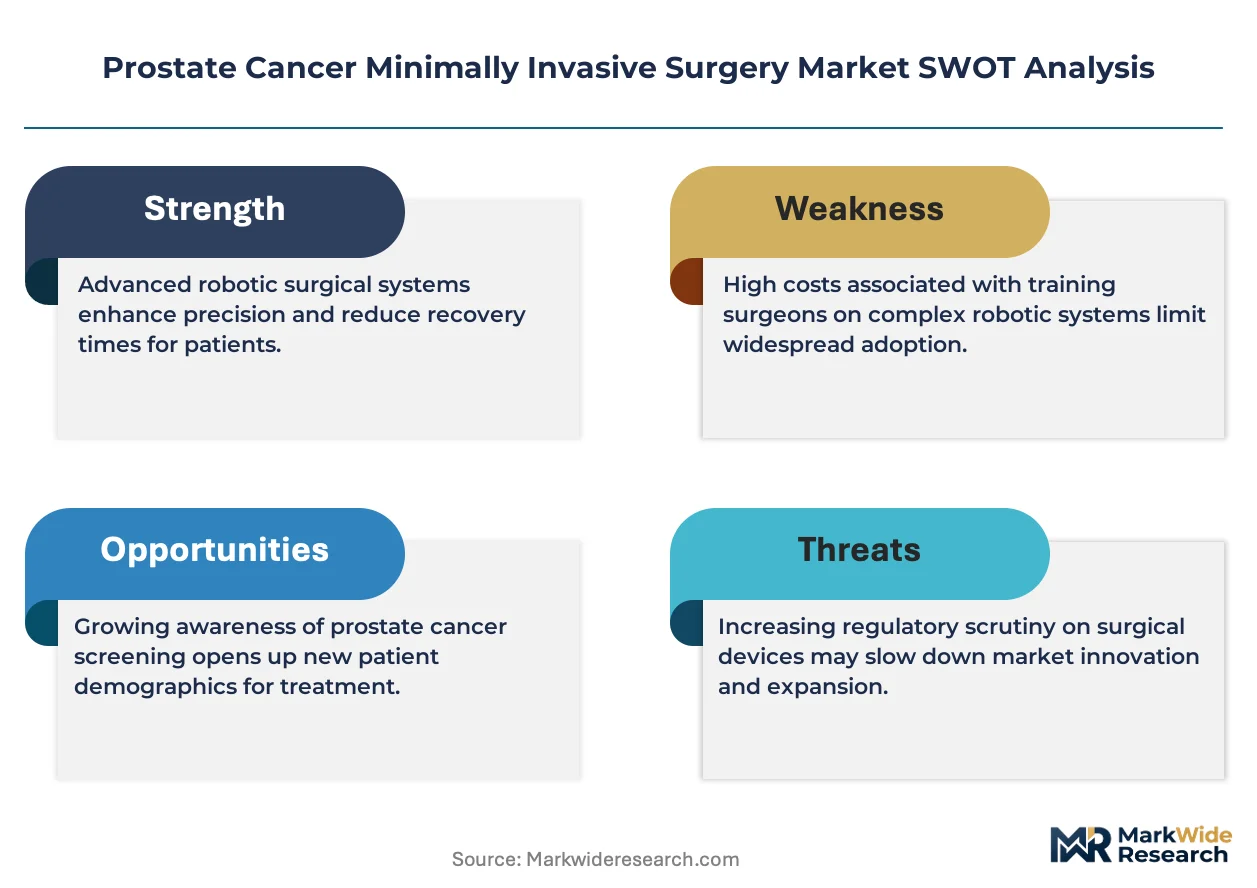
Robotic-assisted surgical platforms are consolidating procedure volume as hospitals and ambulatory surgical centers standardize on single-vendor ecosystems, compressing competitive entry points for alternative minimally invasive modalities.
Growth Catalysts
- Aging demographics in Japan and Germany:Prostate cancer incidence curves in these markets are expanding the addressable patient pool for nerve-sparing robotic prostatectomy. Screening program maturation in both countries is detecting localized disease earlier, preserving surgical candidacy.
- EU MDR streamlined pathways for breakthrough devices:The European Medical Device Regulation's expedited review track is compressing time-to-market for novel ablation platforms. Manufacturers leveraging this route gain commercial access ahead of standard certification timelines.
- Outpatient capacity expansion in US ambulatory surgical centers:Medicare reimbursement shifts toward site-neutral payment are incentivizing procedure migration from inpatient settings. Robotic prostatectomy volumes in ASCs are climbing as infrastructure investments mature.
Market Restraints
- Capital intensity of da Vinci system placement:The $2 million platform cost plus per-procedure instrument disposables locks out smaller hospital networks and public systems in cost-constrained markets. Leasing arrangements partially offset but extend payback periods.
- Supply concentration in single-use robotic instruments:Proprietary instrument ecosystems create vendor lock-in and limit price competition. Hospital procurement committees face limited leverage in renegotiating consumable contracts.
- Technical limitations in focal therapy guidance:Real-time tissue characterization during laser ablation or cryoablation remains imprecise, restricting adoption to highly selected patient populations and specialized centers.
Strategic Opportunities
- Focal therapy expansion in localized disease:MRI-ultrasound fusion biopsy is identifying unifocal lesions suitable for gland-preserving ablation. This segment addresses patient demand for continence-preserving alternatives to radical prostatectomy.
- Modular robotic platforms for cost-constrained settings:Systems offering laparoscopic-to-robotic upgrade paths are penetrating mid-tier hospitals in India and Brazil. These configurations defer full capital commitment while building surgical team familiarity.
- CMS outpatient procedure code expansion:Reimbursement coverage for ASC-based robotic prostatectomy is widening the addressable site-of-care footprint. Facilities securing these codes gain competitive positioning for commercially insured patient volumes.
Industry Challenges
- Surgeon training pipeline constraints:Robotic prostatectomy proficiency requires 50-100 supervised cases, creating bottlenecks as experienced proctors concentrate in academic centers. Community hospital recruitment struggles against this scarcity.
- Integration complexity with electronic health record systems:Surgical robot data streams require custom interfaces for operative documentation and quality tracking. Health system IT departments face backlogs in prioritizing these builds.
- IP fragmentation in navigation software:Patent thickets around MRI-fusion biopsy guidance are complicating licensing for new market entrants. Legal exposure deters smaller manufacturers from feature parity investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prostate Cancer Minimally Invasive Surgery Market |
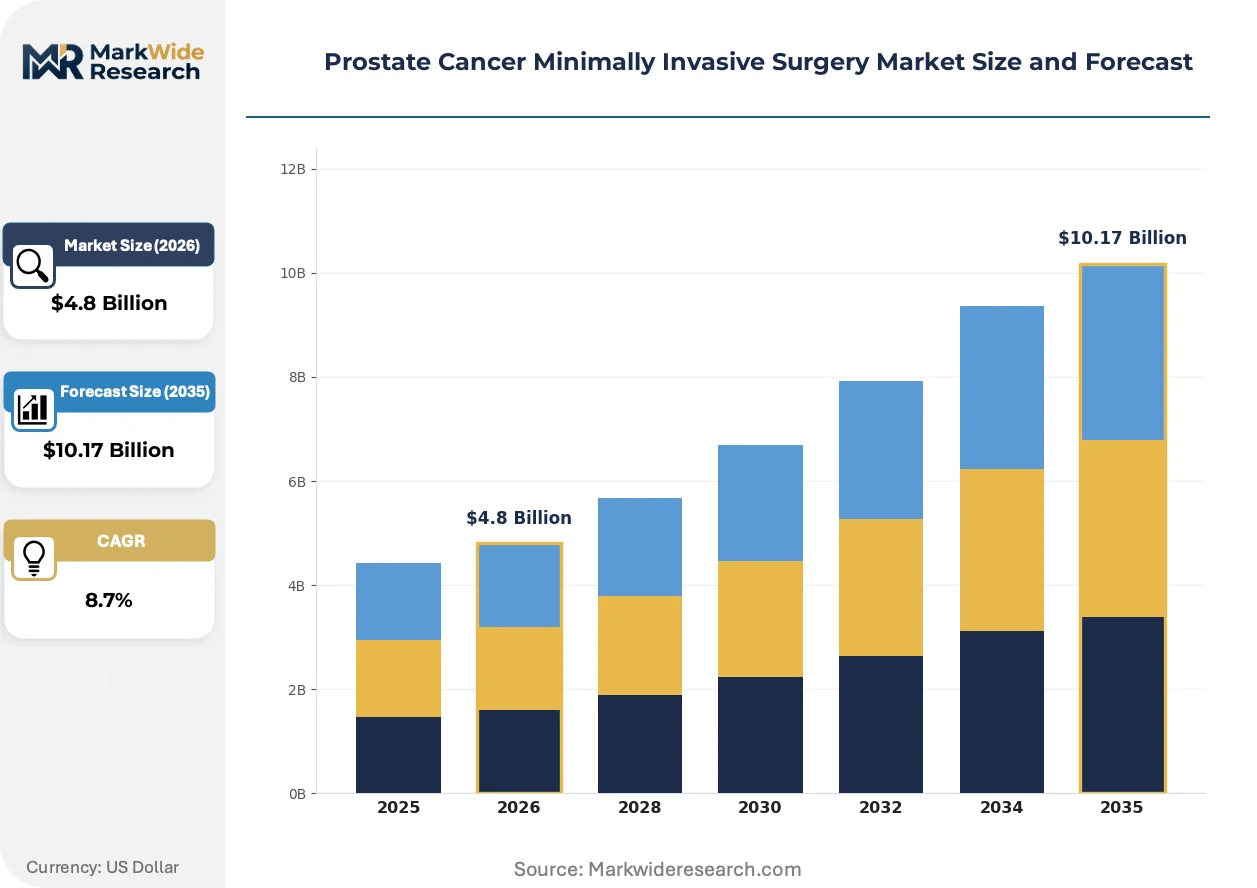
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic-Assisted Surgery, Laparoscopic Surgery, Laser Surgery, Cryoablation Technology: Ultrasound, MRI Guidance, Electrosurgery, Endoscopic Techniques End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Radical Prostatectomy, Tissue Ablation, Diagnostic Procedures, Imaging |
| Companies Covered | Intuitive Surgical, Medtronic, Johnson & Johnson Services, Profound Medical, AngioDynamics, Olympus, Siemens Healthineers, EDAP TMS, SonaCare Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prostate Cancer Minimally Invasive Surgery Market Strategic Shifts
Artificial intelligence integration is compressing surgical decision cycles, with real-time tissue analytics and predictive outcome modeling migrating from research environments into commercial platform roadmaps.
Multi-modal imaging fusion is unifying preoperative MRI, intraoperative ultrasound, and optical coherence tomography into single-display navigation. Academic medical centers in the United States and Germany are piloting these configurations for nerve bundle identification. The technology is unifying previously separate diagnostic and therapeutic workflows, reducing operative time variability and flattening learning curves for new robotic surgeons.
CE marking under the EU MDR is demanding prospective clinical data for novel ablation devices, elevating evidence requirements above the previous directive's equivalence standards. European manufacturers are restructuring regulatory strategies to accommodate longer approval timelines. The focal therapy segment is most affected, with several laser and cryoablation platforms delaying commercial launches to complete mandated follow-up studies.
Hospital procurement committees are consolidating vendor relationships around full-service robotic contracts spanning capital, training, and maintenance. Independent service organizations and third-party instrument reprocessors are losing access as original equipment manufacturers tighten contractual control. This concentration is most visible in integrated delivery networks across Texas, California, and Florida, where standardization across 10-plus facility systems is driving sole-source negotiations.
Prostate Cancer Minimally Invasive Surgery Market Segmentation
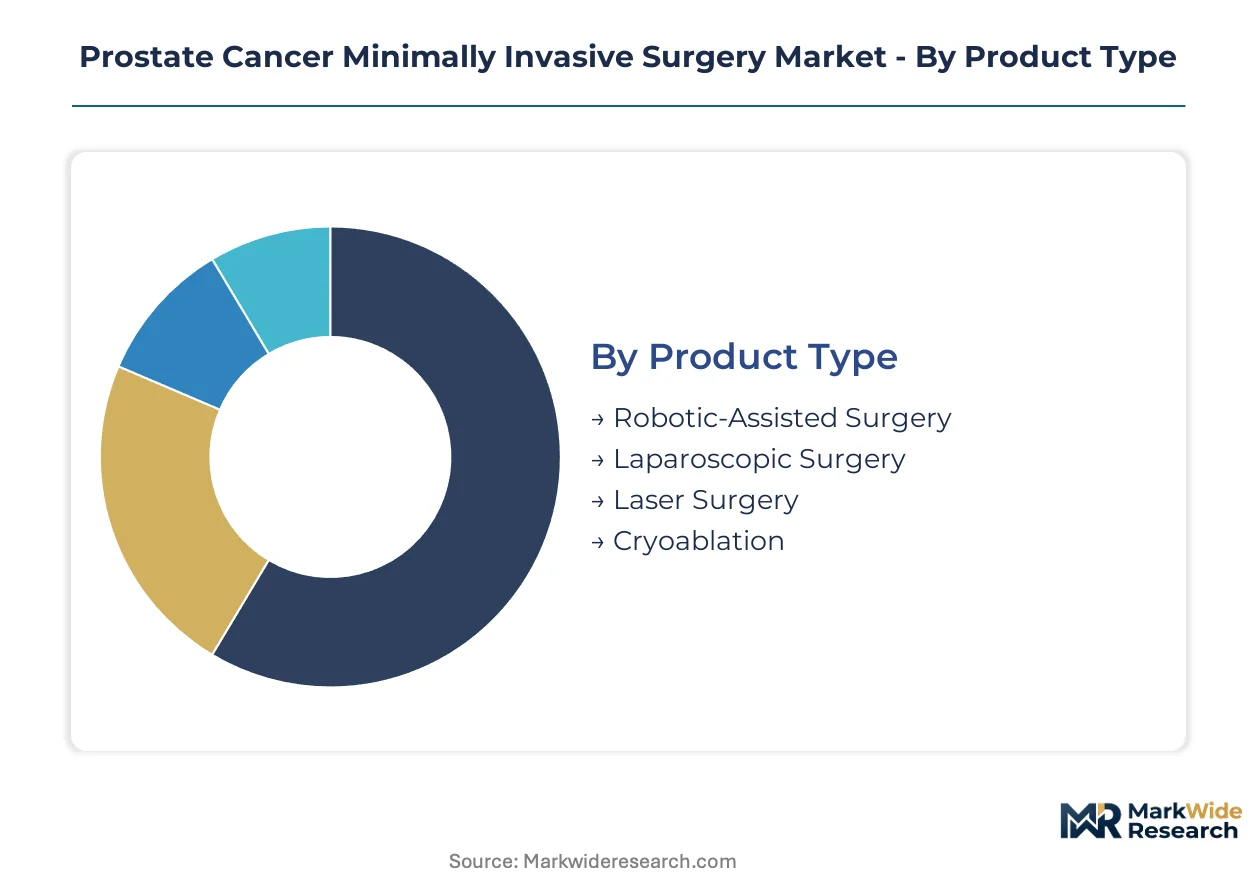
Segmentation in prostate cancer minimally invasive surgery reveals how capital intensity, regulatory pathways, and site-of-care economics partition demand across modalities. Each dimension captures distinct procurement behaviors, from bundled robotic contracts to disposable instrument flows.
Product Type:
Standardization dominates high-volume robotic platforms while customization persists in ablation technologies targeting focal therapy niches.
- Robotic-Assisted Surgery:Systems employ articulated instruments through 8-12 mm ports with 3D visualization and tremor filtration. Demand concentrates in United States integrated delivery networks where bundled payments justify capital deployment. Intuitive Surgical's installed base creates switching costs that compress competitive entry.
- Laparoscopic Surgery:Manual instrumentation through 5-10 mm ports without robotic articulation retains volume in Germany's public hospital systems and Japan's regional medical centers where capital constraints delay robotic adoption. Energy device disposables generate recurring revenue at lower per-procedure cost.
- Laser Surgery:Holmium and thulium fiber delivery systems enable precise tissue vaporization for focal ablation.
- Cryoablation:Argon-helium probe systems destroy tissue through freeze-thaw cycles, deployed in select United States academic centers for gland-preserving therapy.
Most installed capacity flows through Robotic-Assisted Surgery. Expansion is steepest in Laser Surgery as MRI-targeted focal therapy protocols mature.
Technology:
Cost tiers separate premium navigation systems from basic visualization, with reimbursement differentials driving hospital procurement priorities.
- Ultrasound:Transrectal and laparoscopic probes provide real-time anatomical imaging at moderate capital cost. Germany's outpatient clinics deploy these systems for biopsy guidance and intraoperative margin assessment where MRI access remains limited.
- MRI Guidance:Preoperative staging and intraoperative fusion navigation enable nerve-sparing dissection with reduced positive margin rates. United States academic medical centers in Boston and Houston prioritize these configurations for referral network differentiation.
- Electrosurgery:Radiofrequency and plasma energy devices achieve hemostasis and tissue transection through standard laparoscopic ports.
- Endoscopic Techniques:Rigid and flexible scopes with high-definition cameras support diagnostic and therapeutic access.
Procurement volume clusters in Ultrasound for its capital efficiency. MRI Guidance claims the steepest expansion trajectory as fusion biopsy protocols standardize.
End User:
Customer type determines contract structure, with health systems negotiating enterprise pricing while independent centers face list pricing.
- Hospitals:Inpatient facilities with 24-hour recovery capacity manage complex cases and complications. Japan's cancer center hospitals in Tokyo and Osaka anchor robotic prostatectomy volumes through surgeon training pipelines and referral catchment.
- Ambulatory Surgical Centers:Outpatient-focused facilities with streamlined discharge protocols are capturing migration from inpatient settings. United States ASCs in Texas and Florida are securing CMS procedure codes that enable commercially insured patient recruitment.
- Specialty Clinics:Urology-focused practices offer consultation and minor procedures without full surgical suites.
- Research Institutions:Academic centers conduct clinical trials and device validation studies.
Procedure volume concentrates in Hospitals. Patient migration is accelerating fastest toward Ambulatory Surgical Centers as site-neutral payment policies mature.
Application:
Maturity gradients separate established radical procedures from emerging focal therapies with evolving evidence bases.
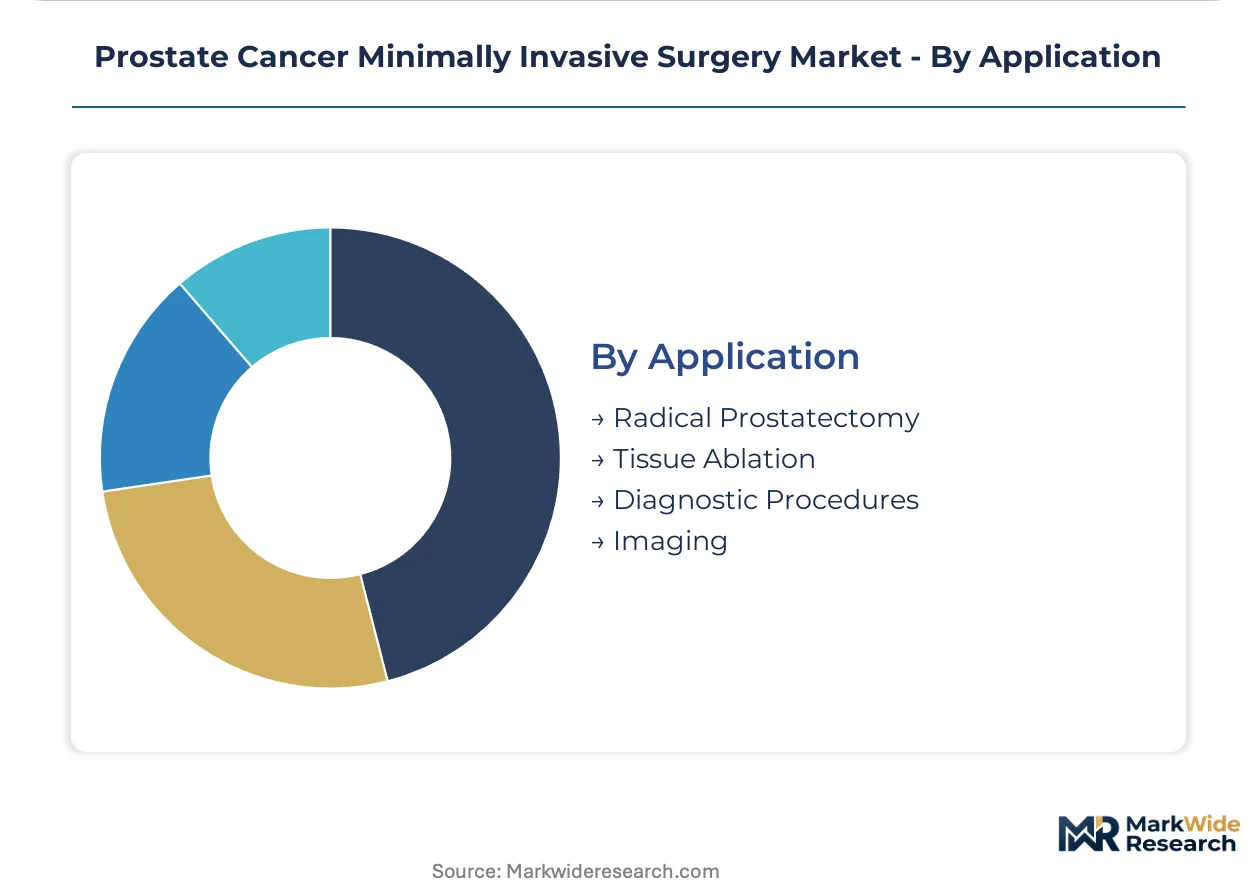
- Radical Prostatectomy:Complete gland excision with pelvic lymph node dissection remains the curative standard for localized disease. United States community hospitals in California and New York are standardizing on robotic platforms for this indication as open surgery volumes decline.
- Tissue Ablation:Focal destruction of MRI-visible lesions preserves gland function and continence. German university hospitals in Munich and Heidelberg are accumulating prospective data to support CE marking applications under EU MDR.
- Diagnostic Procedures:Biopsy and staging interventions guide treatment selection.
- Imaging:Intraoperative navigation and postoperative surveillance support care pathways.
Surgical capacity centers on Radical Prostatectomy. Clinical investment is climbing fastest in Tissue Ablation as patient demand for function-preserving alternatives intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's public hospital systems sustain laparoscopic volumes where robotic capital proves prohibitive, while the United States concentrates installed robotic capacity within integrated delivery networks. Japan's aging demographics and screening maturation are expanding surgical candidacy pools. Regulatory pathways in each jurisdiction are reshaping competitive access timelines.
United States
Integrated delivery networks in Texas and California are consolidating procurement around sole-source robotic contracts spanning capital, training, and maintenance. CMS site-neutral payment policies are accelerating procedure migration toward ambulatory surgical centers. The FDA's breakthrough device designation is compressing commercial access timelines for novel ablation platforms seeking outpatient code expansion.
Germany
Public hospital systems in Bavaria and North Rhine-Westphalia retain significant laparoscopic volumes due to capital constraints on robotic platform deployment. The EU MDR's expedited review track is enabling faster CE marking for manufacturers with prospective clinical data. University hospitals in Munich and Heidelberg are accumulating focal therapy evidence to support gland-preserving ablation protocols.
Japan
Cancer center hospitals in Tokyo and Osaka anchor robotic prostatectomy volumes through surgeon training pipelines and regional referral catchment. METI's medical device reimbursement frameworks are standardizing coverage for minimally invasive modalities. Screening program maturation is detecting localized disease earlier, preserving nerve-sparing surgical candidacy.
United Kingdom
NHS procurement frameworks are evaluating robotic platform cost-effectiveness against laparoscopic alternatives in England's regional hospital networks. MHRA post-Brexit regulatory pathways are diverging from EU MDR timelines for novel device submissions. London and Southeast academic centers are piloting multi-modal imaging fusion for intraoperative nerve bundle identification.
India
Mid-tier hospitals in Maharashtra and Karnataka are adopting modular robotic platforms offering laparoscopic-to-robotic upgrade paths. CDSCO streamlined approval processes are accelerating commercial access for established international manufacturers. Mumbai and Delhi-NCR medical centers are building surgeon training capacity to address proficiency bottlenecks in community hospital recruitment.
Prostate Cancer Minimally Invasive Surgery Market Competitive Environment
United States producers anchor one tier; European and Japanese specialists hold differentiated positions in imaging and energy modalities. Market structure concentrates around three strategic archetypes: integrated robotic platform vendors, advanced energy device manufacturers, and focal therapy navigation specialists. Competitive dynamics center on installed base expansion and recurring instrument revenue capture.
Within the integrated platform tier, Intuitive Surgical exemplifies the capital-plus-consumables model that locks hospital procurement committees into long-term contractual relationships. Medtronic and Johnson & Johnson Services occupy positions spanning laparoscopic energy devices and open surgical portfolios, representing diversification strategies that sustain presence across modality transitions.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Johnson & Johnson Services |
| Profound Medical |
| AngioDynamics |
| Olympus |
| Siemens Healthineers |
| EDAP TMS |
| SonaCare Medical |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States and Germany anchor procurement volumes for robotic prostatectomy platforms, locking vendors into bundled capital-plus-consumables contracts that compress price transparency and extend payback horizons for smaller hospital systems.
Pricing Analysis
Capacity additions in modular robotic platforms across India and Brazil are reshaping price floors for mid-tier hospital segments. Three-tier pricing structure across premium, standard, and economy levels separates da Vinci system placements from laparoscopic-to-robotic upgrade paths and manual laparoscopic instrument bundles. Price differentiation rests on FDA breakthrough designation status and surgeon training ecosystem depth. Cost compression in disposable robotic instruments is intensifying because ASC procurement committees are consolidating vendor relationships around full-service contracts. Community hospitals in cost-constrained markets exhibit highest price sensitivity; academic medical centers with training revenue streams demonstrate lowest.
Supply Chain Analysis
Instrument refurbishment flows and single-use disposable returns are tightening OEM control over aftermarket service revenue as third-party reprocessors lose contractual access in United States integrated delivery networks. Manufacturing concentration clusters in the United States for robotic platform assembly, Germany for precision optical components, and Japan for high-definition camera modules. Supply chains draw from semiconductor-grade sensors, medical-grade polymers, and rare-earth magnet assemblies. Single-source vulnerability in proprietary instrument ecosystems creates vendor lock-in exposure. Distribution runs through direct sales forces for capital equipment and GPO-negotiated channels for disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on software-enabled service tiering and recurring instrument revenue capture as hardware placement growth moderates across mature geographies.
For Market Incumbents: Acquire focal therapy navigation software assets to preempt displacement by MRI-ultrasound fusion specialists. Consolidate procurement relationships through exclusive training academy access and EHR integration commitments. Counter modular platform entrants by embedding predictive maintenance algorithms that raise switching costs for hospital IT departments. For New Entrants and Emerging Players: Begin with laser ablation systems for ASC-based focal therapy in Germany where EU MDR evidence requirements have delayed incumbent launches. Penetrate mid-tier Indian hospitals with laparoscopic-to-robotic upgrade configurations that defer full capital commitment. Pursue CDSCO streamlined approval pathways to compress time-to-revenue versus standard certification timelines. For Investors and Strategic Acquirers: MedTech conglomerates with surgical robotics gaps are the most active acquirer in this space, targeting navigation software specialists and energy device platforms. Long-term viability favors vendors with installed base scale and recurring revenue density over pure-play hardware manufacturers. Monitor CMS outpatient procedure code expansion decisions as inflection indicators for ASC volume migration and capital deployment priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive contracts with Texas and California IDNs lock in 10-plus facility standardization. |
| CE Marking Pathway | EU MDR expedited review compresses commercial access for novel ablation platforms. |
| Software Companion Development | AI-powered tissue analytics differentiate platform roadmaps and justify premium pricing tiers. |
| Reimbursement Strategy | CMS site-neutral payment alignment determines ASC procedure migration and capital allocation. |
| Surgeon Training Ecosystem | Proctoring networks in Tokyo and Osaka anchor regional referral catchment and loyalty. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and urology department heads with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body decisions. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Segment-weighting approaches applied product type, technology tier, end-user facility category, and application indication as primary dimensions across the projection horizon. CAGRs derived from logistic diffusion modeling of robotic platform penetration rates and laparoscopic volume displacement curves. Forecast inputs incorporated surgeon training pipeline constraints and site-of-care reimbursement policy trajectories.
Several conditions sit outside the modeled scope, including unforeseen regulatory pathway reversals, supply chain disruptions in semiconductor-grade sensor sourcing, and radical shifts in prostate cancer screening guidelines. Forecasts reflect documented assumptions about procedure migration timing and capital expenditure recovery periods. Practitioners should monitor CMS ASC procedure code determinations and EU MDR clinical evidence requirement amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Cystectomy Market
Urology
Urinary Incontinence Market
Urology
Urology Robotic Surgery Market
Urology
Uropathy Treatment Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Urology Devices Market
Urology
Urology Laser Fibers Market
Urology
Self-Intermittent Catheters Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Europe Bladder Disorders Market
Urology
Ureterorenoscopes Market
Urology
Urology Forceps Market