
 Immunoassay CDMO Market | 2026-2036
Immunoassay CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoassay CDMO Market Insights
The distinction between large pharma captive manufacturing and independent diagnostic company outsourcing is collapsing as mid-sized assay developers consolidate vendor relationships. Thermo Fisher Scientific leverages its integrated reagent-instrument-service portfolio to capture multi-year development contracts. Lonza anchors its position through specialized bioconjugation capabilities that reduce client technology transfer risk. Jabil competes on electronics manufacturing discipline applied to lateral flow and reader-based platforms.
An immunoassay contract development and manufacturing organization produces antibody-antigen binding diagnostic systems under client specifications, typically operating within sensitivity thresholds measured in picograms per milliliter and lot-to-lot variation below 10% coefficient of variation. These organizations serve primarily to accelerate regulatory clearance timelines for in vitro diagnostic sponsors. Chemiluminescent assays command premium service margins due to complex magnetic microparticle chemistry and instrument-locked consumable economics. Lateral flow assays sustain volume leadership in point-of-care applications where manufacturing scale determines unit economics. Assay development services generate the highest hourly margins while scale-up manufacturing locks in long-term revenue visibility.
FDA's Quality System Regulation and EMA's In Vitro Diagnostic Regulation impose design control and post-market surveillance burdens that filter out undercapitalized CDMO competitors. ISO 13485 certification functions as a baseline market access credential rather than a differentiator. China's NMPA has tightened clinical evidence requirements for imported diagnostic kits, prompting CDMOs to establish localized validation capabilities. Stakeholders must monitor how evolving IVD software regulations reshape assay reader integration requirements and determine whether to build, partner, or acquire algorithm validation expertise.
Market Dynamics
Diagnostic laboratories are consolidating vendor relationships around full-service partners capable of navigating FDA Quality System Regulation and EMA In Vitro Diagnostic Regulation compliance, collapsing the historical separation between assay development and commercial manufacturing.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:The 2022 enforcement timeline forces IVD sponsors to rebuild technical documentation, accelerating outsourcing to CDMOs with established quality management systems.
- Point-of-care testing expansion:Emergency departments and retail clinics in the United States demand rapid turnaround lateral flow manufacturing at million-unit scale.
- Magnetic microparticle chemistry:Chemiluminescent assay platforms require specialized bioconjugation expertise that captive facilities lack, driving contract demand toward Lonza and Thermo Fisher Scientific service portfolios.
Market Restraints
- Antibody raw material concentration:Three suppliers control over 80% of high-affinity monoclonal antibody production, exposing CDMOs to price volatility and allocation risk.
- FDA 510(k) pathway complexity:Predicate device requirements for novel chemiluminescent formats extend clearance timelines by 12-18 months, compressing client cash flows.
- Instrument-locked consumable economics:Siemens, Roche, and Abbott dominate installed base of automated analyzers, limiting third-party assay penetration to niche applications.
Strategic Opportunities
- China NMPA localization mandates:Imported diagnostic kits now require domestic clinical evidence, creating first-mover advantage for CDMOs with Shanghai or Suzhou validation facilities.
- Multiplexed respiratory panels:Post-pandemic surveillance infrastructure demands 15-25 target combination assays that exceed in-house development capacity of mid-sized IVD sponsors.
- Algorithm-integrated readers:FDA software as medical device guidance creates white space for CDMOs building machine learning validation capabilities alongside hardware manufacturing.
Industry Challenges
- ISO 13485 auditor scarcity:Certification backlog at notified bodies delays new facility qualification by 9-14 months, constraining capacity expansion.
- Technology transfer friction:Client-proprietary antibody clones require customized buffer formulations that disrupt standard manufacturing workflows and erode batch margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoassay CDMO Market |
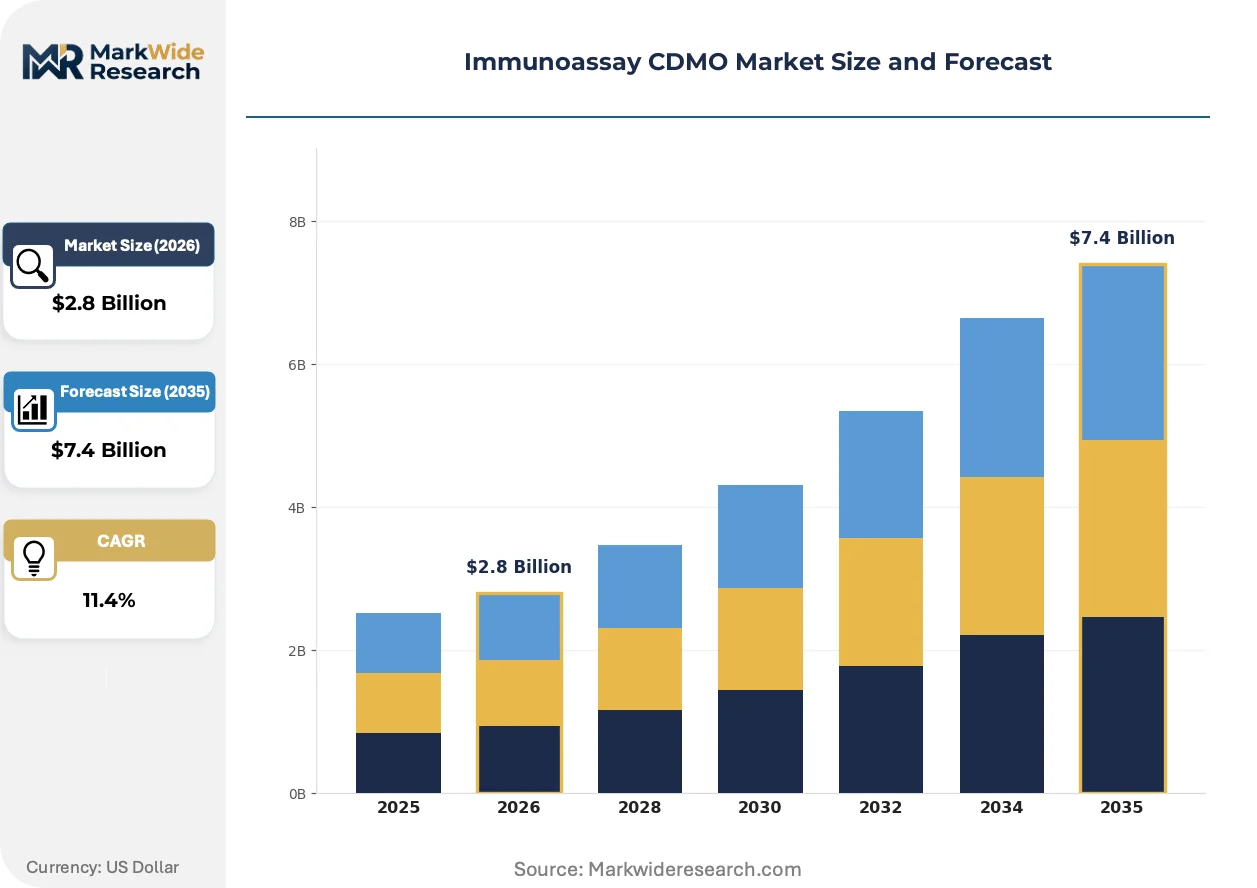
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Lateral Flow Assays, Chemiluminescent Assays, Radioimmunoassays, Fluorescent Immunoassays Application: Infectious Disease Diagnostics, Food Safety Testing, Drug Development, Environmental Monitoring, Veterinary Diagnostics End User: Biopharmaceutical Companies, Diagnostic Laboratories, Contract Research Organizations, Academic Institutions Service Type: Assay Development, Analytical Testing, Scale-Up Manufacturing, Regulatory Support, Validation Services |
| Companies Covered | Thermo Fisher Scientific, Jabil, Lonza, Recipharm, Vetter, PCI Pharma Services, Samsung Biologics, FLEX, Phillips-Medisize, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoassay CDMO Market Trends and Innovations
Microfluidic integration and software-defined diagnostics are compressing development cycles while regulatory fragmentation forces CDMOs to build multi-jurisdictional compliance infrastructure.
Digital microfluidic platforms are replacing traditional 96-well plate workflows for high-complexity testing. Reference laboratories in Germany and the United States are piloting cartridge-based systems that reduce sample volume requirements by 90%. This architecture is miniaturizing instrument footprints and enabling distributed testing networks that bypass centralized lab shipping logistics.
EMA's In Vitro Diagnostic Regulation introduced performance evaluation requirements and post-market surveillance obligations that exceed FDA 510(k) stringency. European IVD sponsors now demand CDMO partners with notified body relationships and clinical investigation capabilities. Small molecule and infectious disease assay developers face the steepest compliance cost increases.
Hospital procurement consortia are consolidating contract awards to reduce supplier management overhead. Academic medical centers in Boston and Heidelberg now issue multi-year sole-source agreements covering development through commercial supply. This concentration is squeezing mid-tier CDMOs without integrated reagent-instrument portfolios, favoring partners with captive magnetic particle synthesis and reader manufacturing capabilities.
Immunoassay CDMO Market Segmentation
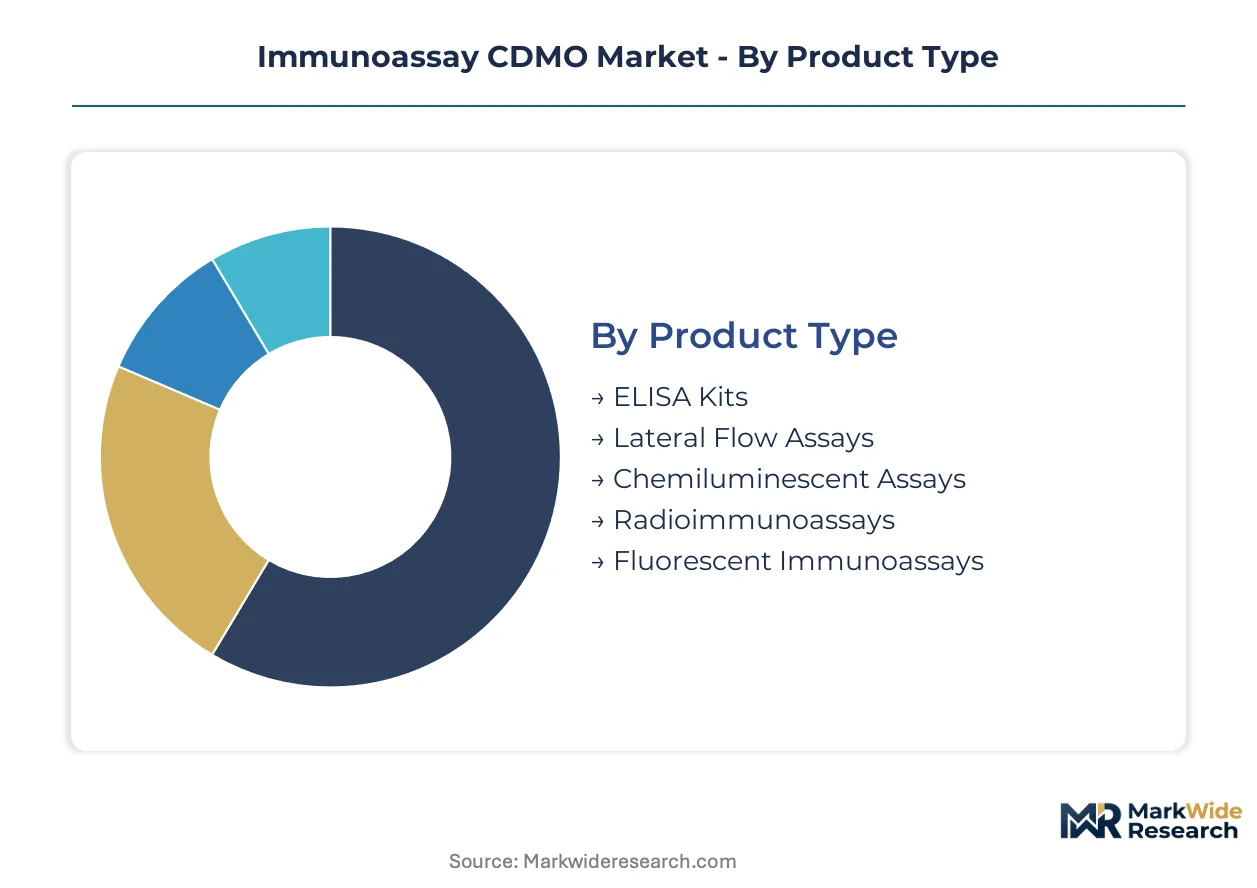
Immunoassay CDMO service portfolios fragment across distinct technical specifications and regulatory pathways. Each segment commands different margin structures and requires specialized infrastructure investments that reshape vendor competitive positions.
Product Type:
Channel mix varies sharply across immunoassay formats, with automated analyzer-locked consumables flowing through instrument OEM partnerships while point-of-care formats reach end-users through distribution networks.
- Chemiluminescent Assays:Magnetic microparticle-based systems achieve picogram-per-milliliter sensitivity thresholds. Demand concentrates in reference laboratories across the United States and Germany where automated throughput requirements dominate procurement specifications. Complex bioconjugation chemistry sustains premium service margins.
- Lateral Flow Assays:Nitrocellulose membrane platforms enable rapid point-of-care deployment without instrument infrastructure. Emergency departments and retail clinics in the United States drive million-unit scale manufacturing contracts. Manufacturing velocity determines unit economics more than analytical sensitivity.
- ELISA Kits:96-well plate formats serve research-use-only and clinical laboratory markets with established regulatory pathways.
- Radioimmunoassays:Isotope-labeled systems persist in endocrinology and specialized reference testing despite declining volume share.
- Fluorescent Immunoassays:Time-resolved and europium-chelate systems occupy niche positions in high-sensitivity cardiac marker applications.
Chemiluminescent assays dominate installed base. Lateral flow formats are where expansion concentrates.
Application:
Cost tier stratification separates high-complexity clinical diagnostics from commodity environmental and food safety screening.
- Infectious Disease Diagnostics:Multiplexed respiratory panels combine 15-25 targets on single cartridges. Post-pandemic surveillance infrastructure in the United States and China exceeds in-house development capacity of mid-sized IVD sponsors. Seasonal variant surveillance creates recurring contract demand.
- Drug Development:Pharmacokinetic and immunogenicity assays support biologics clinical trials with GLP-compliant documentation. Sponsors in Germany and the United States outsource to CDMOs with established FDA and EMA quality management systems. Regulatory submission timelines compress development partnerships.
- Food Safety Testing:Pathogen and allergen screening serves industrial laboratories with high-throughput automation requirements.
- Environmental Monitoring:Pesticide and contaminant detection operates at lower price points with reduced regulatory documentation burdens.
- Veterinary Diagnostics:Companion animal and livestock applications follow simplified registration pathways compared to human clinical markets.
Infectious disease applications dominate installed base. Drug development services are where expansion concentrates.
End User:
Customer type determines contract structure, with biopharmaceutical sponsors preferring milestone-based development agreements while diagnostic laboratories seek supply security through multi-year manufacturing commitments.
- Diagnostic Laboratories:Quest Diagnostics and LabCorp-scale networks consolidate vendor relationships around full-service partners. Academic medical centers in Boston and Heidelberg issue sole-source agreements spanning development through commercial supply. Procurement consortia reduce supplier management overhead.
- Biopharmaceutical Companies:Mid-sized assay developers lack captive manufacturing infrastructure and rely on CDMOs for technology transfer execution. FDA 510(k) and EMA IVDR compliance requirements filter vendor qualification to established quality system operators.
- Contract Research Organizations:Clinical trial service providers subcontract analytical testing to specialized immunoassay partners.
- Academic Institutions:Research-use-only demand operates at smaller scales with reduced regulatory documentation requirements.
Diagnostic laboratories dominate installed base. Biopharmaceutical outsourcing is where expansion concentrates.
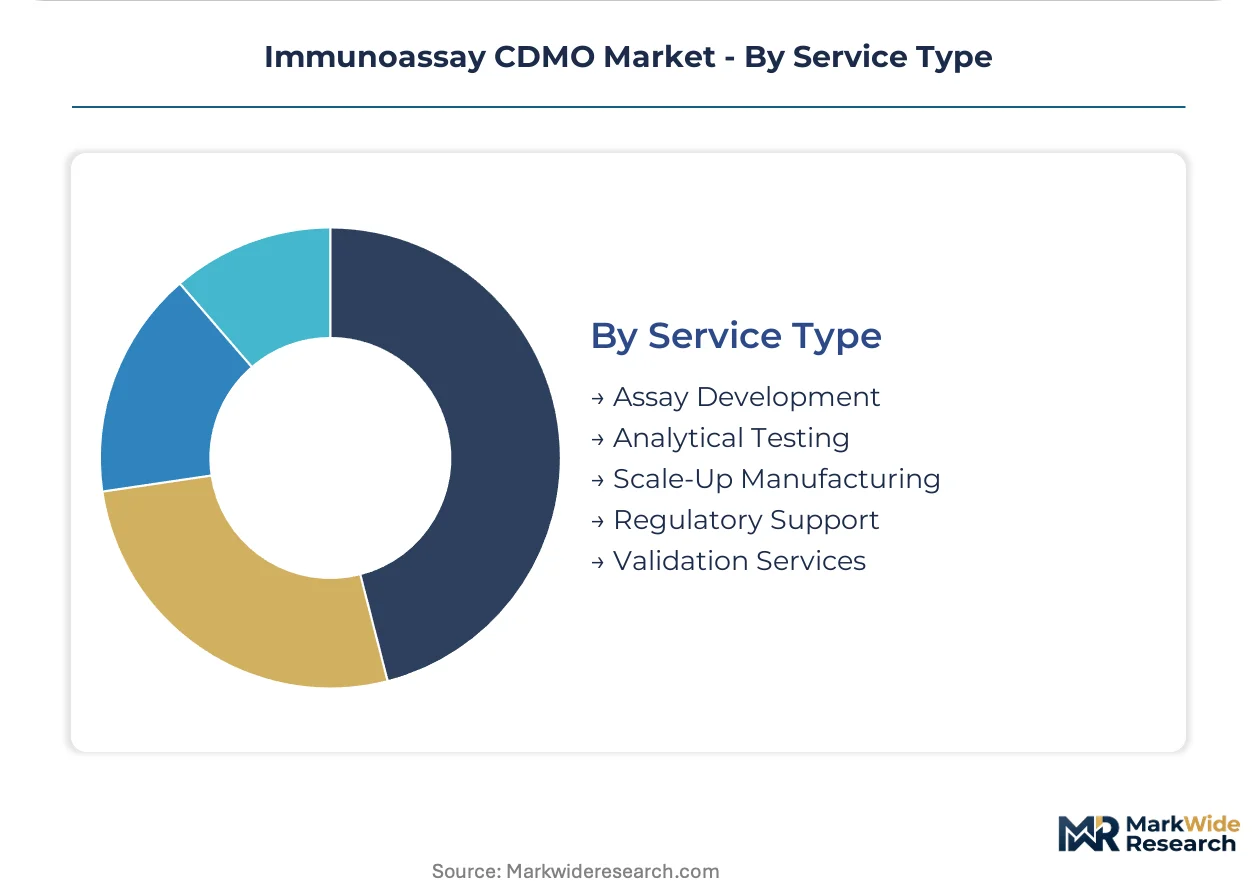
Service Type:
Margin structure inverts across the service continuum, with development commanding hourly premiums while manufacturing locks in long-term revenue visibility.
- Assay Development:Antibody-antigen optimization and buffer formulation generate the highest hourly margins in CDMO portfolios. Client-proprietary clones require customized workflows that disrupt standard manufacturing. Thermo Fisher Scientific and Lonza capture multi-year development contracts through integrated reagent capabilities.
- Scale-Up Manufacturing:Commercial supply agreements provide revenue predictability through minimum volume commitments. Lot-to-lot variation below 10% coefficient of variation remains the critical quality threshold. ISO 13485 certification functions as baseline market access credential.
- Analytical Testing:Characterization and stability studies support regulatory submission packages with documented precision and accuracy.
- Regulatory Support:FDA 510(k) preparation and EMA technical documentation rebuilds accelerate under IVDR enforcement timelines.
- Validation Services:Clinical evidence generation for China NMPA localization mandates requires domestic facility presence.
Scale-up manufacturing dominates installed base. Assay development services are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision bioconjugation services to diagnostic laboratories across the United States and China, establishing the primary trade corridor in high-sensitivity immunoassay manufacturing. This cross-border service flow concentrates around regulatory-aligned quality systems and specialized magnetic microparticle chemistry capabilities.
United States
Emergency departments and retail clinics in Texas and Florida drive million-unit lateral flow contracts. FDA Quality System Regulation enforcement filters vendor qualification to ISO 13485-certified operators with established 510(k) submission track records. Greater Boston academic medical centers consolidate sole-source agreements spanning development through commercial supply.
Germany
Reference laboratories in Heidelberg and Munich demand automated analyzer-locked consumables with picogram-per-milliliter sensitivity thresholds. EMA In Vitro Diagnostic Regulation performance evaluation requirements exceed FDA stringency, forcing sponsors toward CDMOs with notified body relationships. Bavaria hosts the densest cluster of biopharmaceutical innovators outsourcing pharmacokinetic assay development.
China
Post-pandemic surveillance infrastructure in Shanghai and Suzhou exceeds in-house multiplexed respiratory panel capacity of mid-sized IVD sponsors. NMPA localization mandates now require domestic clinical evidence for imported diagnostic kits. Yangtze River Delta validation facilities capture first-mover advantage in regulatory-compliant manufacturing.
Japan
Time-resolved fluorescent immunoassays for cardiac marker applications sustain niche demand in Tokyo and Osaka metropolitan laboratories. PMDA alignment with EMA technical documentation standards accelerates outsourcing to partners with dual-jurisdiction quality systems. Kanto region biopharmaceutical sponsors compress regulatory submission timelines through integrated CDMO partnerships.
Immunoassay CDMO Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory infrastructure dimensions. The vendor base stratifies into three tiers: integrated life science conglomerates with captive reagent portfolios, mid-scale bioconjugation specialists, and electronics manufacturing services firms applying semiconductor discipline to diagnostic hardware. Consolidation pressures favor full-service partners capable of navigating multi-jurisdictional compliance. Dominant competitive moves include strategic partnerships for magnetic particle synthesis capacity and geographic expansion into China NMPA-aligned validation corridors.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Lonza exemplify archetypes competing on reagent-instrument-service bundling and specialized bioconjugation capabilities respectively. Jabil occupies a position representing electronics manufacturing discipline applied to lateral flow and reader-based platforms. These three anchors illustrate how competitive positioning fragments across technical specialization rather than consolidating around undifferentiated scale.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Jabil |
| Lonza |
| Recipharm |
| Vetter |
| PCI Pharma Services |
| Samsung Biologics |
| FLEX |
| Phillips-Medisize |
| Others |
Pricing and Supply Chain Analysis
Magnetic microparticle substitution for enzyme-labeled conjugates redraws procurement geography toward Germany and China while compressing service margins for legacy ELISA workflows. CDMOs capturing this chemistry transition command premium positioning as reference laboratories in the United States and Germany consolidate contracts around picogram-sensitivity capabilities.
Pricing Analysis
Chemiluminescent assay development commands premium-mid-economy pricing differentiation against commoditized lateral flow manufacturing. ISO 13485 certification tier and automated analyzer compatibility drive price spreads between qualified and unqualified vendors. Pricing pressure stems from antibody raw material concentration among three dominant suppliers, squeezing batch margins for mid-tier CDMOs. Diagnostic laboratories exhibit lowest price sensitivity due to multi-year sole-source agreements, while research-use-only buyers negotiate spot contracts aggressively.
Supply Chain Analysis
Extended lead times for high-affinity monoclonal antibodies stretch manufacturing schedules across United States, Germany, and China validation facilities. Nitrocellulose membrane and magnetic particle inputs draw from specialized chemical synthesis networks concentrated in Bavaria and the Yangtze River Delta. Single-source vulnerability in bioconjugation reagents exposes CDMOs to allocation risk during demand surges. Distribution runs through instrument OEM partnerships for analyzer-locked consumables and direct hospital procurement consortia for point-of-care formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA In Vitro Diagnostic Regulation enforcement is accelerating market disruption as IVD sponsors rebuild technical documentation and outsource to quality-validated partners.
For Market Incumbents: Consolidate notified body relationships and captive magnetic particle synthesis capacity to defend against emerging bioconjugation specialists. Backward integration into antibody raw material sourcing mitigates supplier concentration risk. Anchor quality system investments in China NMPA-aligned validation corridors to capture localization mandate premiums.
For New Entrants and Emerging Players: Anchor in algorithm-integrated reader manufacturing where FDA software as medical device guidance creates white space absent incumbent dominance. Target multiplexed respiratory panel development for mid-sized IVD sponsors lacking in-house capacity. Pursue hospital procurement consortia sole-source agreements through integrated reagent-instrument bundling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMOs holding ISO 13485 certifications and established 510(k) track records but lacking China validation infrastructure. Five-to-ten year viability hinges on multi-jurisdictional compliance capabilities rather than undifferentiated scale. Watch NMPA clinical evidence requirement enforcement velocity as inflection indicator for geographic expansion returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Particle Synthesis Capacity Expansion | Captive microparticle production secures bioconjugation margins against raw material volatility. |
| China NMPA Validation Facility Establishment | Domestic clinical evidence generation captures localization mandate first-mover advantage. |
| Software as Medical Device Capability Buildout | Machine learning validation expertise addresses FDA guidance for algorithm-integrated readers. |
| Notified Body Relationship Deepening | EMA IVDR performance evaluation capabilities filter European sponsor vendor qualification. |
| Hospital Procurement Consortium Sole-Source Agreements | Multi-year development-to-commercial contracts reduce supplier management overhead for academic medical centers. |
Research Methodology
A spread of perspectives from CDMO operations directors, IVD sponsor regulatory affairs leads, diagnostic laboratory procurement managers, and notified body auditors converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov assay service listings, and hospital GPO contract databases. Bottom-up service revenue estimates triangulated against top-down IVD sponsor outsourcing spend patterns.
Segmentation dimensions modeled include assay format chemistry, application area, end-user type, and service stage across the projection horizon. CAGRs derived from fitted growth curves incorporating EMA IVDR enforcement phase-ins, China NMPA localization mandate adoption curves, and point-of-care testing expansion trajectories. Forecast inputs included antibody raw material pricing indices and automated analyzer installed base evolution.
Material uncertainties — regulatory timeline delays, antibody supplier allocation disruptions, and software validation standard revisions — sit outside the modeled envelope. Forecasts reflect assumptions about EMA notified body capacity expansion and China clinical evidence requirement stability. Revision becomes warranted when NMPA enforcement intensity crosses thresholds triggering accelerated localization investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Registered Nurses Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
UK Pharmaceutical Logistics Market