
 Healthcare Staffing Market | 2026-2036
Healthcare Staffing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Staffing Market Intelligence
Australia's expanded recruitment infrastructure for overseas clinicians is reshaping the competitive positioning of agencies operating across the Asia-Pacific region. AMN Healthcare leverages its scale to secure large hospital system contracts in the United States. Aya Healthcare differentiates through its technology platform for nurse-centric mobile recruiting. Cross Country Healthcare focuses on a diversified portfolio including both clinical and non-clinical placements to mitigate cyclical demand shifts.
Healthcare staffing involves supplying qualified clinical and non-clinical personnel to facilities on a temporary, contract, or permanent basis. The service includes critical functions like credential verification, state licensure compliance, and skills-to-demand matching to ensure patient safety and quality of care. Temporary staffing assignments for Registered Nurses continue to dominate service volume, driven by acute needs within large hospitals. Placements for allied health professionals in ambulatory care centers are expanding rapidly due to a shift towards outpatient services.
Regulations such as HIPAA in the United States and GDPR in Europe impose strict data security and privacy mandates on staffing agencies handling patient records. These frameworks govern how temporary personnel can access and transmit sensitive health information, directly impacting compliance costs and operational protocols. Stakeholder success depends on navigating disparate state-level and national credentialing requirements while investing in technology to automate compliance and placement.
Market Dynamics
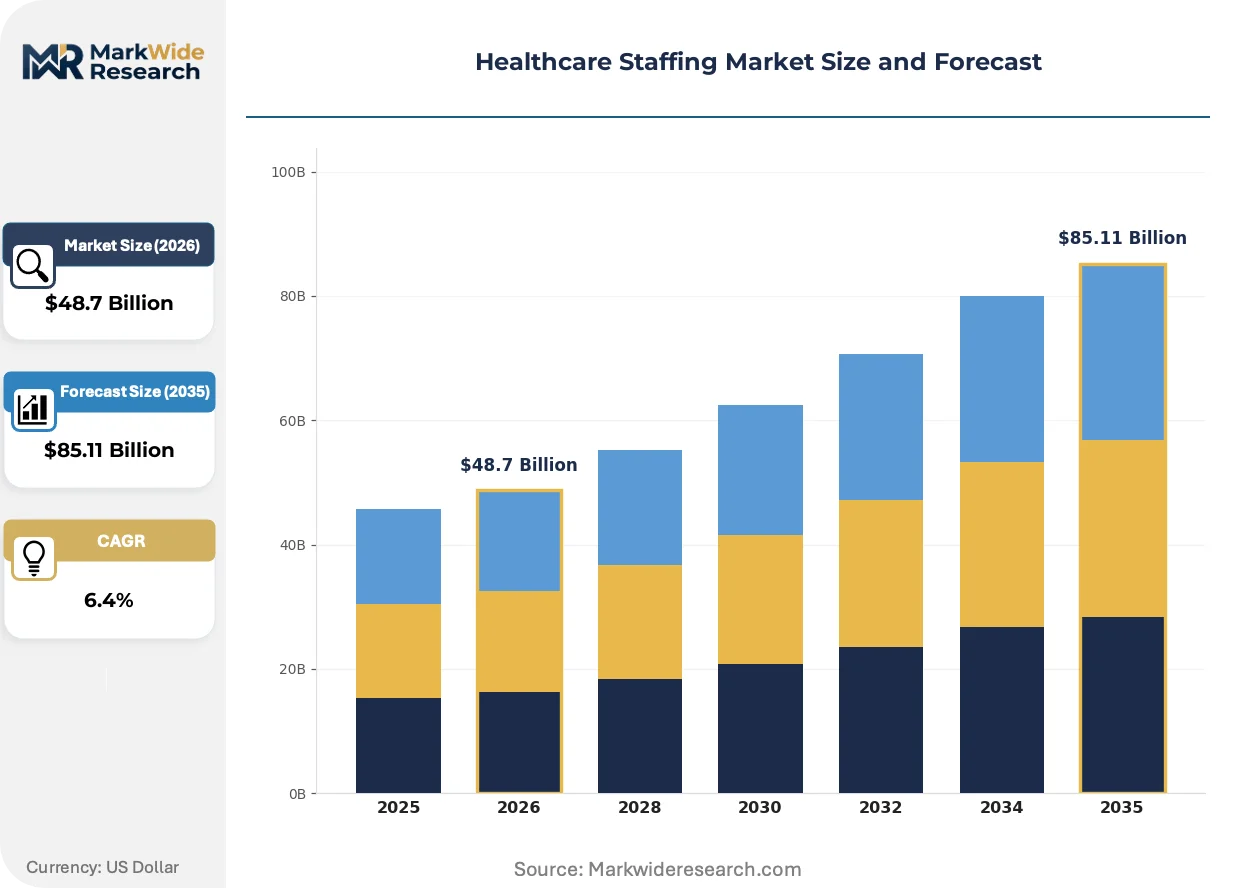
Persistent clinical labor shortages in developed economies are the central structural force shaping the market. This scarcity drives demand for flexible staffing solutions, while digital platforms simultaneously attempt to improve labor allocation efficiency and transparency for both healthcare facilities and clinicians.
Growth Catalysts
- Aging Demographics in Developed Nations:The expanding elderly population in countries like Japan and Germany is increasing patient volumes in long-term care and geriatric specialty facilities, directly boosting demand for temporary nurses and allied health professionals.
- Expanded Healthcare Access Policies:Government initiatives aimed at increasing health insurance coverage, such as reforms seen in the United States, broaden the patient base for hospitals and clinics, necessitating a larger and more flexible clinical workforce.
- Vendor Management Systems (VMS):The adoption of VMS and Managed Service Provider (MSP) programs by large hospital systems creates a streamlined procurement channel for temporary staff, improving placement efficiency and encouraging higher volume contracts.
Market Restraints
- Credentialing Fragmentation:The lack of standardized, cross-state licensure for nurses and physicians in the United States creates significant administrative friction and delays, limiting the rapid deployment of staff across state lines.
- Wage Inflation and Premium Pay:Intense competition for a limited pool of qualified clinicians, particularly specialized nurses, leads to wage inflation and a reliance on high-cost premium pay, compressing agency margins.
- Internal Resource Pools:Large hospital systems are investing in building their own internal float pools and resource management teams, creating a direct substitute for external agency services and reducing reliance on third-party staffing.
Strategic Opportunities
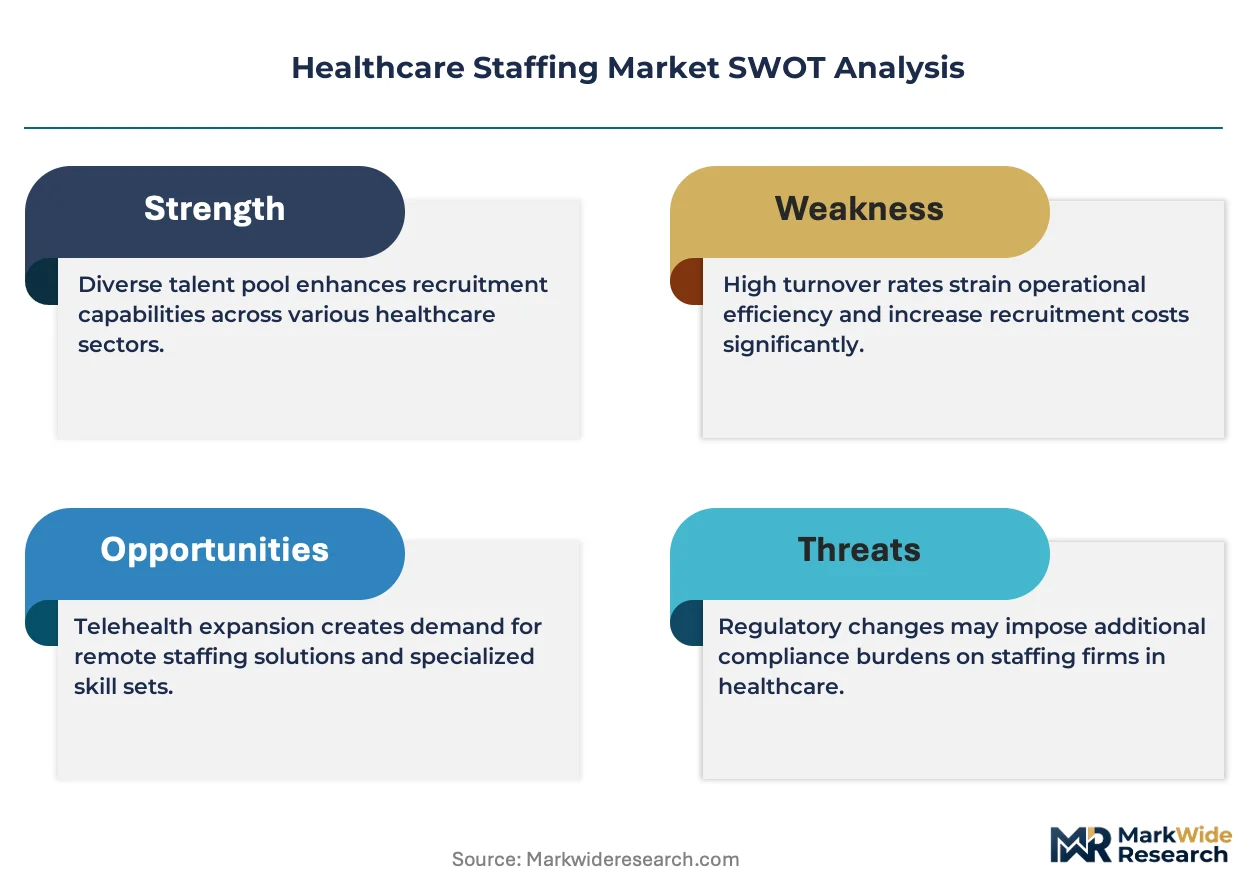
- Telehealth and Virtual Care Staffing:The expansion of telehealth services creates an opportunity to provide specialized remote staffing for virtual consultations, remote patient monitoring, and telemental health, a segment with distinct credentialing needs.
- Emerging Markets in Southeast Asia:Developing healthcare infrastructure in countries like Vietnam and Indonesia presents an opportunity for establishing staffing services that cater to new hospitals and clinics, especially for specialized clinical roles.
- AI-Powered Credentialing and Matching:Integrating artificial intelligence with compliance software offers a path to automate the verification of credentials against disparate national requirements, significantly reducing placement times and compliance risk.
Industry Challenges
- Data Privacy Compliance Burden:Adhering to complex data security mandates like HIPAA in the US and GDPR in Europe requires continuous investment in secure IT infrastructure and training, increasing operational costs for agencies handling sensitive patient information.
- Scarcity of High-Acuity Specialists:A persistent shortage of clinicians with experience in critical care and emergency departments makes it difficult to fill high-urgency, high-skill assignments, challenging service level agreements with hospital clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Staffing Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Staffing Type: Temporary Staffing, Permanent Placement, Contract Staffing, Temp-to-Perm Healthcare Roles: Registered Nurses, Physicians, Allied Health Professionals, Medical Technicians Service Mode: Onsite Staffing, Remote Staffing, Managed Staffing Services, Recruitment Process Outsourcing End User: Hospitals, Ambulatory Care Centers, Long-Term Care Facilities, Diagnostic Laboratories |
| Companies Covered | AMN Healthcare, Aya Healthcare, CHG Healthcare, Medical Solutions, Cross Country Healthcare, Amergis Healthcare Staffing, Maxim Healthcare, Interim HealthCare, MedPro Healthcare Staffing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Staffing Market Strategic Shifts & Innovations
A fundamental shift from transactional, role-filling services toward integrated workforce solutions is defining the market's evolution. This transition prioritizes technology platforms that offer predictive analytics, compliance automation, and direct access for clinicians to manage their careers and assignments.
Mobile-first recruiting platforms combine job matching, credential management, and scheduling into a single application for nurses and allied health professionals. Healthcare systems and individual clinicians are rapidly adopting these platforms for their convenience and transparency in managing assignments. This technology is virtualizing the entire recruitment and deployment process, reducing the reliance on traditional phone-based recruiters and physical branch offices.
The Nurse Licensure Compact (NLC) in the United States allows registered nurses to have one multistate license with the ability to practice in other compact states. This framework significantly reduces administrative barriers for travel nursing, enabling a more fluid and responsive national labor pool to address regional shortages. Staffing agencies focused on rapid-response assignments are most affected, as they can deploy clinicians faster across NLC member states.
A growing number of large hospital networks are developing internal agency or direct sourcing models to manage their contingent labor needs. This model disrupts the traditional reliance on multiple external staffing agencies by creating a private talent pool of pre-vetted, system-familiar clinicians. The trend is most visible in large, multi-state integrated delivery networks in the United States seeking greater control over labor costs and quality.
Healthcare Staffing Market Segmentation
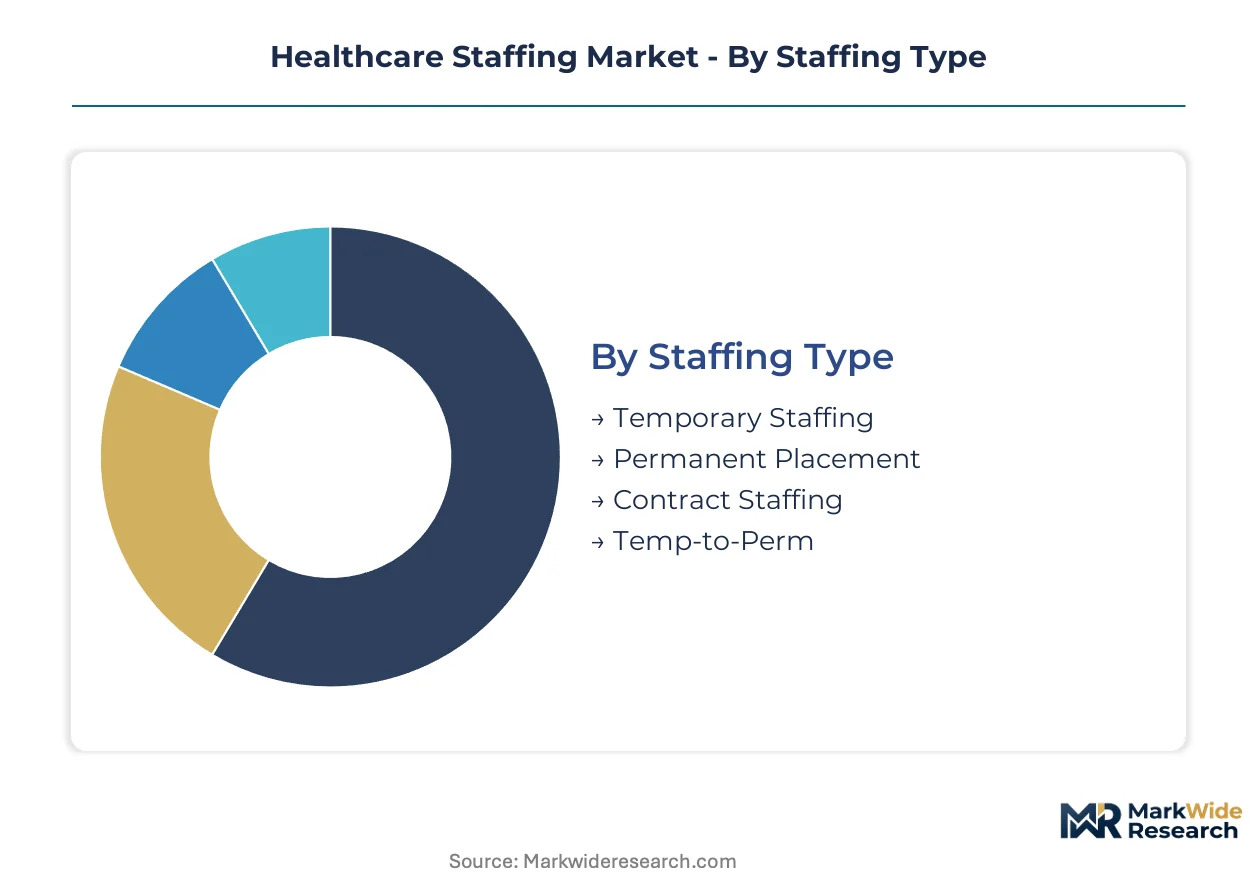
The Healthcare Staffing Market exhibits diverse operational models and service requirements, necessitating a granular segmentation to understand demand patterns and competitive dynamics. This analysis dissects the market across staffing type, healthcare roles, service mode, and end-user categories, highlighting the unique characteristics and growth trajectories within each.
Staffing Type:
The varied staffing types delineate the speed and duration of clinical deployments, reflecting different operational cycle times for healthcare facilities.
- Temporary Staffing:This service provides immediate, short-term coverage for fluctuating patient volumes, seasonal peaks, or staff absences. Demand concentrates in large hospitals in the United States for acute needs, driven by persistent clinical labor shortages.
- Permanent Placement:Focuses on recruiting and onboarding long-term employees for stable, core workforce positions within healthcare organizations. This segment addresses critical workforce stability for specialized roles in clinics and long-term care facilities, particularly in countries with aging populations like Germany.
- Contract Staffing:Involves fixed-term engagements for specific projects, extended leaves, or specialized departmental initiatives.
- Temp-to-Perm:Allows healthcare facilities to evaluate a clinician's performance and fit before extending an offer for permanent employment.
Temporary Staffing anchors the volume base while Temp-to-Perm gains share at the steepest rate.
Healthcare Roles:
Healthcare roles segmentation highlights the specialized skill sets required across diverse clinical environments and patient care applications.
- Registered Nurses:Constitute the largest segment, providing direct patient care across all healthcare settings, from acute to long-term care. Acute care hospitals in the United States drive significant demand for these professionals due to persistent shortages and high patient acuity.
- Physicians:Include general practitioners and various specialists, fulfilling diagnostic, treatment, and consultation functions for patients. Demand for physicians in telehealth services is expanding rapidly, especially in remote areas of Canada and Australia.
- Allied Health Professionals:Encompasses a broad range of therapists, technicians, and other support staff crucial for comprehensive patient management.
- Medical Technicians:Perform diagnostic tests, maintain medical equipment, and assist in various clinical procedures within laboratories and clinics.
Specialized roles like Physicians command premium compensation, reflecting scarcity, while Registered Nurses maintain the broadest demand across facilities.
Service Mode:
Service mode differentiation reflects the operational models staffing agencies employ to serve diverse client needs, from direct placement to integrated workforce management.
- Onsite Staffing:Involves the physical placement of personnel at client facilities for direct patient interaction and care delivery. Hospitals and long-term care facilities in Japan heavily rely on onsite staff for continuous patient monitoring and hands-on care.
- Managed Staffing Services:Provides comprehensive workforce solutions, including vendor management, compliance oversight, and consolidated billing for contingent labor. Large hospital systems in the United States increasingly adopt these services to streamline contingent labor procurement and reduce administrative burdens.
- Remote Staffing:Supplies clinicians for virtual consultations, telehealth platforms, and remote patient monitoring roles.
- Recruitment Process Outsourcing:Agencies manage the entire recruitment lifecycle for client organizations, from sourcing to onboarding.
Onsite Staffing remains the traditional core, yet Remote Staffing is expanding most quickly due to telehealth adoption.
End User:
End user segmentation illustrates where the primary demand volume for healthcare staffing services originates, reflecting varying patient populations and care delivery models.
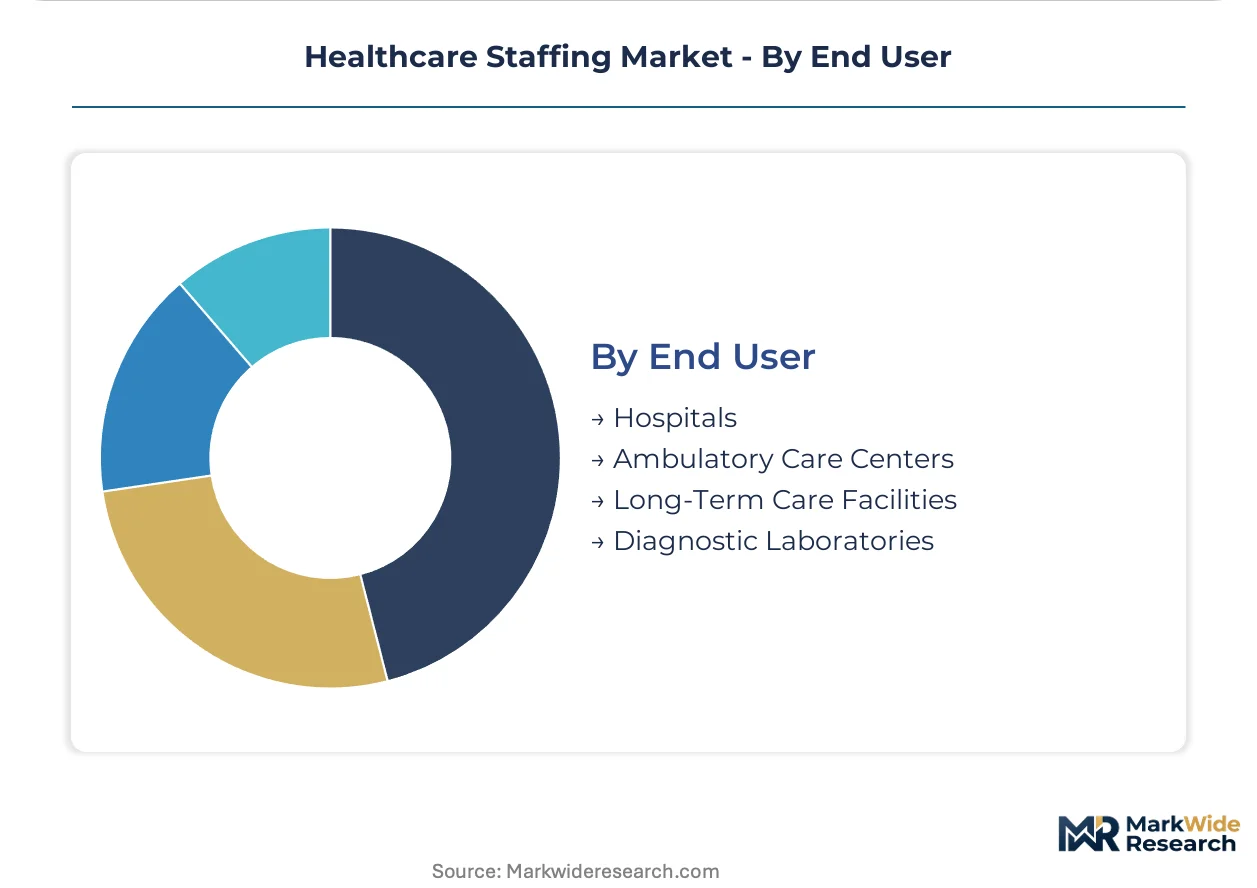
- Hospitals:Represent the largest end-user segment, requiring extensive staffing for acute care, emergency services, and surgical units. Persistent clinical labor shortages in the United States compel hospitals to rely on external agencies for critical coverage.
- Long-Term Care Facilities:Serve aging populations requiring continuous medical and personal care, including nursing homes and assisted living facilities. The expanding elderly population in Germany and Japan directly boosts demand for temporary nurses and allied health professionals in these settings.
- Ambulatory Care Centers:Focus on outpatient services, including clinics, urgent care centers, and specialized diagnostic facilities.
- Diagnostic Laboratories:Require specialized medical technicians and phlebotomists for sample collection, analysis, and testing.
Hospitals consistently generate the highest volume of staffing requests, while Ambulatory Care Centers demonstrate significant growth driven by outpatient shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side dynamics in healthcare staffing largely concentrate within developed economies facing demographic pressures. These regions experience persistent clinical labor shortages, driving demand for flexible staffing solutions. Agencies leverage advanced platforms to improve labor allocation efficiency across these critical markets.
United States
Demand for healthcare staffing in the United States remains exceptionally high due to persistent clinical labor shortages. HIPAA regulations impose strict data privacy mandates on staffing agencies handling patient records. Large hospital systems in cities like New York and Los Angeles increasingly adopt managed staffing services to streamline contingent labor procurement.
Germany
Germany experiences significant demand for permanent placement and temporary staffing in long-term care facilities. The country's national health insurance system influences the need for a stable clinical workforce. Major metropolitan areas such as Berlin and Munich are seeing increased investment in internal resource pools by large hospital networks.
Japan
Aging demographics in Japan are fueling demand for onsite staffing, particularly in nursing homes and geriatric care. The Ministry of Health, Labour and Welfare oversees healthcare workforce planning and credentialing standards. Tokyo and Osaka's healthcare clusters are adopting remote staffing models to address specialist shortages in rural areas.
Australia
Australia's expanded recruitment infrastructure for overseas clinicians is reshaping competitive positioning for agencies. The Therapeutic Goods Administration (TGA) ensures quality standards for healthcare professionals and services. Cities like Sydney and Melbourne are hubs for technology-driven recruitment platforms for nurse-centric mobile recruiting.
Canada
Canadian healthcare providers are seeing expanding demand for physicians in telehealth services, especially in remote areas. Health Canada guidelines influence the adoption of virtual care staffing models. Urban centers such as Toronto and Vancouver are investing in AI-powered credentialing solutions to automate compliance and placement processes.
Healthcare Staffing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing niche services. The market exhibits a tiered structure, with large-scale providers offering comprehensive solutions alongside specialized agencies focusing on specific roles or geographies. Strategic archetypes include technology-driven platforms, diversified portfolio providers, and volume-focused generalists. Portfolio diversification and strategic partnerships are dominant competitive moves.
At the scale-driven end, AMN Healthcare exemplifies an agency leveraging its size to secure large hospital system contracts in the United States. Aya Healthcare represents the technology-centric archetype, differentiating through its platform for nurse-centric mobile recruiting. Cross Country Healthcare occupies a position among diversified portfolio providers, mitigating cyclical demand shifts through clinical and non-clinical placements.
| Leading Market Players |
|---|
| AMN Healthcare |
| Aya Healthcare |
| CHG Healthcare |
| Medical Solutions |
| Cross Country Healthcare |
| Amergis Healthcare Staffing |
| Maxim Healthcare |
| Interim HealthCare |
| MedPro Healthcare Staffing |
| Others |
Cost & Logistics Intelligence
Regulatory fragmentation, particularly inconsistent state-level credentialing in the United States, determines both pricing tier spreads and the operational shape of the healthcare staffing supply chain. This complexity directly increases compliance costs for agencies and influences the speed of clinician deployment.
Pricing Analysis
HIPAA regulations dictate the pricing tier structure for data-sensitive placements, ensuring agencies invest in secure data handling. Contract-based long-term offtake models for large hospital systems dominate, alongside per-unit transactional pricing for temporary staffing. Pricing differentiation stems from clinician specialization, particularly for high-acuity roles, and rapid deployment capabilities across Nurse Licensure Compact states. Wage inflation for qualified clinicians creates upward pricing pressure across all segments. Ambulatory care centers exhibit higher price sensitivity compared to large hospital systems with critical, immediate staffing needs.
Supply Chain Analysis
Regulatory restrictions on cross-border clinician movement and data flows limit the agile deployment of international talent. The supply of qualified healthcare professionals concentrates heavily in developed economies like the United States, alongside emerging source countries for overseas clinicians like the Philippines. Key dependencies include Registered Nurses, Allied Health Professionals, and Physicians, supported by credentialing software. Credentialing fragmentation across US states represents a significant structural risk. Digital platforms and Vendor Management Systems (VMS) form the dominant downstream distribution model, streamlining procurement for healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, with incumbents navigating the growing threat of large hospital systems developing their own internal resource pools.
For Market Incumbents: Pre-empt the erosion of market share by actively investing in advanced AI-powered credentialing and matching platforms. Deepen strategic relationships with large hospital networks through comprehensive Managed Service Provider (MSP) programs, offering integrated workforce solutions beyond basic staffing. Focus on retaining high-acuity specialists through competitive compensation and career development pathways to counter internal agency models.
For New Entrants and Emerging Players: Underpenetrated emerging markets in Southeast Asia present significant white-space opportunities for specialized staffing services. Target developing healthcare infrastructure in countries like Vietnam by offering technology-driven mobile platforms for localized recruitment. Focus on niche segments such as remote telehealth staffing for underserved rural populations, leveraging virtual care models as a go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-centric platforms and diversified portfolio providers. Long-term viability remains strong due to persistent clinical labor shortages and aging global demographics over the next decade. Acquisition targets should include niche firms specializing in AI-powered compliance solutions or telehealth staffing. Accelerated adoption of national or interstate licensure compacts for nurses is a key signal to watch for enhanced market fluidity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Streamlines clinician placement and compliance, reducing operational overhead for agencies. |
| Strategic Partnership | Secures long-term contracts with large hospital systems, ensuring stable demand volume. |
| Geographic Expansion | Accesses new talent pools and addresses unmet demand in emerging healthcare markets. |
| Technology Licensing | Enhances AI-powered credentialing capabilities, improving matching efficiency and compliance. |
| Specialized Service Development | Captures growth in telehealth and remote patient monitoring roles, expanding service offerings. |
Research Approach
The analysis maps temporary staffing, permanent placement, remote staffing, and managed staffing services, each validated through extensive primary interviews with industry stakeholders. This involved conversations with clinical directors, human resource managers at hospitals, staffing agency executives, and allied health professionals. Secondary validation draws from government health department reports, healthcare industry association publications, and financial filings of publicly traded staffing firms, triangulating data from both bottom-up and top-down approaches.
The forecast framework assumes a continuation of current healthcare policy trajectories across the projection horizon, with variations in technological adoption rates. Segmentation dimensions modeled include staffing type, healthcare roles, service mode, end-user categories, and regional demand dynamics. Compound Annual Growth Rates (CAGRs) derive from historical growth patterns and future demand projections. Key industry-specific forecast inputs include aging population growth rates and per capita healthcare expenditure trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large hospital systems creating internal float pools or technology disruptors would shift outcomes. These forecasts reflect assumptions documented through a rigorous validation process. Material shifts in government healthcare policies or major technological advancements in automated care delivery would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Hospice Care Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Care Services Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Kids Sports Injury Treatment Market