
 Michigan Urgent Care Center Market | 2026-2036
Michigan Urgent Care Center Market Size, Share, and Industry Trends Forecast 2026-2036
Michigan Urgent Care Center Market Intelligence
Michigan's southeastern health corridor is tilting toward outpatient capacity expansion as health systems redirect emergency department overflow. Spectrum Health leverages its integrated delivery network to anchor urgent care access across West Michigan. Corewell Health sustains geographic dominance through hospital-owned centers that feed downstream specialty referrals. Concentra, Inc. specializes in occupational health clinics positioned near manufacturing employers in Grand Rapids and Lansing.
An urgent care center delivers episodic, non-emergency medical services through walk-in facilities equipped with on-site diagnostics, suture capabilities, and basic laboratory processing. These centers bridge primary care access gaps and divert non-critical cases from hospital emergency departments, operating with lower cost structures and faster throughput times. Hospital-owned centers capture the deepest patient flows and payer contracts, while independent centers compete on convenience and price transparency under self-pay and direct primary care models. Occupational health services generate the most predictable revenue streams through employer contracts, whereas pediatric care segments face margin pressure from seasonal volume variability and Medicaid reimbursement constraints.
Michigan's Department of Licensing and Regulatory Affairs enforces facility licensing standards that dictate staffing ratios and scope-of-service limitations for urgent care operators. The federal Centers for Medicare and Medicaid Services shapes reimbursement frameworks that determine payer mix viability across facility types. OSHA workplace health requirements drive employer demand for occupational medicine programs. Stakeholders must monitor how Michigan's evolving scope-of-practice regulations for nurse practitioners and physician assistants reshape staffing economics and rural site feasibility.
Market Dynamics
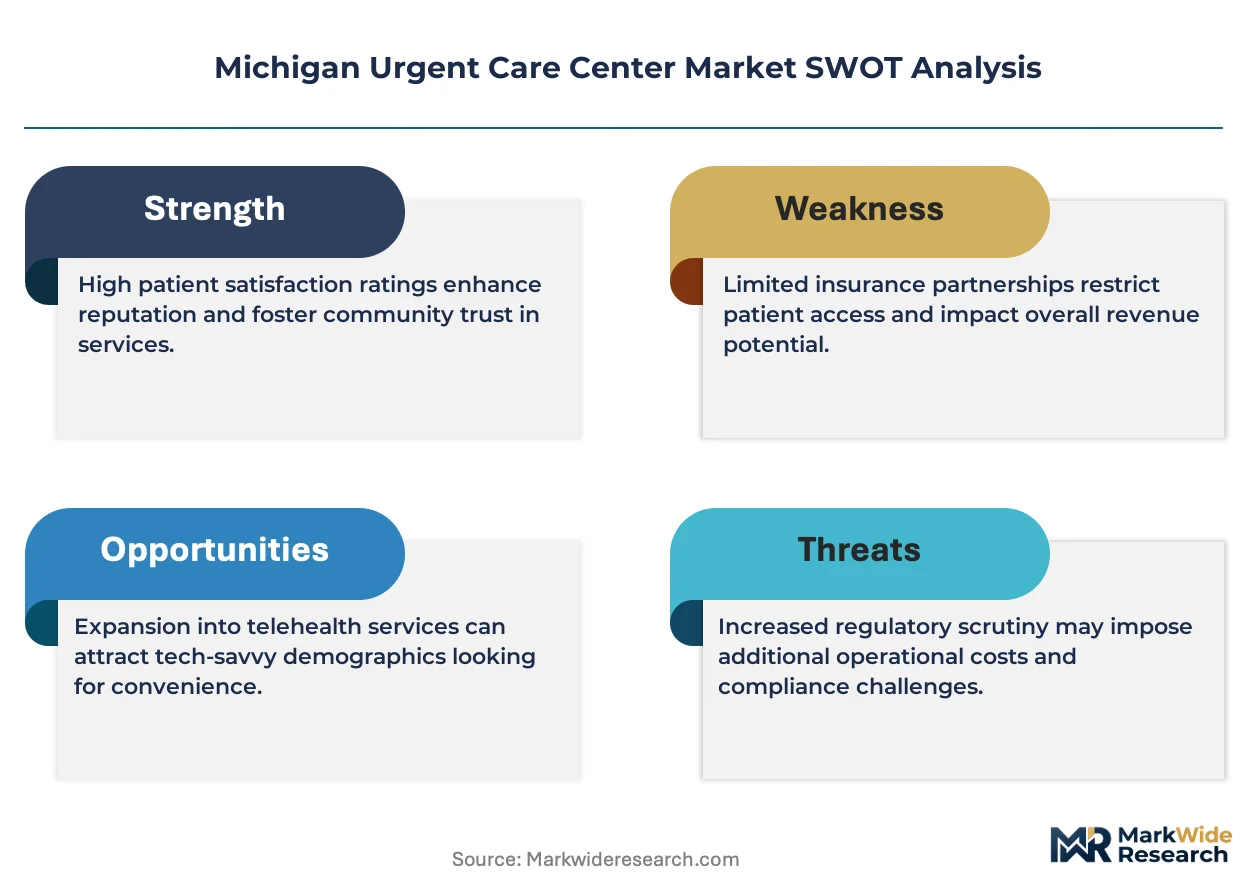
Michigan's Certificate of Need program creates artificial scarcity in facility licensing, forcing operators to secure regulatory approval before expanding diagnostic capabilities or adding service lines. This constraint compresses competitive timelines and elevates strategic site selection above operational efficiency as the primary growth lever.
Growth Catalysts
- OSHA workplace health mandates:Manufacturing employers in Grand Rapids and Lansing must maintain compliant occupational medicine programs, generating predictable contract revenue for clinics positioned near industrial corridors.
- Detroit-Warren-Ann Arbor corridor density:Population concentration aligns with commercial insurance penetration, creating favorable payer mix conditions for urgent care operators targeting middle-income households.
- Telehealth integration:Remote triage capabilities extend clinic reach into rural Upper Peninsula counties where physical facility economics fail, expanding addressable patient populations without capital deployment.
Market Restraints
- Medicaid reimbursement compression:Michigan's Medicaid fee schedules for urgent care services sit below commercial rates, squeezing margins on pediatric and low-acuity visits that dominate seasonal volume.
- Nurse practitioner scope limitations:State licensing restrictions require physician oversight ratios that inflate staffing costs and constrain rural site feasibility where specialist availability thins.
- Emergency department capacity expansion:Hospital systems adding fast-track ED zones compete directly for the same non-critical patient segment without urgent care's regulatory overhead.
Strategic Opportunities
- Employer onsite clinic penetration:Manufacturing and logistics employers in Flint and Saginaw remain underserved by occupational health networks, creating first-mover advantages for contract-based expansion.
- Value-based care alignment:Michigan's Medicaid managed care organizations increasingly reward preventable ED diversion, positioning urgent care as a cost-containment node in accountable care organization structures.
- Retail health convergence:Pharmacy chains and grocery-anchored clinics are entering Michigan markets, creating partnership or acquisition pathways for independent operators seeking capital access.
Industry Challenges
- Radiology technician recruitment:On-site X-ray and basic imaging capabilities require certified staff that command premium wages in tight Michigan labor markets, particularly outside Detroit metro.
- EHR interoperability fragmentation:Hospital-owned centers operate on Epic or Cerner systems that resist data exchange with independent competitors, complicating care coordination and referral handoffs.
- Seasonal volume volatility:Pediatric respiratory seasons create capacity crunches followed by utilization droughts, demanding flexible staffing models that conflict with clinical quality retention goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Michigan Urgent Care Center Market |
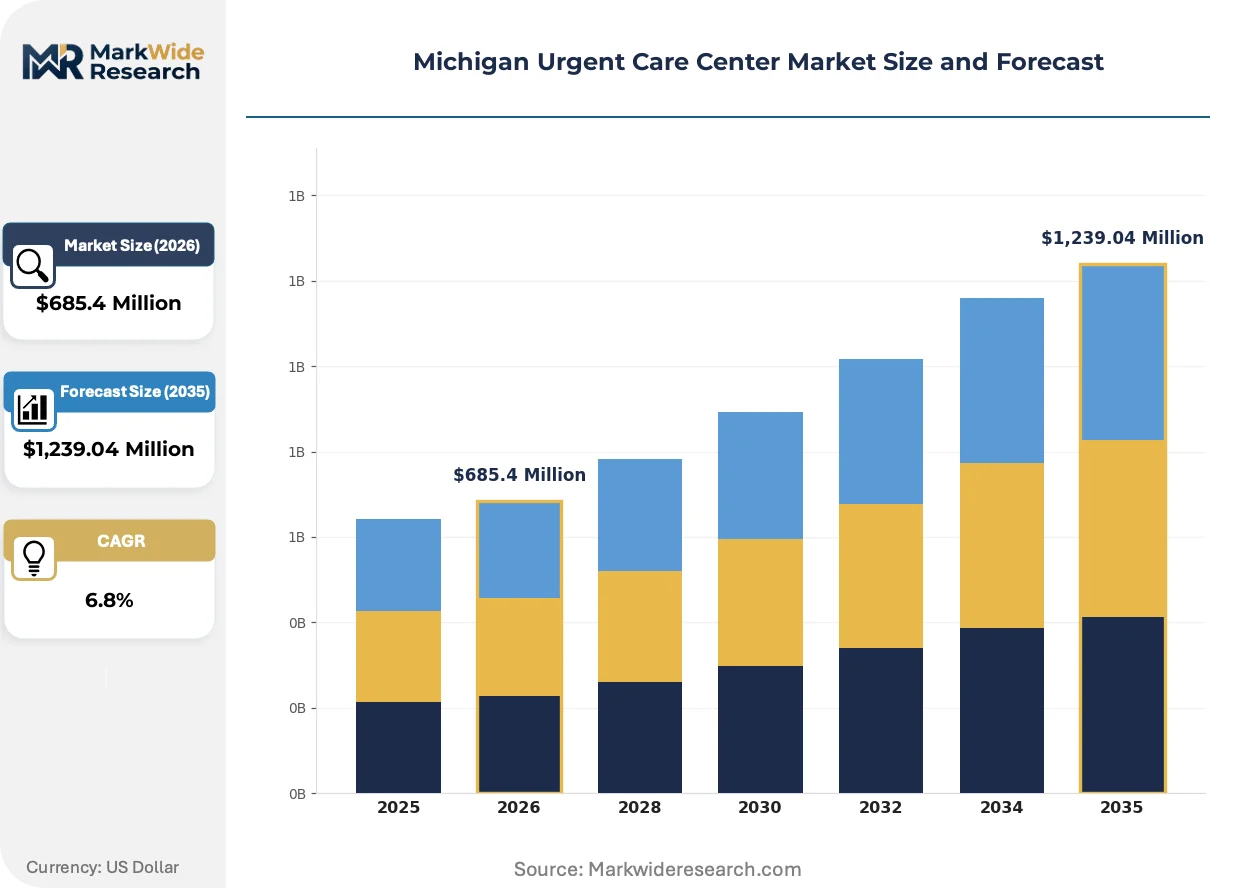
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Occupational Health, Sports Medicine, Pediatric Care, Family Medicine Facility Type: Independent Centers, Hospital-Owned Centers, Retail Clinics, Freestanding Facilities Payment Model: Insurance-Based, Self-Pay, Direct Primary Care, Subscription-Based Patient Demographics: Adults, Children, Seniors, Special Needs |
| Companies Covered | Spectrum Health, Ascension, Michigan Medicine, Corewell Health, Concentra, Inc., MedExpress, American Family Care, NextCare, GoHealth Urgent Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Michigan Urgent Care Center Market Strategic Shifts & Innovations
Digital front-door strategies are redefining patient intake workflows across Michigan's urgent care landscape. Operators now compete on pre-visit convenience rather than post-arrival speed alone.
Point-of-care diagnostic platforms integrating PCR and rapid antigen testing are rendering obsolete centralized laboratory send-out models for respiratory and infectious disease panels. West Michigan health systems deploy these devices at scale. Turnaround times compress from 24-48 hours to under 30 minutes. This capability shift is rendering obsolete the competitive advantage of hospital-affiliated labs that previously captured downstream revenue through referral capture.
Michigan's Department of Licensing and Regulatory Affairs maintains strict facility licensing standards dictating staffing ratios and scope-of-service boundaries. These rules elevate capital requirements for new entrants. Independent operators respond by pursuing hospital joint ventures that transfer regulatory burden to established license holders.
Self-pay and direct primary care models are gaining traction among price-sensitive patients bypassing traditional insurance channels. Cash-transparent pricing appeals to gig economy workers and high-deductible plan holders concentrated in Ann Arbor and Grand Rapids tech corridors. This behavioral shift pressures legacy urgent care operators to unbundle service pricing from payer contract complexity.
Michigan Urgent Care Center Market Segmentation
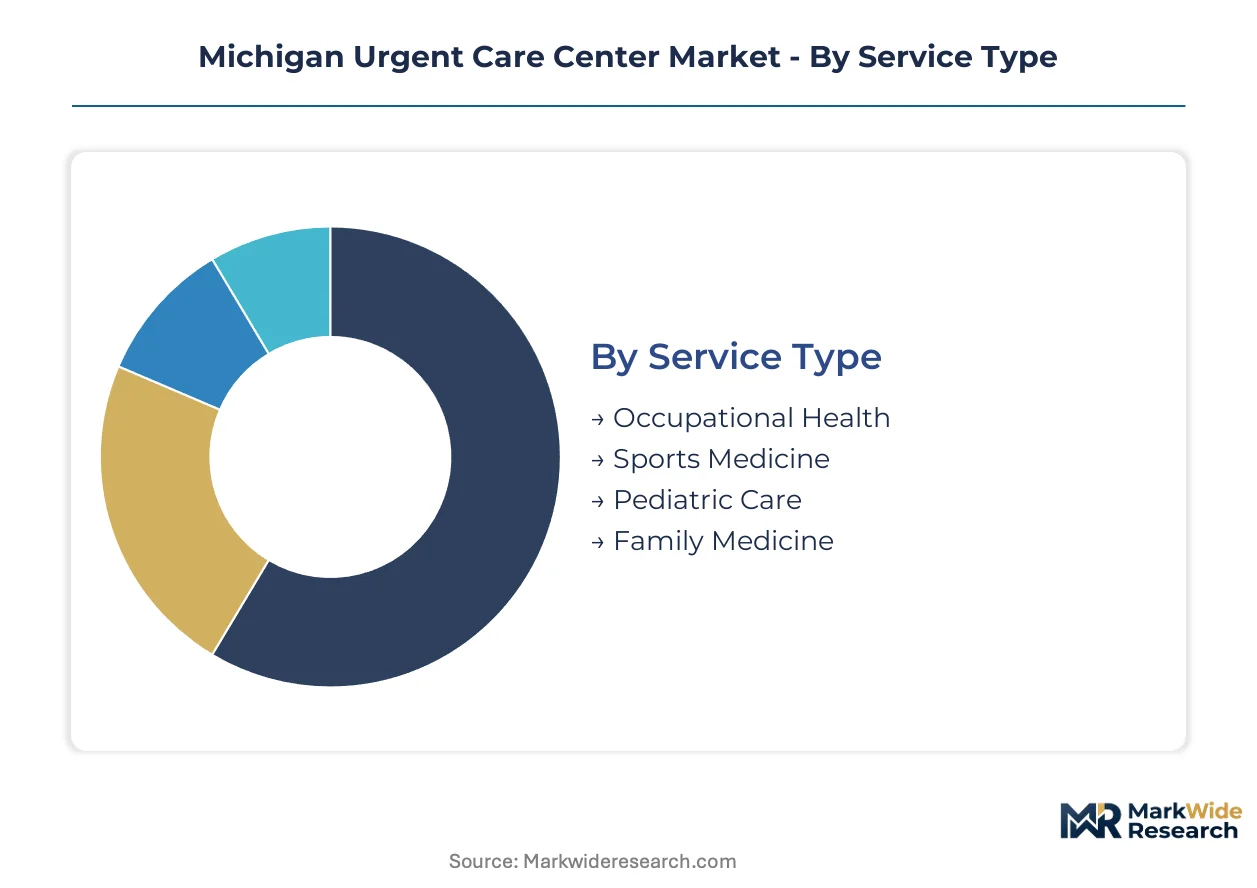
Urgent care operators in Michigan deploy distinct service configurations to match regional labor market demands, payer concentration, and regulatory constraints. Segmentation reveals how facility economics shift across occupational health contracts, pediatric seasonality, and insurance penetration corridors.
Service Type:
Mature service lines anchor revenue stability while emerging specialties reshape competitive positioning.
- Occupational Health:Employer-contracted services encompassing workplace injury treatment, drug screening, and compliance physicals. Demand concentrates in Grand Rapids and Lansing manufacturing corridors where OSHA mandates drive predictable visit volumes through multi-year service agreements.
- Sports Medicine:Orthopedic urgent services targeting athletic injuries with on-site splinting, bracing, and concussion assessment protocols. Southeast Michigan high school and collegiate athletic programs generate concentrated seasonal demand aligned with football and hockey calendars.
- Pediatric Care:After-hours acute illness management for patients under 18, requiring specialized equipment and staff training.
- Family Medicine:General episodic care spanning all age groups, serving as the default catch-all category for undifferentiated urgent complaints.
Occupational health retains volume leadership; sports medicine holds the steepest expansion curve.
Facility Type:
Cost tier stratification separates capital-intensive hospital networks from lean independent operators.
- Hospital-Owned Centers:Integrated delivery network facilities leveraging Epic or Cerner systems for seamless specialty referrals. These command premium reimbursement rates through established payer contracts and downstream revenue capture.
- Independent Centers:Physician- or investor-owned sites competing on price transparency and convenience metrics. Self-pay and direct primary care models proliferate here, particularly in Ann Arbor and Grand Rapids tech corridors where high-deductible plan penetration runs deepest.
- Retail Clinics:Pharmacy- and grocery-anchored micro-facilities offering limited scope services.
- Freestanding Facilities:Purpose-built urgent care structures with full diagnostic capabilities including on-site X-ray and laboratory processing.
Hospital-owned centers dominate revenue concentration; retail clinics are expanding most quickly through pharmacy chain partnerships.
Payment Model:
Customer type fragmentation mirrors Michigan's insurance market heterogeneity across employer-sponsored, Medicaid, and uninsured populations.
- Insurance-Based:Commercial and Medicare Advantage reimbursement structures requiring contracted rate negotiations and prior authorization compliance.
- Self-Pay:Transparent cash pricing for uninsured or high-deductible plan holders seeking cost certainty before treatment.
- Direct Primary Care:Membership-based models offering unlimited urgent access for fixed monthly fees, concentrated among gig economy workers and small employer groups.
- Subscription-Based:Employer-sponsored clinic access programs bundling occupational and urgent services into per-employee-per-month arrangements.
Insurance-based models retain volume leadership; direct primary care holds the steepest expansion curve.
Patient Demographics:
Geographic demand patterns align age-specific service needs with Michigan's population distribution across urban cores and aging rural counties.
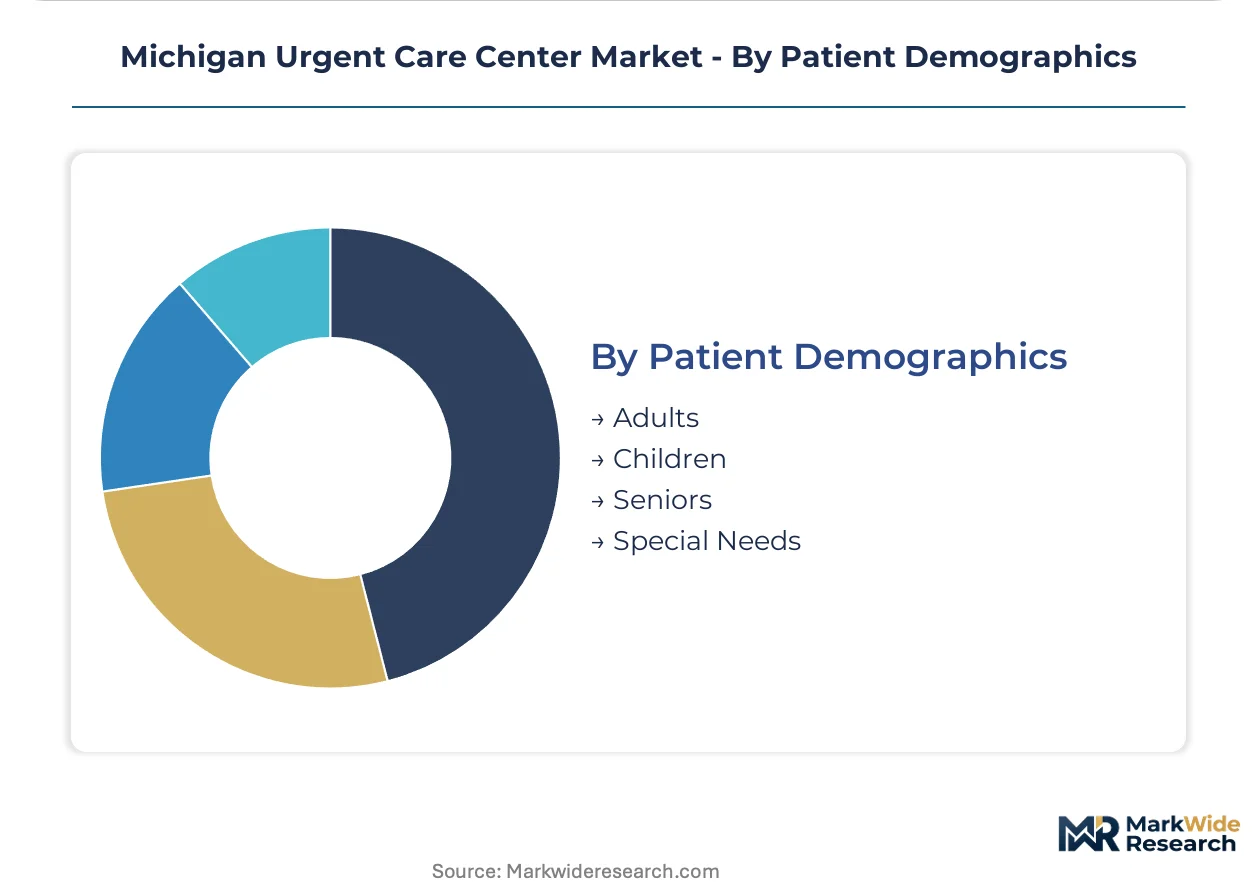
- Adults:Working-age patients aged 18-64 generating the highest visit frequency for occupational injuries and acute illness.
- Children:Pediatric patients under 18 requiring specialized dosing protocols and family-centered care environments.
- Seniors:Medicare-eligible patients over 65 with complex comorbidities often exceeding urgent care scope, creating referral pressure to emergency departments.
- Special Needs:Patients with developmental disabilities or behavioral health conditions requiring modified facility accommodations and extended visit durations.
Adult demographics retain volume leadership; senior-focused services are expanding most quickly as Michigan's population ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace health mandates anchor demand concentration across Michigan's industrial corridors, with the state's Department of Licensing and Regulatory Affairs enforcing facility standards that shape expansion feasibility. Population density and insurance penetration create divergent economics across sub-regional markets.
Detroit-Warren-Ann Arbor Corridor
Commercial insurance penetration rates exceed state averages here, supporting premium reimbursement structures for urgent care operators. Michigan's Certificate of Need program delays facility licensing for new diagnostic capabilities, compressing competitive timelines. Hospital systems in Detroit and Ann Arbor leverage integrated Epic networks to capture downstream specialty referrals from urgent care entry points.
West Michigan
Manufacturing employers in Grand Rapids generate predictable occupational health contract volumes through multi-year service agreements. OSHA compliance requirements for workplace injury reporting sustain clinic utilization independent of seasonal illness patterns. Spectrum Health anchors integrated delivery network coverage across Kent and Ottawa counties, feeding patient flows into hospital-owned specialty services.
Central Michigan
Lansing's state government employment base creates stable commercial insurance demand alongside manufacturing corridors to the south. Nurse practitioner scope limitations under state licensing rules inflate staffing costs, constraining rural site feasibility where physician oversight availability thins. Concentra positions occupational health clinics near industrial employers in Eaton and Ingham counties.
Northern Lower Peninsula
Seasonal tourism around Traverse City and Petoskey creates volatile utilization patterns that conflict with fixed staffing models. Telehealth triage capabilities extend clinic reach without capital deployment, addressing rural access gaps where physical facility economics fail. Medicaid reimbursement compression squeezes margins on pediatric and low-acuity visits that dominate summer volume spikes.
Upper Peninsula
Geographic isolation and sparse population density render traditional urgent care facility economics unworkable across most of the region. Michigan's evolving scope-of-practice regulations for nurse practitioners reshape rural site feasibility where specialist availability is minimal. Hospital systems deploy mobile and telehealth modalities to capture episodic demand without brick-and-mortar investment.
Michigan Urgent Care Center Market Key Industry Players
Capability concentration sits with hospital-owned networks; scale advantage sits with national occupational health chains. The market structures around three tiers: integrated delivery networks commanding premium payer contracts, employer-focused operators capturing predictable contract revenue, and independent centers competing on price transparency. Strategic moves concentrate on geographic densification through Certificate of Need positioning and telehealth integration for rural reach extension.
Among hospital-affiliated operators, Spectrum Health and Corewell Health anchor integrated network positions that exemplify the capability-concentrated tier. Concentra, Inc. represents the employer-contract specialization archetype, with its positioning near manufacturing corridors reflecting the scale-driven competitive vector. These three entities collectively illustrate how reimbursement structure alignment and regulatory licensing access determine sustainable market positioning.
| Leading Market Players |
|---|
| Spectrum Health |
| Ascension |
| Michigan Medicine |
| Corewell Health |
| Concentra, Inc. |
| MedExpress |
| American Family Care |
| NextCare |
| GoHealth Urgent Care |
| Others |
Cost & Logistics Intelligence
Undercapacity in Michigan's Upper Peninsula and Northern Lower Peninsula drives divergent pricing postures across the state, with rural telehealth deployments commanding premium reimbursement while Detroit-Warren-Ann Arbor corridor saturation compresses margins through competitive density.
Pricing Analysis
Geographic price spreads separate Michigan's urgent care market into three distinct reimbursement zones. Hospital-owned centers in Detroit and Ann Arbor capture premium commercial rates through established payer contracts and downstream specialty capture, while independent operators in Grand Rapids and Lansing compete on transparent cash pricing for high-deductible plan holders. Medicaid reimbursement compression squeezes pediatric and low-acuity visit margins statewide, particularly in seasonal tourism corridors where volume volatility conflicts with fixed staffing costs. Self-pay and direct primary care models show the highest price sensitivity among gig economy workers, whereas employer-sponsored occupational health contracts demonstrate the lowest sensitivity due to OSHA compliance mandates.
Supply Chain Analysis
Extended payment terms from Michigan's hospital systems are reshaping supplier financing structures for independent urgent care operators. Medical equipment and diagnostic device supply concentrates in the United States, Germany, and China, with point-of-care PCR platforms and digital radiography systems representing critical capital dependencies. Single-source vulnerability sits with specialized laboratory consumables and certified radiology technician labor pools, particularly outside Detroit metro where recruitment tightens. Distribution runs through integrated delivery network procurement channels for hospital-affiliated centers, while independent operators source through group purchasing organizations and direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Michigan's urgent care market is cycling through a post-pandemic normalization phase, with seasonal respiratory volume patterns and employer contract renewals driving the recovery rhythm.
For Market Incumbents: Harden Certificate of Need positioning through preemptive licensing applications for diagnostic capability expansion before competitors secure regulatory slots. Deepen Epic and Cerner interoperability investments to lock in referral capture from hospital-owned entry points, while defending against retail clinic encroachment through employer contract exclusivity clauses in manufacturing corridors.
For New Entrants and Emerging Players: Pursue Flint and Saginaw occupational health white space where manufacturing employers remain underserved by incumbent networks. Target direct primary care membership models in Ann Arbor and Grand Rapids tech corridors, where high-deductible plan penetration and price transparency demand align with lean operational structures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telehealth-enabled rural extension models, reducing barrier-to-entry calculations for scalable platforms. Acquisition targets should concentrate on independent operators with established OSHA employer contracts and Certificate of Need licenses in constrained geographies. Watch for Michigan Department of Licensing and Regulatory Affairs scope-of-practice rule changes as the signal for rural site feasibility inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Certificate of Need Pre-Positioning | Secures regulatory licensing slots before artificial scarcity constraints expansion timelines. |
| Employer Contract Exclusivity | Locks multi-year occupational health revenue streams in Grand Rapids manufacturing corridors. |
| Epic Network Integration | Enables seamless downstream specialty referral capture from urgent care entry points. |
| Telehealth Rural Extension | Expands addressable patient populations without capital-intensive brick-and-mortar deployment. |
| Point-of-Care Diagnostic Deployment | Compresses laboratory turnaround times and captures revenue previously sent to hospital-affiliated labs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of CMS Medicare cost reports, Michigan Department of Licensing and Regulatory Affairs facility filings, and GPO contract databases. Interviews with urgent care operators, hospital system strategy officers, employer benefits managers, and biomedical equipment suppliers inform demand-side and supply-side validation. Bottom-up modeling of facility economics and top-down reconciliation against state health expenditure data ensure cross-verified outputs.
Forecast inputs include service line segmentation by occupational health, sports medicine, pediatric care, and family medicine; facility type stratification across hospital-owned, independent, retail, and freestanding structures; and payment model differentiation across insurance-based, self-pay, direct primary care, and subscription-based arrangements. CAGRs derive from regression analysis of historical utilization trends, payer mix evolution, and regulatory capacity constraints. Nurse practitioner scope-of-practice liberalization scenarios and Medicaid reimbursement schedule revisions serve as sensitivity inputs.
Sensitivities concentrate around Certificate of Need approval timelines, scope-of-practice regulatory shifts, and employer-sponsored insurance penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Funeral Goods and Services Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Contract Manufacturing Services Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
US Hospice Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Care Services Market
Healthcare Services
Spa Services Market