
 Funeral and Cremation Services Market | 2026-2036
Funeral and Cremation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Funeral and Cremation Services Market Intelligence
EPA mercury emissions rules for crematoria is pivoting the industry toward costly filtration retrofits and new-build compliance. Service Corporation International leverages its North American scale to absorb these capital requirements across hundreds of facilities. Dignity Plc anchors its UK position through pre-need funeral plan trusts that lock in future revenue. Nirvana Asia Ltd. dominates Southeast Asian markets with integrated cemetery-crematorium complexes that control land scarcity.
Funeral and cremation services encompass the preparation, disposition, and commemoration of human remains through burial, flame-based or alkaline hydrolysis reduction, and memorial ceremonies, typically operating under state or provincial licensing with facility permits for emissions, health, and zoning compliance. The primary purpose is managing sanitary final disposition while delivering grief-support rituals to families and communities. Cremation now leads service type mix in most developed economies as cultural acceptance widens and land costs for traditional burial escalate. Online planning tools within the technology segment represent the fastest-expanding category, with virtual memorials and streaming services capturing margin pools previously lost to third-party platforms. Memorial products and keepsakes sustain higher per-transaction yields than commoditized caskets and urns.
The US EPA enforces Maximum Achievable Control Technology standards for crematory mercury emissions, while the EU F-Gas Regulation constrains fluorinated greenhouse gases in refrigeration for body storage, and state-level cemetery and funeral service boards across Australia mandate trust fund adequacy ratios for pre-paid contracts. These frameworks elevate compliance spending but also create barriers that favor scaled operators over fragmented independents. Stakeholders must monitor regulatory divergence between jurisdictions as it determines where capital deployment for new capacity earns acceptable risk-adjusted returns.
Market Dynamics
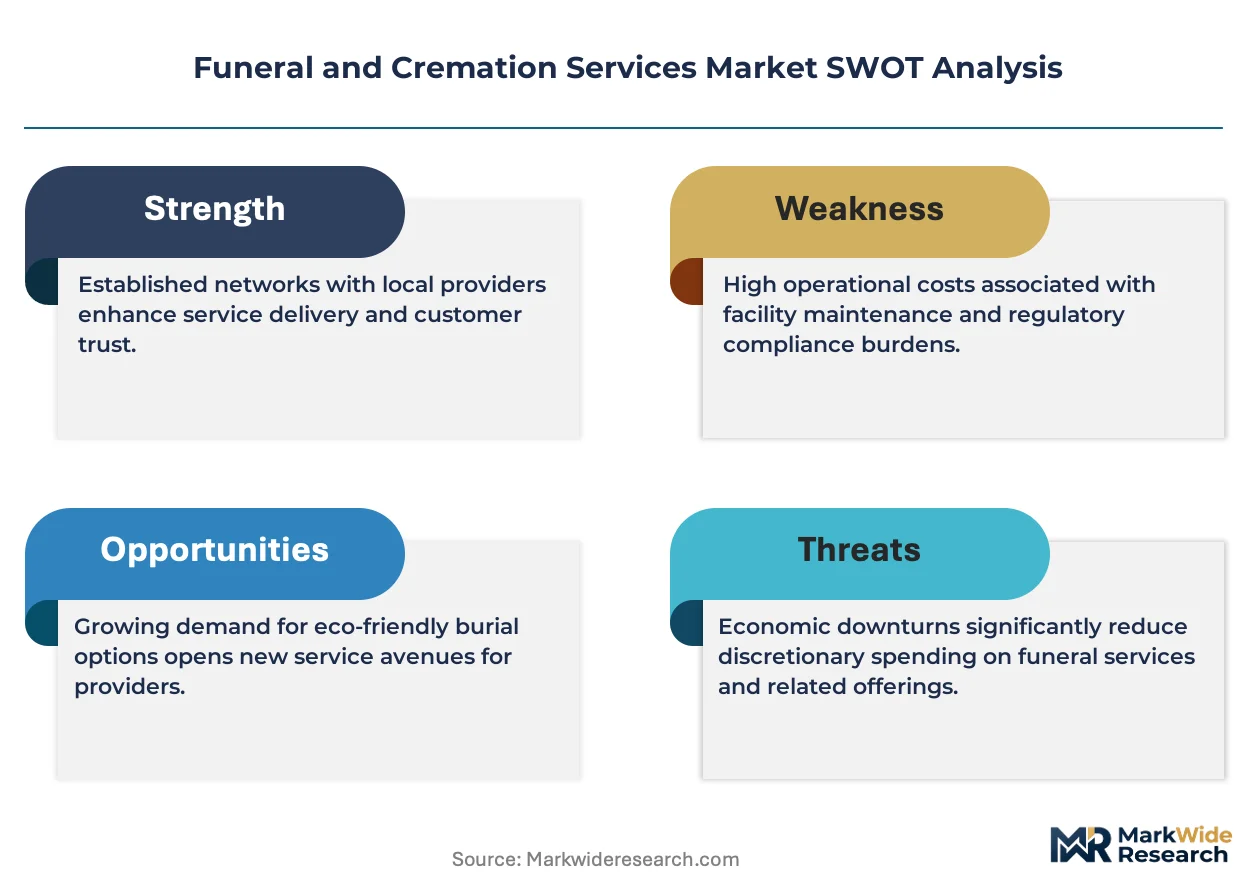
Pre-need funeral planning among aging populations is consolidating demand around licensed operators with trust-fund capacity, compressing the independent funeral home segment and elevating compliance capital requirements across the cremation technology supply chain.
Growth Catalysts
- EU Green Deal environmental standards:The framework redirects facility investment toward mercury filtration and low-emission retort systems, accelerating technology replacement cycles.
- Alkaline hydrolysis adoption:Water-based disposition methods gain regulatory approval in additional jurisdictions, expanding service menus beyond flame cremation.
- United States baby-boomer demographics:The cohort's mortality transition concentrates volume in metropolitan markets with scaled cemetery-crematorium complexes.
Market Restraints
- EPA Maximum Achievable Control Technology compliance:Crematory mercury emission retrofits impose capital burdens that fragment operators unable to access financing.
- Land scarcity for cemetery expansion:Urban zoning restrictions in Japan and Singapore constrain greenfield burial capacity and inflate per-plot costs.
- Flame cremation energy intensity:Natural gas price volatility directly pressures operating margins at facilities without thermal efficiency upgrades.
Strategic Opportunities
- Virtual memorial and streaming services:Digital commemoration platforms capture margin pools previously lost to third-party technology providers.
- Biodegradable urns and ocean disposition:Coastal regulatory frameworks in California and Florida enable expansion of scattering services and reef burial alternatives.
- Pre-need trust fund consolidation:Regulatory scrutiny of independent plan providers in the United Kingdom creates acquisition pathways for capitalized operators.
Industry Challenges
- Embalmer and crematory operator certification pipelines:Vocational program enrollment declines constrain staffing at facilities facing volume surges.
- Multi-jurisdiction trust fund adequacy compliance:Australian state-level pre-paid contract reserve requirements demand specialized actuarial and accounting infrastructure.
- Legacy cemetery management system integration:Cloud-based planning tools encounter data migration friction with decades-old burial record archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Funeral and Cremation Services Market |
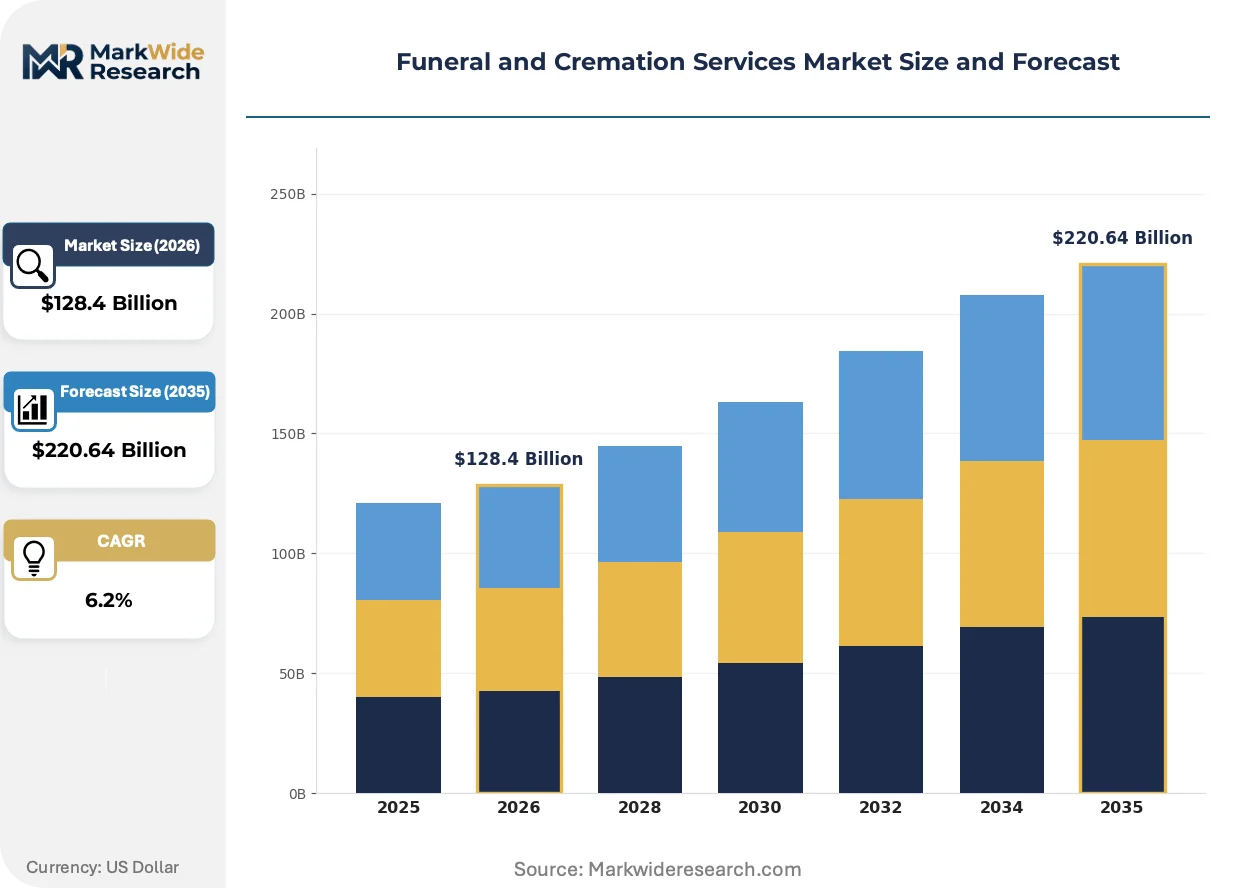
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $220.64 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Traditional Burial, Cremation, Memorial Services, Green Burials Customer Type: Individuals, Families, Funeral Homes, Pre-need Planning Product Offering: Caskets, Urns, Memorial Products, Keepsakes Technology: Online Planning Tools, Virtual Memorials, Funeral Home Software, Streaming Services |
| Companies Covered | Service Corporation International, StoneMor Partners, Dignity Plc, InvoCare Australia Pty Ltd., Carriage Services, Park Lawn Corporation, Nirvana Asia Ltd., NorthStar Memorial Group, Foundation Partners Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Funeral and Cremation Services Market Strategic Shifts & Innovations
Digital commemoration platforms and regulatory pressure on emissions are converging to transform how services are delivered, priced, and consumed across the disposition value chain.
Alkaline hydrolysis technology is rewriting competitive positioning in jurisdictions where water-based reduction receives equivalent legal status to flame cremation. Facilities in Minnesota and Ontario are installing commercial-scale resomators to serve environmentally motivated pre-need planners. The technology compresses mercury management costs while enabling nutrient recovery partnerships with agricultural sectors.
REACH chemical restrictions and EU F-Gas Regulation constraints on fluorinated greenhouse gases are reshaping body storage refrigeration specifications across European mortuary facilities. Equipment suppliers must certify replacement units under phasedown schedules that accelerate capital replacement cycles. German and Dutch operators face the steepest compliance timelines due to earlier national implementation dates.
Family procurement of funeral services is fragmenting across direct cremation brokers, online planning platforms, and traditional full-service homes. Price transparency tools enable comparison shopping that disintermediates longstanding referral relationships between hospitals and legacy operators. The United Kingdom and Australia exhibit the most pronounced channel shift, where digital-first entrants capture cremation-only volume.
Funeral and Cremation Services Market Segmentation
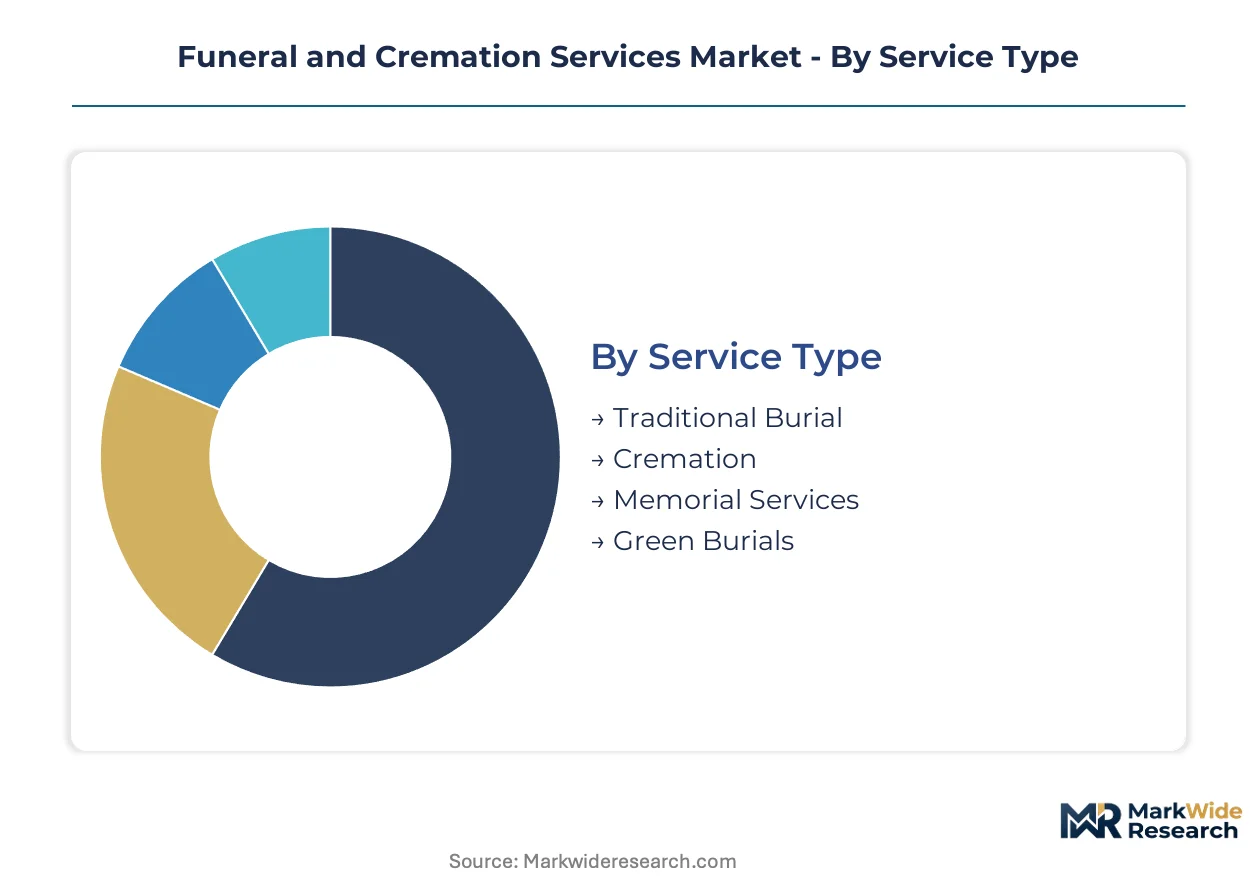
Service configuration in funeral and cremation markets follows distinct procurement patterns across disposition methods, buyer relationships, commemorative merchandise, and digital infrastructure. Segmentation clarity enables operators to align capital deployment with margin concentration and regulatory exposure.
Service Type:
Disposition technology defines facility investment requirements and emissions compliance exposure.
- Cremation:Flame-based and alkaline hydrolysis reduction methods now dominate service mix in developed economies. Demand concentrates in United States metropolitan markets where baby-boomer mortality transition coincides with land cost escalation for burial alternatives. EPA mercury filtration mandates and EU Green Deal emission standards are redirecting capital toward retort upgrades and water-based systems.
- Traditional Burial:Earth interment requires perpetual cemetery maintenance and land reserves that face urban zoning compression. Japan and Singapore exhibit acute scarcity-driven cost inflation as municipal authorities restrict greenfield cemetery development. This segment retains cultural significance in Catholic and Orthodox communities despite share erosion.
- Memorial Services:Ceremony-only offerings decouple commemoration from disposition, enabling price competition through venue flexibility and clergy selection.
- Green Burials:Chemical-free interment in biodegradable containers appeals to environmental certification-motivated planners in California and Pacific Northwest markets.
Mature deployment sits with Traditional Burial. Newer deployment is concentrated in Cremation.
Customer Type:
Procurement authority shapes pricing power, payment timing, and trust fund regulatory exposure.
- Pre-need Planning:Advance funeral arrangements lock in future revenue through licensed trust structures that demand actuarial reserve adequacy. United Kingdom regulatory scrutiny of independent plan providers is compressing the fragmented provider base. Australian state-level trust fund ratio mandates require specialized compliance infrastructure that favors scaled operators.
- Families:At-need purchasing decisions occur under time constraint and emotional duress, limiting price elasticity and sustaining premium service tiers. Hospital and hospice referral relationships remain significant volume channels despite digital disintermediation pressures.
- Individuals:Solo planners utilizing direct cremation brokers and online platforms drive commoditization in basic disposition services.
- Funeral Homes:Wholesale procurement of caskets, urns, and embalming supplies operates on volume contracts with tiered pricing structures.
Pre-need Planning commands the steepest expansion trajectory as aging demographics accelerate advance arrangement uptake.
Product Offering:
Margin structure diverges sharply between commoditized containment and personalized commemoration.
- Memorial Products:Customized headstones, plaques, and engraving services sustain higher per-transaction yields through material selection and artistic labor. Demand clusters in cemetery-crematorium complexes where Nirvana Asia Ltd. controls integrated land scarcity in Southeast Asian markets.
- Keepsakes:Cremation jewelry, fingerprint impressions, and ash-infused glass command premium pricing through emotional value attachment rather than material cost. Digital design tools enable mass customization without inventory risk.
- Caskets:Metal and wood burial containers face price transparency pressure from online distributors and direct cremation growth.
- Urns:Vessel commoditization intensifies as biodegradable and scattering alternatives reduce permanent storage demand.
Margin capture concentrates in Memorial Products and Keepsakes as containment products face yield compression.
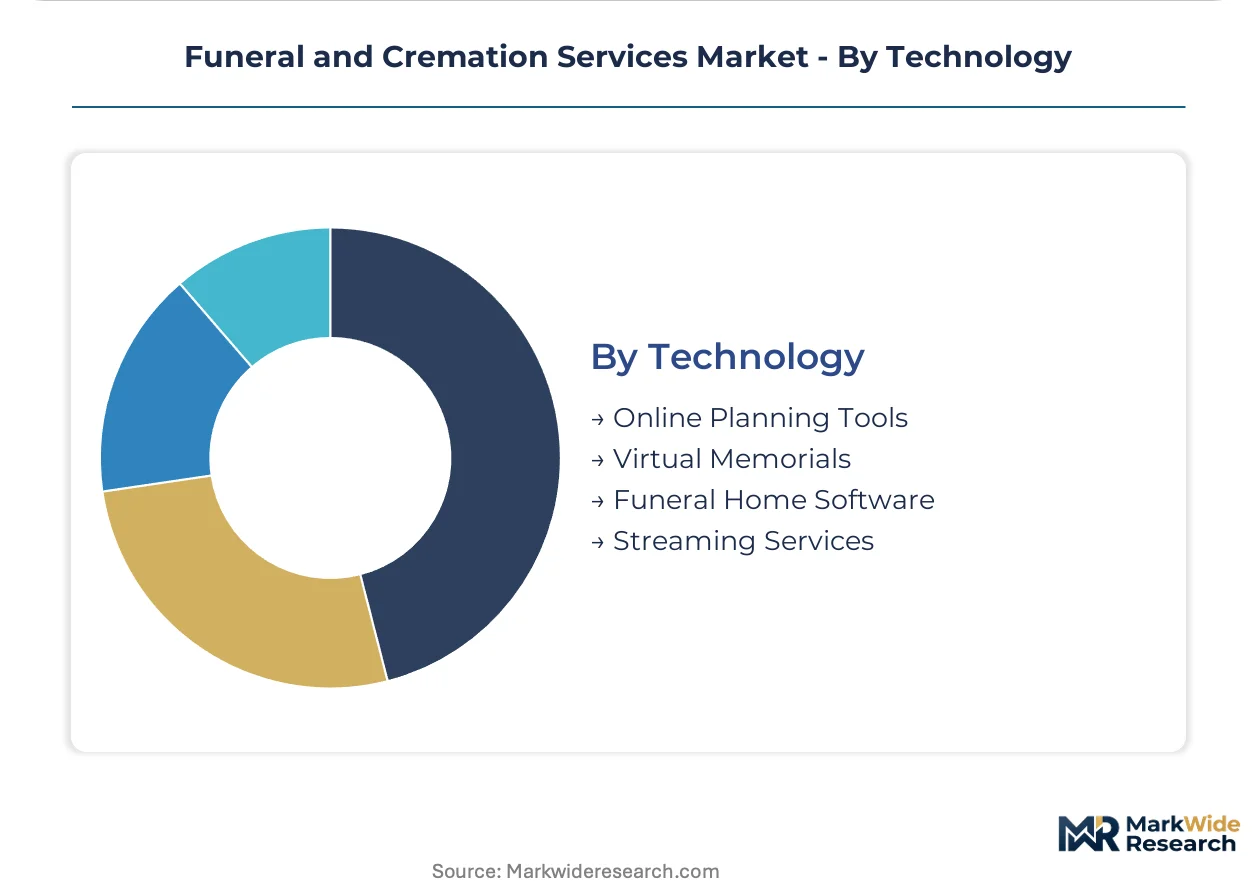
Technology:
Digital infrastructure investment determines customer acquisition cost and service differentiation.
- Virtual Memorials:Streaming ceremonies, digital guestbooks, and online tribute walls capture margin pools previously lost to third-party technology providers. United Kingdom and Australian markets exhibit pronounced channel shift where digital-first entrants disintermediate legacy operators.
- Online Planning Tools:Price transparency platforms enable comparison shopping that fragments traditional hospital-referral relationships. Cloud-based systems encounter data migration friction with decades-old burial record archives at legacy cemeteries.
- Streaming Services:Live and recorded ceremony distribution became essential infrastructure during pandemic restrictions and retains adoption for dispersed families.
- Funeral Home Software:Scheduling, compliance documentation, and trust fund management systems elevate operational efficiency at multi-location operators.
Virtual Memorials and Online Planning Tools are climbing the fastest as consumer procurement patterns digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level pre-need trust fund frameworks in the United States concentrate licensed operator investment, while Japan's municipal cemetery land scarcity and Germany's REACH chemical compliance timelines create divergent capital deployment conditions across major markets.
United States
Baby-boomer mortality transition concentrates volume in metropolitan cemetery-crematorium complexes across Florida, Arizona, and California. EPA Maximum Achievable Control Technology standards for mercury emissions mandate costly filtration retrofits at legacy facilities. Houston and Phoenix clusters absorb these capital requirements through scaled operator consolidation.
Japan
Urban zoning restrictions in Tokyo, Osaka, and Yokohama constrain greenfield burial capacity and inflate per-plot costs. METI guidelines on funeral service pricing transparency compress independent operator margins. Chiba Prefecture's integrated memorial park developments exemplify land-scarcity-driven vertical integration of cemetery and crematorium functions.
Germany
REACH chemical restrictions and EU F-Gas Regulation phasedown schedules accelerate refrigeration equipment replacement at mortuary facilities. North Rhine-Westphalia and Bavaria face the steepest compliance timelines due to earlier national implementation dates. Cologne and Munich operators invest in low-emission retort systems ahead of federal mandates.
United Kingdom
Regulatory scrutiny of independent pre-need funeral plan providers compresses the fragmented provider base. Financial Conduct Authority oversight of trust fund adequacy creates acquisition pathways for capitalized operators. London and Southeast England clusters dominate pre-need planning volume through licensed trust structures.
Australia
State-level pre-paid contract reserve requirements demand specialized actuarial infrastructure that favors scaled operators. TGA-aligned state funeral service boards mandate trust fund ratio compliance across New South Wales, Victoria, and Queensland. Sydney and Melbourne metropolitan markets exhibit the most pronounced digital channel shift toward online planning platforms.
Funeral and Cremation Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a market structure consolidating around scaled trust-fund operators and integrated cemetery-crematorium complexes. Tiered concentration separates North American volume leaders from regional specialists in Asia-Pacific and European markets. Two strategic archetypes dominate: capital-heavy consolidators absorbing compliance costs across facility networks, and land-scarce integrated operators controlling cemetery-crematorium development. Competitive moves concentrate on pre-need trust fund acquisitions and alkaline hydrolysis technology licensing.
Within the North American consolidator tier, Service Corporation International and Carriage Services exemplify scale-driven absorption of EPA compliance costs across multi-state facility portfolios. Dignity Plc anchors UK market positioning through pre-need funeral plan trust structures. Nirvana Asia Ltd. occupies the integrated land-scarcity archetype in Southeast Asian markets.
| Leading Market Players |
|---|
| Service Corporation International |
| StoneMor Partners |
| Dignity Plc |
| InvoCare Australia Pty Ltd. |
| Carriage Services |
| Park Lawn Corporation |
| Nirvana Asia Ltd. |
| NorthStar Memorial Group |
| Foundation Partners Group |
| Others |
Cost & Logistics Intelligence
Natural gas input costs cascade through flame cremation operating margins to shape three-tier pricing differentiation across premium memorial packages, standard service bundles, and economy direct-cremation offerings. EPA mercury filtration mandates and EU Green Deal emission standards elevate capital recovery requirements at facility level, compressing margins for independents while scaled operators absorb retrofits across volume bases.
Pricing Analysis
Short lead-time premiums attach to at-need arrangements where families face compressed decision windows under emotional duress, while pre-need planners capture spot-inventory discounts through advance trust-fund commitments. The dominant structure stratifies across premium full-service ceremonies, standard cremation-with-memorial packages, and economy direct disposition tiers. Price differentiation hinges on facility certification tier and geographic land scarcity, with urban cemetery-crematorium complexes in Japan and Singapore commanding scarcity premiums. Cost compression in economy tiers is intensifying because direct cremation brokers disintermediate traditional referral channels. Families exhibit highest price sensitivity among buyer archetypes, while pre-need planners lock rates regardless of future cost escalation.
Supply Chain Analysis
Freight logistics for casket and urn manufacturing concentrate production in China, Vietnam, and Mexico to serve North American and European distribution networks. Retort fabrication draws from specialized steel foundries in Germany, Italy, and South Korea, while mercury filtration systems source from Dutch and Swiss engineering clusters. Single-source vulnerability sits with alkaline hydrolysis resomator technology, where limited commercial-scale suppliers constrain deployment timelines. Distribution runs through funeral home wholesale procurement networks, direct-to-consumer online platforms, and cemetery-crematorium integrated retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over cemetery land reserves and downstream capture of digital memorial platforms to lock in margin pools across the disposition value chain.
For Market Incumbents: To counter digital-first cremation brokers disintermediating hospital referral relationships, legacy operators should deepen backward integration into pre-need trust fund administration and secure exclusive cemetery-crematorium land positions in metropolitan growth corridors. Channel control through hospice and senior living partnership networks remains essential for volume defense. For New Entrants and Emerging Players: EU F-Gas Regulation phasedown schedules in Germany and the Netherlands open a window for low-emission retort technology specialists to penetrate mortuary refrigeration replacement cycles. White-space targets include alkaline hydrolysis service licensing in Minnesota and Ontario, plus virtual memorial platform deployment in Australia and the United Kingdom where digital channel shift is most pronounced. A go-to-market angle anchored in environmental certification differentiation captures premium pricing from sustainability-motivated pre-need planners. For Investors and Strategic Acquirers: Distressed-cycle entries favor capitalized consolidators in the United Kingdom and Australia where regulatory scrutiny of independent pre-need plan providers compresses the fragmented provider base. Long-term viability over a five-to-ten-year window rests on trust fund adequacy infrastructure and multi-location compliance scale. The signal to watch is state-level pre-paid contract reserve requirement tightening as an inflection indicator for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-need Trust Fund Consolidation | Captures locked-in revenue streams through licensed fiduciary structures in the United Kingdom and Australia. |
| Alkaline Hydrolysis Technology Licensing | Positions operators ahead of EPA mercury compliance escalation and EU Green Deal emission trajectory. |
| Virtual Memorial Platform Integration | Recaptures margin pools previously lost to third-party streaming and digital commemoration providers. |
| Cemetery-Crematorium Complex Development | Controls land scarcity premiums in Tokyo, Singapore, and Southeast Asian metropolitan markets. |
| Funeral Home Software Modernization | Resolves data migration friction with legacy burial record archives while enabling cloud-based planning tools. |
Research Approach
Regulatory filings, cemetery and funeral service board trust fund disclosures, and EPA enforcement databases formed the secondary backbone for compliance cost modeling and facility count estimation. Primary interviews with funeral home operators, pre-need plan trust administrators, crematory equipment manufacturers, and state regulatory officials validated secondary estimates and informed technology adoption assumptions. Bottom-up facility counts by disposition technology type were triangulated against top-down service revenue estimates across the analysis window.
Historical trendline analysis of cremation rate trajectories, pre-need plan penetration curves, and emission compliance capital expenditure cycles informed the projection framework. Segmentation dimensions modeled include disposition technology, customer procurement type, product offering category, and digital infrastructure tier, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived through curve-fitting of technology substitution patterns and demographic mortality transition timing, incorporating natural gas price volatility and mercury filtration mandate implementation schedules as forecast inputs.
The model assumes a particular technology adoption path for alkaline hydrolysis; alternative pathways for water-based disposition would alter the outlook if regulatory equivalency spreads faster or slower than baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Hospital Services Market
Healthcare Services
Aged Care Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Medical Spa Market
Healthcare Services
Retail Clinics Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
China Fertility Services Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market