
 Healthcare Cold Chain Logistics Market | 2026-2036
Healthcare Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Cold Chain Logistics Market Intelligence
EU Good Distribution Practice certification is redrawing competitive boundaries for temperature-controlled pharmaceutical transport. Deutsche Post DHL Group leverages its global station network to sustain GDP-compliant lanes across multiple continents. FedEx anchors its healthcare division around specialized thermal packaging and real-time monitoring infrastructure. UPS Healthcare competes through dedicated healthcare facilities that integrate cold storage with last-mile delivery capabilities.
Healthcare cold chain logistics encompasses the end-to-end management of temperature-sensitive medical products within validated ranges, typically maintaining biologics between 2°C and 8°C and cryogenic materials below -150°C using liquid nitrogen or specialized mechanical freezers. The primary purpose is preserving molecular stability and therapeutic efficacy from manufacturing through patient administration. Vaccines and biologics represent the most structurally demanding product categories, with biologics commanding premium logistics spend due to narrow temperature tolerances and high product value. Refrigerated transportation occupies the largest technology spend pool, while temperature monitoring systems capture disproportionate investment growth as regulators mandate continuous digital records.
FDA enforcement of the Drug Supply Chain Security Act, EU GDP guidelines administered by national competent authorities, and WHO prequalification standards collectively determine market access for logistics providers serving pharmaceutical clients. These frameworks mandate validated equipment, documented temperature excursions, and auditable chain-of-custody records that disqualify general freight operators from pharmaceutical lanes. Stakeholders must evaluate whether their monitoring infrastructure can satisfy emerging requirements for real-time data transmission and automated alert protocols as regulatory expectations advance beyond passive logger documentation.
Market Dynamics
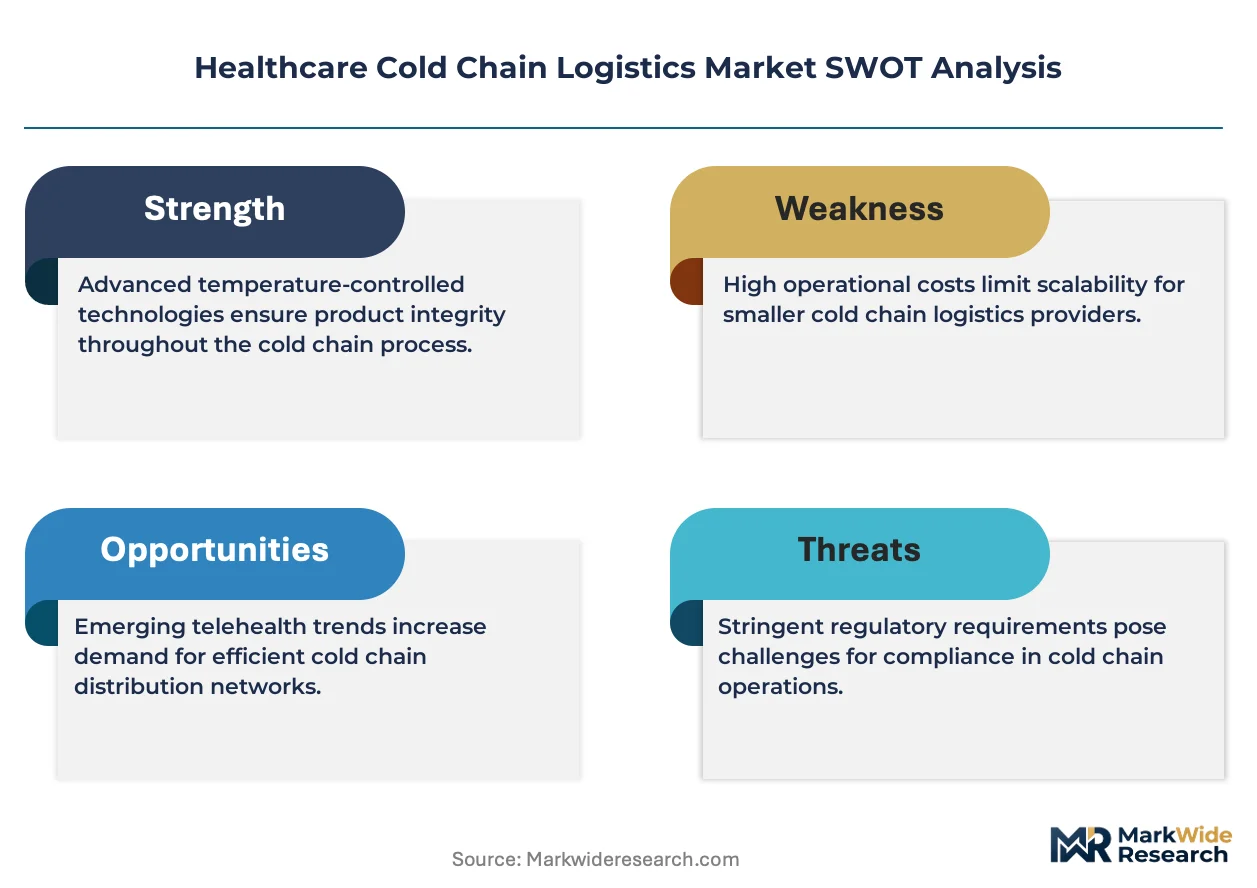
Biologics manufacturers are forcing logistics providers to revalidate entire lane networks as FDA DSCSA serialization deadlines compress qualification timelines from years to months.
Growth Catalysts
- WHO prequalification expansion:Vaccine export programs in India and Brazil now require cold chain certification that funnels demand toward qualified 3PL networks capable of documented temperature integrity.
- mRNA platform proliferation:Pharmaceutical developers are building refrigerated manufacturing footprints that multiply touchpoints requiring GDP-compliant handoffs between production and distribution.
- Cell and gene therapy commercialization:Cryogenic logistics below minus 150 degrees Celsius is pulling investment into liquid nitrogen infrastructure and specialized courier networks.
Market Restraints
- Qualified equipment scarcity:Container manufacturing capacity for validated thermal shippers concentrates among European and North American suppliers, creating eighteen-month procurement backlogs.
- Energy cost volatility:Refrigerated warehouse operators face margin compression from electricity price spikes that cannot be fully passed through under long-term pharmaceutical contracts.
- Specialized labor shortages:GDP-qualified quality assurance personnel and cold chain engineers command premium compensation that inflates fixed cost structures.
Strategic Opportunities
- Last-mile direct-to-patient:Home infusion and specialty pharmacy delivery is opening demand for patient-centric cold chain solutions with consumer-grade visibility.
- Reusable packaging systems:Sustainability mandates under EU Green Deal packaging regulations are creating first-mover advantage for circular thermal container programs.
- Real-time monitoring convergence:Integration of IoT sensors with blockchain custody records addresses DSCSA traceability requirements while reducing reconciliation costs.
Industry Challenges
- Multi-modal qualification complexity:Pharmaceutical sponsors must demonstrate temperature integrity across air, ocean, and ground segments with incompatible documentation systems.
- Legacy warehouse retrofitting:Older distribution centers require extensive mechanical and control system upgrades to meet current GDP temperature mapping standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Cold Chain Logistics Market |
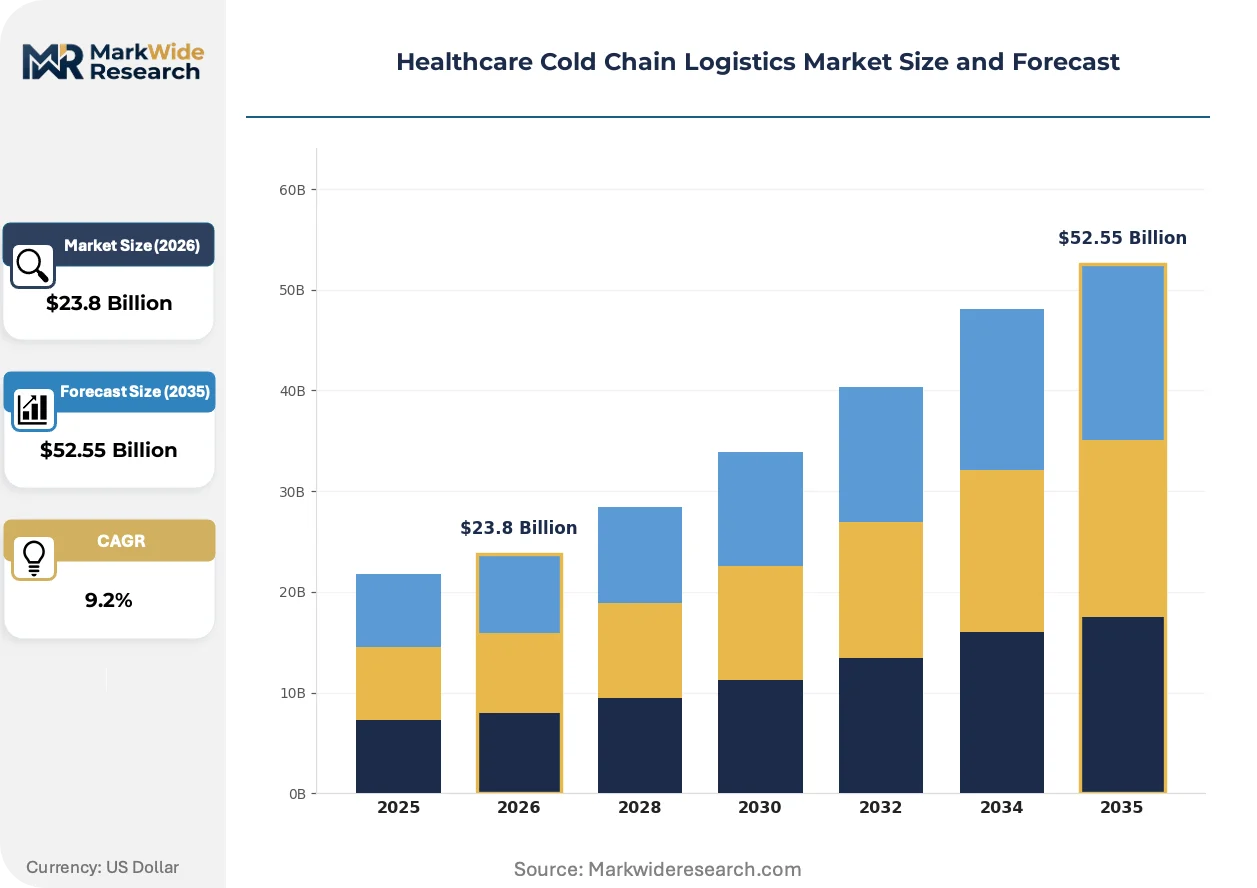
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $52.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Biologics, Pharmaceuticals, Blood Products Technology: Refrigerated Transportation, Temperature Monitoring, Packaging Solutions, Tracking Systems End User: Hospitals, Pharmacies, Research Institutions, Manufacturers Delivery Mode: Air Freight, Ground Transportation, Ocean Freight, Rail Transport |
| Companies Covered | UPS Healthcare, Kuehne+Nagel, Maersk, DB Schenker, CEVA Logistics, Deutsche Post DHL Group, AmerisourceBergen, Lineage Logistics, FedEx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Cold Chain Logistics Market Strategic Shifts & Innovations
Digitization of custody documentation and sensor miniaturization are compressing the cost structure of compliance while raising baseline performance expectations across pharmaceutical logistics.
Active thermal packaging with integrated phase-change materials is decomposing the traditional distinction between parcel and freight cold chain economics. Biologics shippers are adopting these systems for international lane validation at volumes previously reserved for bulk pharmaceutical distribution. The technology is decomposing capital barriers to entry in cryogenic transport by reducing dependence on mechanical refrigeration infrastructure.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in transport refrigeration and warehouse cooling systems. Logistics providers face equipment replacement cycles compressed from fifteen years to seven as hydrofluorocarbon bans tighten. Cold storage operators in Germany and the Netherlands are responding with ammonia-CO2 cascade systems and air-source heat pump retrofits.
Pharmaceutical procurement departments are consolidating vendor panels around integrated service providers capable of spanning clinical trial logistics through commercial distribution. Specialty courier networks and regional cold storage operators face displacement as multinational 3PLs bundle temperature-controlled warehousing with international freight forwarding. This concentration is most visible in United States oncology distribution, where integrated service contracts now cover investigational product through patient administration.
Healthcare Cold Chain Logistics Market Segmentation
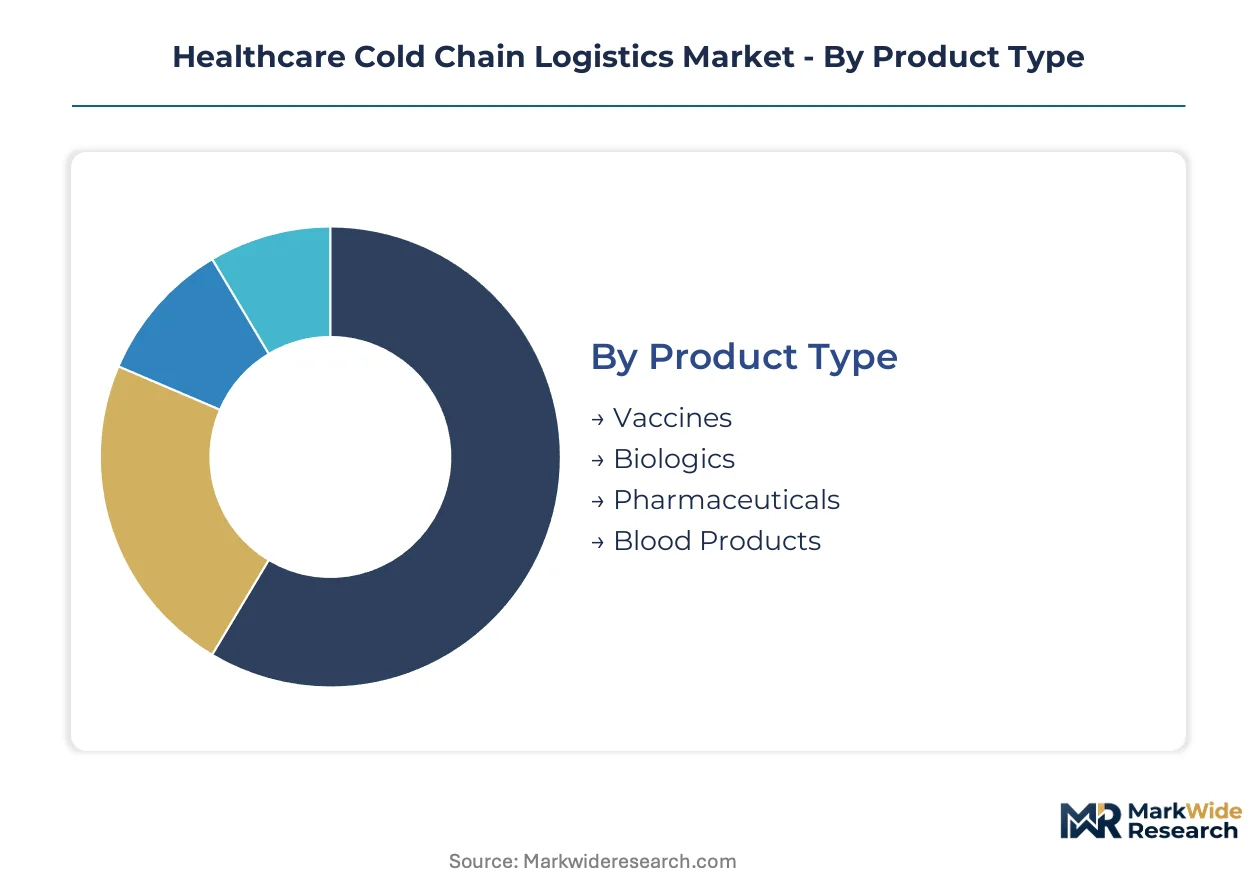
Healthcare cold chain logistics segments by product thermal tolerance, technology investment intensity, and channel infrastructure requirements. Each dimension determines qualification protocols, equipment specifications, and margin structures that separate pharmaceutical-grade providers from general freight operators.
Product Type:
Vaccines and biologics flow through GDP-validated lanes with continuous monitoring, while pharmaceuticals and blood products access broader refrigerated networks with selective qualification requirements.
- Vaccines:Ultra-cold requirements for mRNA platforms demand liquid nitrogen or specialized mechanical freezers maintaining -70°C to -80°C. UNICEF and Gavi procurement programs in India and Nigeria concentrate demand toward qualified 3PLs with WHO prequalification.
- Biologics:Monoclonal antibodies and recombinant proteins require narrow 2°C to 8°C ranges with strict excursion limits. Oncology and autoimmune therapy distribution in Germany and the United States drives premium logistics spend due to high product value and temperature sensitivity.
- Pharmaceuticals:Small-molecule drugs with moderate cold chain needs access standard refrigerated transport. Generic manufacturers in India leverage established 2°C to 8°C infrastructure for export distribution.
- Blood Products:Plasma and platelet concentrates require validated cold chain with documented chain-of-custody. Hospital blood bank networks in the United States and France maintain specialized regional distribution.
Vaccines dominate installed base by volume. Biologics is where expansion concentrates.
Technology:
Technology investment tiers separate passive compliance from predictive capability, with monitoring systems commanding disproportionate capital allocation relative to their revenue share.
- Refrigerated Transportation:Active and passive thermal containers for air, ocean, and ground modes represent the largest technology spend pool. Container manufacturing backlogs in Germany and the United States stretch to eighteen months as pharmaceutical lane validation accelerates.
- Temperature Monitoring:IoT sensors with real-time data transmission and automated alert protocols capture fastest investment growth. FDA DSCSA and EU GDP mandates for continuous digital records displace passive logger documentation.
- Packaging Solutions:Phase-change materials and vacuum-insulated panels enable lane validation at reduced capital intensity. Reusable thermal container programs under EU Green Deal packaging regulations create first-mover sustainability advantage.
- Tracking Systems:Blockchain-integrated custody records address traceability requirements while reducing reconciliation costs. Pharmaceutical sponsors in Switzerland and Singapore pilot automated chain-of-custody documentation.
Refrigerated transportation anchors current infrastructure spend. Temperature monitoring is climbing the fastest.
End User:
End-user segments diverge by procurement sophistication, with manufacturers and research institutions demanding validated qualification protocols that hospitals and pharmacies rarely replicate.
- Manufacturers:Pharmaceutical and biotech sponsors require end-to-end GDP compliance from production through patient administration. Contract logistics relationships in the United States and Germany consolidate around integrated providers spanning clinical trials to commercial distribution.
- Research Institutions:Cell and gene therapy developers need cryogenic logistics below -150°C for investigational product stability. Academic medical centers in Boston and Basel pull investment into specialized courier networks.
- Hospitals:Inpatient and outpatient facilities source cold chain through group purchasing organizations with standardized temperature requirements. Oncology infusion centers in France and Japan drive last-mile direct-to-patient demand.
- Pharmacies:Specialty and retail pharmacy chains require consumer-grade visibility for home infusion delivery. Mail-order pharmacy growth in the United States opens patient-centric cold chain solutions.
Manufacturers control qualification standards. Research institutions are gaining share fastest.
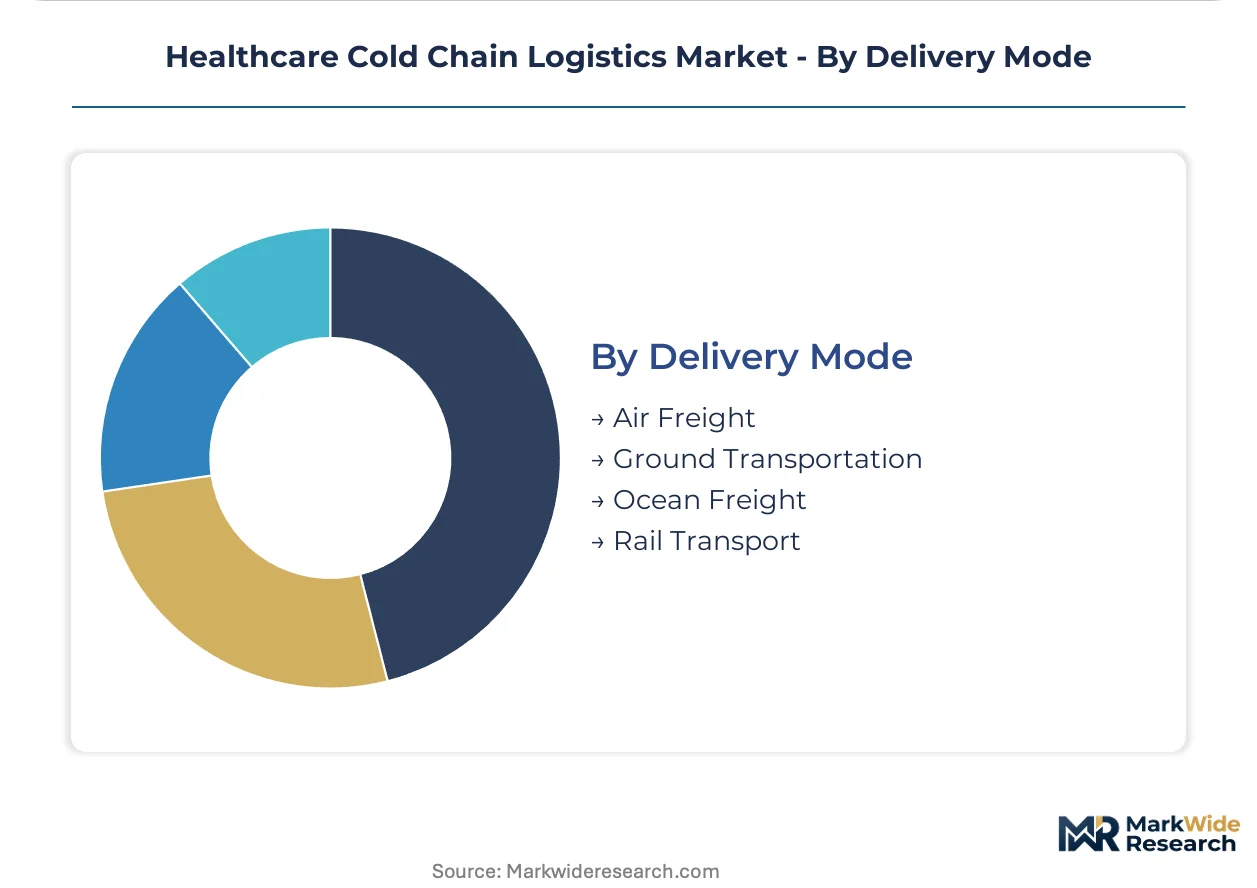
Delivery Mode:
Delivery mode selection balances speed against qualification complexity, with air freight commanding premium positioning for time-sensitive biologics and ocean freight expanding for stable temperature requirements.
- Air Freight:Pharmaceutical cargo maintains 2°C to 8°C through active container systems on international lanes. Frankfurt and Mumbai cargo hubs concentrate GDP-compliant handling infrastructure.
- Ground Transportation:Regional and last-mile distribution leverages refrigerated vehicles with real-time tracking. United States oncology distribution networks integrate dedicated healthcare facilities with cold storage.
- Ocean Freight:Reefer containers with validated thermal performance enable cost-effective bulk pharmaceutical movement. Port cold chain infrastructure in Rotterdam and Singapore supports multi-week lane qualification.
- Rail Transport:Intermodal refrigerated wagons gain traction for continental pharmaceutical distribution. European rail corridors between Belgium and Italy reduce carbon intensity against air freight.
Air freight dominates high-value biologics. Ocean freight is expanding most quickly for stable temperature requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Airport's GDP-compliant cargo terminals anchor European pharmaceutical distribution, while Mumbai's Chhatrapati Shivaji International Airport underwrites India's vaccine export surge. These infrastructure nodes concentrate qualified cold chain capacity where regulatory density and manufacturing investment intersect.
United States
Oncology biologics distribution and cell therapy commercialization drive refrigerated network expansion. FDA DSCSA serialization mandates compress qualification timelines for logistics providers. Greater Boston's biotech corridor pulls specialized courier investment for cryogenic investigational product handling.
Germany
EU F-Gas Regulation phase-down schedules accelerate refrigerant transitions in transport and warehouse cooling systems. EMA-administered GDP guidelines tighten validation requirements for cross-border pharmaceutical lanes. The Rhine-Main region around Frankfurt concentrates active container manufacturing and qualification laboratory capacity.
India
WHO prequalification expansion for vaccine export programs funnels demand toward certified 3PL networks. CDSCO alignment with international cold chain standards enables participation in UNICEF and Gavi procurement. Hyderabad's vaccine manufacturing cluster drives investment in validated thermal packaging and regional distribution infrastructure.
Switzerland
Swissmedic oversight of pharmaceutical distribution maintains stringent temperature mapping and documentation protocols. Basel's academic and commercial biologics research institutions require cryogenic logistics below minus 150 degrees Celsius. The country's alpine logistics corridors integrate rail and air freight for continental pharmaceutical movement.
Singapore
Port cold chain infrastructure supports multi-week lane qualification for ocean freight pharmaceutical distribution. The city-state's free trade agreements with ASEAN and Pacific Rim economies position it as a regional redistribution hub. Changi Airport's pharmaceutical cargo zones concentrate GDP-compliant handling equipment and real-time monitoring systems.
Healthcare Cold Chain Logistics Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The market structure tilts toward consolidation as pharmaceutical procurement departments consolidate vendor panels around integrated service providers. Three archetypes dominate: multinational 3PLs bundling warehousing with freight forwarding, specialized healthcare divisions of express carriers, and dedicated cold storage operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification timelines compress.
Within the integrated logistics tier, Deutsche Post DHL Group and FedEx exemplify archetypes combining global station networks with specialized thermal infrastructure. UPS Healthcare occupies a position representing dedicated healthcare facility investment. Kuehne+Nagel sits within the freight-forwarding-specialist segment emphasizing pharmaceutical lane validation across multiple transport modes.
| Leading Market Players |
|---|
| UPS Healthcare |
| Kuehne+Nagel |
| Maersk |
| DB Schenker |
| CEVA Logistics |
| Deutsche Post DHL Group |
| AmerisourceBergen |
| Lineage Logistics |
| FedEx |
| Others |
Cost & Logistics Intelligence
Phase-change material substitution for mechanical refrigeration is redrawing supply geography toward contract packaging manufacturers in Germany and the United States while compressing capital intensity premiums across GDP-compliant lane networks.
Pricing Analysis
Three-tier pricing structure across premium GDP-validated, standard temperature-monitored, and economy refrigerated tiers governs pharmaceutical logistics procurement. Price differentiation hinges on certification grade (EU GDP versus national competent authority standards) and volume scale (multinational sponsor contracts versus regional generic shipments). Pricing pressure stems from energy cost volatility that warehouse operators cannot fully pass through under long-term pharmaceutical agreements. Generic manufacturers in India exhibit highest price sensitivity, while cell and gene therapy sponsors in Switzerland and the United States demonstrate lowest sensitivity due to product value concentration.
Supply Chain Analysis
Germany and the United States anchor active thermal container manufacturing, with qualification laboratory capacity concentrated around Frankfurt and regional pharmaceutical clusters. Raw material dependencies include phase-change materials, vacuum-insulated panels, and IoT sensor components sourced from specialized chemical and electronics suppliers. Single-source vulnerability concentrates in validated thermal shipper production, where eighteen-month procurement backlogs create lane qualification bottlenecks. Distribution runs through integrated 3PL networks bundling warehousing with international freight forwarding, displacing fragmented regional cold storage operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical procurement consolidation around integrated service providers has shifted negotiating leverage toward buyers capable of bundling clinical trial through commercial distribution under unified vendor panels.
For Market Incumbents: Consolidate qualification capacity through dedicated healthcare facility investment in United States oncology corridors and Rhine-Main pharmaceutical clusters. Acquire specialized cryogenic courier networks serving Boston and Basel academic medical centers to preempt emerging platform competition. Lock in long-term thermal container supply agreements with German and North American manufacturers before procurement backlogs extend further. For New Entrants and Emerging Players: WHO prequalification fast-track for vaccine export lanes in India and Nigeria offers lowest barrier to qualified 3PL status. Target last-mile direct-to-patient segments where consumer-grade visibility requirements remain undefined and incumbent infrastructure overhangs. Pursue sustainability-first positioning through reusable thermal container programs aligned with EU Green Deal packaging regulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional cold storage operators lacking integrated freight forwarding capabilities. Five-to-ten year viability hinges on successful vendor panel consolidation by multinational pharmaceutical sponsors. Monitor FDA DSCSA enforcement intensity as inflection indicator for qualification timeline compression and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Fast-Track | WHO prequalification unlocks UNICEF and Gavi procurement programs in vaccine-exporting economies. |
| Cryogenic Infrastructure Buildout | Liquid nitrogen networks below minus 150 degrees Celsius capture cell therapy commercialization in Basel and Boston. |
| Reusable Packaging Program | Circular thermal container investment secures first-mover advantage under EU Green Deal packaging mandates. |
| Real-Time Monitoring Integration | IoT sensor deployment with blockchain custody records satisfies DSCSA traceability while reducing reconciliation overhead. |
| Last-Mile Direct-to-Patient | Home infusion delivery capabilities open specialty pharmacy segments with consumer-grade visibility requirements. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA DSCSA guidance documents, EU GDP regulatory frameworks, WHO prequalification standards, and pharmaceutical trade customs data. Primary interviews engaged cold chain operations directors, regulatory affairs managers at biologics manufacturers, quality assurance leads at 3PL providers, and hospital procurement officers. Secondary validation drew from EMA inspection reports, ClinicalTrials.gov logistics disclosures, and national competent authority enforcement records. Bottom-up capacity modeling triangulated against top-down pharmaceutical shipment value estimates.
Segmentation dimensions modeled include product thermal tolerance (vaccines, biologics, pharmaceuticals, blood products), technology investment intensity (refrigerated transport, temperature monitoring, packaging solutions, tracking systems), end-user procurement sophistication (manufacturers, research institutions, hospitals, pharmacies), and delivery mode qualification complexity (air, ground, ocean, rail). CAGRs derived from trend extrapolation of lane validation timelines, equipment procurement cycles, and regulatory enforcement intensity across the projection horizon. Industry-specific inputs incorporated mRNA platform proliferation rates and cell therapy commercialization pipelines.
Underlying assumptions cover sustained FDA DSCSA serialization compliance deadlines, EU F-Gas Regulation phase-down schedules, and WHO prequalification expansion trajectories, with deviation risk concentrated in qualified equipment manufacturing capacity constraints and energy cost volatility. Recalibration cycles align with material shifts in regulatory enforcement intensity, pharmaceutical sponsor vendor consolidation patterns, and cryogenic logistics infrastructure investment decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Care Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
US Care Services Market
Healthcare Services
Global Ambulatory Services Market