
 US Cord Blood Banking Services Market | 2026-2036
US Cord Blood Banking Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Cord Blood Banking Services Market Intelligence
Subscription-based long-term storage contracts is recalibrating revenue predictability across the US cord blood banking services landscape. Cord Blood Registry leverages its national hospital partnerships to sustain collection volume leadership. Cryo-Cell International anchors its competitive stance through proprietary cryopreservation protocols. Viacord differentiates via integrated family health advisory services that extend beyond raw storage.
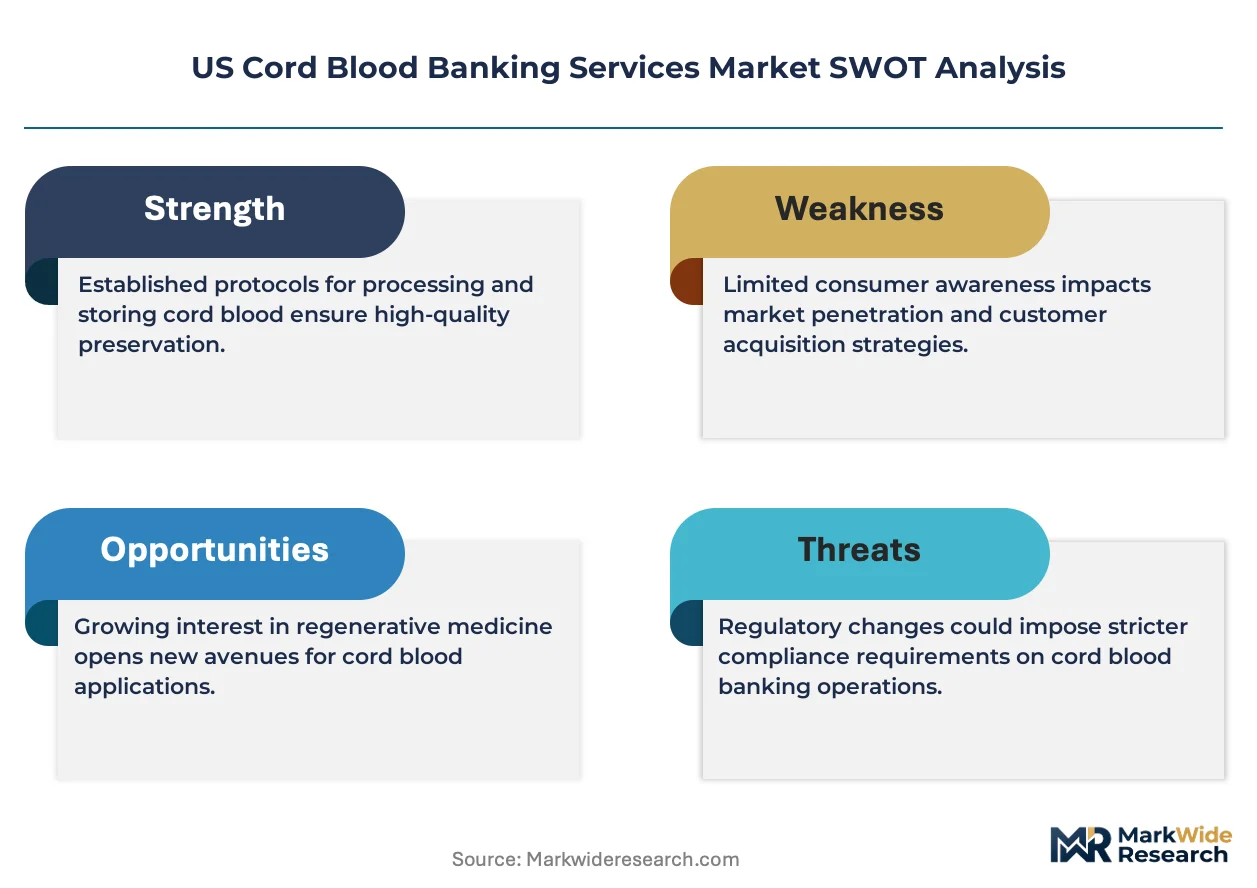
US cord blood banking services encompass the procurement, processing, cryogenic preservation, and retrieval of hematopoietic stem cells derived from umbilical cord blood and tissue, maintained at temperatures below minus 150 degrees Celsius in liquid nitrogen or vapor-phase systems. These biological assets serve therapeutic applications spanning oncology, hematology, and emerging regenerative medicine protocols. Private banking dominates current revenue pools due to upfront collection fees and recurring annual storage charges, while public banking operates on donated inventory models with narrower margin profiles. Hybrid banking arrangements represent the fastest-expanding structural segment as families seek dual-access frameworks combining private security with public donation pathways.
FDA regulates cord blood as human cells, tissues, and cellular tissue-based products under 21 CFR Part 1271, mandating donor screening, Good Tissue Practice compliance, and adverse event reporting that elevates operational costs for market participants. AABB accreditation and state-level health department licensure in jurisdictions such as California and New York impose additional facility and process standards that shape regional market access. Stakeholders must monitor evolving CMS reimbursement determinations for cord blood-derived therapies and anticipate how clinical trial outcomes in graft-versus-host disease applications will redirect family education investments and hospital partnership priorities.
Market Dynamics
Subscription-based long-term storage contracts is recalibrating revenue predictability across the US cord blood banking services landscape, shifting operators toward recurring revenue models that reduce acquisition cost volatility and extend customer lifetime value horizons.
Growth Catalysts
- FDA 21 CFR Part 1271:The FDA's human cells and tissues framework mandates donor screening and Good Tissue Practice compliance, elevating quality benchmarks that differentiate accredited operators from marginal competitors and justify premium pricing tiers.
- Expectant families:This end-use segment is broadening awareness of hematopoietic stem cell therapies through obstetrician education programs and direct-to-family digital outreach, converting prenatal care touchpoints into collection decisions.
- Hybrid banking arrangements:Dual-access frameworks combining private security with public donation pathways are accelerating as families seek flexibility without sacrificing therapeutic access, expanding addressable market scope beyond traditional binary choices.
Market Restraints
- Liquid nitrogen supply concentration:Cryogenic preservation depends on regional industrial gas infrastructure concentrated in Gulf Coast petrochemical corridors, exposing operators to input cost volatility and supply disruption risks during extreme weather events.
- AABB accreditation timelines:Facility certification processes impose 12-18 month compliance windows that delay market entry for new processing centers, entrenching incumbent advantages in metropolitan hospital corridors.
- Allogeneic stem cell alternatives:Bone marrow registries and peripheral blood stem cell donation programs offer established graft sources with lower collection complexity, constraining cord blood's addressable therapeutic applications to specific hematologic malignancies.
Strategic Opportunities
- Texas perinatal corridors:Houston and Dallas-Fort Worth birthing volumes exceed current accredited collection capacity, creating white space for hospital partnership expansion and regional processing hub development.
- Regenerative medicine protocols:Clinical trials in cerebral palsy and autism spectrum applications are expanding cord blood's therapeutic addressability beyond oncology, positioning operators to capture emerging indication demand.
- Integrated family health advisory services:Service bundling that extends beyond raw storage into genetic counseling and family health planning is creating differentiation vectors that command pricing premiums and reduce churn.
Industry Challenges
- Cryopreservation specialist recruitment:Qualified laboratory personnel with cell therapy processing expertise command compensation premiums that compress operating margins, particularly in secondary metropolitan markets competing with biopharma manufacturing hubs.
- Legacy inventory system integration:Sample tracking and chain-of-custody documentation requirements strain outdated laboratory information management systems, forcing capital-intensive upgrades to maintain FDA audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cord Blood Banking Services Market |
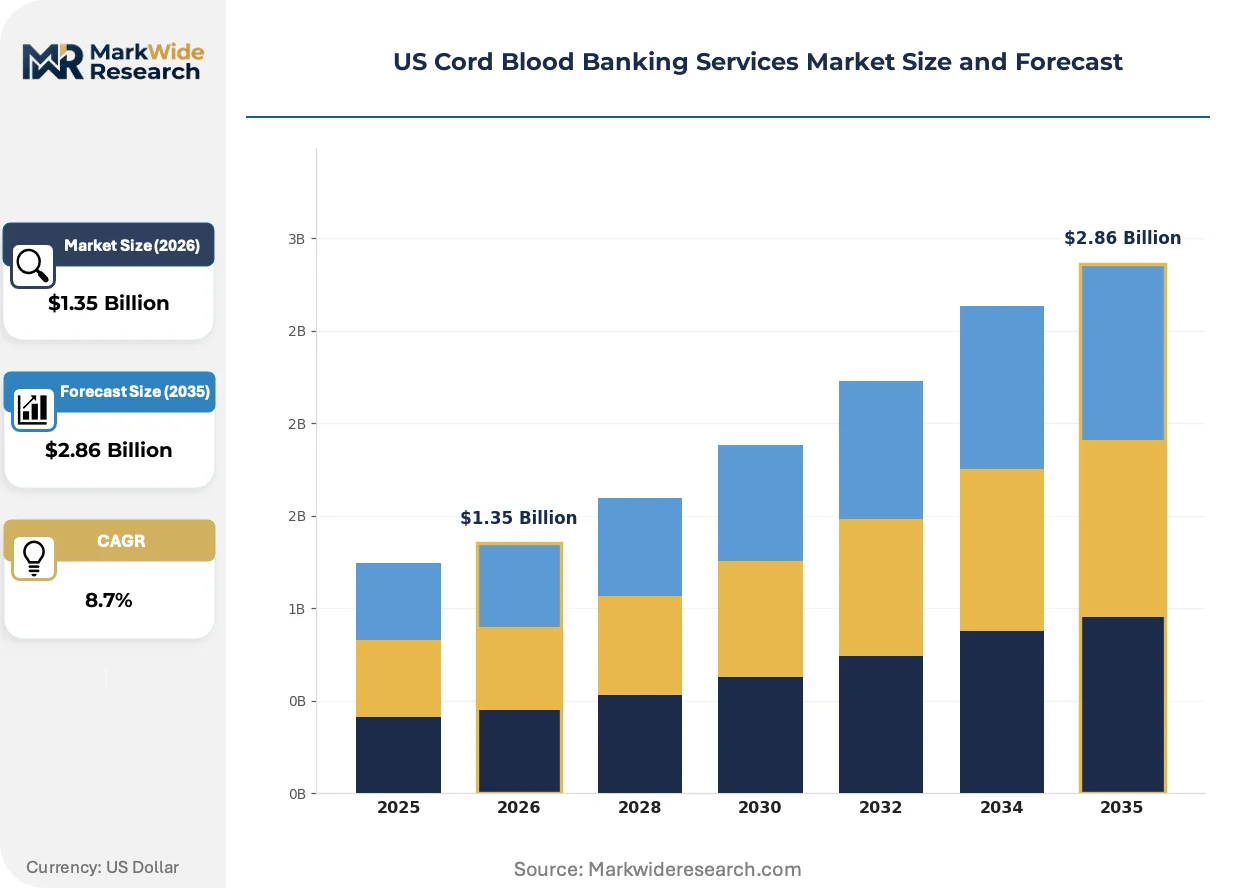
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Private Banking, Public Banking, Hybrid Banking, Storage Services End User: Hospitals, Clinics, Research Institutions, Families Processing Technology: Hematopoietic Stem Cell Processing, Cellular Storage, Cryopreservation, Analysis Technologies Collection Method: In-Hospital Collection, Home Collection Kit, Manual Collection, Automated Collection |
| Companies Covered | Cord Blood Registry, Cryo-Cell International, Viacord, California Cryobank, StemCyte, Americord Registry, MiracleCord, Lifeforce Cryobank Sciences, New Jersey Cord Blood Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cord Blood Banking Services Market Strategic Shifts & Innovations
Automation is penetrating processing workflows while regulatory disclosure requirements intensify, compressing operational timelines and forcing capital reallocation toward compliance infrastructure and quality assurance capabilities.
Vapor-phase cryogenic storage systems is consolidating market preference over liquid nitrogen immersion methods. These systems reduce cross-contamination risks and improve temperature stability during retrieval events. Private banking operators are adopting vapor-phase infrastructure at accelerated replacement cycles. The technology is consolidating competitive positioning around facilities with redundant cryogenic architectures that satisfy evolving AABB facility standards.
CMS reimbursement determinations for cord blood-derived therapies are tightening documentation requirements for graft-versus-host disease applications. The industrial consequence is elevated pre-collection counseling investment to ensure families understand therapeutic utilization pathways and insurance coverage limitations. California and New York state health departments are responding with enhanced licensure conditions that mandate transparent outcome reporting, affecting hybrid banking operators most directly.
Hospital partnership exclusivity arrangements are compressing collection network access for independent operators. Metropolitan birthing centers are consolidating referral relationships with vertically integrated banking services that offer on-site collection logistics and electronic medical record integration. This channel concentration is most visible in California's Los Angeles and San Francisco corridors, where perinatal care system consolidation has reduced independent collection site availability by half over recent contract renewal cycles.
US Cord Blood Banking Services Market Segmentation
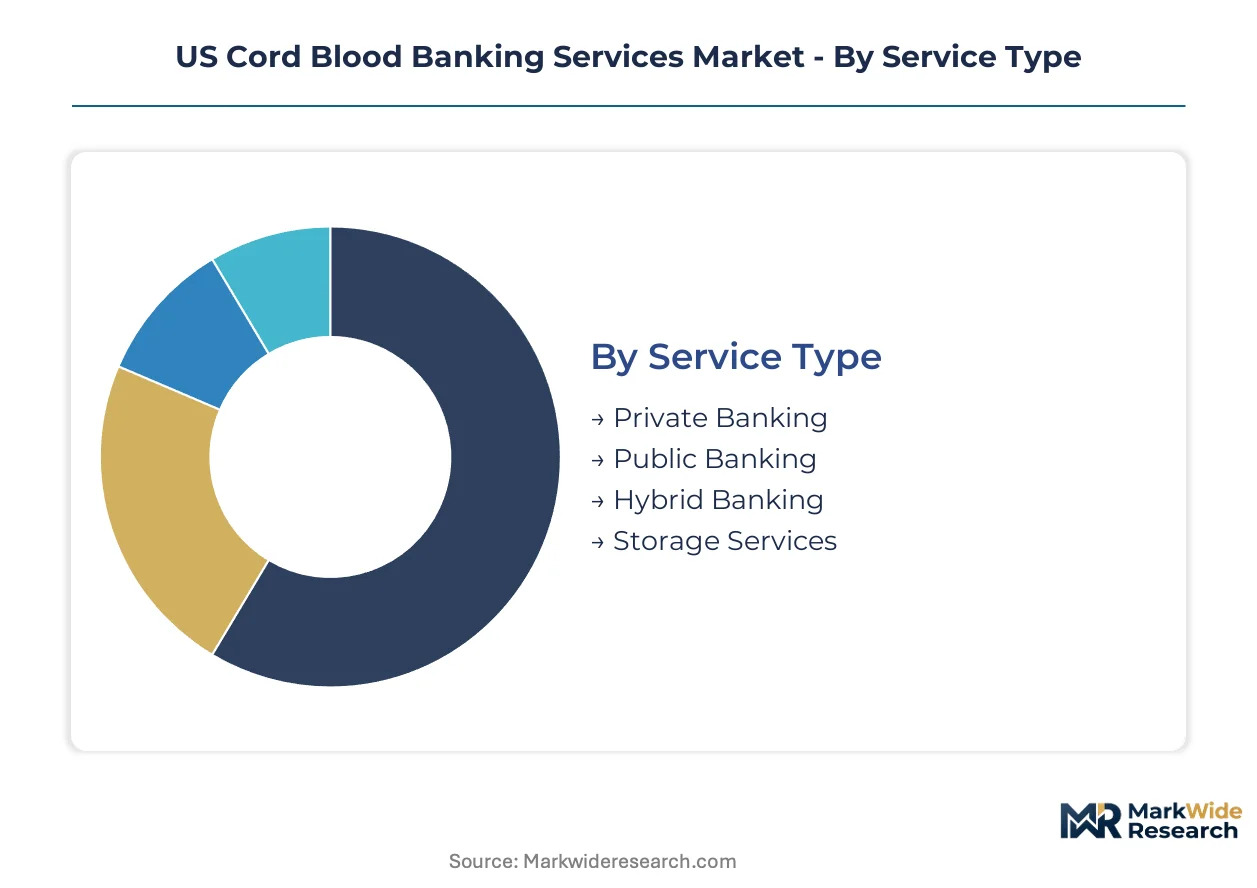
Segmentation in US cord blood banking services reveals how FDA 21 CFR Part 1271 compliance burdens and AABB accreditation requirements concentrate across operational models. Each category exposes distinct margin structures, collection logistics, and customer acquisition economics that shape competitive positioning.
Service Type:
Private banking demands full FDA donor screening compliance plus AABB facility accreditation, while public banking operates under narrower tissue donor eligibility standards with reduced recurring revenue capture.
- Private Banking:Families pay upfront collection fees plus annual storage charges for exclusive autologous access. California, Texas, and New York metropolitan hospital corridors concentrate demand where perinatal care infrastructure and disposable income align.
- Public Banking:Donated inventory models serve allogeneic transplant candidates through federally qualified cord blood banks. Narrower margin profiles depend on National Marrow Donor Program contracts and CMS reimbursement pathways for hematologic malignancy treatments.
- Hybrid Banking:Dual-access frameworks combine private security with public donation pathways. Families retain therapeutic priority while contributing to searchable donor registries.
- Storage Services:Third-party cryogenic infrastructure providers lease vapor-phase liquid nitrogen capacity to banks lacking redundant facility architectures.
Leading the category by volume: Private Banking. Growing fastest: Hybrid Banking.
End User:
Collection site economics vary sharply by end-user type, with hospital-based procurement absorbing logistics costs that home collection kits shift to families.
- Families:Direct-to-consumer decision makers convert obstetrician recommendations into collection contracts. Digital education campaigns and prenatal care touchpoints drive conversion in high-birth-volume metropolitan statistical areas.
- Hospitals:Birthing centers with Level III neonatal intensive care units anchor collection volume through on-site logistics and electronic medical record integration. Exclusivity arrangements with vertically integrated banks compress independent operator access.
- Clinics:Outpatient perinatal practices extend collection reach into suburban corridors lacking full-service hospital obstetrics departments.
- Research Institutions:Academic medical centers access banked units for graft-versus-host disease and regenerative medicine protocol development under institutional review board oversight.
Dominant by collection volume: Hospitals. Steepest expansion trajectory: Families.
Processing Technology:
Technology selection determines FDA audit readiness and AABB compliance cost structures, with automated platforms reducing labor intensity but demanding capital replacement cycles.
- Cryopreservation:Vapor-phase liquid nitrogen systems below minus 150 degrees Celsius consolidate market preference over immersion methods. Temperature stability during retrieval events and cross-contamination risk reduction justify infrastructure replacement investments.
- Hematopoietic Stem Cell Processing:Density gradient separation and automated cell washing concentrate viable CD34+ populations for therapeutic application. Qualified laboratory personnel scarcity compresses operating margins in secondary metropolitan markets.
- Cellular Storage:Chain-of-custody documentation and sample tracking requirements strain legacy laboratory information management systems.
- Analysis Technologies:Flow cytometry and viability assays verify unit quality for transplant suitability reporting.
Widest installed base: Cryopreservation. Accelerating replacement demand: Hematopoietic Stem Cell Processing.
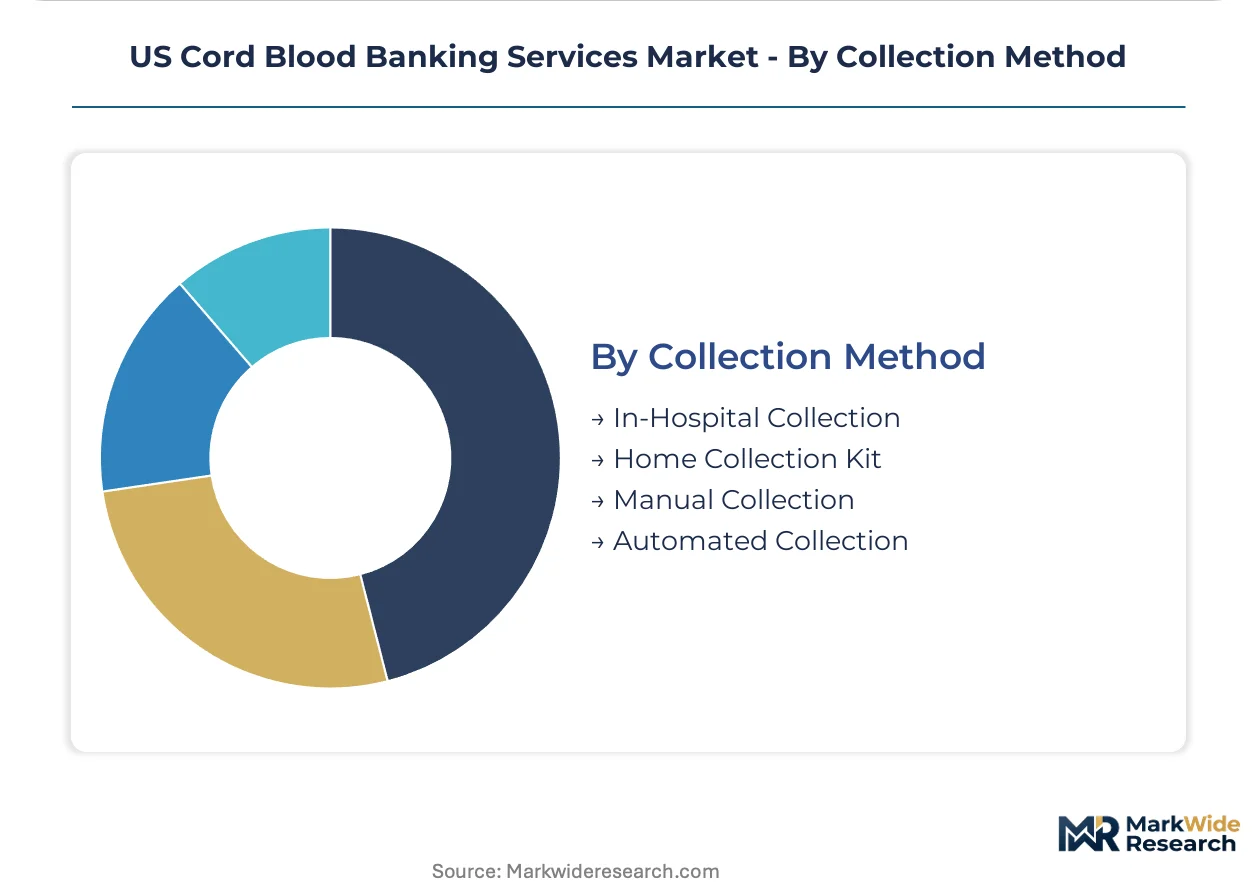
Collection Method:
Method selection shapes contamination risk profiles and courier logistics costs, with automated systems reducing variability but requiring hospital capital commitment.
- In-Hospital Collection:Trained obstetric staff perform procurement during delivery with immediate cold-chain handoff to processing facilities. Los Angeles and San Francisco corridor consolidation has reduced independent collection site availability through exclusivity renewals.
- Home Collection Kit:Families receive sterile collection vessels and temperature-controlled shipping containers for midwife-assisted or self-managed procurement. Courier logistics extend processing windows and elevate contamination risks.
- Manual Collection:Standard syringe-based techniques persist in resource-constrained settings without automated platform investment.
- Automated Collection:Closed-system devices reduce open-field contamination during umbilical cord cannulation.
Highest volume throughput: In-Hospital Collection. Gaining share fastest: Home Collection Kit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collection infrastructure concentrates in high-birth-volume metropolitan corridors, while processing capacity distributes across regional cryogenic hubs. Demand patterns track perinatal care consolidation and state-level health department licensure requirements.
California
Los Angeles and San Francisco perinatal corridors generate concentrated collection volume through hospital exclusivity arrangements. State health department licensure mandates transparent outcome reporting for hybrid banking operators. San Diego and Sacramento birthing centers anchor regional processing demand, with Level III NICU facilities driving on-site collection logistics.
Texas
Houston and Dallas-Fort Worth metropolitan statistical areas exceed current accredited collection capacity, creating expansion white space. FDA 21 CFR Part 1271 compliance elevates operational costs for new market entrants. Austin and San Antonio hospital systems consolidate referral relationships with vertically integrated banking services.
New York
New York City metropolitan birthing volumes align with disposable income concentrations supporting private banking adoption. State health department licensure imposes facility and process standards shaping regional market access. Long Island and Westchester County perinatal practices extend collection reach through outpatient clinic networks.
Florida
Miami and Tampa perinatal corridors attract snowbird and immigrant family demographics with elevated private banking interest. CMS reimbursement determinations for cord blood-derived therapies influence family education investments. Orlando hospital systems compete for collection network access through electronic medical record integration offerings.
Illinois
Chicago metropolitan birthing centers anchor Midwest collection volume through academic medical center partnerships. AABB accreditation timelines delay market entry for independent processing facilities. Northwestern and University of Chicago health systems access banked units for graft-versus-host disease protocol development.
US Cord Blood Banking Services Market Key Industry Players
Top-tier vendors anchor national hospital partnership networks, while regional specialists compete on collection site access and proprietary processing protocols. Three structural archetypes dominate: vertically integrated operators with captive laboratory infrastructure, specialized cryogenic storage providers leasing third-party capacity, and hybrid banking platforms combining private security with public donation pathways. Competitive moves concentrate on hospital exclusivity renewals and vapor-phase cryogenic infrastructure replacement cycles.
Within the national-scale tier, Cord Blood Registry, Cryo-Cell International, and Viacord occupy positions representing distinct strategic orientations. Cord Blood Registry exemplifies volume-driven collection network breadth. Cryo-Cell International anchors proprietary cryopreservation protocol differentiation. Viacord represents integrated family health advisory service extension beyond raw storage commoditization. These three operators collectively illustrate how competitive positioning fragments across collection logistics, processing technology, and customer relationship depth rather than consolidating around uniform scale advantages.
| Leading Market Players |
|---|
| Cord Blood Registry |
| Cryo-Cell International |
| Viacord |
| California Cryobank |
| StemCyte |
| Americord Registry |
| MiracleCord |
| Lifeforce Cryobank Sciences |
| New Jersey Cord Blood Bank |
| Others |
Cost & Logistics Intelligence
Cryopreservation specialist concentration in Boston and San Francisco biotech corridors widens pricing-tier spreads, as qualified laboratory personnel command compensation premiums that operators pass through to private banking subscribers while public banking margins compress.
Pricing Analysis
Margin tightening in public banking reflects CMS reimbursement stagnation against rising FDA compliance costs. Three-tier pricing structure across premium AABB-accredited facilities, standard hospital-partnered operators, and economy direct-to-consumer kits separates families by certification sensitivity. Cost-down pressure on economy tiers accelerates because home collection kit providers absorb courier logistics without hospital infrastructure subsidies. Research institutions exhibit least price sensitivity given institutional review board funding, while uninsured families drive economy-tier volume.
Supply Chain Analysis
Liquid nitrogen supply rests on Gulf Coast petrochemical infrastructure concentrated in Texas, Louisiana, and Oklahoma. Vapor-phase cryogenic storage systems draw from specialty stainless steel fabrication in Germany and industrial gas purification in the United States. Single-source vulnerability emerges from regional weather disruption exposure. Distribution runs through hospital-based cold-chain logistics with third-party courier extension for home collection segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vapor-phase cryogenic systems are displacing liquid nitrogen immersion methods, forcing capital reallocation toward redundant temperature-stability infrastructure.
For Market Incumbents: Lock in hospital exclusivity renewals in Houston and Dallas-Fort Worth corridors before AABB accreditation timelines entrench competitor positions. Extend proprietary cryopreservation protocols into regenerative medicine clinical trial partnerships to defend against allogeneic stem cell registry substitution. Prioritize FDA 21 CFR Part 1271 audit readiness investments as quality differentiation lever. For New Entrants and Emerging Players: Begin with hybrid banking arrangements in Texas perinatal corridors where accredited collection capacity lags birthing volumes. Target outpatient clinic networks in Austin and San Antonio as underpenetrated channel with lower exclusivity concentration. Deploy integrated family health advisory services as differentiation wedge against commoditized storage competitors. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated operators possessing captive laboratory infrastructure given CMS reimbursement determination catalysts. Five-to-ten year viability favors those with redundant cryogenic architectures and hospital partnership density. Watch graft-versus-host disease clinical trial outcomes as inflection signal for family education investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Vapor-Phase Infrastructure Replacement | Redundant cryogenic architectures satisfy evolving AABB facility standards and reduce cross-contamination liability. |
| Hospital Partnership Expansion | Electronic medical record integration secures collection volume in Los Angeles and San Francisco corridor consolidation. |
| Regenerative Medicine Clinical Trial Access | Cerebral palsy and autism spectrum applications expand cord blood therapeutic addressability beyond oncology indications. |
| Hybrid Banking Platform Development | Dual-access frameworks capture families seeking private security without sacrificing public donation pathway flexibility. |
| Integrated Family Health Advisory Services | Genetic counseling bundling commands pricing premiums and reduces subscriber churn in competitive metropolitan markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cord blood bank laboratory directors, hospital perinatal service administrators, and FDA regulatory affairs specialists combined with AABB accreditation databases and CMS reimbursement determination records. Bottom-up collection volume modeling triangulated against top-down market size estimates from National Marrow Donor Program contract disclosures.
Granularity-level modeling operated at service type, end user, processing technology, and collection method dimensions across the analysis window. CAGRs derived from segment-level growth trajectory analysis incorporating birth volume projections, accreditation expansion timelines, and clinical trial enrollment curves. Forecast inputs included liquid nitrogen supply cost indices and AABB facility standard revision schedules.
Underlying measurement precision varies by segment; private banking carries tighter precision than public banking given disclosed subscription contract values. Forecasts reflect assumptions regarding CMS reimbursement stability and FDA enforcement intensity. Regulatory standard revision, extreme weather supply disruption, and allogeneic stem cell therapy advancement warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
Hospice Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Hospital Workforce Management Market