
 Uro Gynaecological Surgical Devices Market | 2026-2036
Uro Gynaecological Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Uro Gynaecological Surgical Devices Market Intelligence
Buyer concentration among ambulatory surgical centers is expanding as outpatient migration accelerates across developed healthcare systems. Medtronic leverages its integrated surgical ecosystem to anchor high-volume supply agreements with consolidated purchasing networks. Boston Scientific competes through specialized pelvic floor repair portfolios that target ambulatory settings. Johnson & Johnson sustains R&D intensity in robotic-compatible instrumentation, extending its reach into minimally invasive urogynaecology.
Uro gynaecological surgical devices encompass retractors, forceps, sutures, and electrosurgical units engineered for pelvic floor repair, incontinence correction, and hysterectomy procedures, typically manufactured from medical-grade stainless steel, polymer composites, or absorbable matrices with tolerances meeting ISO 13485 quality protocols. Their primary purpose is to enable precise tissue manipulation and hemostasis during pelvic reconstructive surgery. Robotic-assisted technology leads capital expenditure allocation among health systems, while laparoscopic platforms occupy the largest installed base and generate recurring instrument revenue. Electrosurgical units concentrate margin pools through disposable blade attachments and energy-delivery patents.
FDA 510(k) pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers seeking dual-territory approval. ISO 10993 biocompatibility testing and ASTM material standards further constrain material selection and supplier qualification processes. Stakeholders must monitor reimbursement parity between robotic and laparoscopic procedural codes, as payer alignment will determine capital deployment speed across hospital networks.
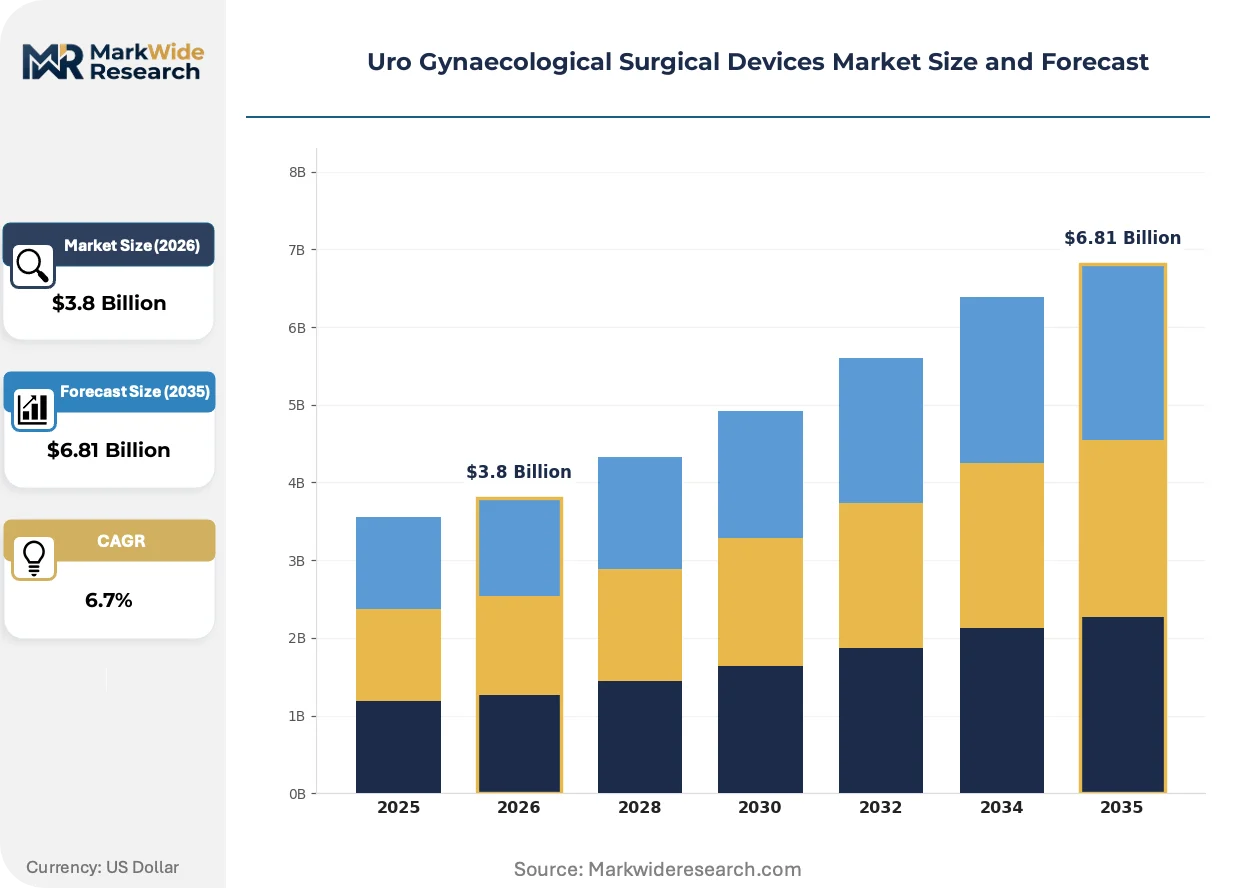
Market Dynamics
Robotic-assisted surgical platforms are compressing development cycles across the urogynaecological device sector, forcing manufacturers to reconfigure R&D pipelines around FDA 510(k) and EU MDR dual-approval timelines while ambulatory surgical centers consolidate purchasing power.
Growth Catalysts
- Outpatient Migration:Ambulatory surgical centers in the United States, Germany, and Japan are expanding minimally invasive procedure volumes, driving kit procurement for pelvic floor repair.
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification processes for predicate-based submissions are accelerating market entry for electrosurgical and laparoscopic instrumentation.
- Polymer Composite Advancement:Absorbable matrix materials meeting ISO 10993 biocompatibility standards are enabling next-generation suture and mesh platforms with reduced postoperative complications.
Market Restraints
- EU MDR Technical Documentation Burden:Expanded clinical evidence requirements for Class IIb and III devices are extending approval timelines and inflating regulatory compliance costs for manufacturers seeking CE marking.
- Medical-Grade Stainless Steel Supply Concentration:Specialized alloy sourcing remains concentrated among a limited supplier base in Germany and Japan, creating input cost volatility and qualification bottlenecks.
- Reimbursement Parity Gaps:Divergent procedural coding between robotic-assisted and laparoscopic hysterectomy platforms is constraining capital deployment speed across hospital networks.
Strategic Opportunities
- Metropolitan Hospital Network Consolidation:Integrated delivery networks in the United States are centralizing high-volume urogynaecological surgery, creating captive demand for single-source robotic instrumentation contracts.
- Disposable Electrosurgical Attachment Expansion:Patent-protected energy-delivery systems with recurring blade revenue models are capturing margin pools previously allocated to reusable instrument maintenance.
- ISO 13485-Certified Contract Manufacturing:Outsourced production partnerships in Ireland and Switzerland are enabling mid-tier device firms to access quality-compliant manufacturing without captive facility investment.
Industry Challenges
- Robotic Surgery Specialist Training Pipeline:Fellowship programs in minimally invasive urogynaecology are producing insufficient operator volumes to match installed platform expansion.
- Dual-Territory Certification Synchronization:Manufacturers face misaligned FDA and EU MDR audit schedules, forcing parallel documentation streams and redundant quality management system maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uro Gynaecological Surgical Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractors, Forceps, Sutures, Electrosurgical Units Technology: Laparoscopic, Robotic-Assisted, Open Surgery, Endoscopic End User: Hospitals, Clinics, Surgical Centers, Research Institutions Application: Pelvic Prolapse, Incontinence, Hysterectomy, Uterine Fibroids |
| Companies Covered | Medtronic, Boston Scientific, Coloplast, Johnson & Johnson, Intuitive Surgical, CooperSurgical, Hologic, Becton Dickinson, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uro Gynaecological Surgical Devices Market Strategic Shifts & Innovations
Energy-delivery platforms and robotic instrumentation architectures are converging to redefine procedural economics, while regulatory frameworks on both sides of the Atlantic compress product lifecycles and reshape competitive entry barriers.
Single-use electrosurgical units with integrated vessel-sealing algorithms are consolidating market share across high-volume hysterectomy and pelvic floor reconstruction procedures. Academic medical centers in the United States are standardizing procurement around platforms with disposable blade attachments and proprietary energy patents. This consolidation is compressing margins for reusable instrument manufacturers and locking in recurring revenue streams for integrated surgical ecosystem providers.
EU MDR technical documentation requirements are reshaping clinical evidence obligations for absorbable mesh and biologic implant categories. Manufacturers must now submit expanded biocompatibility testing under ISO 10993 and post-market surveillance protocols that exceed prior Medical Device Directive standards. Pelvic floor repair portfolios face the steepest compliance burden, with notified body capacity constraints in Germany and the Netherlands extending review timelines.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment agreements, forcing device manufacturers to compete on discrete maintenance and training pricing. Metropolitan health systems in the United States are consolidating vendor panels and demanding outcome-based performance guarantees for robotic platform utilization rates. This behavioral shift is most pronounced in North American integrated delivery networks, where purchasing power concentration enables aggressive service unbundling.
Uro Gynaecological Surgical Devices Market Segmentation
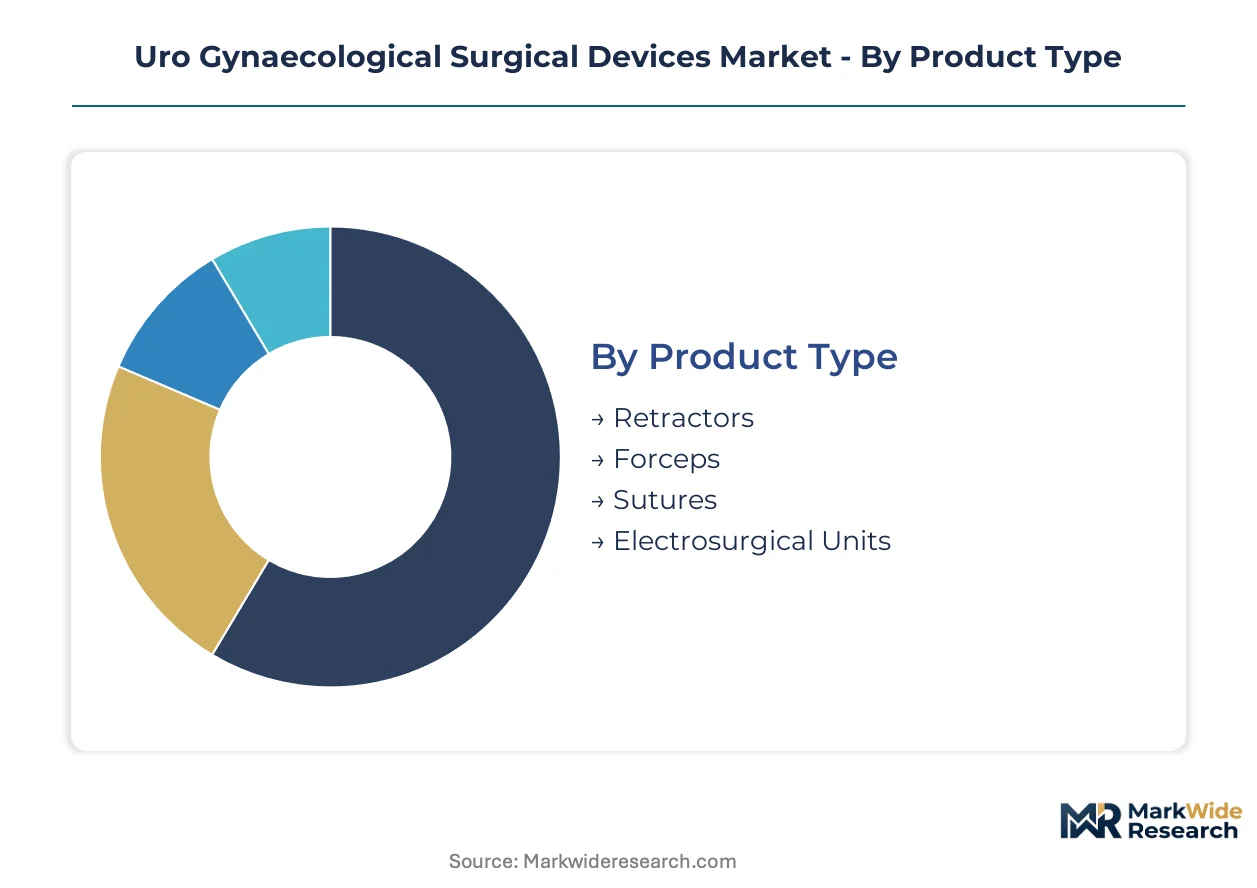
Segmentation in uro gynaecological surgical devices reveals how regulatory pathways, technology platforms, and care delivery settings fragment procurement patterns. Manufacturers must align product portfolios with distinct certification burdens and reimbursement frameworks across each dimension.
Product Type:
ISO 13485 quality protocols and FDA 510(k) predicate requirements apply unevenly across this category, with absorbable matrices demanding expanded biocompatibility testing under ISO 10993 while reusable instrumentation faces lighter documentation loads.
- Retractors:Medical-grade stainless steel and polymer composite designs enable tissue exposure during pelvic floor reconstruction. Demand concentrates in ambulatory surgical centers across Germany and Japan, where minimally invasive kit standardization is accelerating procurement consolidation for disposable retractor platforms.
- Electrosurgical Units:Energy-delivery systems with proprietary vessel-sealing algorithms command premium positioning through disposable blade attachments. United States metropolitan hospital networks are centralizing procurement around integrated surgical ecosystems that lock in recurring consumable revenue.
- Forceps:Tissue grasping instruments manufactured to ASTM material standards for laparoscopic and open procedures.
- Sutures:Absorbable matrices requiring ISO 10993 biocompatibility validation and EU MDR clinical evidence for mesh-based pelvic repair applications.
Leading the category by volume: Sutures. Growing fastest: Electrosurgical Units.
Technology:
Capital intensity and training infrastructure requirements create stark tiering across technology platforms, with robotic systems demanding dedicated fellowship pipelines while laparoscopic platforms leverage existing surgeon skill bases.
- Robotic-Assisted:Computer-assisted platforms with articulated instrumentation enabling precise pelvic dissection through small incisions. North American integrated delivery networks are consolidating vendor panels around single-source contracts that bundle capital equipment with disposable instrument streams.
- Laparoscopic:Camera-guided minimally invasive systems with the largest installed base and established reimbursement codes. Clinics and surgical centers in Japan are expanding procedural volumes as training program output stabilizes.
- Open Surgery:Conventional incision-based approaches retaining indication for complex pelvic reconstruction cases.
- Endoscopic:Transvaginal and transurethral visualization systems for diagnostic and interventional urogynaecology.
Dominating installed base: Laparoscopic. Steepest expansion trajectory: Robotic-Assisted.
End User:
Purchasing power concentration varies sharply across settings, with consolidated hospital networks extracting outcome-based guarantees while fragmented clinic environments sustain multi-vendor sourcing.
- Hospitals:Academic medical centers and metropolitan networks performing high-volume hysterectomy and pelvic floor reconstruction. United States health systems are unbundling after-sales service contracts from capital agreements, forcing discrete pricing for maintenance and training.
- Surgical Centers:Ambulatory facilities specializing in same-day minimally invasive procedures. Germany and Japan are expanding kit procurement for incontinence correction as outpatient migration accelerates across developed healthcare systems.
- Clinics:Office-based and community settings handling diagnostic and minor interventional urogynaecology.
- Research Institutions:Academic centers conducting clinical trials and technology validation studies under FDA and EU MDR protocols.
Capturing highest procedure volume: Hospitals. Gaining share fastest: Surgical Centers.
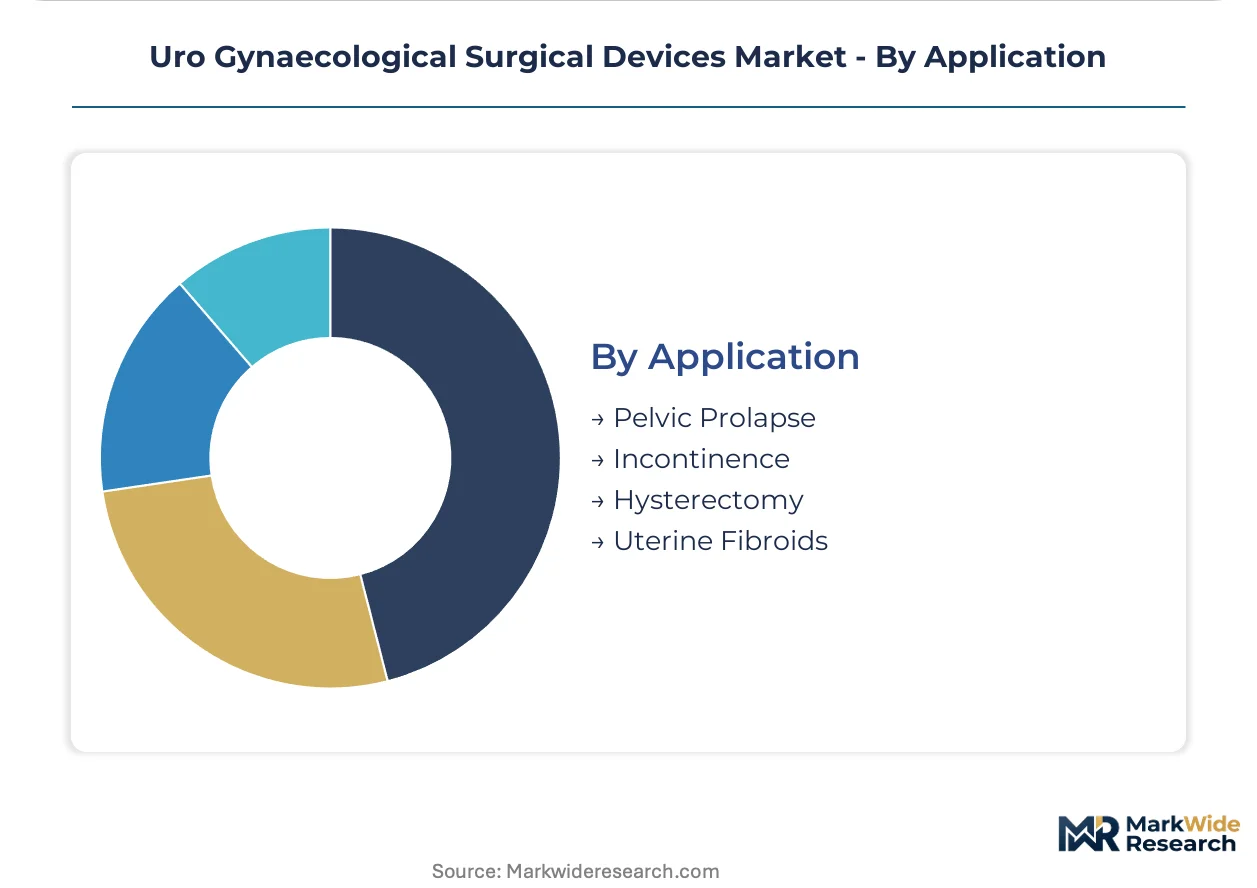
Application:
Clinical indication drives material selection and regulatory classification, with mesh-based pelvic repair facing heightened EU MDR scrutiny while hysterectomy platforms benefit from established predicate pathways.
- Hysterectomy:Uterine removal procedures spanning benign and oncological indications, served by robotic, laparoscopic, and open platforms. United States reimbursement parity debates between robotic and laparoscopic procedural codes are constraining capital deployment speed across hospital networks.
- Pelvic Prolapse:Pelvic floor reconstruction utilizing native tissue or synthetic mesh repair. EU MDR technical documentation requirements are extending approval timelines for absorbable matrix portfolios in Germany and the Netherlands.
- Incontinence:Stress urinary incontinence correction through sling procedures and injectable therapies.
- Uterine Fibroids:Myomectomy and related interventions preserving uterine function.
Generating largest procedure volume: Hysterectomy. Expanding most quickly: Pelvic Prolapse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical-grade stainless steel suppliers anchor raw material sourcing for precision surgical instrumentation, while finished device manufacturing concentrates in metropolitan hospital networks across the United States, Japan, and Western Europe.
United States
Metropolitan integrated delivery networks in Chicago, Houston, and Los Angeles are consolidating vendor panels for robotic-assisted hysterectomy platforms. FDA 510(k) pathway efficiency accelerates predicate-based submissions for electrosurgical units. Academic medical centers in the Northeast Corridor are unbundling after-sales service contracts from capital equipment agreements.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia are expanding minimally invasive kit procurement for pelvic floor repair. EU MDR technical documentation requirements extend approval timelines for absorbable mesh portfolios. Notified body capacity constraints in Berlin-Brandenburg and the Netherlands create qualification bottlenecks for Class IIb devices.
Japan
Clinics and surgical centers in the Kanto region surrounding Tokyo are stabilizing laparoscopic procedural volumes as training program output increases. PMDA consultation procedures shape biocompatibility testing protocols for polymer composite sutures. Medical-grade alloy sourcing from domestic suppliers in Osaka-Kobe manufacturing clusters faces input cost volatility.
United Kingdom
NHS procurement frameworks in London and the Southeast are centralizing purchasing for disposable electrosurgical attachments. MHRA post-Brexit regulatory alignment with EU MDR standards extends conformity assessment timelines. Research institutions in the Midlands are conducting clinical validation studies for next-generation absorbable matrices.
Switzerland
ISO 13485-certified contract manufacturing facilities in Basel and Zurich enable mid-tier device firms to access quality-compliant production. Swissmedic regulatory pathways attract dual-territory certification strategies from manufacturers seeking CE marking efficiency. Precision engineering clusters in the Lake Geneva region supply specialized instrumentation components to German and French hospital networks.
Uro Gynaecological Surgical Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue robotic-compatible instrumentation and disposable energy-delivery platforms. The vendor base stratifies across integrated surgical ecosystem providers, specialized pelvic floor repair portfolios, and contract manufacturing specialists. Three archetypes dominate: diversified medtech conglomerates with captive hospital network relationships, mid-tier firms leveraging outsourced ISO-certified production, and capital equipment manufacturers bundling disposable recurring revenue streams. Competitive moves center on metropolitan hospital network consolidation through single-source contracts and patent-protected energy-delivery system expansion.
Within the diversified medtech tier, Medtronic and Johnson & Johnson exemplify integrated ecosystem strategies that anchor high-volume supply agreements. Boston Scientific occupies a specialized position targeting ambulatory surgical center procurement for pelvic floor repair applications. These three entities represent distinct competitive vectors: ecosystem breadth, ambulatory-focused specialization, and robotic R&D intensity.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Coloplast |
| Johnson & Johnson |
| Intuitive Surgical |
| CooperSurgical |
| Hologic |
| Becton Dickinson |
| Stryker |
| Others |
Cost & Logistics Intelligence
Specialized biomedical engineers in Basel-Zurich precision clusters command wage premiums that compress margin spreads between premium robotic instrumentation and standard laparoscopic kits. Labor-cost differentials between Swiss contract manufacturers and German stainless steel fabricators drive three-tier pricing stratification across integrated surgical ecosystems, ambulatory procurement bundles, and economy disposable platforms.
Pricing Analysis
Warranty and preventive maintenance bundling once anchored capital equipment contracts, yet metropolitan hospital networks in the United States now unbundle after-sales service to force discrete pricing. Three-tier pricing structure across premium, standard, and economy levels separates robotic-compatible platforms with proprietary energy patents from ISO 13485-certified mid-tier instrumentation and unbranded disposable retractors. Price differentiation stems from FDA 510(k) predicate complexity and CE marking tier under EU MDR. Cost compression in economy sutures is intensifying because absorbable matrix suppliers face ISO 10993 biocompatibility testing inflation. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize outcome-based performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from consolidated purchasing networks in Germany and Japan force manufacturers to qualify redundant suppliers for medical-grade stainless steel alloys. Geographic supply concentration centers on German specialty steel foundries, Japanese polymer composite compounders, and Swiss precision machining clusters. Raw material dependencies include cobalt-chromium alloys for retractor durability, absorbable polyglycolic acid matrices for sutures, and ceramic substrates for electrosurgical insulation. Single-source vulnerability persists in EU MDR notified body capacity, where Berlin-Brandenburg and Netherlands-based auditors create qualification bottlenecks for Class IIb devices. Distribution runs through GPO contracts in North American integrated delivery networks and direct hospital procurement in European metropolitan systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints under EU MDR technical documentation requirements prop pricing power for manufacturers with pre-qualified quality management systems, creating a supply-constrained market structure where approved device portfolios command persistent premiums.
For Market Incumbents: Hedge against margin erosion in reusable instrumentation by deepening backward integration into polymer composite suture production and securing captive supply of medical-grade stainless steel from Osaka-Kobe manufacturing clusters. Defensive positioning requires accelerating FDA 510(k) pathway efficiency for predicate-based electrosurgical submissions before EU MDR audit backlogs resolve. Threat substitution from single-use disposable platforms demands channel control through exclusive GPO contracts with metropolitan hospital networks. For New Entrants and Emerging Players: Begin with ISO 13485-certified contract manufacturing partnerships in Ireland and Switzerland to bypass captive facility capital requirements. White-space targets include ambulatory surgical center kit procurement in Germany and Japan, where outpatient migration outpaces established vendor penetration. Most penetrable segment: disposable electrosurgical attachments with vessel-sealing algorithms for pelvic floor repair. Go-to-market angle: unbundled maintenance pricing that undercuts integrated ecosystem service contracts. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier firms possessing dual-territory FDA and EU MDR certifications given accelerating consolidation in metropolitan hospital network procurement. Long-term viability over the projection horizon favors acquisition targets with robotic-compatible instrumentation pipelines and recurring consumable revenue models. Signal to watch: reimbursement parity alignment between robotic-assisted and laparoscopic hysterectomy procedural codes as inflection indicator for capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined predicate pathways compress market entry timelines for electrosurgical platforms. |
| EU MDR CE Marking Pathway | Notified body capacity constraints in Germany extend approval timelines for absorbable mesh portfolios. |
| Hospital System Partnership | Single-source contracts with integrated delivery networks lock in recurring instrument revenue streams. |
| Software Companion Development | Integrated vessel-sealing algorithms differentiate electrosurgical units in academic medical center procurement. |
| Reimbursement Strategy | Procedural code parity alignment determines capital deployment speed across robotic platform installations. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation submissions, hospital procurement databases, and GPO contract disclosures, complemented by interviews with clinicians, hospital purchasing committee directors, biomedical engineers, and regulatory affairs specialists. Primary fieldwork triangulated against secondary validation from ISO certification registries, notified body audit schedules, and CMS Medicare reimbursement data. Bottom-up demand modeling across product type, technology platform, and end-user segments was cross-referenced with top-down market sizing from capital equipment installation records.
Historical utilization rates for robotic-assisted and laparoscopic platforms were cross-referenced against panel input from hospital procurement executives to establish baseline assumptions. Segmentation dimensions modeled include product type, technology platform, end-user setting, application indication, and regional regulatory cluster. CAGRs were derived from installed base expansion trajectories and recurring instrument revenue per procedure. Industry-specific forecast inputs incorporate fellowship program output rates for robotic surgery specialists and EU MDR notified body capacity constraints.
Regulatory approval delays, reimbursement parity misalignment, and raw material alloy cost volatility are the dominant revision risks across the analysis window. Forecasts reflect documented assumptions regarding outpatient migration velocity and dual-territory certification synchronization timelines. Deviation in notified body audit capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Cryosurgery Market