
 Hand-Held Surgical Instruments Market | 2026-2036
Hand-Held Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Hand-Held Surgical Instruments Market Intelligence
Aftermarket service revenue is reshaping profitability dynamics across the hand-held surgical instruments sector. Johnson & Johnson leverages its DePuy Synthes service network to capture recurring maintenance contracts. B. Braun Melsungen AG anchors its position through captive sterilization and refurbishment operations in Europe. Stryker Corporation differentiates via instrument tracking systems bundled with preventive service agreements.
Hand-held surgical instruments comprise manually operated tools fabricated from stainless steel, titanium, or polymer composites, designed for incision, dissection, grasping, or hemostasis during operative procedures requiring direct physician manipulation. Stainless steel forceps and hemostats dominate hospital procurement volumes due to established sterilization protocols and cost-effective reprocessing cycles. Titanium instruments command premium positioning in neurosurgery and microsurgical applications where reduced tissue adhesion and non-ferromagnetic properties prove critical. Carbon fiber variants represent the fastest-expanding material class as manufacturers respond to surgeon demand for lightweight ergonomics in prolonged orthopedic reconstructions.
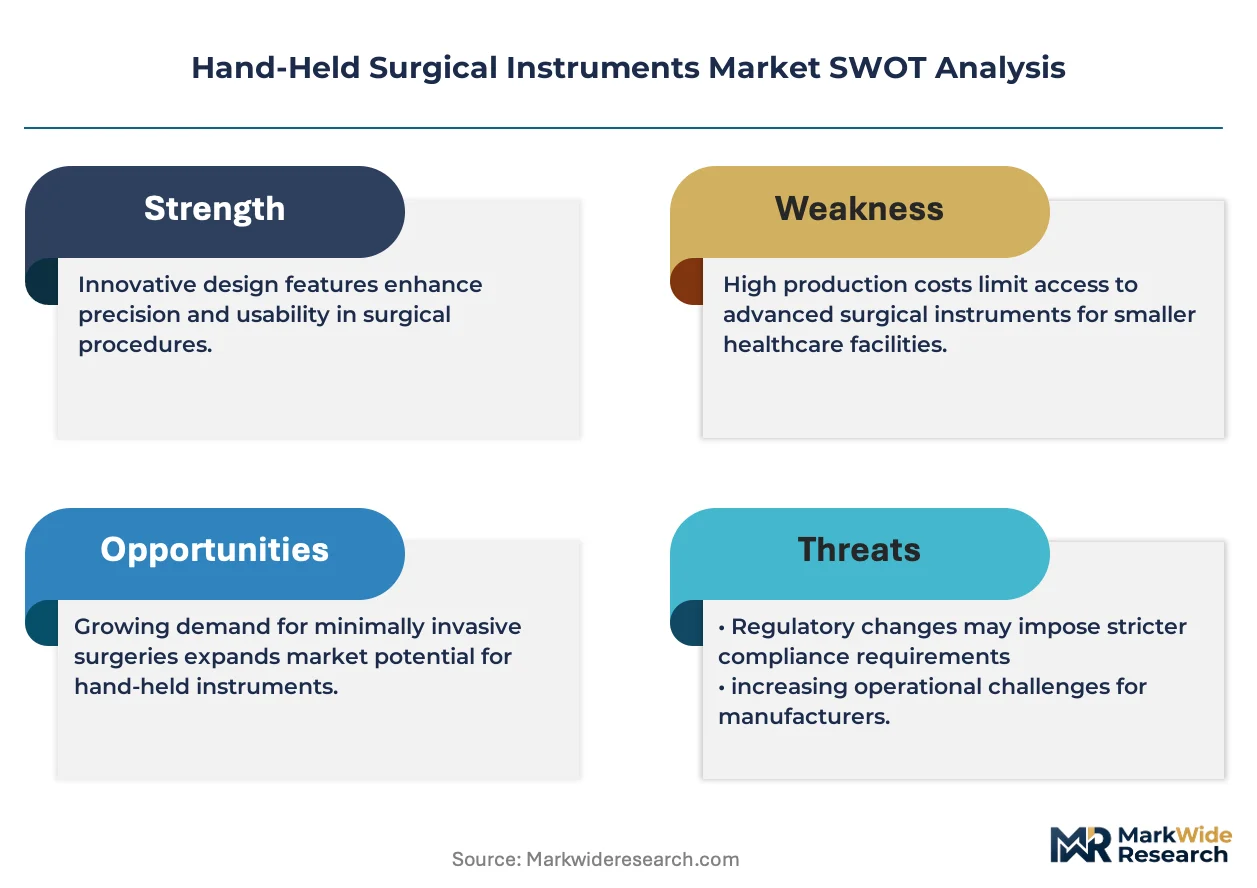
FDA 510(k) premarket notification requirements govern instrument material biocompatibility and dimensional tolerances in the United States, while EU MDR and ISO 13485 certification frameworks enforce design history file documentation and post-market surveillance obligations across European markets. The FDA's intensified scrutiny of reprocessed single-use instrument analogs is redirecting capital toward validated reusable platforms. Stakeholders must monitor evolving notified body capacity constraints under MDR implementation timelines and calibrate supply chain investments accordingly.
Market Dynamics
EU MDR material traceability mandates are forcing instrument manufacturers to reconfigure supply chains around documented stainless steel and titanium provenance, compressing margins for undifferentiated suppliers while rewarding vertically integrated producers with captive metallurgical operations.
Growth Catalysts
- EU MDR Conformity Deadlines:Notified body capacity constraints under the Medical Device Regulation are accelerating consolidation toward manufacturers with established technical documentation capabilities, privileging incumbent instrument suppliers over new entrants.
- Ambulatory Surgical Center Expansion:Freestanding ASCs in the United States are procuring validated reusable instrument sets to minimize per-procedure supply costs, creating volume pull for sterilization-durable forceps and hemostat configurations.
- Titanium Adoption in Neurosurgery:Reduced tissue adhesion and non-ferromagnetic properties are displacing conventional stainless steel in cranial and spinal microsurgical suites, commanding premium positioning despite higher unit economics.
Market Restraints
- Raw Material Cost Volatility:Surgical-grade stainless steel and medical titanium spot prices fluctuate with energy-intensive smelting costs, squeezing margin predictability for instrument fabricators without long-term metallurgical contracts.
- Notified Body Bottlenecks:EU MDR implementation has collapsed available conformity assessment capacity, extending certification timelines and freezing product launches for manufacturers dependent on third-party audit schedules.
- Reprocessed Single-Use Analogs:FDA intensified scrutiny of reprocessed disposable instruments creates pricing pressure on reusable platforms in cost-sensitive hospital systems, threatening volume retention for traditional instrument suppliers.
Strategic Opportunities
- German Operating Room Modernization:Hospital infrastructure refurbishment programs in Bavaria and North Rhine-Westphalia are specifying instrument tracking systems bundled with preventive maintenance agreements, opening service revenue streams.
- Carbon Fiber Ergonomics:Lightweight polymer composite instruments are penetrating orthopedic reconstruction segments where surgeon fatigue reduction justifies material premiums above titanium alternatives.
- Japan PMDA Harmonization Pathways:Convergence between Japanese pharmaceutical and medical device agency standards and ISO 13485 frameworks is streamlining dual-market registration for instrument manufacturers with existing European certification.
Industry Challenges
- Design History File Documentation:EU MDR technical file requirements demand exhaustive traceability for design changes across multi-decade instrument lifecycles, consuming specialized regulatory affairs capacity.
- Sterilization Validation Complexity:Reusable instrument reprocessing protocols must demonstrate bioburden elimination across varying hospital autoclave configurations, requiring extensive validation studies per SKU.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand-Held Surgical Instruments Market |
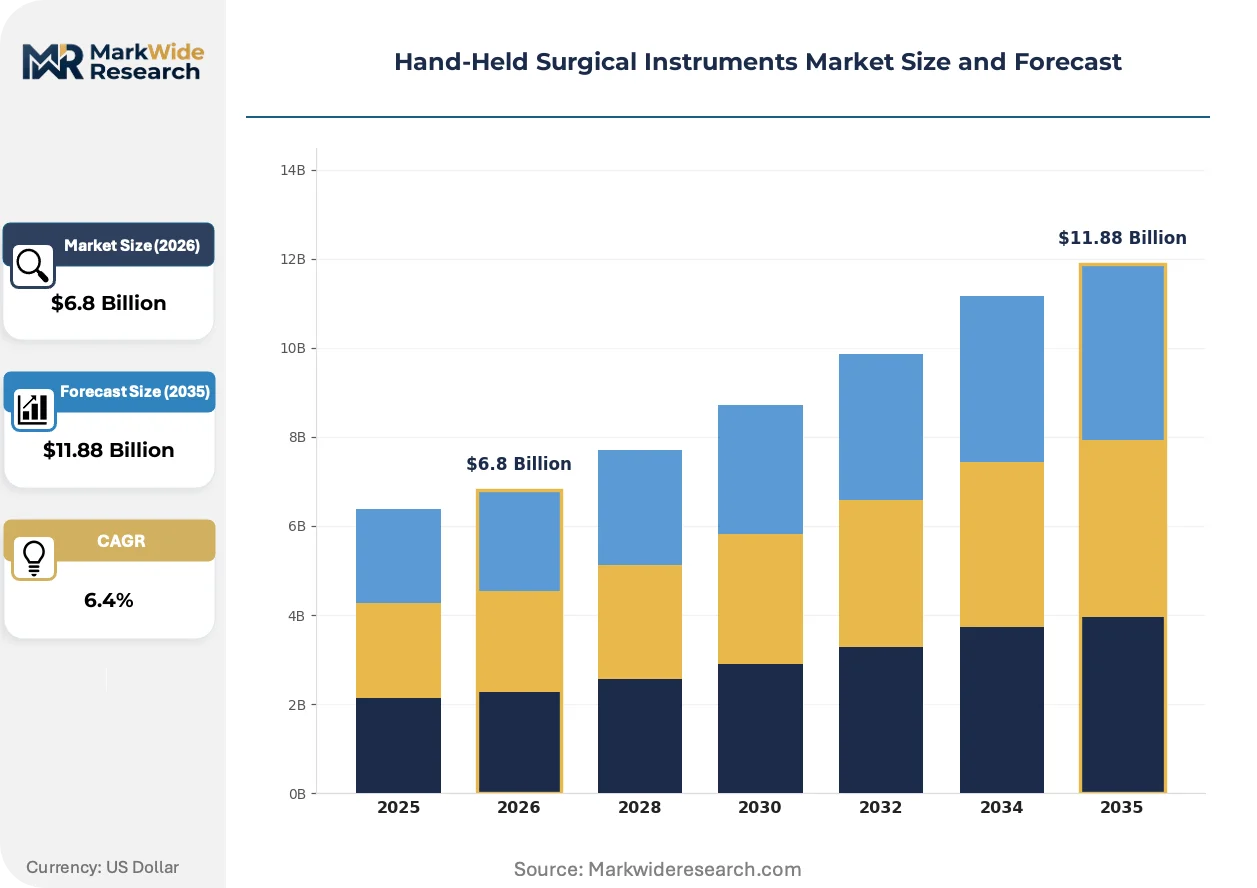
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Scissors, Forceps, Hemostats Application: General Surgery, Orthopedic Surgery, Neurosurgery, Cardiothoracic Surgery End User: Hospitals, Surgical Centers, Clinics, Research Laboratories Material: Stainless Steel, Titanium, Plastic, Carbon Fiber |
| Companies Covered | Johnson & Johnson, B. Braun Melsungen AG, Stryker Corporation, Medtronic plc, Zimmer Biomet Holdings, Integra LifeSciences Corporation, Smith & Nephew plc, KLS Martin Group, Aspen Surgical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand-Held Surgical Instruments Market Strategic Shifts & Innovations
Instrument intelligence layers are embedding tracking and usage analytics directly into hand-held surgical tools, transforming passive metalware into data-generating assets that reshape procurement evaluation criteria and after-sales relationships.
Carbon fiber reinforced polymer composites are collapsing the weight-performance tradeoff that previously constrained prolonged orthopedic procedures. Surgical suites in Germany and Japan are adopting these instruments for joint reconstruction cases exceeding three hours, where cumulative gram-reduction in tool mass demonstrably reduces operator fatigue. The technology is collapsing traditional material hierarchies that positioned titanium as the sole lightweight alternative to stainless steel.
EU MDR Article 10 post-market surveillance obligations are mandating systematic complaint handling and trend reporting across instrument lifecycles. Manufacturers must maintain vigilance systems capable of detecting performance degradation signals from distributed hospital installations. German notified bodies are enforcing these requirements most stringently, driving instrument suppliers to invest in digital feedback infrastructure previously unnecessary under the Medical Device Directive framework.
Surgeon preference is consolidating around instrument sets bundled with predictive maintenance and refurbishment scheduling. United States health system procurement committees now evaluate total cost of ownership across sterilization cycles rather than unit purchase price alone. This behavioral pivot privileges suppliers with captive service networks over pure manufacturing competitors, concentrating contract awards toward vertically integrated instrument providers.
Hand-Held Surgical Instruments Market Segmentation
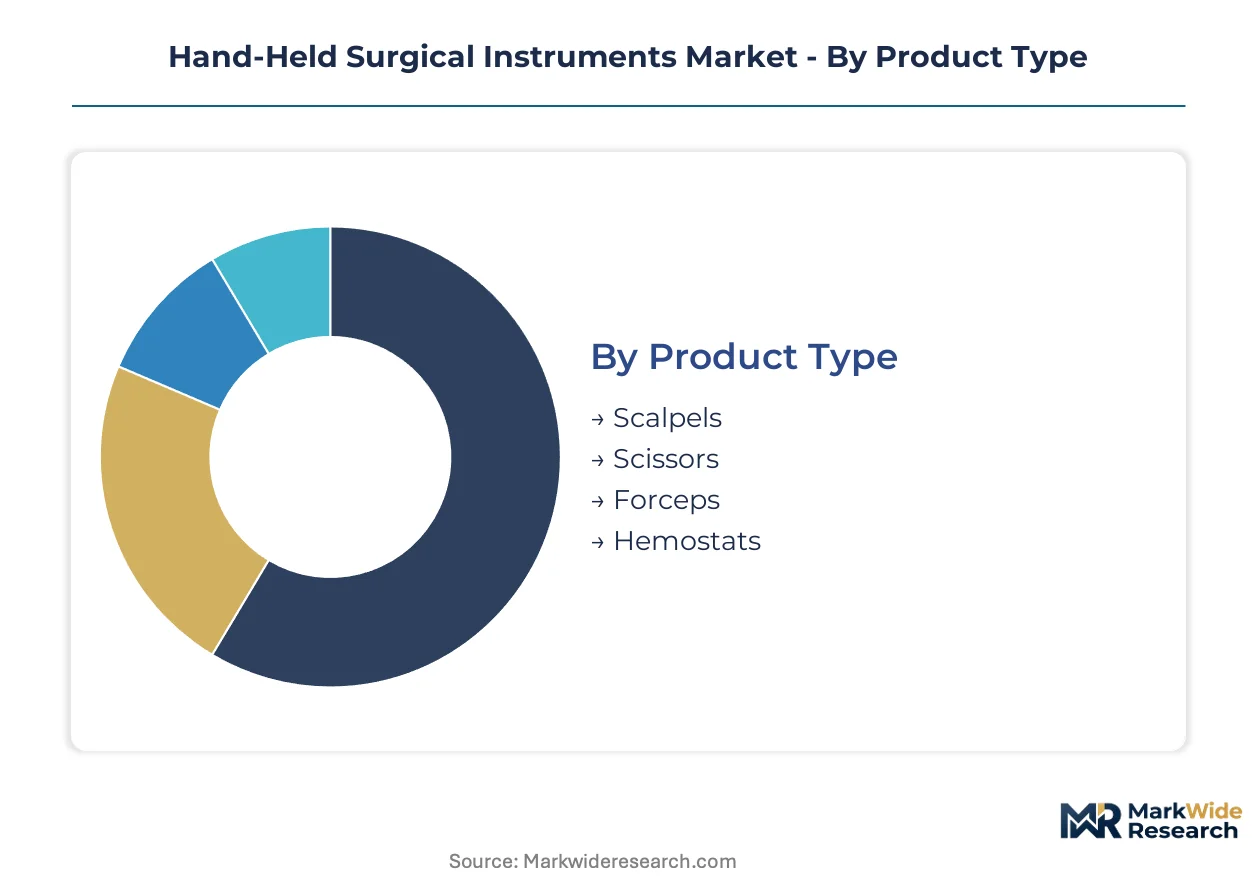
Segmentation in hand-held surgical instruments reveals how material science, procedural specialization, and procurement economics fragment demand across distinct technical and commercial profiles. Each dimension carries regulatory and supply chain implications that reshape competitive positioning.
Product Type:
Cost tier differentiation separates commodity metalware from precision-engineered instruments commanding maintenance contracts and refurbishment revenue streams.
- Scalpels:Disposable blade systems with reusable handles dominate high-volume general surgery suites. German hospital procurement committees prioritize validated reprocessing protocols over unit price.
- Scissors:Tungsten carbide inserts and micro-serrated edges define premium tiers in cardiothoracic applications. United States ASCs are consolidating purchasing around sterilization-durable configurations.
- Forceps:Ratcheted and non-ratcheted variants span tissue handling to hemostatic control.
- Hemostats:Locking jaw mechanisms with box-lock joints remain the workhorse clamping technology across surgical disciplines.
Scalpels hold installed capacity. Forceps are rotating up the share rankings.
Application:
Procedure-specific instrument requirements concentrate demand in surgical suites where material properties directly impact clinical outcomes and operative duration.
- General Surgery:Broad-spectrum instrument sets emphasizing versatility across laparotomy and open procedures. United States hospital systems standardize around configurable trays.
- Orthopedic Surgery:Heavy-duty retractors and bone-holding forceps withstand torque loads. Carbon fiber variants are gaining share fastest in joint reconstruction centers.
- Neurosurgery:Micro-instrument precision demands non-ferromagnetic titanium alloys.
- Cardiothoracic Surgery:Atraumatic tissue handling instruments prioritize hemostasis in vascular anastomosis.
General Surgery commands procedure volume. Orthopedic Surgery is climbing the fastest in instrument specialization.
End User:
Customer type determines procurement authority, reprocessing infrastructure, and total cost of ownership evaluation criteria.
- Hospitals:Integrated delivery networks with captive sterilization departments and instrument tracking systems. German university hospitals specify predictive maintenance bundles.
- Surgical Centers:Freestanding ASCs minimize per-procedure supply costs through validated reusable sets. United States outpatient migration is accelerating instrument turnover.
- Clinics:Limited-procedure settings favor disposable or single-patient-use instruments.
- Research Laboratories:Non-clinical validation and training applications drive demand for anatomically accurate simulation instruments.
Hospitals anchor procurement volume. Surgical Centers are expanding share fastest in reusable instrument adoption.
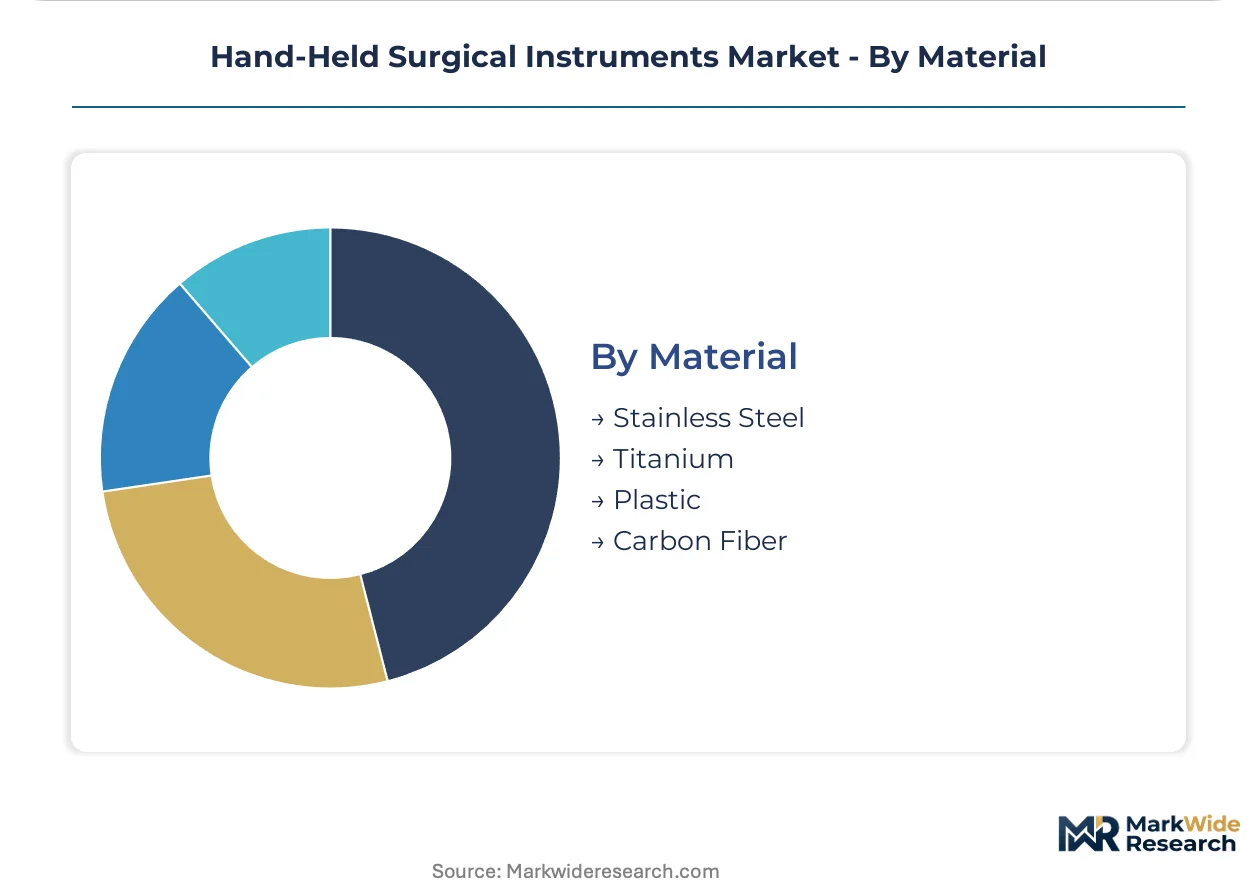
Material:
Supply concentration and metallurgical provenance determine margin structure and regulatory compliance burden under EU MDR traceability mandates.
- Stainless Steel:Surgical-grade 400-series and precipitation-hardened alloys dominate hospital procurement. Established autoclave compatibility and cost-effective reprocessing sustain volume leadership.
- Titanium:Grade 5 and 23 alloys with reduced tissue adhesion command premium positioning. Neurosurgical suites in Japan specify non-ferromagnetic properties for MRI compatibility.
- Plastic:Polymer-based disposable instruments serve cost-sensitive single-use applications.
- Carbon Fiber:Reinforced polymer composites collapse weight-performance tradeoffs in prolonged orthopedic reconstructions.
Stainless Steel holds installed capacity. Carbon Fiber is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies: United States health systems minimize total cost of ownership through predictive maintenance contracts, while Japanese university hospitals prioritize premium titanium alloys regardless of unit economics. German operating room modernization programs occupy the middle ground, balancing upfront capital constraints against lifecycle durability requirements.
United States
Ambulatory surgical centers now drive reusable instrument procurement volumes as outpatient migration accelerates. FDA intensified scrutiny of reprocessed single-use analogs redirects hospital capital toward validated reusable platforms. Cleveland Clinic and Mayo Clinic anchor instrument tracking system adoption in the Midwest, bundling predictive maintenance into procurement evaluations.
Germany
Bavarian and North Rhine-Westphalian hospital refurbishment programs specify instrument sets with embedded intelligence layers. EU MDR notified body capacity constraints privilege incumbent suppliers with established technical documentation. Tuttlingen's surgical instrument cluster concentrates captive metallurgical operations and sterilization validation capabilities under vertically integrated producer networks.
Japan
Neurosurgical suites in Tokyo and Osaka specify Grade 23 titanium alloys for MRI-compatible micro-instrumentation. PMDA harmonization with ISO 13485 frameworks streamlines dual-market registration for European-certified manufacturers. Nagoya's medical device corridor anchors carbon fiber composite development for orthopedic reconstruction applications.
China
Domestic hospital procurement committees balance cost containment against NMPA biocompatibility mandates for imported stainless steel instruments. Yangtze River Delta manufacturing bases expand surgical-grade metallurgical capacity to reduce import dependency. Shanghai's medical device registration reform accelerates 510(k)-cleared foreign product market entry.
Switzerland
Swissmedic enforcement of EU MDR-equivalent traceability requirements compresses margins for undifferentiated instrument suppliers. Geneva and Basel university hospitals specify premium hemostat configurations with documented alloy provenance. The Jura Arc watchmaking precision ecosystem transfers micro-machining capabilities into microsurgical instrument fabrication.
Hand-Held Surgical Instruments Market Key Industry Players
Diversified medical technology conglomerates and specialized surgical instrument fabricators split the market into distinct competitive spheres. The vendor base concentrates around three strategic archetypes: vertically integrated producers with captive metallurgical operations, service-network orchestrators capturing recurring maintenance revenue, and precision-engineering specialists commanding premium positioning in microsurgical niches. Consolidation pressures favor incumbents with established EU MDR technical documentation capabilities, while notified body bottlenecks freeze new entrant product launches. Geographic expansion and strategic partnerships constitute the dominant competitive moves as manufacturers navigate certification timeline uncertainty.
Among diversified medical technology conglomerates, Johnson & Johnson and Stryker Corporation exemplify the service-network orchestrator archetype through aftermarket revenue capture. B. Braun Melsungen AG anchors the vertically integrated producer category with European-based captive sterilization operations. These three entities occupy positions that concentrate contract awards from procurement committees evaluating total cost of ownership across instrument lifecycles rather than unit purchase price alone.
| Leading Market Players |
|---|
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Medtronic plc |
| Zimmer Biomet Holdings |
| Integra LifeSciences Corporation |
| Smith & Nephew plc |
| KLS Martin Group |
| Aspen Surgical Products |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp metallurgical corridor's freight cost dynamics concentrate surgical-grade stainless steel supply in Tuttlingen and Solingen, compressing margins for distributors without captive foundry relationships while amplifying price differentiation between EU MDR-certified instrument sets and undifferentiated commodity metalware.
Pricing Analysis
Preventive maintenance and refurbishment contracts drive lifetime value capture for instrument suppliers. Three-tier pricing structure across premium, standard, and economy levels separates titanium microsurgical sets with tracking intelligence from basic stainless steel configurations. Cost compression in economy tiers is intensifying because raw material spot volatility erodes fabricator margins without long-term metallurgical contracts. Ambulatory surgical centers exhibit highest price sensitivity, while German university hospitals prioritize total cost of ownership over unit purchase economics.
Supply Chain Analysis
Export-control restrictions on surgical-grade titanium alloys and precision machining equipment limit technology transfer to non-allied manufacturing bases. Supply concentrates in Germany, Switzerland, and Japan for finished instruments, with surgical-grade stainless steel feedstock drawing from Swedish and Finnish metallurgical operations. Single-source vulnerability runs through Tuttlingen's instrument cluster for specialized microsurgical fabrication. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, direct tender contracts in Germany, and regional medical device distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR implementation creates a high-growth disruption window as notified body bottlenecks freeze new entrant certifications while privileging incumbents with established technical documentation capabilities.
For Market Incumbents: Build regulatory documentation moats by expanding in-house notified body liaison capacity and captive sterilization validation operations. Consolidate supply relationships with Swedish stainless steel producers to secure metallurgical provenance documentation. Deepen backward integration into precision forging to defend against carbon fiber composite substitution threats.
For New Entrants and Emerging Players: Carbon fiber orthopedic instruments for Japanese joint reconstruction centers represent the most penetrable entry point given PMDA-ISO harmonization and surgeon demand for fatigue-reduction ergonomics. Target United States ambulatory surgical centers with validated reusable instrument sets priced below incumbent service-bundled offerings. Pursue white-label manufacturing partnerships with Tuttlingen cluster firms to bypass certification timeline barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineering specialists with established EU MDR technical files and captive metallurgical operations. Long-term viability hinges on service-network density rather than manufacturing scale alone. Watch for PMDA acceleration of carbon fiber composite approvals as inflection signal for material substitution trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body capacity constraints privilege incumbents with pre-submitted design history files. |
| Instrument Tracking System Integration | Mayo Clinic and Cleveland Clinic procurement committees now mandate RFID-enabled sets. |
| Carbon Fiber Composite Platform Development | Nagoya medical device corridor anchors lightweight orthopedic instrument innovation. |
| Captive Sterilization Service Network Expansion | Bavarian hospital refurbishment programs specify predictive maintenance bundles. |
| Japanese PMDA Dual Registration Pathway | ISO 13485 convergence streamlines market entry for European-certified manufacturers. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts directors, and sterilization validation specialists and refined through secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and customs trade records. Bottom-up demand modeling across instrument SKUs and top-down market sizing triangulated volume estimates.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation dimensions spanning material class, procedural application, end-user facility type, and regional regulatory cluster. CAGRs derived from instrument replacement cycle analysis, ambulatory surgical center expansion trajectories, and EU MDR implementation timeline impacts. Forecast inputs incorporated surgeon preference surveys and sterilization durability validation data.
Practitioners should monitor notified body capacity expansion, raw material spot price movements, and FDA reprocessing policy shifts for early signals of forecast deviation. Material shifts in EU MDR enforcement stringency or carbon fiber composite regulatory pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Surgical Retainers Market