
 Neurosurgery Surgical Power Tools Market | 2026-2036
Neurosurgery Surgical Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Neurosurgery Surgical Power Tools Market Outlook
Market Context with Strategic Players
Titanium and ceramic composites are shifting the material base for high-speed neurosurgical drill handpieces, reducing thermal necrosis risk during extended cranial procedures. Stryker leverages its integrated manufacturing footprint to control supply continuity for precision-machined handpiece components. Medtronic anchors its competitive stance through deep R&D investment in battery-operated platforms for minimally invasive neurosurgery. Zimmer Biomet specializes in accessory ecosystems that lock into legacy drill systems, creating high switching costs for hospital purchasers.
Technical Definition and Structural Segments
Neurosurgery surgical power tools encompass motorized, pneumatic, or ultrasonic instruments engineered to cut, drill, abrade, or shape bone and soft tissue during intracranial, spinal, and craniofacial procedures, typically operating at rotational speeds exceeding 30,000 RPM with integrated irrigation channels for thermal management. These devices serve the primary commercial purpose of enabling precision tissue removal while minimizing iatrogenic trauma in confined anatomical spaces. Drill systems command the largest revenue pool among product types due to universal utilization across craniotomy and spinal fixation workflows, whereas battery-operated technology is expanding fastest as surgical centers prioritize cordless mobility and reduced OR setup complexity. Neurosurgery applications generate the deepest margin pools given the premium pricing attached to instruments validated for intracranial use, while spine surgery represents the highest-volume application segment driven by degenerative disc disease intervention rates.
Regulatory Frame and Forward Outlook
FDA 510(k) clearance pathways and EU MDR Class IIa/IIb conformity requirements govern neurosurgical power tool commercialization, with FDA scrutinizing electrical safety and biocompatibility data for battery-operated innovations while MDR intensifies post-market surveillance obligations for reusable handpiece sterilization validation. ISO 13485 quality management certification functions as a baseline market-access threshold for component suppliers serving OEM manufacturers. Stakeholders must monitor how FDA guidance on reusable device reprocessing and EU MDR economic operator liability rules reshape supplier qualification criteria and aftermarket service economics.
Market Dynamics
Battery-operated platforms are compressing pneumatic system lifecycles as tertiary surgical centers in Germany, Japan, and the United States prioritize cordless mobility and reduced operating room setup complexity. This technology displacement is restructuring supplier qualification criteria and aftermarket service economics across neurosurgical device supply chains.
Growth Catalysts
- EU MDR post-market surveillance mandates:Intensified sterilization validation requirements for reusable handpieces are accelerating hospital replacement cycles and expanding demand for validated single-use accessories.
- Spinal fixation workflow expansion:Rising degenerative disc disease intervention rates in aging populations are driving drill system utilization across ambulatory surgical centers and hospital outpatient departments.
- Ceramic composite thermal management:Reduced thermal necrosis risk during extended cranial procedures is elevating premium pricing power for high-speed handpiece manufacturers serving academic medical centers.
Market Restraints
- Titanium supply concentration:Precision-machined component sourcing depends on a limited base of aerospace-qualified metallurgical suppliers in Germany and the United States, creating vulnerability to capacity constraints.
- FDA 510(k) electrical safety scrutiny:Battery-operated platform submissions face extended review timelines for biocompatibility data packages, delaying commercialization windows for innovative cordless systems.
- Pneumatic infrastructure lock-in:Legacy hospital installations with compressed gas lines create switching costs that retard electric platform penetration in budget-constrained community hospitals.
Strategic Opportunities
- India neurosurgery hub development:Greenfield hospital construction in Mumbai and Delhi is creating first-mover advantage for battery-operated platform suppliers establishing training and service infrastructure.
- ISO 13485 component supplier qualification:Quality management certification gaps among Asian machining subcontractors present acquisition targets for OEMs seeking captive supply chain control.
- Ultrasonic ablation convergence:Integration of ultrasonic tissue removal with traditional rotary drilling is opening procedure-specific device bundles for minimally invasive intracranial applications.
Industry Challenges
- Sterilization validation engineering talent:EU MDR technical documentation requirements exceed the specialized workforce supply for reusable device reprocessing validation, extending compliance timelines.
- Legacy drill system integration:Accessory ecosystem lock-in by incumbent manufacturers creates friction for hospitals attempting to phase in next-generation battery platforms without full capital replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurosurgery Surgical Power Tools Market |
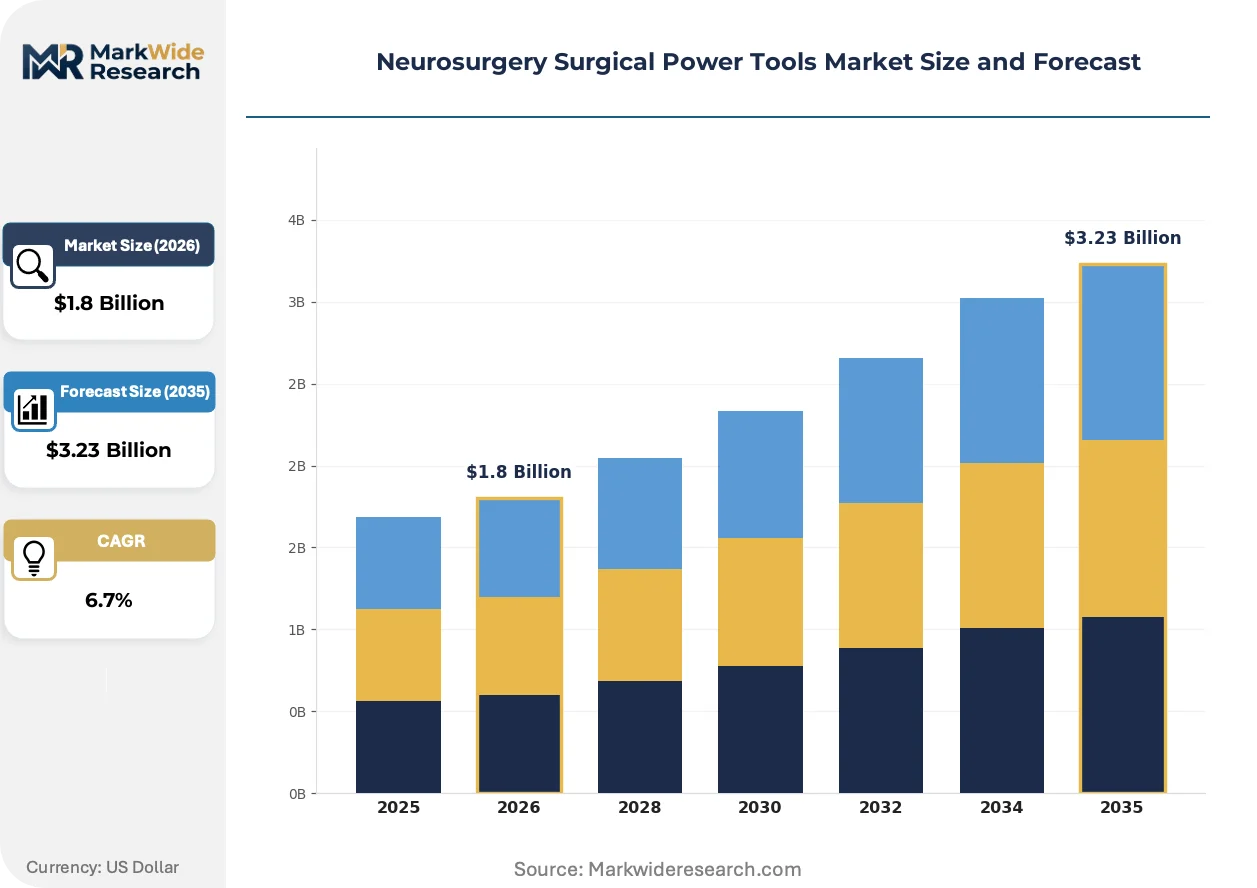
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handpieces, Accessories, Drill Systems, Saw Systems Technology: Pneumatic, Electric, Battery-operated, Ultrasonic End User: Hospitals, Surgical Centers, Research Institutions, Ambulatory Surgical Centers Application: Neurosurgery, Spine Surgery, Craniofacial Surgery, Neurotrauma |
| Companies Covered | Zimmer Biomet, KARL STORZ SE & Co. KG, Medtronic, DePuy Synthes, Integra LifeSciences, Stryker, Johnson & Johnson Services, Adeor Medical, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurosurgery Surgical Power Tools Market Strategic Shifts
Neurosurgical power tool architecture is undergoing fundamental redesign as thermal management, cordless energy density, and regulatory validation requirements converge. These forces are compressing product development cycles and elevating the strategic importance of materials science partnerships.
Brushless DC motor systems with integrated torque feedback sensors are rewriting performance benchmarks for high-speed cranial drilling. Academic medical centers in the United States are piloting these platforms for extended tumor resection procedures. The technology is rewriting competitive positioning by enabling real-time bone density compensation that reduces iatrogenic perforation risk.
EU MDR economic operator liability rules are intensifying post-market surveillance obligations for reusable handpiece sterilization validation. OEM manufacturers now face direct liability for reprocessing outcomes in European surgical centers. Battery-operated platforms with sealed, non-penetrating enclosures are capturing preference share as hospitals seek to minimize validation documentation burdens.
Service contract unbundling is disrupting traditional capital-equipment purchasing relationships in North American hospital systems. Procurement departments are separating device acquisition from maintenance and training obligations, pressuring manufacturer margin structures. This pattern is most visible in multi-hospital integrated delivery networks consolidating neurosurgical service lines across California and Texas.
Neurosurgery Surgical Power Tools Market Segmentation
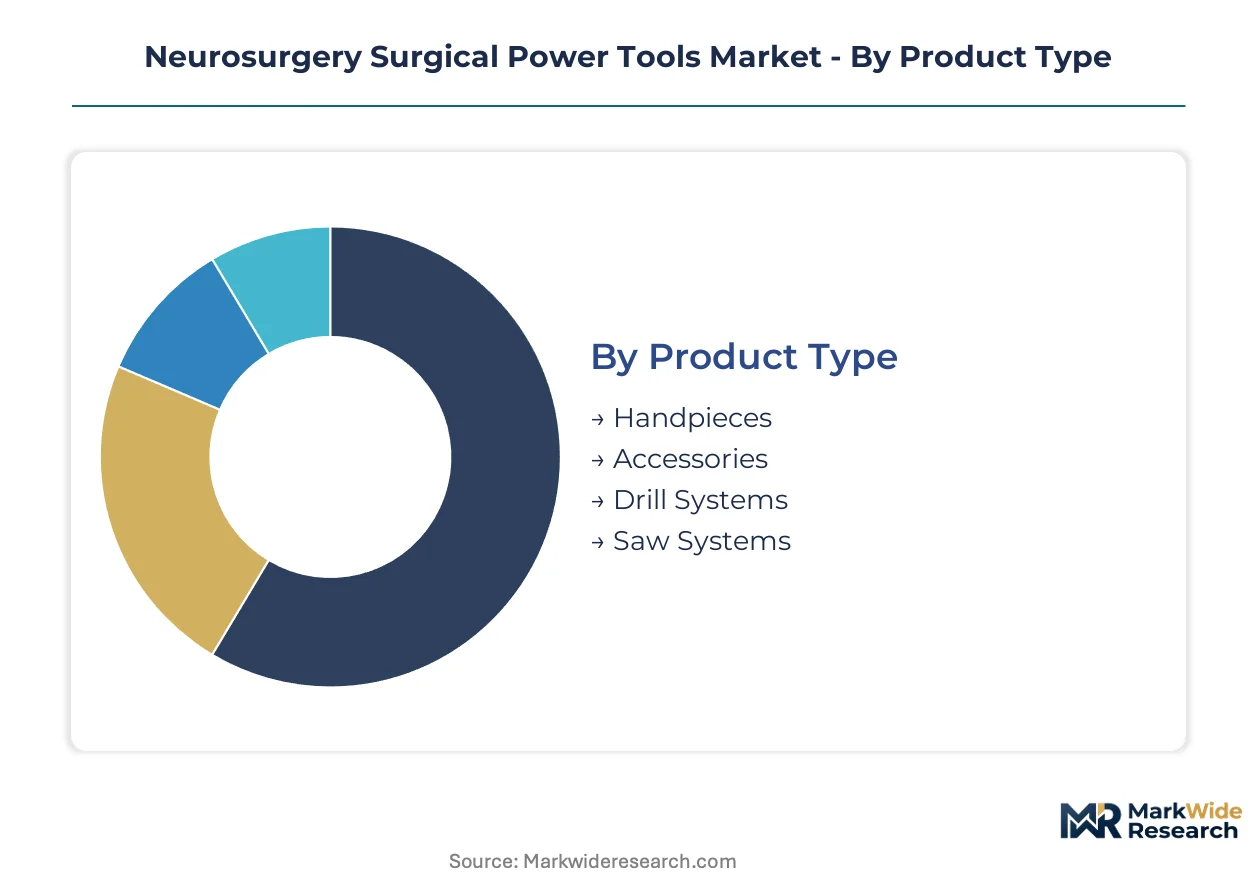
Power tool segmentation in neurosurgery reflects divergent procurement priorities across institutional settings. Academic medical centers demand precision-calibrated platforms for complex intracranial work, while ambulatory facilities prioritize capital efficiency and rapid turnover. Material specifications, sterilization protocols, and service infrastructure requirements fragment purchasing decisions across these divides.
Product Type:
Standardization dominates high-volume consumables, whereas handpiece systems require extensive customization to surgeon preference and institutional reprocessing capabilities.
- Drill Systems:High-speed rotary platforms operating above 30,000 RPM with integrated irrigation channels for thermal management during extended cranial procedures. Demand concentrates in tertiary care centers across Germany, Japan, and the United States as procedure volumes for tumor resection and spinal fixation climb. Pneumatic infrastructure lock-in at legacy facilities creates friction for electric platform conversion.
- Handpieces:Precision-machined titanium and ceramic composite components engineered for torque feedback and reduced thermal necrosis risk. Academic medical centers in the United States are piloting brushless DC motor variants with real-time bone density compensation, elevating switching costs for incumbent suppliers.
- Saw Systems:Oscillating and sagittal blade platforms for cranial flap creation and spinal osteotomy, typically procured as complementary attachments to drill system consoles.
- Accessories:Drill bits, guards, and irrigation tubing validated for single-use or limited reprocessing cycles, capturing recurring revenue streams through consumable replenishment.
Leading the category by volume: Drill Systems. Growing fastest: Handpieces with integrated sensor feedback.
Technology:
Energy density improvements and cordless mobility are restructuring platform economics across surgical center capital budgets.
- Battery-operated:Lithium-ion powered platforms with sealed enclosures eliminating pneumatic line dependency and reducing OR setup complexity. Tertiary surgical centers in the United States and Germany are prioritizing these systems for new construction and renovation projects, though FDA 510(k) electrical safety scrutiny extends commercialization timelines for innovative submissions.
- Electric:Corded brushless motor systems delivering sustained torque for extended procedures without battery swap interruption. Hospitals with established pneumatic infrastructure in Japan are adopting electric platforms as intermediate transition technology.
- Pneumatic:Compressed gas-driven systems with established reliability records but declining preference share due to infrastructure maintenance costs and noise exposure concerns.
- Ultrasonic:Piezoelectric tissue removal platforms converging with rotary drilling for minimally invasive intracranial applications, currently niche but expanding in academic research settings.
Fastest-expanding technology: Battery-operated platforms. Still commanding installed base: Pneumatic systems in budget-constrained community hospitals.
End User:
Capital intensity and procedure complexity stratify purchasing authority across institutional tiers.
- Hospitals:Comprehensive neurosurgical service lines with dedicated sterile processing departments and in-house biomedical engineering support. EU MDR post-market surveillance mandates are accelerating replacement cycles for reusable handpiece inventories as validation documentation burdens intensify.
- Surgical Centers:Focused delivery settings for spinal and craniofacial procedures, prioritizing single-use accessories to minimize reprocessing infrastructure investment.
- Ambulatory Surgical Centers:Outpatient-focused facilities with compressed case turnaround requirements, driving preference for lightweight battery platforms and streamlined setup protocols.
- Research Institutions:Preclinical and cadaveric training facilities with specialized procurement for experimental device evaluation and surgeon education programs.
Procurement volume leader: Hospitals. Fastest-climbing segment: Ambulatory Surgical Centers with degenerative disc disease intervention expansion.
Application:
Regulatory validation tiers and reimbursement rates create margin stratification across anatomical targets.
- Spine Surgery:Highest-volume application driven by aging population intervention rates for degenerative disc disease and spinal fixation workflows. Ambulatory surgical centers and hospital outpatient departments are expanding drill system utilization for decompressive laminectomy and pedicle screw placement.
- Neurosurgery:Deepest margin pool given premium pricing for instruments validated for intracranial use, with ceramic composite thermal management commanding price premiums at academic medical centers.
- Craniofacial Surgery:Reconstructive and trauma applications requiring specialized saw and drill configurations for maxillofacial bone work.
- Neurotrauma:Emergency decompression and hematoma evacuation procedures with emphasis on rapid deployment and reliability under time pressure.
Volume leader: Spine Surgery. Premium pricing concentration: Neurosurgery applications with intracranial validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for neurosurgery surgical power tools concentrates in tertiary care centers across Germany, Japan, and the United States, where aging populations and elevated procedure volumes for degenerative disc disease and intracranial interventions drive capital equipment procurement cycles.
United States
Academic medical centers in California and Texas are piloting brushless DC motor platforms with real-time bone density compensation for extended tumor resections. FDA 510(k) clearance pathways govern commercialization timelines for battery-operated innovations, with electrical safety scrutiny extending review periods for biocompatibility submissions. The Greater Boston cluster anchors neurosurgical device R&D concentration, with proximity to NIH-funded research institutions accelerating clinical validation partnerships.
Germany
Precision-machined titanium component sourcing from aerospace-qualified metallurgical suppliers in Bavaria and Baden-Württemberg underpins handpiece manufacturing for European OEMs. EU MDR Class IIa/IIb conformity requirements intensify post-market surveillance obligations, accelerating hospital replacement cycles for reusable handpiece inventories. The Stuttgart industrial corridor hosts concentrated machining subcontractor networks serving neurosurgical device supply chains.
Japan
Hospitals with established pneumatic infrastructure in the Kanto and Kansai regions are adopting electric platforms as intermediate transition technology, balancing cordless mobility demand against compressed gas line sunk costs. METI industrial standards shape domestic procurement specifications for high-speed rotary systems. The Nagoya medical device cluster concentrates precision motor manufacturing capabilities for regional OEM supply.
India
Greenfield hospital construction in Mumbai and Delhi is creating first-mover advantage for battery-operated platform suppliers establishing training and service infrastructure. CDSCO medical device registration requirements are tightening quality management expectations for imported neurosurgical equipment. The Maharashtra medical device corridor is emerging as a hub for ISO 13485-certified machining subcontractors targeting OEM qualification.
United Kingdom
NHS procurement consolidation across integrated care systems is separating device acquisition from maintenance contracts, pressuring manufacturer margin structures in neurosurgical service lines. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards for reusable device sterilization validation. The Oxford-Cambridge arc concentrates academic medical center demand for ceramic composite handpiece platforms with thermal management capabilities.
Neurosurgery Surgical Power Tools Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated OEMs controlling premium handpiece system supply and fragmented machining subcontractors competing on component cost. Three archetypes dominate: integrated device manufacturers with captive supply chains, precision component specialists serving multiple OEMs, and battery technology platform licensors. Competitive moves concentrate on M&A for ISO 13485-certified machining capacity and strategic partnerships for ceramic composite material science access.
Within the integrated device tier, Stryker and Medtronic exemplify archetypes of supply chain control and R&D platform investment respectively. Zimmer Biomet occupies a position emphasizing accessory ecosystem lock-in. Among European precision specialists, KARL STORZ SE & Co. KG and B. Braun Melsungen AG represent German-origin market anchors with established sterile processing validation expertise. DePuy Synthes and Johnson & Johnson Services sit within the diversified medical technology conglomerate tier, leveraging cross-divisional manufacturing scale.
| Leading Market Players |
|---|
| Zimmer Biomet |
| KARL STORZ SE & Co. KG |
| Medtronic |
| DePuy Synthes |
| Integra LifeSciences |
| Stryker |
| Johnson & Johnson Services |
| Adeor Medical |
| B. Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
EU MDR post-market surveillance mandates for reusable handpiece sterilization validation are gating qualified supply access and premium-tier pricing power, as hospitals face direct liability for reprocessing outcomes and OEMs must absorb elevated compliance documentation costs into platform economics.
Pricing Analysis
The volume-versus-margin split in neurosurgery surgical power tools separates high-unit spinal fixation workflows from premium-priced intracranial applications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with ceramic composite thermal management commanding price premiums at academic medical centers. Cost compression in battery-operated platforms is intensifying because FDA 510(k) electrical safety scrutiny extends commercialization timelines and R&D amortization periods. Ambulatory surgical centers exhibit highest price sensitivity due to compressed capital budgets, while tertiary care centers in Germany and the United States demonstrate lowest sensitivity given outcome-based procurement criteria.
Supply Chain Analysis
ISO 13485 quality management certification functions as the primary gating mechanism for component supplier qualification, with OEMs demanding validated machining subcontractors for precision-machined titanium and ceramic composite handpiece production. Supply concentration centers on Germany, Japan, and the United States, where aerospace-qualified metallurgical suppliers in Bavaria and Baden-Württemberg feed European manufacturing networks. Raw material dependencies rest on titanium billet sourcing, lithium-ion battery cell supply, and ceramic powder metallurgy. Single-source vulnerability in precision-machined component sourcing creates exposure to capacity constraints at aerospace-qualified suppliers. Distribution runs through direct OEM sales forces serving hospital purchasing committees and GPO contracts managers, with service contract unbundling disrupting traditional capital-equipment relationships in North American integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with players pursuing captive control over ISO 13485-certified machining capacity to secure supply continuity for precision-machined handpiece components and reduce qualification timeline exposure.
For Market Incumbents: Extend accessory ecosystem lock-in through backward integration into single-use consumable manufacturing, creating high switching costs for hospitals attempting phased platform transitions without full capital replacement. Deepen in-house production of ceramic composite handpiece components to reduce dependency on limited aerospace-qualified metallurgical suppliers in Germany and the United States. Battery-operated platform proliferation by emerging entrants threatens installed base retention, making channel control through training and service infrastructure the critical defensive lever. For New Entrants and Emerging Players: Ambulatory surgical centers in the United States represent the most penetrable buyer archetype, as degenerative disc disease intervention expansion drives drill system utilization in facilities prioritizing lightweight battery platforms and streamlined setup protocols. Greenfield hospital construction in Mumbai and Delhi offers white-space opportunity for suppliers establishing training and service infrastructure ahead of incumbent footprint. A direct-to-procurement go-to-market angle targeting hospital purchasing committees with unbundled service contracts can bypass traditional capital-equipment relationships. For Investors and Strategic Acquirers: EU MDR economic operator liability rule implementation is the leading indicator that sterilization validation engineering talent scarcity will reshape aftermarket service economics and create acquisition opportunities for specialized compliance consultancies. Long-term viability in this market hinges on materials science partnerships for thermal management innovation and captive supply chain control over precision-machined components. Acquisition targets should profile ISO 13485-certified machining subcontractors in Asian markets with quality management certification gaps, as OEMs seek upstream control to reduce supplier qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Composite Material Science Partnership | Access to advanced thermal management capabilities reduces iatrogenic trauma risk and commands premium pricing at academic medical centers. |
| ISO 13485-Certified Machining Subcontractor Acquisition | Captive supply of precision-machined components insulates against aerospace-qualified supplier capacity constraints in Germany. |
| Battery-Operated Platform FDA Submission | Electrical safety clearance for cordless systems unlocks tertiary care center procurement cycles in the United States and Germany. |
| Hospital System Training Infrastructure Buildout | Service contract bundling with capital equipment creates switching costs and defends margin position against unbundling pressures. |
| Single-Use Accessory Manufacturing Scale-Up | Validated consumable production captures recurring revenue streams and reduces hospital reprocessing documentation burdens under EU MDR. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation guidance, and hospital procurement contract filings, complemented by interviews with neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from SEC filings of publicly traded medical device manufacturers, ISO 13485 certification registries, and customs data for titanium and ceramic composite trade flows. Bottom-up and top-down triangulation cross-referenced procedure volume estimates with capital equipment replacement cycle assumptions.
Historical shipment data for drill systems, handpieces, and battery-operated platforms were cross-referenced against expert panel input from supply chain directors at major OEMs and sterile processing department heads at academic medical centers. Segmentation dimensions modeled across the analysis window included product type, technology platform, end-user facility tier, and application anatomy. CAGRs were derived from regression analysis of replacement cycle acceleration factors and technology displacement curves, with specific inputs for EU MDR compliance timeline impacts and battery energy density improvement trajectories.
Revisions become necessary when regulatory guidance on reusable device reprocessing shifts materially, when aerospace-qualified metallurgical supplier capacity constraints deepen, or when battery-operated platform electrical safety scrutiny intensifies beyond current FDA review patterns. A model refresh is warranted upon material change in hospital procurement consolidation dynamics or integrated delivery network service line restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Cystoscopy Needles Market