
 Surgical and Interventional Cardiology Devices Market | 2026-2036
Surgical and Interventional Cardiology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical and Interventional Cardiology Devices Market Analytics
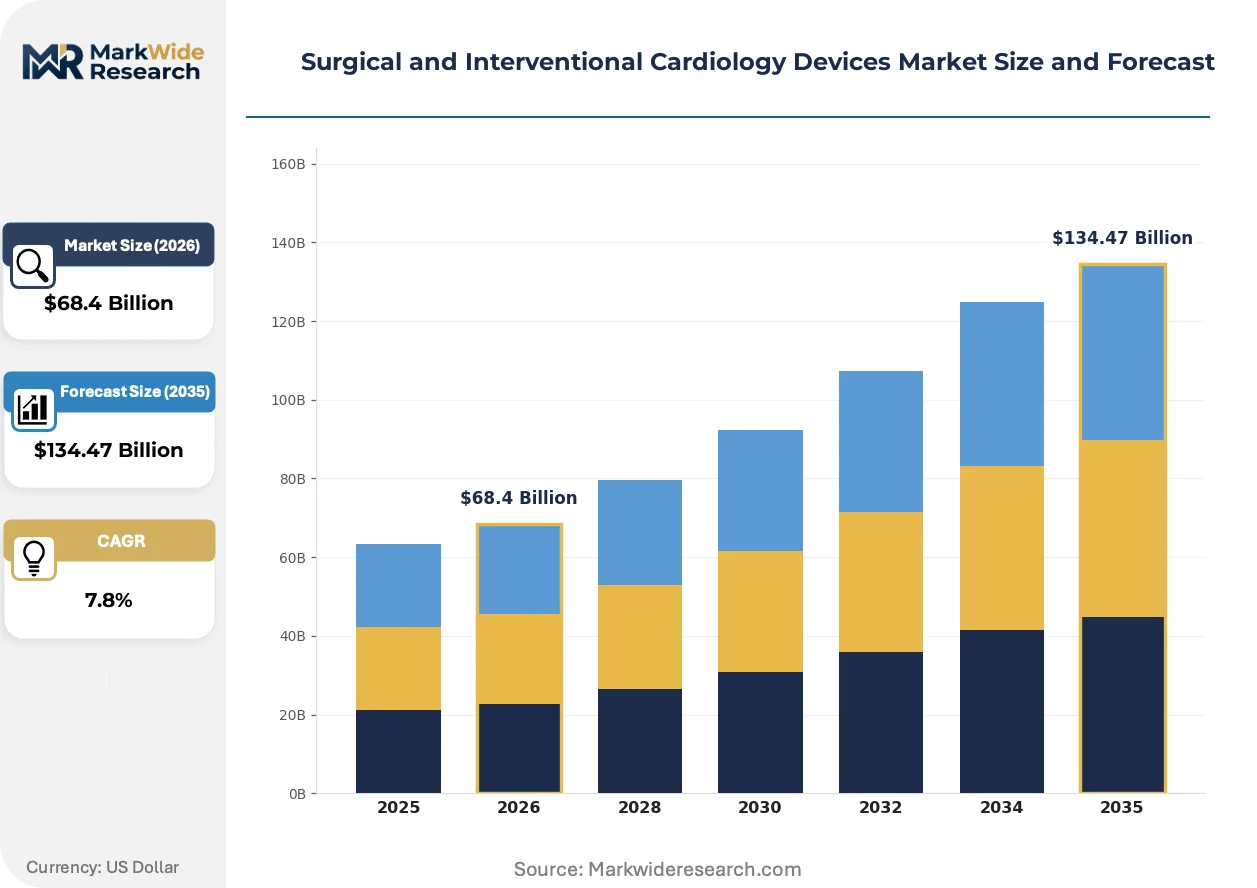
Transcatheter valve replacement platforms is reconfiguring how manufacturers engineer delivery systems and bioprosthetic materials. Abbott Laboratories leverages its structural heart portfolio to anchor North American catheter lab penetration. Medtronic sustains manufacturing scale across its guidewire and stent supply chains. Edwards Lifesciences Corporation specializes in pericardial tissue processing for transcatheter aortic valve implantation systems.
Surgical and interventional cardiology devices encompass stents, catheters, angioplasty balloons, and guidewires engineered from nitinol, cobalt-chromium alloys, or drug-eluting polymer matrices, designed to restore coronary or peripheral blood flow through percutaneous or open surgical access. Coronary artery disease indications dominate procedure volumes, while heart valve disease segments command premium pricing due to complex bioprosthetic engineering and extended regulatory pathways. Catheter-based delivery modes are displacing open surgery in elective revascularization, concentrating capital expenditure in hybrid operating suites across hospital systems.
FDA premarket approval pathways and EU MDR technical documentation requirements govern biocompatibility testing and clinical evidence standards for coronary stents and transcatheter valves. Japan's PMDA enforces stringent post-market surveillance protocols that extend product lifecycle accountability for manufacturers. Stakeholders must monitor convergence between minimally invasive delivery platforms and AI-guided procedural navigation as reimbursement frameworks evolve.
Market Dynamics
Catheter-based delivery systems are compressing the addressable market for open surgical valve repair while expanding procedural eligibility to high-risk patient cohorts previously excluded from intervention.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress time-to-revenue for transcatheter mitral valve repair platforms, incentivizing manufacturers to prioritize structural heart portfolios over conventional coronary stents.
- Japan's aging demographic:PMDA reimbursement expansion for transcatheter aortic valve implantation procedures drives hospital capital expenditure toward hybrid catheterization labs in Tokyo and Osaka metropolitan clusters.
- Nitinol superelastic alloys:Advanced shape-memory properties enable thinner delivery catheter profiles, expanding femoral access feasibility in peripheral artery disease interventions across ambulatory surgical centers.
Market Restraints
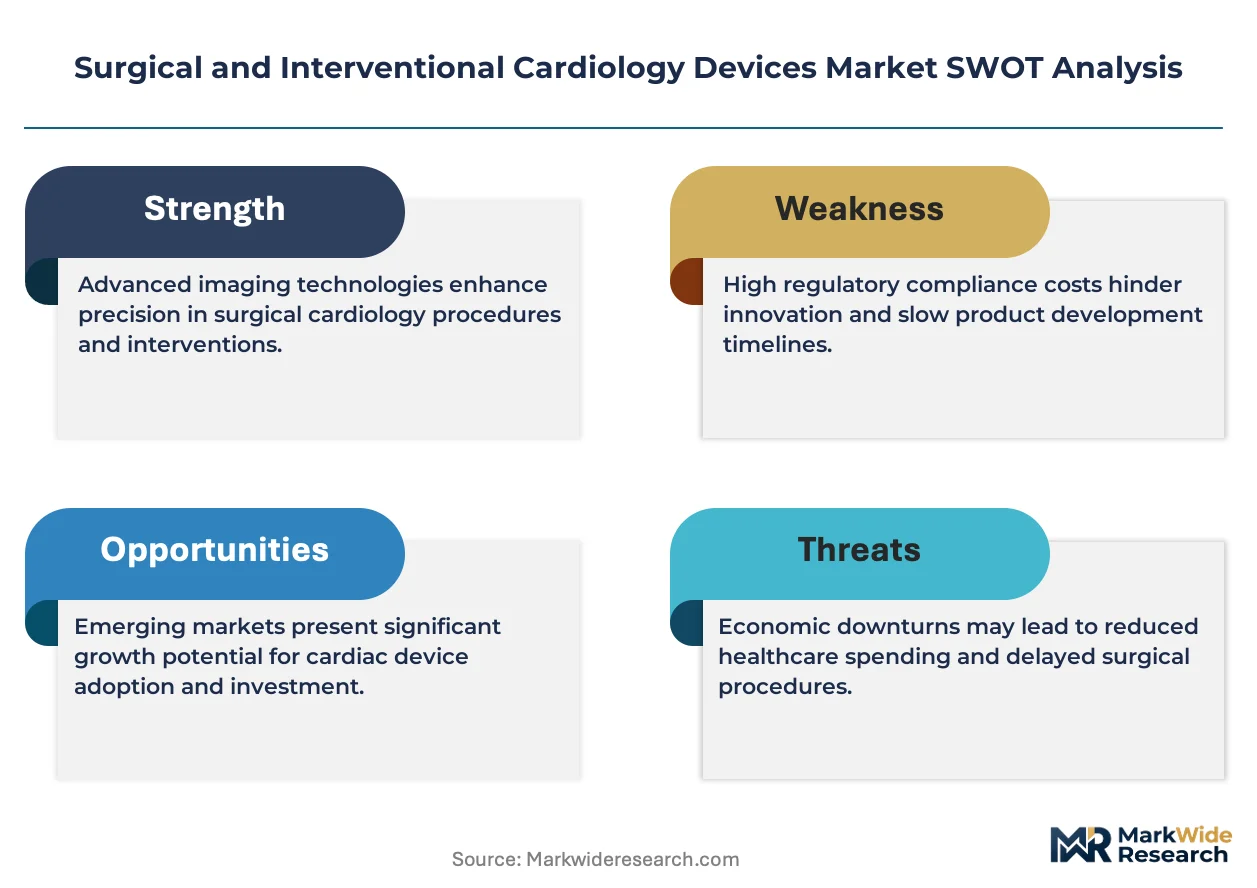
- Platinum-iridium electrode scarcity:Concentrated mining operations in South Africa and Russia create input cost volatility for electrophysiology catheter manufacturers, compressing gross margins on ablation systems.
- EU MDR technical documentation:Extended conformity assessment timelines for Class III implantable devices delay product launches by 18-24 months, freezing pipeline commercialization across European markets.
- Surgical robotics substitution:Intuitive Surgical's da Vinci ecosystem captures coronary bypass procedures previously addressed by interventional cardiology, constraining volume growth in elective revascularization segments.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import dependency for drug-eluting stents, creating localized supply chain advantages for multinational joint ventures with Indian contract manufacturers.
- AI-guided procedural navigation:Machine learning integration with fluoroscopy systems reduces radiation exposure and contrast dye volumes, opening reimbursement negotiations with payors focused on value-based care metrics.
- Teleproctoring networks:Real-time expert guidance via low-latency streaming expands transcatheter procedure adoption to community hospitals lacking onsite structural heart specialists, particularly in Germany's rural Länder.
Industry Challenges
- Interventional cardiologist training pipelines:Procedural complexity for transcatheter mitral valve repair exceeds fellowship exposure, creating credentialing bottlenecks that constrain case volume expansion in US academic medical centers.
- Hybrid operating suite capex requirements:Integrated imaging and surgical infrastructure demands exceed $5 million per installation, forcing hospital systems to consolidate cardiac service lines and decommission standalone catheterization labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical and Interventional Cardiology Devices Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $134.47 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Stents, Catheters, Angioplasty Balloons, Guidewires Indication: Coronary Artery Disease, Heart Valve Disease, Arrhythmias, Peripheral Vascular Disease End User: Hospitals, Surgical Centers, Specialized Clinics, Research Institutes Delivery Mode: Minimally Invasive, Open Surgery, Hybrid Approaches, Outpatient Procedures |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, Edwards Lifesciences Corporation, B. Braun SE, Terumo Corporation, Becton, Dickinson and Company, Teleflex Incorporated, Biotronik SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical and Interventional Cardiology Devices Market Evolving Landscape
Computational modeling and bioresorbable materials are restructuring how device developers validate performance and how clinicians select therapy modalities. Three developments warrant particular attention.
Digital twin technology is virtualizing pre-procedural planning for transcatheter valve interventions. Siemens Healthineers and Philips deploy patient-specific simulations derived from CT angiography to predict device landing zone anatomy and paravalvular leak risk. Cardiac surgery departments at Cleveland Clinic and Charité Berlin integrate these platforms into multidisciplinary heart team workflows, compressing case planning time while reducing intraoperative fluoroscopy exposure. The technology is virtualizing traditional sizing protocols based on two-dimensional echocardiography, displacing empirical device selection with algorithmic precision.
EU MDR Annex XVI expansion captures products without explicit medical purpose but with risk profiles comparable to regulated devices. The European Commission's implementing regulation on substance-based devices now governs certain coronary artery calcium scoring algorithms previously marketed as wellness tools. Software-as-medical-device classifications proliferate across risk stratification applications, forcing cardiovascular AI developers to establish quality management systems and clinical evidence portfolios. German notified bodies report 40% capacity constraints in MDR auditing, extending certification timelines for algorithm-based diagnostic aids.
Hospital procurement committees now unbundle device procurement from capital equipment agreements, reversing decade-old bundling strategies favored by integrated device-imaging vendors. Independent purchasing organizations in France's APHP and England's NHS Supply Chain negotiate stent and catheter contracts separate from angiography system leases, extracting price transparency through competitive tendering. The shift is most pronounced in coronary drug-eluting stent categories where biosimilar alternatives from Indian and Chinese manufacturers disrupt historical premium pricing structures.
Surgical and Interventional Cardiology Devices Market Segmentation
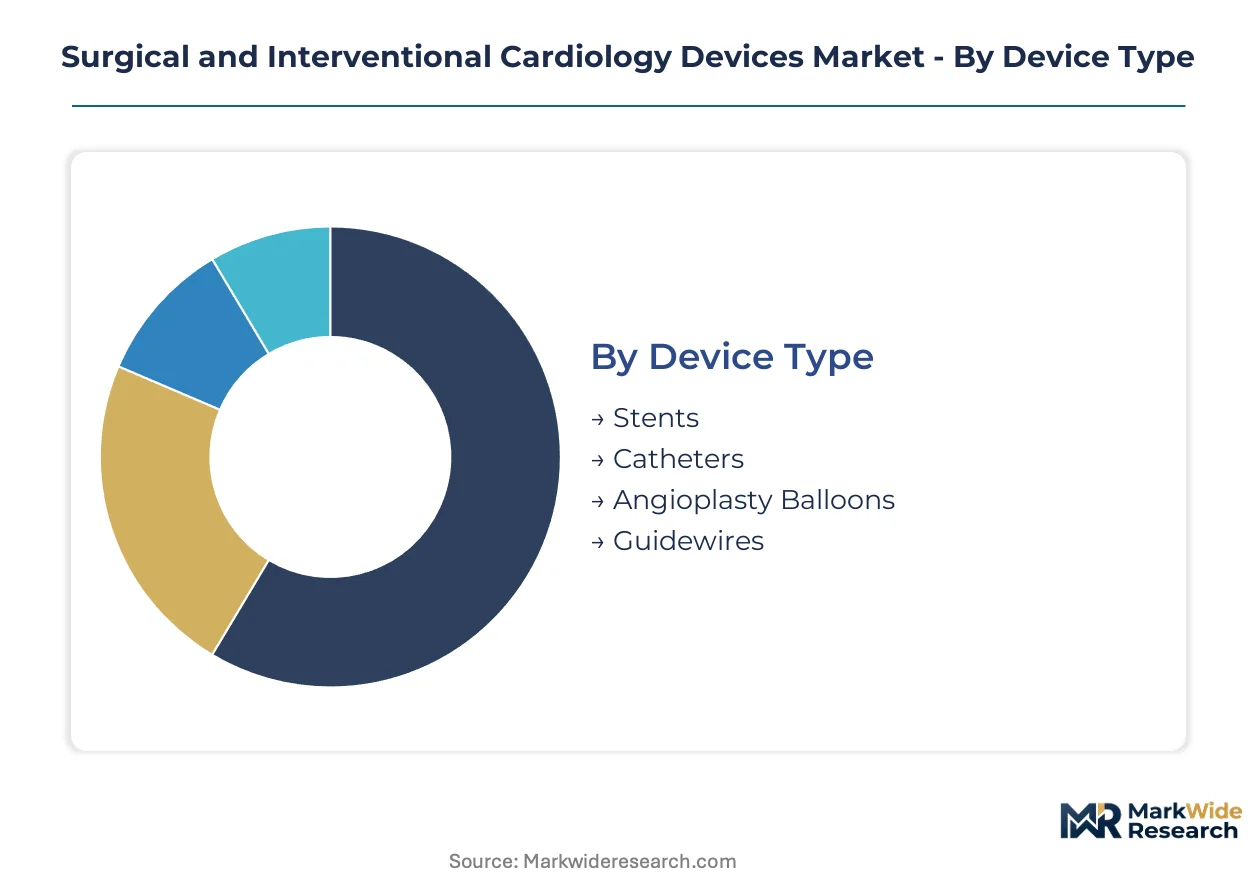
Surgical and interventional cardiology devices segment across multiple dimensions that determine service intensity, capital requirements, and reimbursement complexity. Understanding these divisions clarifies where manufacturers must invest in clinical training infrastructure versus commodity manufacturing scale.
Device Type:
After-sales service intensity varies dramatically across device categories, with implantable platforms demanding specialized field engineering support while consumable accessories rely on distributor logistics networks.
- Stents:Drug-eluting polymer matrices and cobalt-chromium alloy scaffolds require precise deployment technique. Demand concentrates in coronary artery disease interventions across tertiary hospital systems in the United States and Germany, driven by ambulatory surgical center expansion and same-day discharge protocols.
- Catheters:Multi-electrode mapping catheters and balloon-tipped delivery systems incorporate platinum-iridium electrodes and nitinol steering mechanisms. Electrophysiology labs in Japan's metropolitan clusters drive premium catheter volumes, constrained by electrode material scarcity from concentrated mining operations.
- Angioplasty Balloons:Semicompliant and noncompliant balloon platforms for lesion preparation and valve dilatation.
- Guidewires:Hydrophilic-coated and shapeable core wire systems for coronary and peripheral access.
Stents hold the largest share; momentum sits with catheters as structural heart procedures expand.
Indication:
Procedure volumes and pricing power diverge sharply across clinical applications, with valve interventions commanding premium positioning against commoditized coronary revascularization.
- Coronary Artery Disease:Percutaneous coronary intervention with drug-eluting stents dominates procedural volumes globally. Hospital systems in the United States optimize cath lab throughput through same-day discharge protocols, compressing length-of-stay metrics for reimbursement qualification.
- Heart Valve Disease:Transcatheter aortic and mitral valve replacement platforms utilize bovine or porcine pericardial tissue engineered for durability. Japan's aging demographic and PMDA reimbursement expansion concentrate demand in Tokyo and Osaka hybrid catheterization suites.
- Arrhythmias:Catheter ablation for atrial fibrillation and ventricular tachycardia utilizing radiofrequency or cryothermal energy delivery.
- Peripheral Vascular Disease:Femoropopliteal and below-the-knee revascularization with drug-coated balloons and self-expanding nitinol stents.
Coronary artery disease generates the highest procedure volumes; heart valve disease exhibits the steepest expansion trajectory as transcatheter platforms displace surgical candidates.
End User:
Capital expenditure thresholds and regulatory compliance burdens stratify the customer base, determining whether manufacturers deploy direct sales forces or distributor partnerships.
- Hospitals:Integrated delivery networks with hybrid operating suites combining surgical tables and fixed angiography systems. Cleveland Clinic and Charité Berlin anchor structural heart program development, requiring manufacturer investment in proctoring networks and clinical specialist deployment.
- Surgical Centers:Ambulatory facilities expanding catheterization lab capacity for elective revascularization in the United States and Germany. Lower capital barriers and streamlined regulatory pathways accelerate device adoption compared to hospital-based procurement.
- Specialized Clinics:Dedicated electrophysiology and interventional cardiology outpatient facilities.
- Research Institutes:Academic medical centers conducting pivotal trials for FDA premarket approval and EU MDR conformity assessment.
Hospitals retain the dominant procurement volume; surgical centers are gaining share fastest as site-of-service migration accelerates.
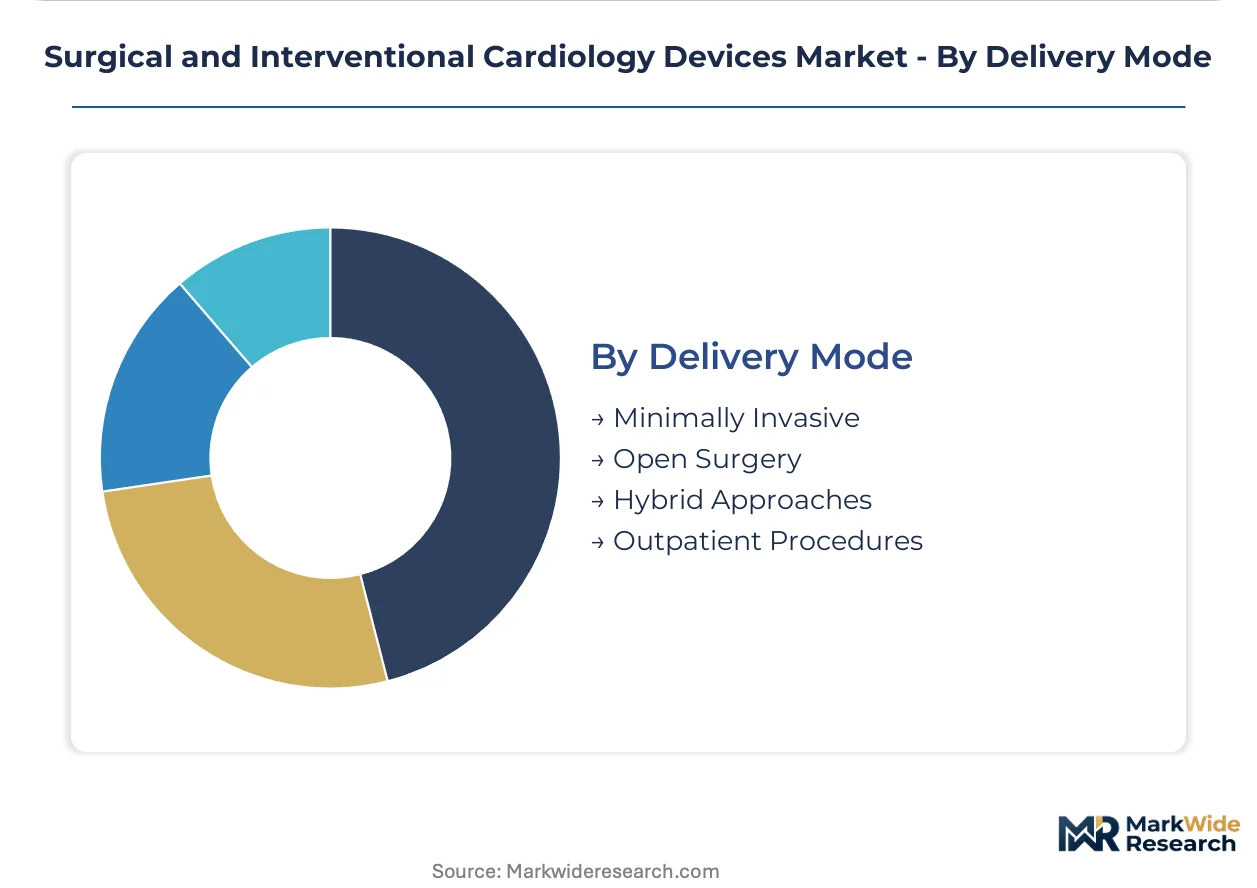
Delivery Mode:
Clinical training requirements and device engineering specifications diverge based on invasiveness level, with minimally invasive platforms demanding advanced imaging integration.
- Minimally Invasive:Transfemoral and transradial catheter-based access with fluoroscopic or intravascular ultrasound guidance. Siemens Healthineers and Philips deploy digital twin technology for pre-procedural planning at Cleveland Clinic, reducing intraoperative contrast exposure and procedure time.
- Open Surgery:Sternotomy-based coronary artery bypass grafting and surgical valve replacement. Intuitive Surgical's da Vinci ecosystem captures volume in elective revascularization, constraining interventional cardiology growth in specific patient cohorts.
- Hybrid Approaches:Combined surgical and catheter-based techniques in integrated operating suites.
- Outpatient Procedures:Same-day discharge protocols for diagnostic catheterization and elective revascularization.
Minimally invasive approaches command the largest share; hybrid approaches are climbing the fastest as heart team models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for nitinol alloys and platinum-iridium electrodes concentrates supply risk in specific geographies while export-oriented manufacturing clusters in Germany and the United States shape device availability across adjacent markets.
United States
FDA breakthrough device designation accelerates transcatheter valve platforms through premarket review, compressing commercialization timelines for structural heart portfolios. Ambulatory surgical center expansion across Texas and Florida drives catheterization lab capital expenditure toward same-day discharge protocols. Cleveland Clinic anchors heart team model adoption, integrating digital twin planning into multidisciplinary workflows.
Germany
EU MDR conformity assessment timelines extend certification cycles for Class III implantable devices, delaying product launches across European markets. Teleproctoring networks expand transcatheter procedure adoption to rural Länder lacking onsite structural heart specialists. Charité Berlin integrates patient-specific CT simulations into valve intervention planning, reducing intraoperative fluoroscopy exposure.
Japan
PMDA reimbursement expansion for transcatheter aortic valve implantation concentrates demand in Tokyo and Osaka metropolitan hybrid catheterization suites. Post-market surveillance protocols extend manufacturer accountability across product lifecycles. Aging demographic structures drive hospital capital expenditure toward minimally invasive valve repair systems.
India
PLI scheme incentives for medical device manufacturing reduce import dependency for drug-eluting stents, attracting multinational joint ventures with domestic contract manufacturers. CDSCO regulatory harmonization accelerates market entry pathways for coronary intervention platforms. Gujarat and Maharashtra clusters develop localized supply chain capabilities for nitinol processing and polymer matrix production.
China
NMPA innovation review pathways prioritize domestic transcatheter valve platforms, compressing approval timelines for locally developed bioprosthetic systems. Dual carbon goals influence hospital procurement criteria toward energy-efficient catheterization lab infrastructure. Yangtze River Delta medical device clusters expand guidewire and balloon catheter manufacturing capacity for regional export markets.
Surgical and Interventional Cardiology Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated structural heart portfolios and specialized electrophysiology platforms. Tiered competitive positioning separates diversified multinationals with catheter lab ecosystem control from mid-scale specialists in bioprosthetic tissue processing and guidewire engineering. Strategic archetypes include full-suite cardiovascular platform vendors, focused transcatheter valve developers, and component-specialist manufacturers. Dominant competitive moves encompass M&A for structural heart technology acquisition and backward integration into nitinol alloy and electrode material supply.
Within the diversified platform tier, Abbott Laboratories and Medtronic occupy positions spanning coronary stents, structural heart devices, and electrophysiology systems. Edwards Lifesciences Corporation exemplifies the focused specialization archetype, concentrating engineering resources on pericardial tissue processing for transcatheter implantation platforms. Boston Scientific Corporation sits within the integrated electrophysiology and interventional cardiology segment, representing competitive positioning across ablation catheters and coronary intervention devices.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| B. Braun SE |
| Terumo Corporation |
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| Biotronik SE & Co. KG |
| Others |
Value Network & Pricing Analysis
Shanghai-Rotterdam maritime freight corridors transmit cost volatility from platinum-iridium electrode scarcity into downstream price differentiation between premium transcatheter valve systems and commodity coronary stents. Hospital procurement committees exploit this dislocation through unbundled contracting strategies that separate device acquisition from capital equipment leases.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across drug-eluting stent categories, while academic medical centers absorb premium positioning for transcatheter valve platforms. Price differentiation rests on FDA breakthrough designation tier and bioprosthetic tissue certification grade. Cost compression in coronary stent segments is intensifying because Indian and Chinese biosimilar manufacturers disrupt historical premium structures. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with hybrid suite infrastructure demonstrate lowest.
Supply Chain Analysis
Export-control restrictions on superalloy technologies limit nitinol shape-memory alloy flows from United States and German specialized foundries to Asian contract manufacturers. Supply concentrates in South Africa and Russia for platinum-iridium electrodes, Germany and United States for cobalt-chromium scaffolds, and India and China for polymer matrix production. Raw material dependencies span concentrated mining operations for electrode metals, bovine and porcine pericardial tissue for bioprosthetic leaflets, and drug-eluting polymer formulations. Single-source vulnerability in electrode supply creates structural risk. Distribution runs through group purchasing organizations and regional distributor networks serving hospital systems and ambulatory facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcatheter mitral valve repair procedural complexity exceeds current fellowship training exposure, creating acute capability scarcity that constrains case volume expansion and fragments competitive positioning among manufacturers with proctoring infrastructure versus those without.
For Market Incumbents: Build captive proctoring networks as a defensive moat against emerging entrants lacking clinical training infrastructure. Expand backward integration into nitinol alloy processing to secure shape-memory material supply against export-control tightening. Prioritize EU MDR technical documentation investment to compress conformity assessment timelines relative to competitors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized domestic manufacturing corridor for drug-eluting stents, leveraging localized supply chain advantages before multinational joint ventures consolidate positions. Target teleproctoring-enabled community hospital segments in Germany's rural Länder where structural heart specialist scarcity creates penetrable demand. Pursue GPO contract participation as primary go-to-market mechanism. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized cardiovascular device divisions lacking structural heart focus. Long-term viability across the analysis window favors specialists with integrated tissue processing and digital twin planning capabilities. Monitor PMDA reimbursement expansion velocity for transcatheter aortic valve implantation as inflection indicator for Japanese market premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses time-to-revenue for transcatheter mitral repair platforms. |
| EU MDR Conformity Assessment | Technical documentation investment delays competitors without notified body relationships. |
| Hospital System Partnership | Cleveland Clinic and Charité Berlin anchor heart team model adoption requiring manufacturer commitment. |
| Software Companion Development | AI-guided procedural navigation opens value-based reimbursement negotiations with payors. |
| Reimbursement Strategy | PMDA expansion for TAVI procedures concentrates capital expenditure in Tokyo-Osaka clusters. |
Research Methodology
A standing panel of interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA premarket approval filings, EU MDR technical documentation databases, PMDA reimbursement bulletins, and hospital procurement contract records. Bottom-up device shipment analysis triangulates against top-down healthcare expenditure modeling.
Scenario-bracketing around regulatory approval velocity, reimbursement expansion timing, and supply disruption probability bounds value projections across the analysis window. Segmentation dimensions span device type, indication category, end-user facility tier, and delivery mode invasiveness level. CAGRs derive from procedure volume elasticity to demographic aging patterns and capital expenditure cycles for hybrid suite installation. Industry-specific inputs incorporate bioprosthetic tissue durability data and fluoroscopy system replacement rates.
Stress conditions across platinum-iridium supply disruption, EU MDR notified body capacity constraints, and surgical robotics substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement trajectory and regulatory harmonization. Material shifts in FDA breakthrough designation criteria or PMDA coverage expansion timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market