
 Ultrasonic Surgical Cutters Market | 2026-2036
Ultrasonic Surgical Cutters Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Surgical Cutters Market Analytics
Japanese piezoelectric ceramics production is decoupling from general industrial supply chains as medical-grade material specifications tighten. Stryker Corporation leverages captive ceramic sourcing to control transducer quality across its ultrasonic surgical platform. Medtronic PLC anchors its competitive position through R&D intensity in energy-based surgical systems, while Johnson & Johnson (Ethicon) dominates soft-tissue dissection applications with proprietary blade geometries.
Ultrasonic surgical cutters employ high-frequency mechanical vibration, typically at 55.5 kHz, to achieve simultaneous tissue transection and hemostasis through protein denaturation without thermal spread beyond the active blade edge. The technology serves primarily in procedures requiring precision near critical structures such as nerves and vessels. Handheld cutters command the largest revenue share due to surgeon familiarity and instrument versatility across multiple specialties, while disposable tips generate recurring revenue streams that stabilize manufacturer cash flows. Orthopedic surgery represents the fastest-growing application segment as ultrasonic osteotomy displaces conventional saw systems in spine and joint procedures.
FDA 510(k) premarket notification and EU MDR conformity assessment create dual compliance burdens that filter smaller participants from transatlantic markets. Japan's PMDA and China's NMPA impose additional clinical evidence requirements that extend registration timelines for imported devices. Stakeholders must monitor harmonization progress between FDA's Quality System Regulation and ISO 13485:2016 revisions to anticipate streamlined audit structures.
Market Dynamics
Japanese piezoelectric ceramic supply concentration is forcing device manufacturers to secure captive sourcing arrangements or absorb volatile raw material premiums, fundamentally restructuring competitive economics across ultrasonic surgical platforms.
Growth Catalysts
- EU MDR harmonization:Streamlined conformity assessment pathways accelerate transatlantic product launches for manufacturers with established quality management systems under ISO 13485:2016.
- Spine and joint arthroplasty expansion:Ultrasonic osteotomy systems displace conventional saw systems in orthopedic suites across Germany and the United States.
- 55.5 kHz frequency standardization:Industry-wide adoption of this vibration protocol reduces surgeon retraining costs and accelerates instrument interoperability across hospital systems.
Market Restraints
- Piezoelectric ceramic supply concentration:Japanese producers control medical-grade ceramic formulations, exposing device manufacturers to input cost volatility and allocation risk.
- FDA 510(k) documentation burden:Substantial equivalence demonstrations require extensive predicate device analysis, extending premarket timelines for novel blade geometries.
- Electrosurgery substitution threat:Radiofrequency-based vessel sealing systems retain cost advantages in high-volume general surgery applications.
Strategic Opportunities
- China NMPA registration acceleration:Streamlined clinical evidence requirements for Class II devices create faster market entry for ultrasonic platforms in tier-one hospital networks.
- Robotic surgery integration:Convergence of ultrasonic cutting heads with da Vinci and Versius surgical systems opens precision dissection applications in thoracic and urologic specialties.
- India CDSCO pathway expansion:Central Drugs Standard Control Organization priority review for energy-based surgical devices reduces import registration cycles.
Industry Challenges
- Transducer calibration expertise gap:Hospital biomedical engineering departments lack specialized training for 55.5 kHz frequency validation, forcing OEM-dependent service models.
- Dual FDA-EU MDR audit complexity:Divergent quality system inspection schedules create compliance coordination burdens for manufacturers maintaining parallel certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Surgical Cutters Market |
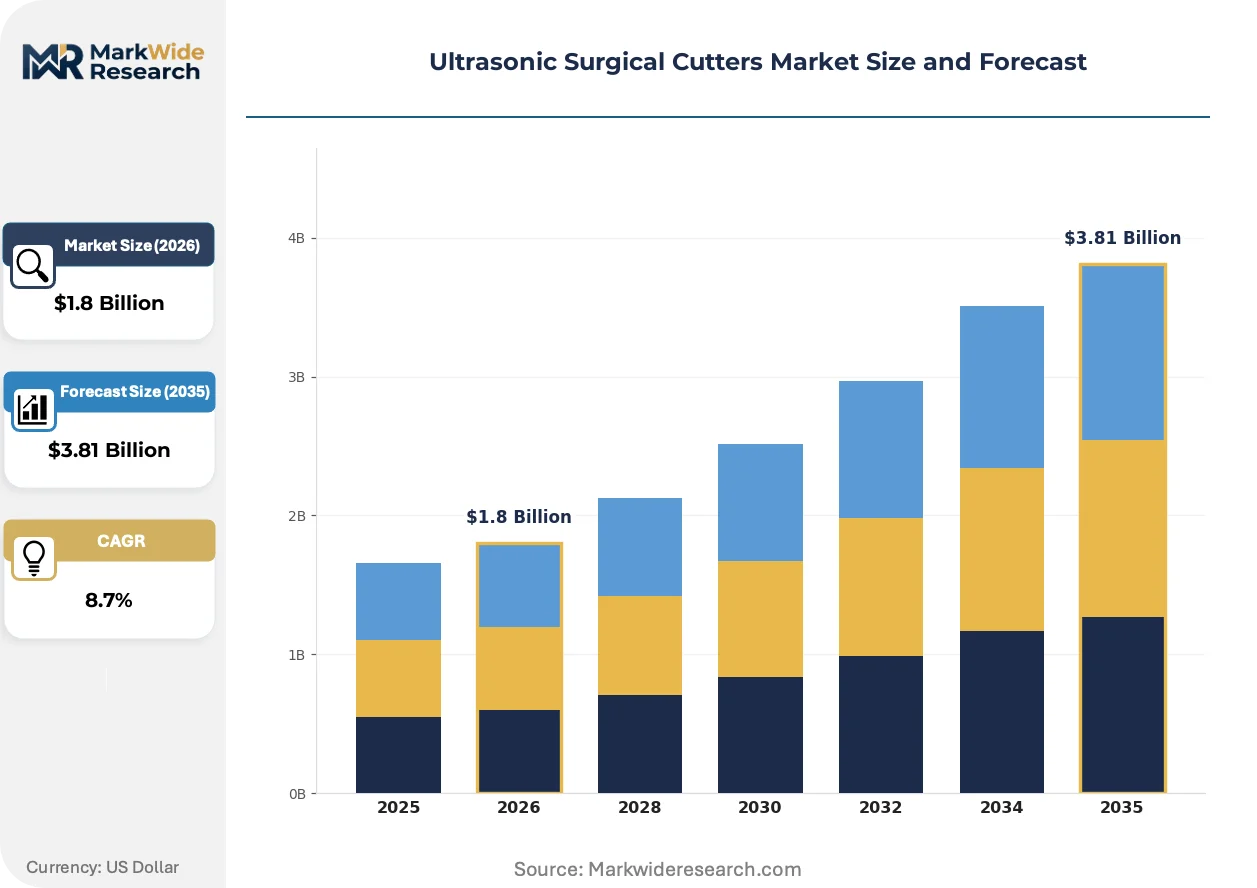
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Cutters, Tabletop Systems, Disposable Tips, Accessories End User: Hospitals, Surgical Centers, Outpatient Facilities, Trauma Centers Technology: Ultrasonic Vibration, Electrosurgery, Plasma Energy, Laser-Assisted Application: Orthopedic Surgery, General Surgery, Cosmetic Surgery, Oncology Surgery |
| Companies Covered | Stryker Corporation, Medtronic PLC, Olympus Corporation, MISONIX Inc, Söring GmbH, Johnson & Johnson (Ethicon), Miconvey SURGICAL, FONA International, BOWA MEDICAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Surgical Cutters Market Evolving Landscape
Active material science breakthroughs and regulatory pathway evolution are compressing product development cycles while elevating performance thresholds for tissue interaction precision.
Single-crystal piezoelectric materials are unifying transducer efficiency and thermal stability in next-generation handheld cutters. Academic medical centers in Germany and the United States are piloting these ceramics in extended-duration oncologic resections. This material transition is unifying previously separate performance tiers into single instrument platforms, collapsing premium-economy segmentation in hospital procurement.
Japan's PMDA revised guidance on energy-based surgical devices now mandates localized thermal damage documentation for novel blade geometries. Manufacturers must submit histopathological evidence from porcine models demonstrating protein denaturation depth profiles. Soft-tissue dissection applications face the steepest compliance ramp, with several US and European submissions delayed for additional biocompatibility testing.
Hospital purchasing consortia are consolidating ultrasonic cutter procurement through single-source agreements with comprehensive service bundling. Independent distributors in secondary US markets are losing access to IDN contracts as direct manufacturer relationships dominate capital equipment placement. This channel compression is most visible in the southeastern United States, where hospital system mergers have reduced viable supplier touchpoints by half.
Ultrasonic Surgical Cutters Market Segmentation
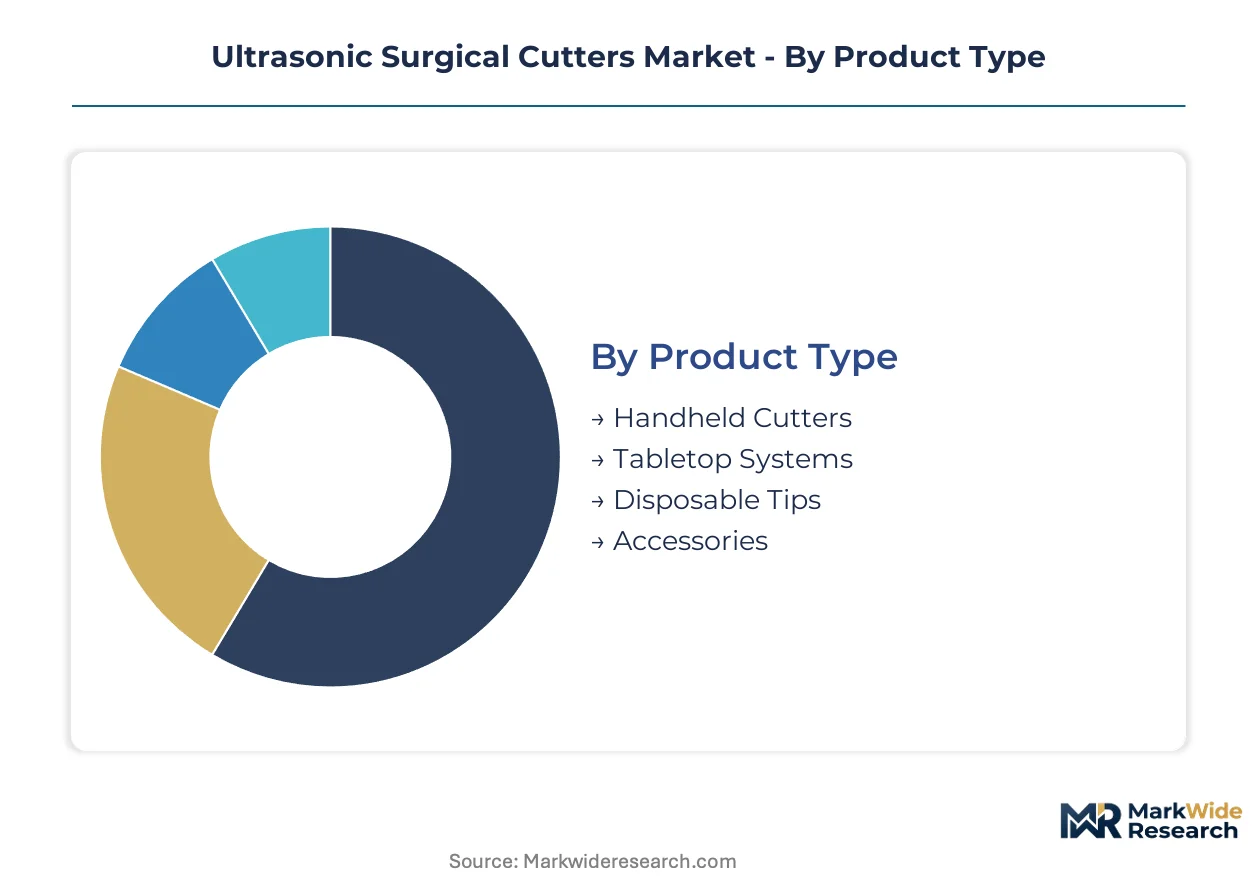
Ultrasonic surgical cutter procurement varies sharply across facility types and procedure volumes. Product specifications, service bundling, and regulatory pathways diverge meaningfully between high-throughput hospital systems and specialized surgical centers.
Product Type:
Japanese ceramic supply concentration is forcing manufacturers to prioritize instrument designs that minimize transducer wear and extend service intervals.
- Handheld Cutters:Surgeon familiarity drives procurement in general surgery suites across the United States and Germany. These instruments command placement through versatility across laparoscopic and open procedures, though disposable tip attachment mechanisms vary by OEM and complicate standardization efforts.
- Disposable Tips:Recurring revenue streams stabilize manufacturer cash flows in hospital systems with high annual procedure volumes. German orthopedic suites are consolidating procurement through single-source agreements that bundle tip supply with preventive maintenance contracts.
- Tabletop Systems:Capital equipment placement concentrates in tier-one hospital networks with dedicated biomedical engineering support.
- Accessories:Sterile sheaths and irrigation adapters represent attach revenue with lower margin profiles.
Today's leader: Handheld Cutters. Tomorrow's challenger: Disposable Tips.
End User:
Facility reimbursement frameworks and procedure mix determine capital equipment acquisition cycles and service contract structures.
- Hospitals:Large installed bases of surgical infrastructure in the United States, Germany, and China support capital equipment procurement through bundled payment models. IDN consolidation in the southeastern United States is reducing viable supplier touchpoints and compressing distributor margins.
- Surgical Centers:Freestanding facilities in Germany are adopting tabletop ultrasonic systems for outpatient orthopedic procedures. Limited biomedical engineering staff forces reliance on OEM-dependent service models for transducer calibration.
- Outpatient Facilities:Lower procedure volumes favor rental or lease arrangements over capital purchase.
- Trauma Centers:Emergency procedure unpredictability requires instrument versatility across multiple surgical specialties.
Procurement gravity sits with Hospitals. Volume expansion is climbing the fastest in Surgical Centers.
Technology:
Energy modality selection hinges on tissue interaction precision requirements and thermal spread tolerance near critical anatomical structures.
- Ultrasonic Vibration:55.5 kHz frequency standardization reduces surgeon retraining costs across hospital systems. Protein denattration without thermal spread beyond the active blade edge serves procedures near nerves and vessels in academic medical centers.
- Electrosurgery:Radiofrequency-based vessel sealing retains cost advantages in high-volume general surgery applications across United States community hospitals.
- Plasma Energy:Lower thermal footprint applications in thoracic specialties remain niche.
- Laser-Assisted:Precision requirements in cosmetic and ophthalmic procedures drive limited adoption.
Ultrasonic Vibration anchors clinical preference. Electrosurgery defends on cost.
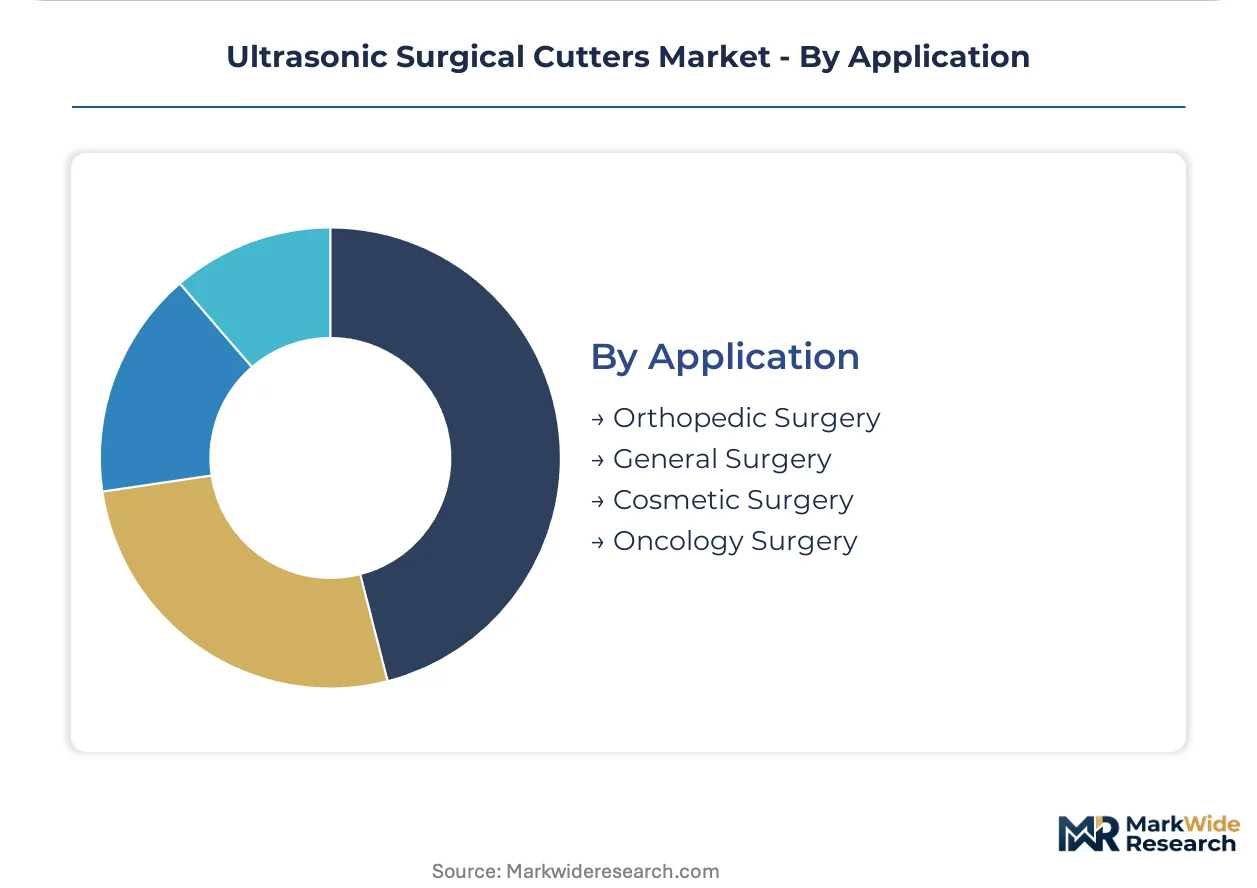
Application:
Procedure-specific tissue characteristics and bone density requirements determine blade geometry and vibration amplitude specifications.
- Orthopedic Surgery:Ultrasonic osteotomy is displacing conventional saw systems in spine and joint procedures across German and United States orthopedic suites. Extended resection durations in oncologic cases are piloting single-crystal piezoelectric materials for thermal stability.
- General Surgery:Soft-tissue dissection applications face steep compliance ramps under Japan's PMDA revised guidance mandating localized thermal damage documentation.
- Cosmetic Surgery:Precision requirements near facial nerve structures favor ultrasonic platforms over electrosurgery.
- Oncology Surgery:Extended-duration resections demand transducer efficiency and thermal management.
Orthopedic Surgery is gaining share fastest. General Surgery carries the heaviest regulatory documentation burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in procurement intensity, with German orthopedic suites consolidating through single-source agreements while US hospital networks fragment across competing IDN structures. Japan's ceramic supply concentration creates input dependencies that reshape competitive economics in both markets. China's NMPA pathway evolution and India's CDSCO priority review are compressing registration timelines for energy-based surgical devices.
United States
Hospital system mergers across the southeastern United States have halved viable supplier touchpoints for ultrasonic surgical platforms. FDA 510(k) premarket notification requirements impose substantial equivalence documentation burdens that filter smaller participants from transatlantic markets. The Greater Boston corridor anchors academic medical center adoption of single-crystal piezoelectric materials in extended-duration oncologic resections.
Germany
Orthopedic suites in Bavaria and North Rhine-Westphalia are displacing conventional saw systems with ultrasonic osteotomy platforms through bundled preventive maintenance contracts. EU MDR conformity assessment harmonization accelerates product launches for manufacturers with ISO 13485:2016 quality management systems. The Baden-Württemberg medical technology cluster concentrates tabletop system manufacturing for outpatient surgical centers.
China
Tier-one hospital networks in Shanghai and Beijing are accelerating capital equipment procurement through streamlined NMPA Class II device pathways. The country's national pharmaceutical regulator has reduced clinical evidence requirements for ultrasonic surgical platforms with established predicate devices. The Yangtze River Delta anchors domestic manufacturing of handheld cutter systems for regional distribution.
Japan
PMDA revised guidance on energy-based surgical devices now mandates localized thermal damage documentation for novel blade geometries, delaying several US and European submissions. METI industrial policy supports medical-grade piezoelectric ceramic production decoupling from general industrial supply chains. The Kanto region around Tokyo concentrates transducer manufacturing with tightened material specifications.
India
Central Drugs Standard Control Organization priority review for energy-based surgical devices reduces import registration cycles for ultrasonic platforms. Maharashtra and Karnataka surgical centers are adopting tabletop systems for outpatient orthopedic procedures through lease arrangements. Delhi-NCR academic hospitals pilot robotic surgery integration with ultrasonic cutting heads in thoracic specialties.
Ultrasonic Surgical Cutters Market Competitive Landscape
Japanese producers anchor one tier in ceramic supply; German and US device manufacturers hold system integration positions. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with captive material sourcing, specialized energy-based surgical system developers, and regional tabletop equipment fabricators. Competitive moves center on backward integration into piezoelectric ceramic supply and robotic surgery platform partnerships.
Among diversified medtech conglomerates, Stryker Corporation and Medtronic PLC exemplify the captive sourcing archetype through control over transducer quality and R&D intensity in energy-based platforms. Johnson & Johnson (Ethicon) occupies a position within soft-tissue dissection specialization. Olympus Corporation and Söring GmbH represent the precision instrument manufacturing tier, with the latter's German corporate structure signaling European engineering heritage. These named entities serve as anchors for understanding how competitive positioning stratifies across material control, clinical application focus, and geographic manufacturing concentration.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic PLC |
| Olympus Corporation |
| MISONIX Inc |
| Söring GmbH |
| Johnson & Johnson (Ethicon) |
| Miconvey SURGICAL |
| FONA International |
| BOWA MEDICAL |
| Others |
Value Network & Pricing Analysis
Medical-grade barium titanate powder indices from Japanese suppliers cascade through ultrasonic surgical cutter manufacturing into three distinct pricing tiers: premium single-crystal systems for academic medical centers, standard handheld platforms for hospital IDNs, and economy tabletop configurations for outpatient surgical centers.
Pricing Analysis
Distributor margins in secondary US markets are compressing as hospital system mergers consolidate procurement through direct manufacturer relationships. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and ISO 13485 certification tier rather than base hardware cost. Pricing pressure stems from electrosurgery substitution in high-volume general surgery applications. Outpatient surgical centers exhibit highest price sensitivity due to capital constraints, while German orthopedic suites prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Single-source vulnerability sits with Japanese producers of medical-grade piezoelectric ceramics, particularly in the Kanto region around Tokyo. Manufacturing draws from Japan for ceramic formulations, Germany for precision machining of blade geometries, and China for handheld cutter assembly. Tariff exposure on ceramic imports threatens margin stability for device manufacturers without captive sourcing. Distribution runs through hospital purchasing consortia in the United States and specialized surgical equipment distributors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ultrasonic surgical cutters rests on ceramic supply security and premium-tier migration toward single-crystal transducer platforms.
For Market Incumbents: To counter electrosurgery substitution in general surgery, deepen backward integration into Japanese ceramic supply chains or secure long-term offtake agreements with METI-supported producers. Prioritize R&D investment in robotic surgery integration to defend positioning in thoracic and urologic specialties where precision requirements favor ultrasonic platforms. For New Entrants and Emerging Players: Enter via India's CDSCO priority review pathway for energy-based surgical devices, targeting Maharashtra and Karnataka surgical centers with tabletop system lease arrangements. White-space opportunity concentrates in tier-two Chinese hospital networks where NMPA Class II pathway streamlines registration for established predicate devices. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized energy-based surgical system developers possessing proprietary blade geometries and PMDA thermal damage documentation capabilities. Long-term viability hinges on regulatory approval velocity rather than manufacturing scale. Monitor FDA 510(k) substantial equivalence determination timelines for novel single-crystal platforms as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ceramic Sourcing Arrangement | Stryker's control over transducer quality insulates margins from Japanese supply volatility. |
| Robotic Surgery Platform Partnership | Integration with da Vinci systems opens precision applications in thoracic specialties. |
| NMPA Class II Registration Acceleration | Streamlined clinical evidence requirements compress market entry timelines in Shanghai and Beijing. |
| Single-Crystal Piezoelectric Material Transition | Academic medical centers in Germany pilot extended-duration oncologic resections with thermal stability gains. |
| Hospital IDN Direct Contracting | Southeastern US system mergers halve distributor touchpoints and stabilize recurring revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at device manufacturers with secondary validation against FDA 510(k) filings, EU MDR conformity assessment databases, NMPA registration records, and hospital procurement contract repositories. Bottom-up procedure volume modeling and top-down equipment replacement cycle analysis provided cross-verification.
Segment-weighting applied product type, end user facility tier, application specialty, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from instrument placement velocity, disposable tip attach rates, and service contract renewal patterns. Forecast inputs incorporated PMDA thermal damage documentation timelines and EU MDR harmonization progress for quality system audit streamlining.
Inputs from hospital procurement databases and ceramic supply chain disclosures were available through the study window; gaps in real-time distributor margin data introduce uncertainty bands around pricing tier boundaries. Forecasts reflect documented assumptions on regulatory pathway velocity and substitution elasticity between ultrasonic and radiofrequency platforms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market