
 Skin Graft Blades Market | 2026-2036
Skin Graft Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Graft Blades Market Outlook
Modular blade-cartridge systems is shifting how procurement teams evaluate total cost of ownership in skin graft procedures. De Soutter Medical leverages in-house production of precision cutting assemblies to control supply quality. Integra LifeSciences anchors its position through deep specialization in regenerative wound care portfolios. Swann-Morton competes on manufacturing scale across carbon and stainless steel blade formats.
Skin graft blades are precision cutting instruments engineered from high-grade stainless steel or carbon steel with defined bevel angles, typically deployed via manual handles or powered dermatomes to harvest uniform split-thickness skin sections for transplantation. Dermatomes command the largest installed base among product types due to their integration into hospital operating theater workflows. Stainless steel dominates material selection for reusable instruments, while composite materials represent the fastest-growing category as facilities seek lighter autoclavable alternatives. Ambulatory surgical centers now constitute the most rapidly expanding end-user channel, though hospitals retain the deepest margin pools through bundled procurement contracts.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for blade manufacturers. ISO 13485 quality management standards further constrain supplier qualification, particularly for direct sales into health system networks. Stakeholders must monitor evolving sterilization validation protocols and reimbursement shifts toward outpatient burn care to align portfolio investments with procurement decision criteria.
Market Dynamics
Precision dermatome manufacturers face mounting pressure from FDA and EU MDR sterilization validation requirements that are compressing product development timelines while expanding compliance costs across the supply chain.
Growth Catalysts
- Burn center infrastructure expansion:Specialized wound care units in the United States, Germany, and China are scaling procurement of powered dermatomes to handle rising trauma caseloads.
- Single-use instrument mandates:EU MDR technical documentation requirements for surgical blades are accelerating hospital transitions toward disposable cartridge systems.
- Autoclavable composite materials:Carbon-fiber reinforced polymers are displacing traditional stainless steel in ambulatory surgical centers seeking lighter instrument portfolios.
Market Restraints
- High-grade steel input volatility:Surgical-grade stainless steel pricing fluctuations constrain margin stability for reusable instrument manufacturers.
- Supply concentration in Sheffield:Carbon steel blade production clusters in a single UK manufacturing hub, creating geographic vulnerability.
- 510(k) pathway friction:FDA clearance timelines for novel blade geometries extend 12-18 months, delaying market entry.
Strategic Opportunities
- Underpenetrated outpatient burn care:Freestanding wound clinics in India and Brazil lack precision dermatomes, creating equipment import demand.
- Modular cartridge standardization:Cross-manufacturer blade-handle compatibility is converging with hospital group purchasing organization consolidation.
- Reimbursement tailwinds:US CMS outpatient procedure coding expansions for skin grafting are shifting procedure volume from inpatient settings.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management system certifiers are concentrated in Western Europe, delaying supplier qualification in Asia-Pacific.
- Legacy instrument refurbishment:Hospital capital constraints extend powered dermatome replacement cycles, compressing new equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Graft Blades Market |
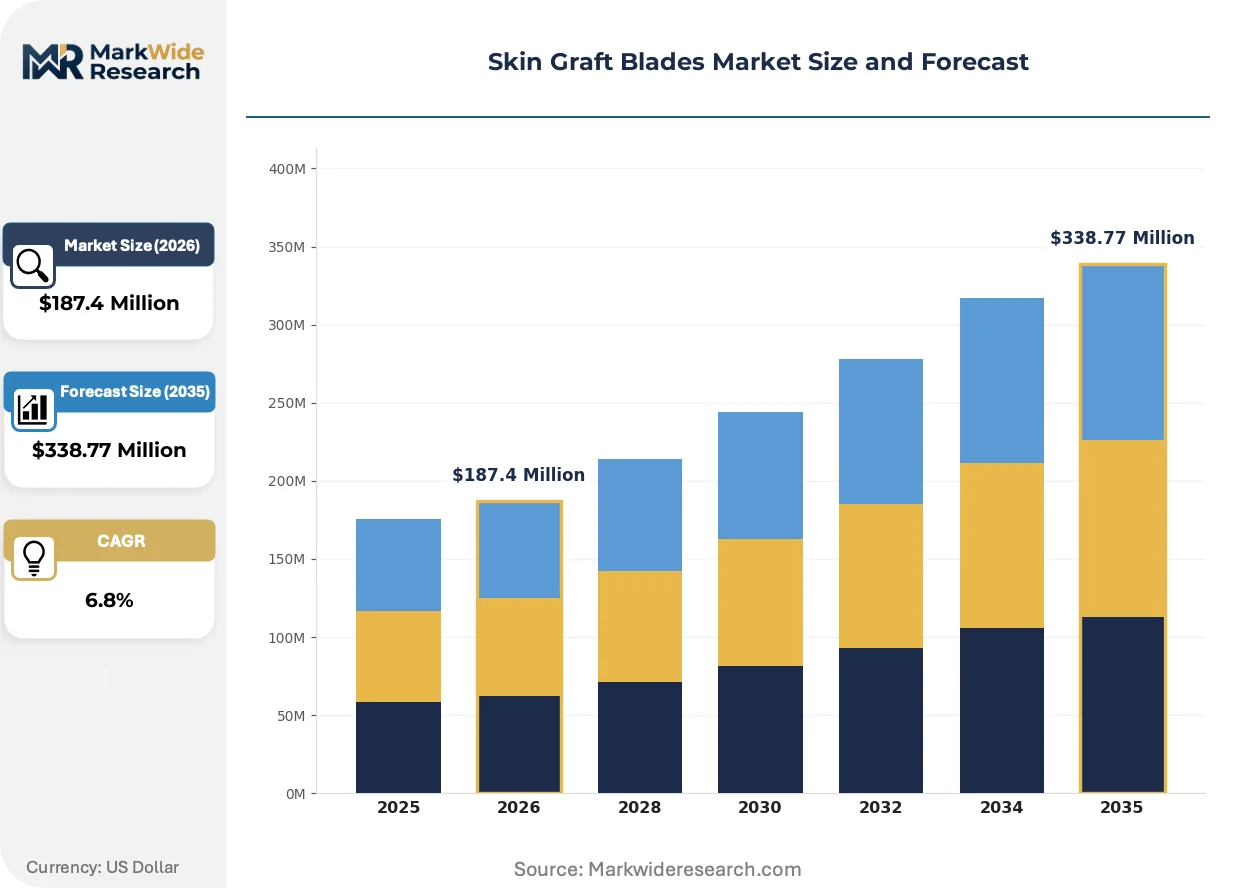
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dermatome, Surgical Blades, Tissue Grafting Instruments, Microneedles Material: Stainless Steel, Carbon Steel, Plastic, Composite Materials End User: Hospitals, Ambulatory Surgical Centers, Dermatology Clinics, Research Laboratories Distribution Channel: Direct Sales, Online Sales, Medical Supply Distributors, Retail Pharmacies |
| Companies Covered | De Soutter Medical, NOUVAG AG, Aygün Surgical Instrument, Zimmer Biomet, Integra LifeSciences, Humeca, Swann-Morton, Exsurco Medical, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Graft Blades Market Strategic Shifts
Electrosurgical integration and disposable cartridge architectures are redefining how procurement teams evaluate total cost of ownership across skin graft workflows.
Ultrasonic dermatomes is converging with robotic positioning systems in academic medical centers. Burn reconstruction units at Massachusetts General and Charité Berlin are piloting these platforms for sub-millimeter depth control. The technology is converging with value-based care metrics by reducing graft failure rates and revision procedures.
EU MDR Annex I general safety and performance requirements are forcing blade manufacturers to revalidate biological safety documentation for all stainless steel grades. Technical file preparation costs have doubled for small and mid-sized suppliers. German and Swiss manufacturers are absorbing these expenses through direct hospital contracting rather than distributor networks.
Hospital group purchasing organizations are consolidating blade procurement across IDN networks. Premier and Vizient in the United States are bundling dermatome capital equipment with multi-year blade supply commitments. This concentration is most visible in the US Southeast, where HCA and Tenet systems are standardizing on single-source agreements.
Skin Graft Blades Market Segmentation
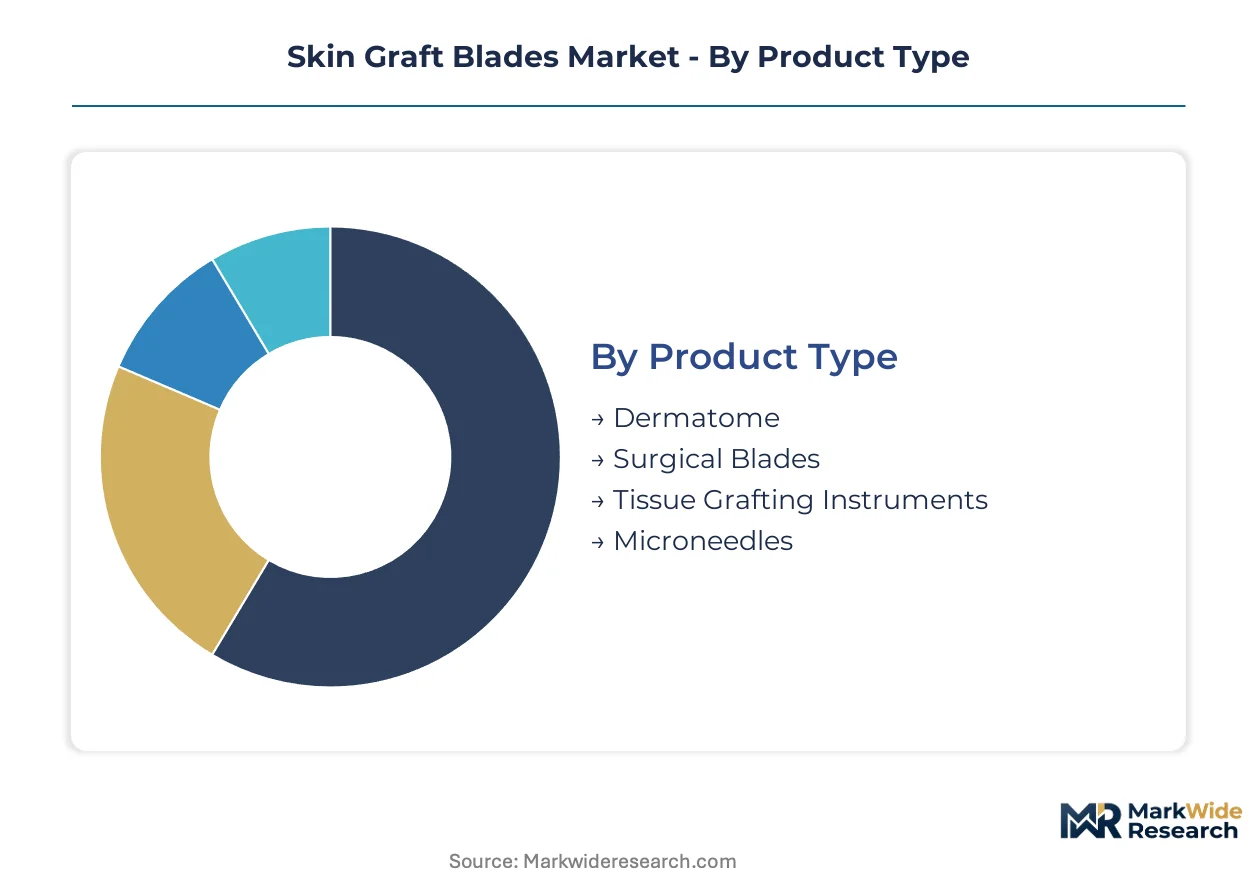
Segmentation in skin graft blades reveals how procurement criteria diverge across surgical settings. Material specifications, sterilization protocols, and workflow integration determine supplier selection and pricing power within each category.
Product Type:
Blade geometry and power integration define the technical axis for surgical teams selecting harvest instruments.
- Dermatome:Powered or manual instruments with oscillating blades engineered for precise split-thickness skin harvesting. Demand concentrates in United States burn centers and German trauma units scaling procurement for rising trauma caseloads, driven by bundled capital equipment contracts.
- Surgical Blades:Handheld precision cutting tools with defined bevel angles for manual graft preparation. Procurement is accelerating in ambulatory surgical centers across China as outpatient wound care infrastructure expands.
- Tissue Grafting Instruments:Specialized forceps and spreaders for graft placement and fixation.
- Microneedles:Fine-gauge instruments for micrografting procedures in reconstructive applications.
Mature deployment sits with dermatomes in hospital operating theaters. Newer deployment is concentrated in surgical blades for freestanding wound clinics.
Material:
Cost tiers separate reusable instrument portfolios from single-use disposable systems.
- Stainless Steel:Surgical-grade austenitic alloys offering corrosion resistance and repeated autoclave cycles. Hospitals in Germany and Switzerland retain deep procurement commitments to reusable stainless portfolios despite higher upfront capital outlay.
- Composite Materials:Carbon-fiber reinforced polymers delivering weight reduction and thermal stability. Ambulatory surgical centers in the United States are adopting these for lighter instrument trays and faster turnover workflows.
- Carbon Steel:High-carbon alloys prized for edge retention in disposable blade formats.
- Plastic:Polymer-based single-use alternatives for low-complexity grafting procedures.
Volume concentration favors stainless steel in academic medical centers. Steepest expansion trajectory belongs to composite materials in outpatient settings.
End User:
Customer type dictates sterilization protocol requirements and capital expenditure authorization levels.
- Hospitals:Integrated delivery networks with centralized procurement of powered dermatomes and multi-year blade supply agreements. Margin pools remain deepest here through bundled contracts with group purchasing organizations.
- Ambulatory Surgical Centers:Freestanding facilities prioritizing disposable cartridge systems and lighter instrument portfolios. These centers are expanding most quickly in United States outpatient markets following CMS procedure coding expansions.
- Dermatology Clinics:Specialized practices focusing on cosmetic and reconstructive micrografting.
- Research Laboratories:Academic and commercial R&D settings requiring precision instruments for tissue engineering protocols.
Procurement authority centralizes with hospital materials management departments. Decentralized purchasing is accelerating in ambulatory surgical centers.
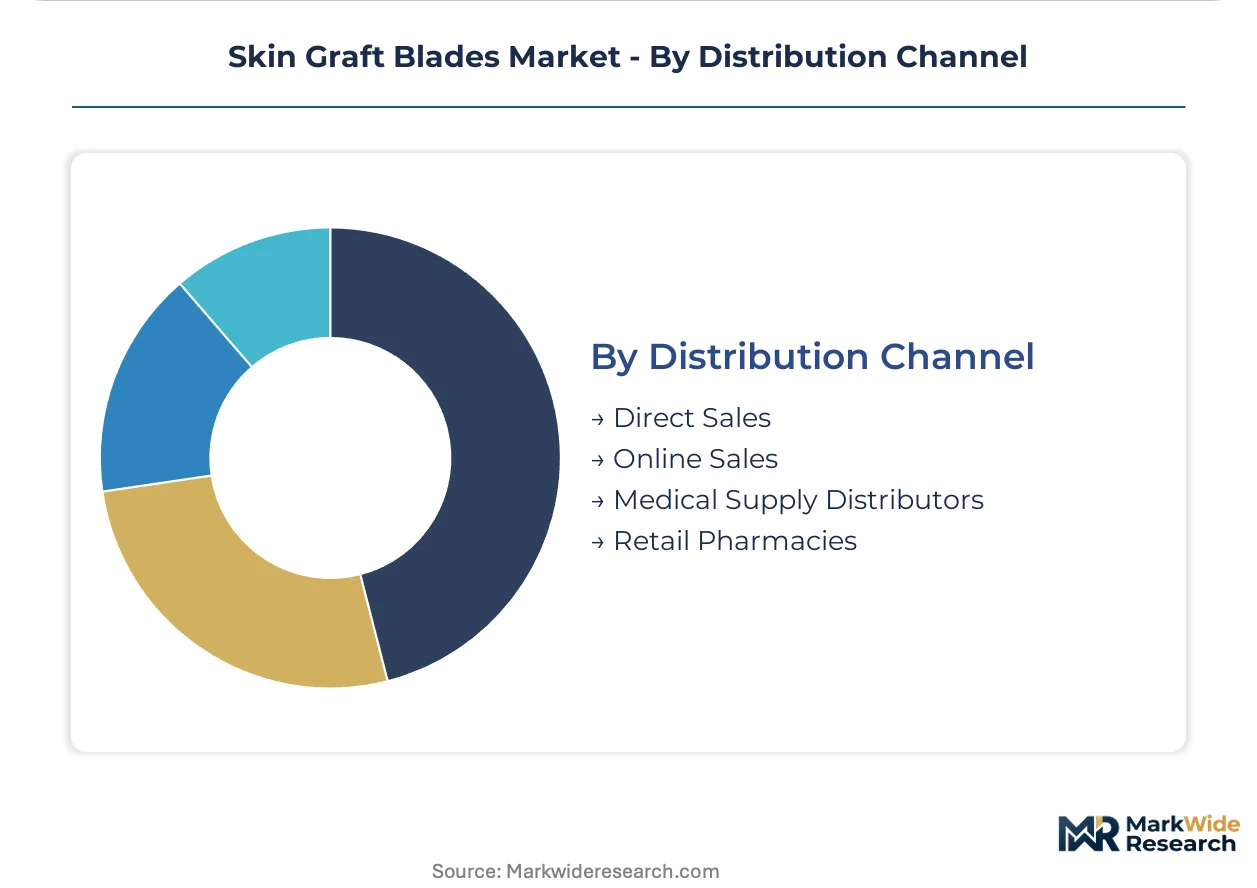
Distribution Channel:
Supply chain configuration determines compliance documentation access and total landed cost.
- Direct Sales:Manufacturer-to-hospital relationships enabling technical file transfer for EU MDR compliance. German and Swiss suppliers are absorbing documentation costs through direct contracting rather than distributor networks.
- Medical Supply Distributors:Regional wholesalers with ISO 13485 certification handling sterile instrument logistics. These intermediaries dominate procurement in mid-tier United States health systems.
- Online Sales:E-commerce platforms serving small dermatology practices and research laboratories.
- Retail Pharmacies:Limited channel for basic surgical blade replenishment in select markets.
Relationship-based contracting sits with direct sales in tier-one hospitals. Transactional procurement is concentrating in online sales for smaller end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and Germany's medical technology clusters concentrate precision instrument manufacturing. These zones attract producers through tax incentives and streamlined regulatory pathways. Demand for dermatome systems concentrates in trauma centers within these manufacturing hubs.
United States
Burn center infrastructure expansion in Texas and California drives procurement of powered dermatomes. FDA 510(k) clearance timelines for novel blade geometries extend market entry for new suppliers. Massachusetts General Hospital in Boston pilots ultrasonic dermatome platforms with robotic positioning systems for sub-millimeter depth control.
Germany
EU MDR Annex I compliance requirements force revalidation of biological safety documentation for stainless steel grades. Charité Berlin operates advanced burn reconstruction units adopting precision harvesting technologies. The Sheffield carbon steel cluster supplies blade materials despite geographic concentration risks.
China
NMPA regulatory harmonization accelerates domestic production of autoclavable composite instruments. Yangtze River Delta special economic zones host expanding wound care equipment manufacturing. Shanghai and Beijing trauma centers scale procurement for rising burn caseloads.
India
Freestanding wound clinics in Maharashtra and Karnataka lack precision dermatomes, creating equipment import demand. CDSCO medical device regulations require technical documentation alignment with international standards. Mumbai hospital networks expand specialized burn units through public-private partnerships.
Brazil
Underpenetrated outpatient burn care in São Paulo and Rio de Janeiro states generates demand for surgical blade imports. ANVISA medical device registration pathways constrain market entry timelines for foreign suppliers. Southeast regional health systems lack capital equipment for advanced grafting procedures.
Skin Graft Blades Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the skin graft blades market. Tier-one suppliers leverage bundled procurement contracts with integrated delivery networks. Three strategic archetypes dominate: diversified medical technology conglomerates with wound care portfolios, precision instrument specialists with in-house blade manufacturing, and regional scale manufacturers serving distributor networks. Competitive moves concentrate on direct hospital contracting to absorb compliance documentation costs and modular cartridge standardization to capture group purchasing organization consolidation.
Within the precision instrument specialist tier, De Soutter Medical and NOUVAG AG exemplify European manufacturers with captive production of cutting assemblies. Zimmer Biomet represents the diversified conglomerate archetype with broad orthopedic and wound care portfolios. Among blade-scale manufacturers, Swann-Morton occupies a position reflecting Sheffield-based carbon and stainless steel production capabilities. These named entities anchor the competitive structure without exhausting the supplier base, which includes additional specialized instrument fabricators and regional distributors holding ISO 13485 certifications for sterile logistics.
| Leading Market Players |
|---|
| De Soutter Medical |
| NOUVAG AG |
| Aygün Surgical Instrument |
| Zimmer Biomet |
| Integra LifeSciences |
| Humeca |
| Swann-Morton |
| Exsurco Medical |
| B. Braun SE |
| Others |
Value Chain & Pricing Dynamics
Hospital group purchasing organization consolidation across United States integrated delivery networks is compressing supplier margins and forcing blade manufacturers toward direct contracting models that absorb EU MDR documentation costs. This procurement concentration shifts pricing power toward buyers with multi-year bundled agreements while squeezing smaller distributors unable to match compliance investment scale.
Pricing Analysis
Expedited lead time premiums dominate transaction pricing for burn centers facing trauma caseload surges, with spot inventory discounts appearing only for standard blade geometries in distributor-held stock. Three-tier pricing structure across premium robotic-integrated systems, standard powered dermatomes, and economy manual handles separates buyers by capital authorization level. Cost compression in stainless steel reusable instruments is intensifying because of surgical-grade alloy input volatility. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Surgical-grade stainless steel supply rests on German and Swiss specialty metallurgy producers, with carbon steel blade fabrication anchored in Sheffield's concentrated UK manufacturing hub. High-carbon alloys, austenitic stainless grades, and carbon-fiber reinforced polymers constitute the core input dependencies. Single-source vulnerability in Sheffield creates geographic concentration risk for disposable blade formats. Distribution runs through ISO 13485-certified medical supply distributors serving mid-tier health systems, with direct sales channels penetrating tier-one hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 auditor scarcity constrains supplier qualification velocity, propping pricing for certified manufacturers able to accelerate hospital onboarding timelines. This capacity bottleneck rewards early compliance investment.
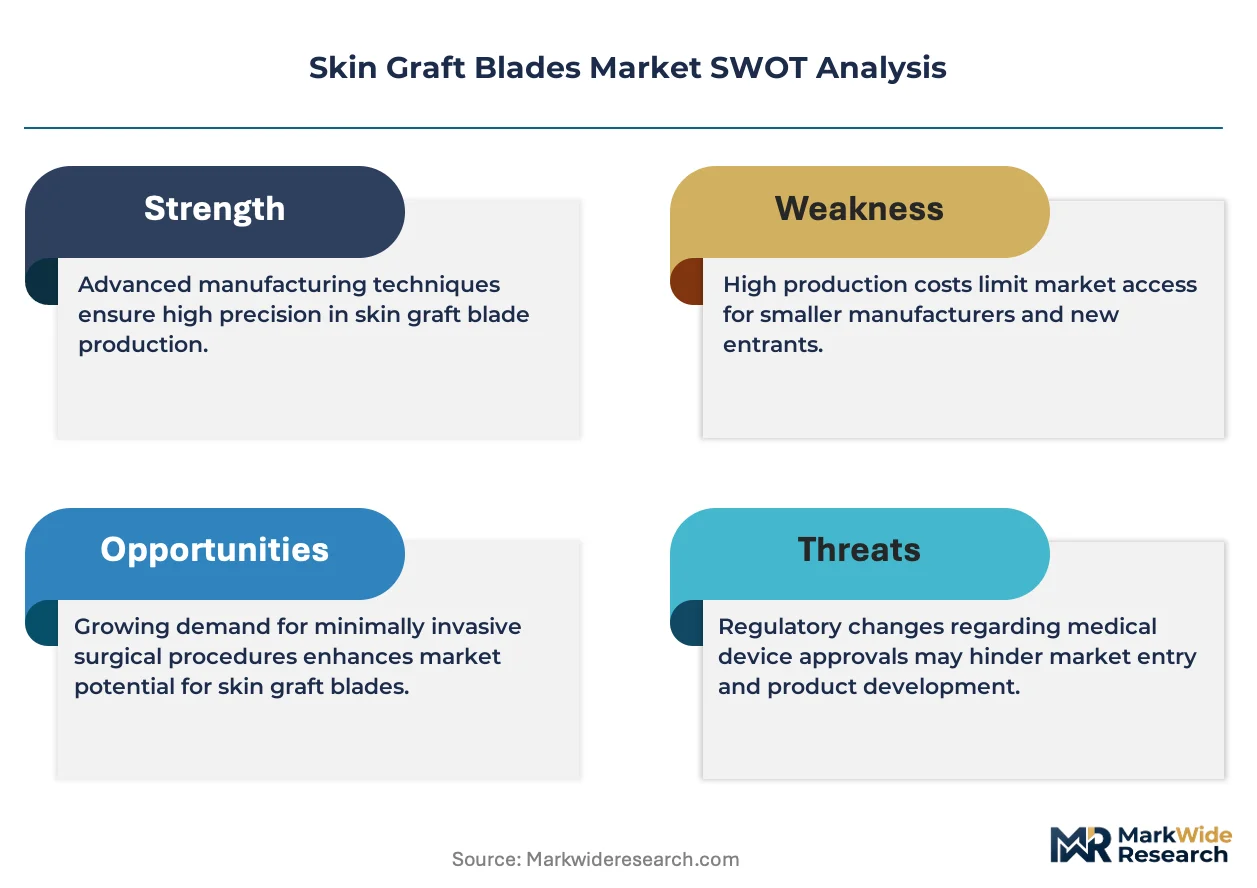
For Market Incumbents: Cement market position through captive production of precision cutting assemblies and backward integration into surgical-grade steel sourcing. Absorb EU MDR technical file preparation costs through direct hospital contracting rather than distributor markups. Threat of modular cartridge standardization demands channel control investment to preserve bundled procurement relationships. For New Entrants and Emerging Players: Launch via online sales platforms targeting research laboratories and small dermatology practices underserved by relationship-based direct sales forces. Freestanding wound clinics in India and Brazil represent the most penetrable geography lacking precision dermatome infrastructure. Reimbursement tailwinds from CMS outpatient procedure coding expansions offer a specific go-to-market angle for disposable cartridge systems. For Investors and Strategic Acquirers: The window for entry favors precision instrument specialists with in-house blade manufacturing and established ISO 13485 quality management systems. Long-term viability hinges on consolidation plays capturing hospital group purchasing organization standardization waves. Watch NMPA regulatory harmonization progress in China as the signal indicating when domestic production scale will displace import-dependent supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Preparation | Direct hospital contracting absorbs doubled documentation costs for German and Swiss manufacturers. |
| Modular Cartridge Standardization | Cross-manufacturer blade-handle compatibility captures Premier and Vizient bundling consolidation. |
| Autoclavable Composite Material Scale-Up | Carbon-fiber reinforced polymer production serves ambulatory surgical center weight-reduction demand. |
| Sheffield Carbon Steel Supply Security | Geographic diversification mitigates single-hub vulnerability for disposable blade formats. |
| Ultrasonic Dermatome Platform Development | Robotic positioning integration targets Massachusetts General and Charité Berlin pilot adoption. |
Study Parameters
FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records formed the secondary backbone of this analysis. Primary interviews with burn center directors, biomedical engineering leads, group purchasing organization contracts managers, and sterile processing department heads complemented secondary validation. Bottom-up and top-down triangulation cross-referenced instrument shipment data with procedure volume estimates from CMS and trauma registry sources.
Bottom-up modeling built from product-level pricing and volume assumptions across dermatome, surgical blade, and tissue grafting instrument categories, while top-down approaches validated aggregate market scale against health system capital expenditure surveys. Segmentation dimensions included product type, material grade, end-user facility class, and distribution channel structure. CAGRs were derived from procedure volume growth trajectories and equipment replacement cycle analysis, with reimbursement coding shifts and sterilization protocol changes serving as key forecast inputs across the projection horizon.
Regulatory timeline delays, steel input cost volatility, and hospital capital constraint extensions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about EU MDR implementation pace and outpatient procedure migration velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Surgical Broaches Market