
 Surgical Incision Closure Devices Market | 2026-2036
Surgical Incision Closure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Incision Closure Devices Market Analytics
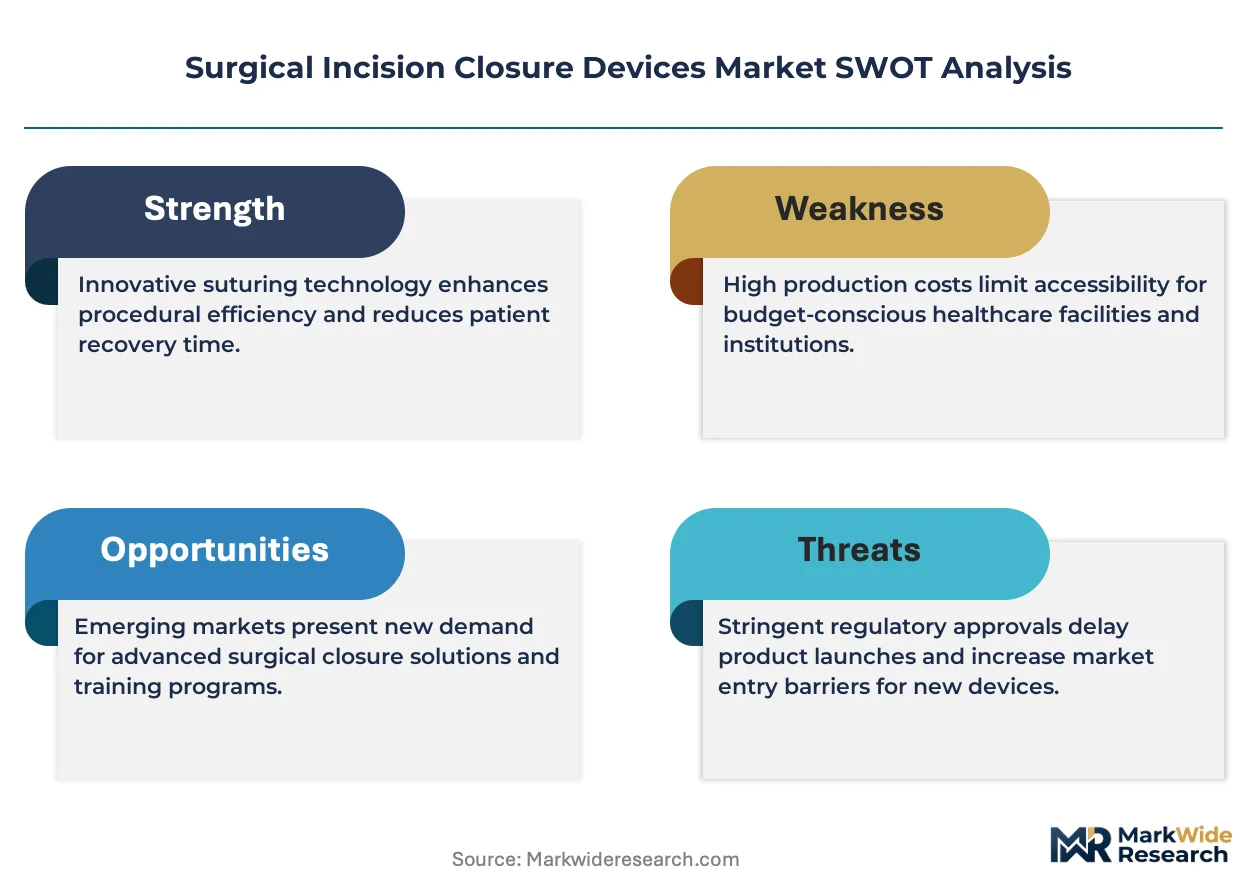
Multi-source procurement for advanced biomaterials is broadening as hospital systems reduce dependency on single-vendor suture contracts. B. Braun Melsungen AG leverages its European manufacturing footprint to sustain cost-competitive sterile thread production. Medtronic anchors North American supply chains through dedicated distribution centers serving integrated delivery networks. Smith & Nephew differentiates in the adhesives sub-category with proprietary cyanoacrylate formulations targeting outpatient settings.
Surgical incision closure devices encompass mechanical, chemical, and biological systems engineered to approximate wound edges, restore tissue integrity, and enable hemostasis following operative procedures; absorbable polyglactin sutures typically degrade through hydrolysis within 56 to 70 days, eliminating foreign body retention. These devices serve the fundamental clinical purpose of reducing surgical site infection risk while optimizing cosmetic outcomes across inpatient and ambulatory contexts. Sutures retain the largest installed base due to decades of surgeon familiarity and universal reimbursement coverage, though adhesives represent the fastest-expanding margin pool as outpatient procedural volumes rise. Biomaterials command premium positioning in cardiothoracic applications where tensile strength requirements exceed synthetic polymer capabilities.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern commercial entry, with the former mandating substantial equivalence demonstrations that elongate development timelines for novel bioengineered formats. The EU Medical Device Regulation intensifies clinical evidence requirements for absorbable staples, redirecting R&D investment toward predicate-device leverage strategies. Stakeholders must monitor evolving cybersecurity addenda to FDA guidance documents, as wireless-enabled smart staplers trigger software validation obligations previously confined to diagnostic equipment categories.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously mandating cybersecurity compliance for connected closure devices, forcing manufacturers to absorb validation costs without commensurate pricing power.
Growth Catalysts
- EU MDR clinical evidence pathways:Absorbable staple manufacturers now leverage predicate-device strategies to accelerate clearance, redirecting R&D toward incremental format improvements rather than novel biomaterial development.
- Ambulatory surgical center expansion:Outpatient procedural volumes in the United States are pulling demand toward single-use adhesive systems that eliminate suture removal visits and reduce nursing labor.
- Smart stapler connectivity:Wireless-enabled devices with embedded usage tracking are capturing preference among integrated delivery networks seeking utilization analytics for value-based contracting.
Market Restraints
- Polymer feedstock volatility:Absorbable suture production depends on glycolide and lactide monomer supplies concentrated in Chinese petrochemical corridors, exposing B. Braun and Ethicon to input cost swings.
- FDA cybersecurity validation:Software-enabled closure devices now require documentation previously confined to diagnostic equipment, extending 510(k) timelines by 8-14 months for first-time filers.
- Biological sealant substitution:Fibrin glue formulations from Baxter and CSL Behring are capturing cardiothoracic cases where synthetic adhesives lack tensile strength, eroding premium suture positioning.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are enabling cost-competitive sterile thread production for export to African and Southeast Asian markets.
- Japan's aging surgical workforce:Prefabricated stapler cartridges with automated tissue sensing are reducing technical variance as experienced surgeons retire from active practice.
- Telehealth-integrated wound monitoring:Post-discharge adhesive patches with embedded biosensors are creating recurring revenue streams through remote surgical site surveillance contracts.
Industry Challenges
- Bioengineer talent scarcity:Formulation chemists with absorbable polymer expertise are concentrated in Basel and Boston corridors, forcing manufacturers to relocate R&D or pay 40-60% salary premiums.
- Legacy ERP integration:Smart stapler data streams require hospital IT departments to reconfigure HL7 interfaces, delaying pilot deployments by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Incision Closure Devices Market |
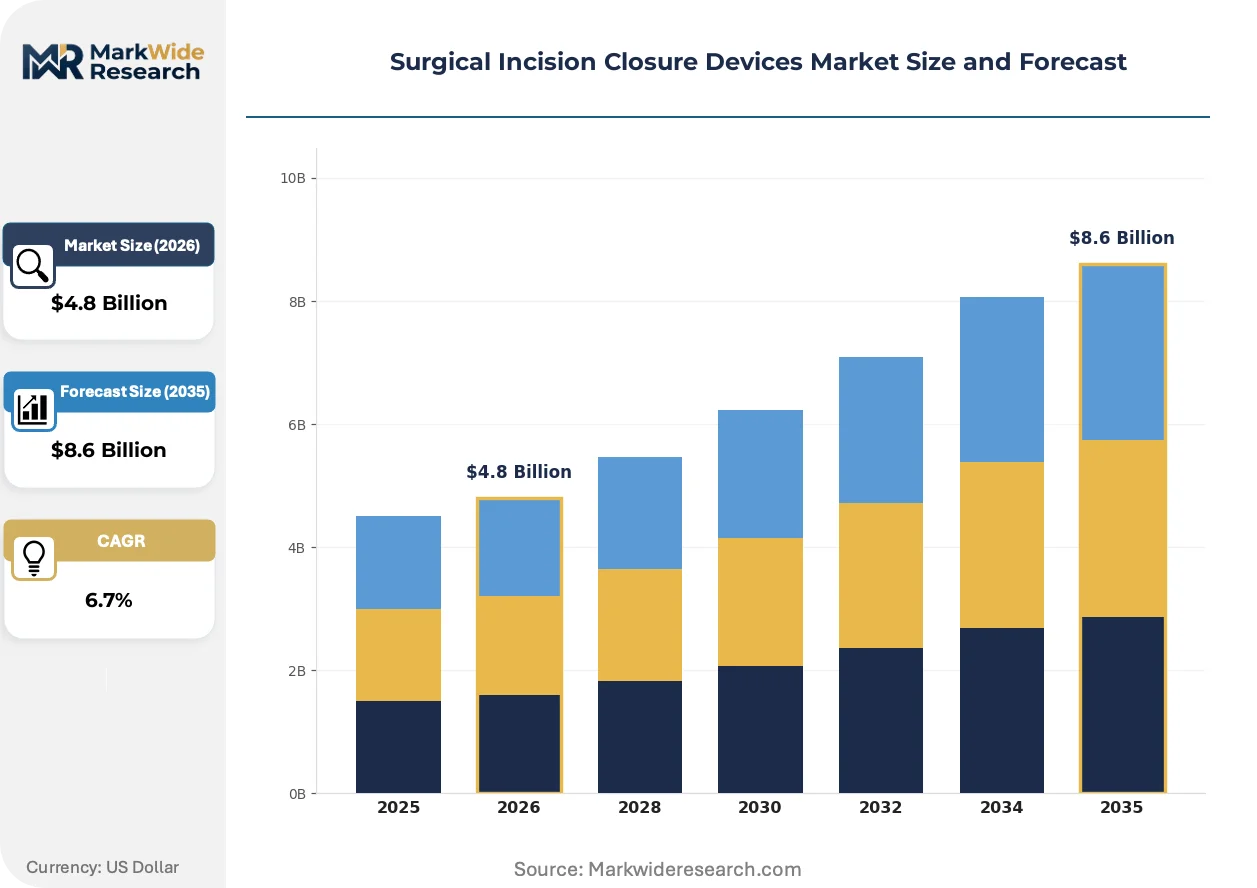
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Staples, Adhesives, Biomaterials Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Plastic Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Technology: Mechanical, Light-assisted, Bioengineered, Surgical |
| Companies Covered | B. Braun Melsungen AG, Smith & Nephew, Medtronic, Ethicon, Stryker, 3M, Baxter, Covidien, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Incision Closure Devices Market Evolving Landscape
Digital connectivity and biomaterial convergence are redefining how closure devices generate value beyond the physical repair function, with data capture and remote monitoring becoming embedded competitive differentiators.
Barbed suture technology is overtaking traditional interrupted closure in laparoscopic procedures. Self-anchoring polydioxanone threads eliminate knot-tying steps, reducing operative time by 12-18 minutes in gynecologic and colorectal cases. Ambulatory surgery centers in Texas and Florida are adopting barbed formats at twice the rate of academic medical centers, compressing reimbursement capture per case while expanding throughput capacity.
Japan's PMDA has implemented post-market surveillance requirements for absorbable medical devices with degradation profiles exceeding 60 days. Manufacturers must now submit real-world performance data from domestic registries, increasing compliance overhead for European exporters. Cardiothoracic suture lines face the steepest documentation burden, prompting Smith & Nephew to establish Tokyo-based clinical affairs staffing.
Hospital systems are consolidating vendor contracts across wound closure categories, replacing product-specific agreements with enterprise-wide surgical supply partnerships. Integrated delivery networks in the United States now mandate single-source accountability for sutures, staples, and sealants, displacing independent adhesive suppliers. This concentration is most advanced in California and Pennsylvania, where three health systems control 60% of inpatient procedural volume.
Surgical Incision Closure Devices Market Segmentation
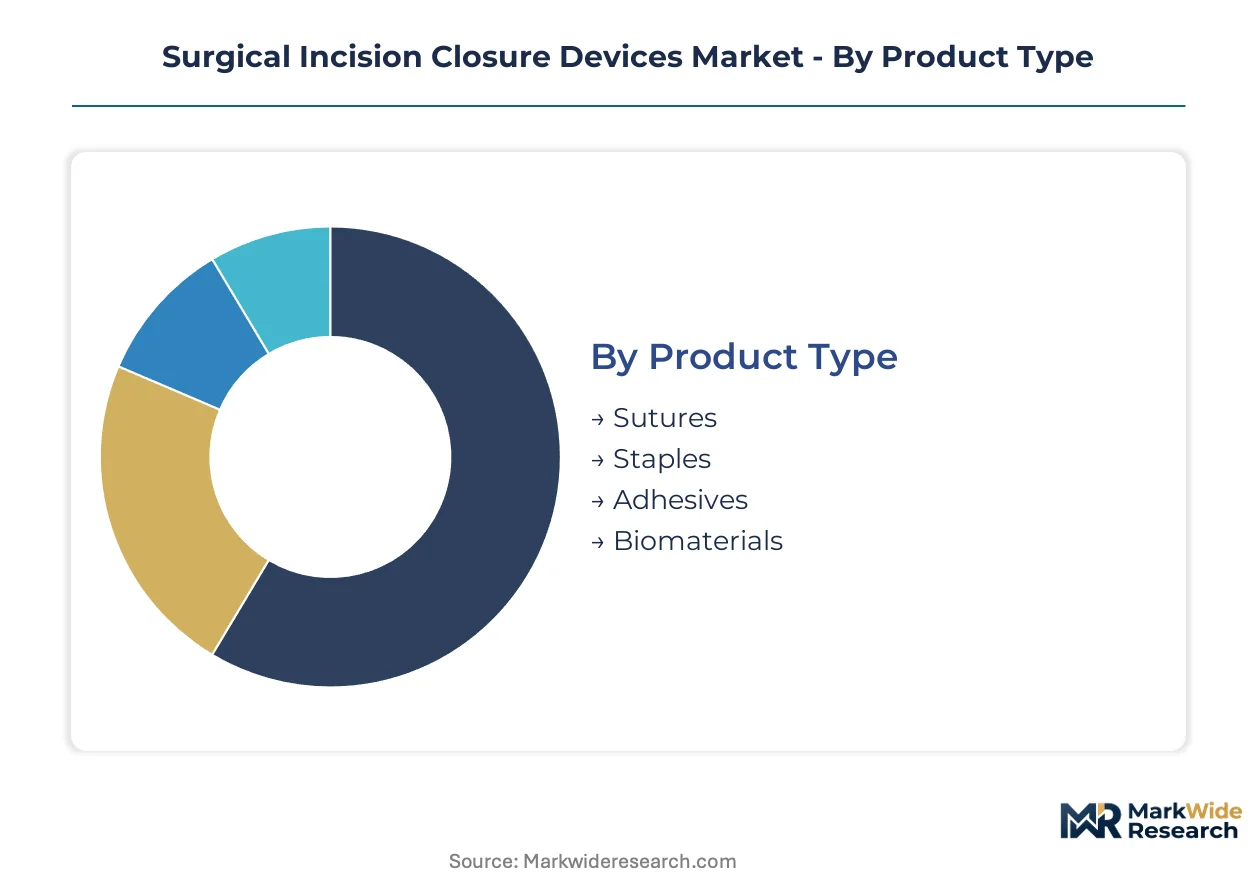
Closure device selection hinges on wound complexity, procedural setting, and reimbursement bandwidth. Each segmentation axis reveals distinct procurement patterns and technology adoption curves that reshape vendor competitive dynamics.
Product Type:
Standardization dominates high-volume formats while premium tiers demand customization for tissue-specific performance.
- Sutures:Absorbable polyglactin and polydioxanone threads remain the default across inpatient settings. Demand concentrates in United States academic medical centers where resident training protocols perpetuate knot-tying proficiency. FDA 510(k) pathways favor predicate-device filings that compress development timelines for incremental gauge variants.
- Adhesives:Cyanoacrylate formulations eliminate suture removal visits. Outpatient procedural volumes in Florida and Texas ambulatory surgical centers pull adoption fastest, driven by reimbursement compression that rewards reduced nursing labor.
- Staples:Stainless steel and absorbable polymer formats anchor laparoscopic closure. Japan's aging surgical workforce favors prefabricated cartridges with automated tissue sensing.
- Biomaterials:Collagen-based and fibrin-derived sealants serve cardiothoracic applications where synthetic tensile strength falls short. EU MDR clinical evidence requirements redirect R&D toward predicate-device leverage strategies.
Most installed capacity flows through Sutures. Expansion is steepest in Adhesives.
Application:
Procedure complexity determines whether mechanical closure suffices or biological intervention becomes necessary.
- General Surgery:Appendectomy and hernia repair generate the highest suture consumption per procedure volume. Ambulatory migration in the United States shifts demand toward disposable staple cartridges.
- Orthopedic Surgery:Deep tissue closure demands high-tensile braided synthetic threads. United States hospital procurement consolidation favors single-vendor contracts spanning sutures and orthopedic implants.
- Cardiothoracic Surgery:Vascular anastomosis requires absorbable monofilament with controlled degradation profiles. Japan's PMDA post-market surveillance mandates for devices exceeding 60-day degradation increase compliance overhead for European exporters.
- Plastic Surgery:Cosmetic outcomes drive premium pricing for barbed sutures and subcuticular closure systems. Outpatient dermatology clinics in California represent the fastest-climbing volume tier.
General Surgery commands the largest addressable base. Plastic Surgery offers the steepest margin expansion trajectory.
End User:
Capital intensity and staffing models separate institutional buyers from distributed care settings.
- Hospitals:Integrated delivery networks in Pennsylvania and California mandate enterprise-wide surgical supply partnerships that displace independent adhesive suppliers.
- Ambulatory Surgical Centers:Single-use adhesive systems dominate procurement to eliminate reprocessing overhead. Texas and Florida lead United States adoption rates for barbed suture formats.
- Clinics:Dermatology and minor procedure offices favor pre-packaged wound closure kits with standardized component ratios.
- Home Care:Post-discharge adhesive patches with embedded biosensors enable remote surgical site surveillance. Reimbursement frameworks for telehealth-integrated monitoring remain fragmented across United States state Medicaid programs.
Hospitals retain the deepest installed base. Ambulatory Surgical Centers are gaining share fastest.
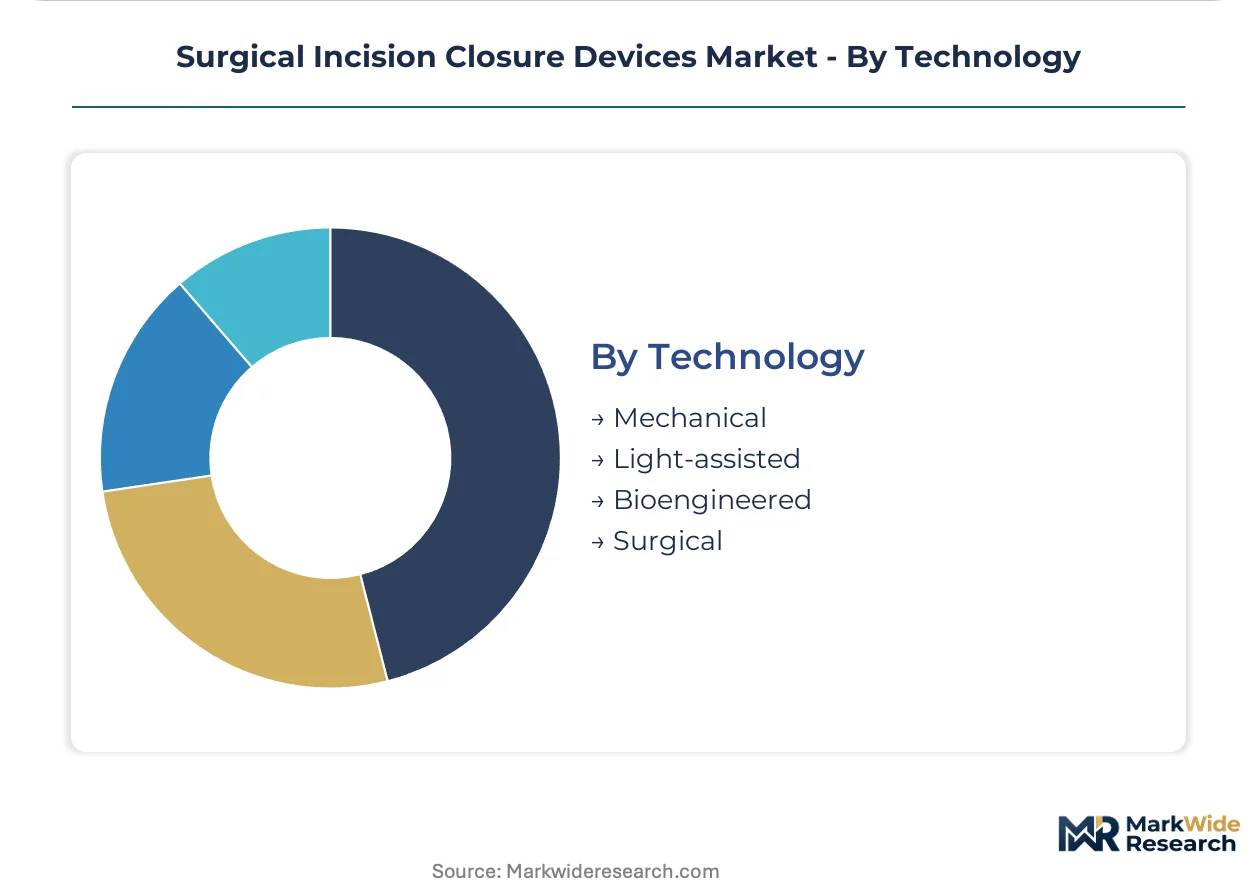
Technology:
Intellectual property concentration varies sharply across maturity curves and regulatory validation burdens.
- Mechanical:Sutures and staples rely on decades-old material science with limited patent protection. India's PLI scheme for medical devices enables cost-competitive sterile thread production for African and Southeast Asian export markets.
- Light-assisted:Photochemical tissue bonding remains experimental outside ophthalmic applications. FDA breakthrough device designation pathways could accelerate clinical validation for vascular closure.
- Bioengineered:Recombinant protein sealants from fibrinogen and thrombin concentrates command premium positioning. Formulation chemists with absorbable polymer expertise concentrate in Basel and Boston corridors.
- Surgical:Smart staplers with embedded usage tracking capture preference among United States integrated delivery networks seeking utilization analytics for value-based contracting. FDA cybersecurity validation requirements extend 510(k) timelines by 8-14 months for first-time filers.
Mechanical technology anchors current revenue. Surgical connectivity offers the steepest forward expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main industrial corridor anchors European manufacturing for sterile suture production, with B. Braun Melsungen AG operating integrated facilities that supply hospital systems across the continent. Regulatory divergence between FDA cybersecurity mandates and EU MDR clinical evidence requirements is fragmenting product development roadmaps. Demand concentrates in the United States, Germany, Japan, India, and Brazil.
United States
Hospital procurement consolidation in Pennsylvania and California drives standardization of wound closure protocols across integrated delivery networks. FDA cybersecurity validation requirements extend 510(k) timelines by 8-14 months for wireless-enabled smart staplers. The Texas Medical Center in Houston anchors adoption of barbed suture formats in ambulatory settings.
Germany
Rhineland-Palatinate's chemical industry supplies glycolide and lactide monomers for absorbable polymer production. EU MDR intensifies clinical evidence requirements for novel bioengineered formats, redirecting R&D toward predicate-device strategies. The Frankfurt-Stuttgart manufacturing belt concentrates sterile thread production for export to African markets.
Japan
Tokyo's aging surgical workforce favors prefabricated stapler cartridges with automated tissue sensing. PMDA post-market surveillance mandates for devices exceeding 60-day degradation increase compliance overhead for European exporters. Osaka's medical device cluster hosts clinical affairs staffing for cardiothoracic suture lines.
India
Maharashtra's pharmaceutical corridor benefits from PLI scheme incentives for domestic medical device manufacturing. CDSCO regulatory pathways enable cost-competitive sterile thread production for Southeast Asian export markets. Gujarat's specialty chemical sector supplies polymer feedstocks to absorbable suture fabricators.
Brazil
São Paulo's private hospital networks drive demand for premium adhesive systems in cosmetic surgery applications. ANVISA regulatory harmonization with FDA standards accelerates approval timelines for predicate devices. The Campinas medical technology cluster hosts distribution centers serving Latin American markets.
Surgical Incision Closure Devices Market Competitive Landscape
Global majors compete with regional champions across sterile thread production, absorbable polymer formulation, and smart stapler connectivity. Market structure tilts toward consolidated procurement relationships with integrated delivery networks, compressing margins for mid-tier suppliers. Three archetypes dominate: diversified medical technology conglomerates with full closure portfolios, European specialists leveraging manufacturing scale in sutures, and adhesive-focused innovators targeting outpatient migration. Competitive moves concentrate on enterprise-wide supply partnerships and cybersecurity compliance investments.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson Services, Inc. represent archetypes of North American supply chain integration, anchoring distribution networks that serve consolidated hospital systems. B. Braun Melsungen AG exemplifies the European manufacturing specialist model, occupying a position sustained by captive polymer production and cost-competitive sterile thread output. Smith & Nephew sits within the adhesive innovation vector, reflecting strategic positioning toward outpatient procedural growth and cyanoacrylate formulation expertise.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Smith & Nephew |
| Medtronic |
| Ethicon |
| Stryker |
| 3M |
| Baxter |
| Covidien |
| Johnson & Johnson Services, Inc. |
| Others |
Value Network & Pricing Analysis
Glycolide and lactide monomer costs originating in Chinese petrochemical corridors flow downstream through absorbable suture pricing tiers, with polymer feedstock volatility compressing margins for European sterile thread manufacturers while Indian PLI-subsidized production captures economy-tier positioning in African and Southeast Asian markets.
Pricing Analysis
Input-cost pass-through from glycolide and lactide monomer supplies drives contract-based long-term offtake agreements for absorbable polymer sutures, with price differentiation resting on FDA 510(k) certification tier and volume scale within integrated delivery network procurement. Cost compression in standard synthetic suture tiers intensifies because hospital consolidation mandates enterprise-wide supply partnerships, while ambulatory surgical centers exhibit highest price sensitivity and cardiothoracic biomaterial buyers show least elasticity due to tensile strength requirements.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for sterile closure device logistics, with manufacturing gravity drawing from Rhineland-Palatinate's chemical industry for polymer feedstocks and Maharashtra's pharmaceutical corridor for cost-competitive thread production. Single-source vulnerability concentrates in Chinese petrochemical corridors for absorbable monomer inputs, while distribution runs through dedicated facilities serving consolidated hospital systems and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical incision closure devices market functions as a geographic-arbitrage play where India's PLI scheme enables 40-60% cost-advantaged sterile thread production against European manufacturing baselines, while FDA cybersecurity validation requirements create regulatory moats protecting North American incumbent positioning.
For Market Incumbents: Hedge against biological sealant substitution in cardiothoracic applications by deepening captive supply of high-tensile absorbable polymers and securing predicate-device 510(k) pathways before EU MDR clinical evidence requirements harden. Channel control through exclusive distribution agreements with Texas and Florida ambulatory surgical center chains defends margin position against adhesive-focused innovators.
For New Entrants and Emerging Players: Enter via telehealth-integrated wound monitoring patches where reimbursement fragmentation across United States state Medicaid programs has delayed incumbent lock-in, targeting home care segments with biosensor-enabled adhesive systems. White-space concentration in Japan's aging surgical workforce favors automated tissue-sensing stapler cartridges, with go-to-market through Osaka's medical device cluster clinical affairs staffing.
For Investors and Strategic Acquirers: Consolidation pressure builds where hospital procurement standardization displaces independent adhesive suppliers and cybersecurity compliance costs exceed $2 million per smart stapler platform. Long-term viability favors targets with predicate-device regulatory archives and established GPO contracts manager relationships. Watch FDA breakthrough device designation pathways for photochemical tissue bonding as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Investment | Software validation documentation extends 510(k) timelines for wireless-enabled smart staplers. |
| Predicate-Device Regulatory Archive Acquisition | EU MDR clinical evidence requirements redirect R&D toward incremental format improvements. |
| PLI Scheme Manufacturing Footprint Expansion | Domestic Indian production enables cost-competitive sterile thread export to African markets. |
| Integrated Delivery Network Supply Partnership | Enterprise-wide contracts displace independent adhesive suppliers in California and Pennsylvania. |
| Telehealth-Integrated Biosensor Development | Post-discharge adhesive patches create recurring revenue through remote surgical site surveillance. |
Research Methodology
Bottom-up ambulatory surgical center and hospital procurement modeling reconciled against top-down sterile thread production tracking forms the analytical core, combining primary interviews with GPO contracts managers, biomedical engineers, hospital purchasing committees, and absorbable polymer formulation chemists with secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement registries, and EU MDR technical documentation.
Historical trendline analysis across installed suture base consumption, adhesive adoption curves, and smart stapler deployment rates informs projection horizon segmentation by product type, application specialty, end-user setting, and technology maturity. CAGRs derive from procedure volume elasticities, reimbursement bandwidth shifts, and regulatory pathway acceleration patterns, with cybersecurity compliance cost curves and polymer feedstock price volatility as key forecast inputs.
Inputs from FDA premarket notification databases and EU MDR notified body assessments were available through the study window; gaps in real-world performance data from Japan's PMDA post-market surveillance registries introduce uncertainty bands around absorbable device degradation profile forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Walking Aids Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Global Biliary Stents Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Antibiotic-Loaded Bone Cement Market