
 Cryosurgical Equipment Market | 2026-2036
Cryosurgical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cryosurgical Equipment Market Analysis
Hospital-grade cryoablation systems with integrated imaging compatibility is bifurcating the competitive landscape into premium integrated platforms and modular outpatient configurations. Medtronic leverages its surgical navigation ecosystem to anchor the high-acuity hospital segment. CooperSurgical specializes in gynecological cryotherapy systems, occupying a distinct niche in cervical precancer treatment. IceCure Medical differentiates through percutaneous tumor ablation platforms, positioning its technology for interventional radiology departments.
Cryosurgical equipment encompasses devices that generate and deliver controlled subzero temperatures through closed or open probe systems, typically using liquid nitrogen, argon-helium mixtures, or nitrous oxide to achieve tissue destruction via freeze-thaw cycles at temperatures ranging from minus 20 to minus 150 degrees Celsius. These systems serve primary clinical purposes in targeted tissue necrosis for benign lesions, malignant tumor ablation, and pain management through cryoneurolysis. Cryoprobes dominate capital expenditure budgets due to their reusable shaft designs and compatibility with multiple gas sources, while closed system technology leads new installations because of reduced cryogen waste and operator safety features. Liquid nitrogen technology retains cost advantages in dermatology practices, though mixed gas systems capture growing share in oncology suites demanding precise thermal monitoring.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation classify cryosurgical platforms as Class II or III devices, mandating biocompatibility testing and clinical performance data that extend development timelines and favor established manufacturers with regulatory infrastructure. Japan's PMDA and South Korea's MFDS impose additional thermal safety standards that filter market entry for non-Asian suppliers. Stakeholders must monitor evolving reimbursement determinations for cryoablation procedures across public and private payers, as coding changes directly influence hospital procurement cycles and physician adoption thresholds.
Market Dynamics
The cryosurgical equipment market is undergoing a fundamental restructuring as integrated imaging compatibility becomes a non-negotiable procurement criterion for hospital systems. This technical mandate is bifurcating vendor portfolios into premium platforms with real-time navigation and modular configurations for outpatient settings.
Growth Catalysts
- EU Medical Device Regulation (MDR):The MDR's enhanced clinical evidence requirements are filtering out marginal suppliers and consolidating demand around manufacturers with established quality management systems. This regulatory elevation protects incumbent positions.
- Interventional radiology departments:Expansion of percutaneous tumor ablation programs in tertiary hospitals is driving capital expenditure toward closed-system cryoprobes with integrated thermal monitoring capabilities.
- Reimbursement stabilization:Established CPT codes for minimally invasive tumor ablation in the United States, Germany, and Japan are removing financial uncertainty and accelerating physician training investments.
Market Restraints
- Argon-helium supply concentration:Dependence on industrial gas suppliers with regional production hubs creates vulnerability to supply disruptions and price volatility for mixed-gas cryosurgical systems.
- FDA 510(k) pathway complexity:Premarket notification requirements for Class II cryothermal devices demand substantial biocompatibility testing that extends development timelines and capital lock-up periods.
- Radiofrequency ablation substitution:RFA systems with lower per-procedure costs and established clinical training infrastructure continue to capture cases in cost-sensitive hospital segments.
Strategic Opportunities
- Outpatient ambulatory surgical centers:Modular cryotherapy configurations with reduced cryogen consumption are penetrating freestanding facilities seeking to expand dermatology and gynecology service lines.
- Japan's PMDA thermal safety standards:Compliance with these stringent protocols opens access to a high-value market where domestic manufacturers have limited cryoablation expertise.
- Artificial intelligence-integrated navigation:Convergence of machine learning with intraoperative imaging is enabling real-time ice ball monitoring that reduces procedure variability and training burdens.
Industry Challenges
- Interventional radiologist training pipelines:Shortage of physicians with dual competency in imaging interpretation and percutaneous probe placement limits program expansion velocity.
- Legacy equipment integration:Hospital information systems with proprietary data architectures create friction when connecting new cryosurgical platforms to electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryosurgical Equipment Market |
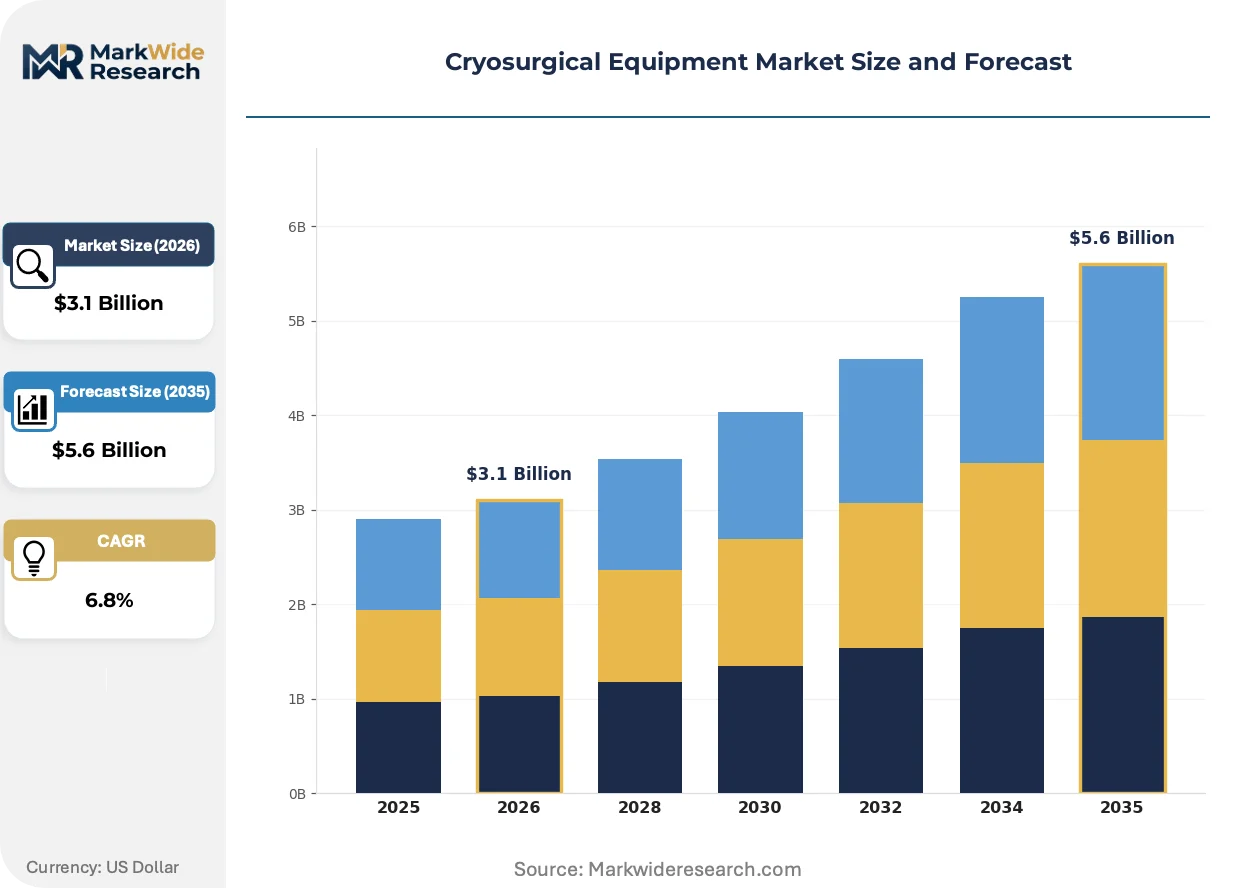
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryoprobes, Cryoguns, Cryo Cart, Cryo Handpieces End User: Hospitals, Outpatient Clinics, Specialty Clinics, Research Laboratories Technology: Closed Systems, Open Systems, Liquid Nitrogen, Mixed Gas Application: Dermatology, Oncology, Gynecology, Pain Management |
| Companies Covered | Medtronic, CooperSurgical, CryoConcepts, Brymill Cryogenic Systems, AtriCure, Cardinal Health, IceCure Medical, Metrum Cryoflex, Cortex Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryosurgical Equipment Market Emerging Trajectories
Closed-system cryotechnology is displacing open liquid nitrogen architectures across multiple clinical settings. This transition is compressing operational costs while elevating safety protocols. Three developments are accelerating this transformation.
Argon-helium Joule-Thomson systems with reusable probe shafts are displacing single-use disposable configurations in high-volume oncology suites. Interventional radiology departments in tertiary hospitals are adopting these platforms for liver and kidney tumor ablation. The technology is displacing capital-intensive equipment refresh cycles by extending probe longevity across thousands of freeze-thaw procedures.
The EU Medical Device Regulation's clinical evidence requirements are reshaping competitive entry barriers for cryosurgical platforms. Manufacturers must now submit post-market surveillance data and biocompatibility documentation that extends approval timelines. Class II and III device classifications under MDR are compressing the viable supplier base to established players with dedicated regulatory infrastructure.
Service unbundling is fragmenting traditional equipment procurement relationships. Hospital systems are separating capital acquisition from maintenance contracts and cryogen supply agreements. This behavioral shift is most visible in United States integrated delivery networks negotiating multi-vendor service level agreements that decouple device ownership from operational support.
Cryosurgical Equipment Market Segmentation
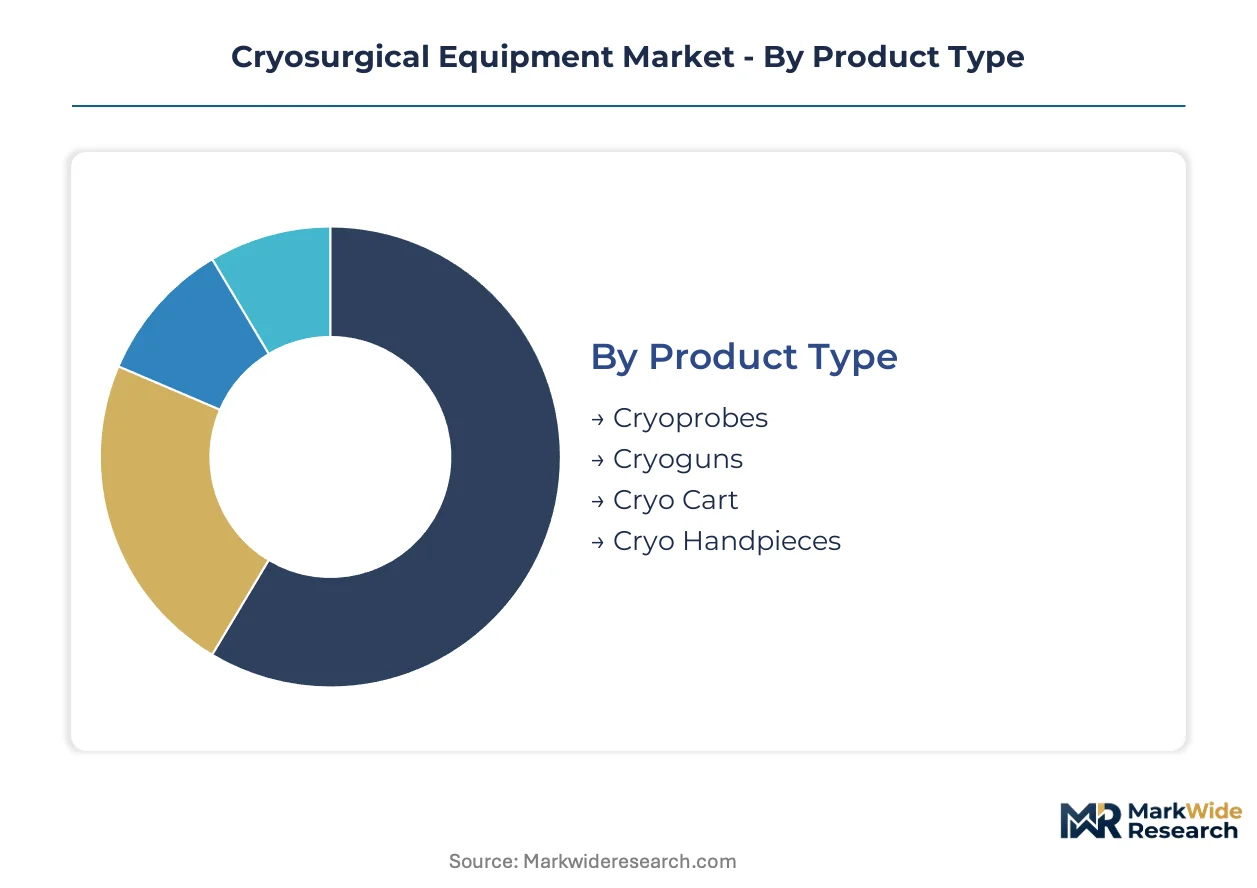
Cryosurgical equipment procurement channels diverge sharply between capital-intensive hospital systems and volume-driven outpatient settings. Channel economics dictate which product configurations gain traction, with integrated platforms flowing through direct sales and modular devices penetrating distributor networks.
Product Type:
Channel mix varies by product complexity — cryoprobes move through surgical supply distributors to hospital systems, while cryoguns and handpieces reach dermatology practices through medical device dealers.
- Cryoprobes:Reusable shaft designs with compatibility across argon-helium and nitrous oxide sources dominate capital budgets in tertiary hospitals. Oncology departments in the United States and Japan concentrate demand here, driven by percutaneous tumor ablation program expansion and integrated imaging requirements.
- Cryoguns:Handheld devices with precision spray nozzles for superficial lesion treatment anchor dermatology practice revenues. Demand clusters in German outpatient clinics where liquid nitrogen cost economics favor open-system architectures over closed alternatives.
- Cryo Cart:Mobile console systems with integrated cryogen storage and thermal monitoring serve interventional radiology suites requiring procedural flexibility.
- Cryo Handpieces:Disposable and reusable tip configurations for targeted tissue contact dominate gynecological cryotherapy applications in cervical precancer treatment protocols.
Cryoprobes dominate installed base. Cryo handpieces are where expansion concentrates.
End User:
Cost tier stratification separates premium integrated platform buyers from modular system adopters, with reimbursement stability determining procurement velocity.
- Hospitals:Tertiary medical centers with interventional radiology departments anchor demand for closed-system platforms with real-time ice ball monitoring. These institutions in the United States and Japan prioritize FDA 510(k) cleared and PMDA compliant devices with established CPT reimbursement pathways.
- Outpatient Clinics:Freestanding ambulatory surgical centers seek reduced cryogen consumption configurations to expand dermatology and pain management service lines without infrastructure overhead.
- Specialty Clinics:Gynecology-focused facilities drive cryotherapy system adoption for cervical dysplasia protocols, particularly where national screening programs create procedure volume.
- Research Laboratories:Academic medical centers with preclinical oncology programs purchase specialized platforms for experimental ablation studies and device validation work.
Hospitals capture premium pricing tiers. Outpatient clinics are climbing the fastest.
Technology:
Volume concentration favors closed architectures in high-throughput settings, while open systems retain footholds where capital constraints dominate.
- Closed Systems:Sealed cryogen circuits with automated pressure regulation and waste reduction are displacing open architectures in oncology suites. German hospital procurement committees specify these platforms for liver and kidney ablation programs under EU MDR quality management requirements.
- Open Systems:Ventilated liquid nitrogen delivery retains cost advantages in dermatology practices with lower procedure volumes and less stringent safety protocols.
- Liquid Nitrogen:Cryogenic fluid at minus 196 degrees Celsius serves superficial applications through spray or probe contact methods, dominating established dermatology workflows.
- Mixed Gas:Argon-helium Joule-Thomson systems enable precise temperature cycling for deep tissue ablation, capturing share in interventional radiology departments demanding thermal monitoring integration.
Closed systems dominate installed base. Mixed gas configurations are where expansion concentrates.
Application:
Customer type segmentation separates procedure reimbursement stability from emerging indication development.
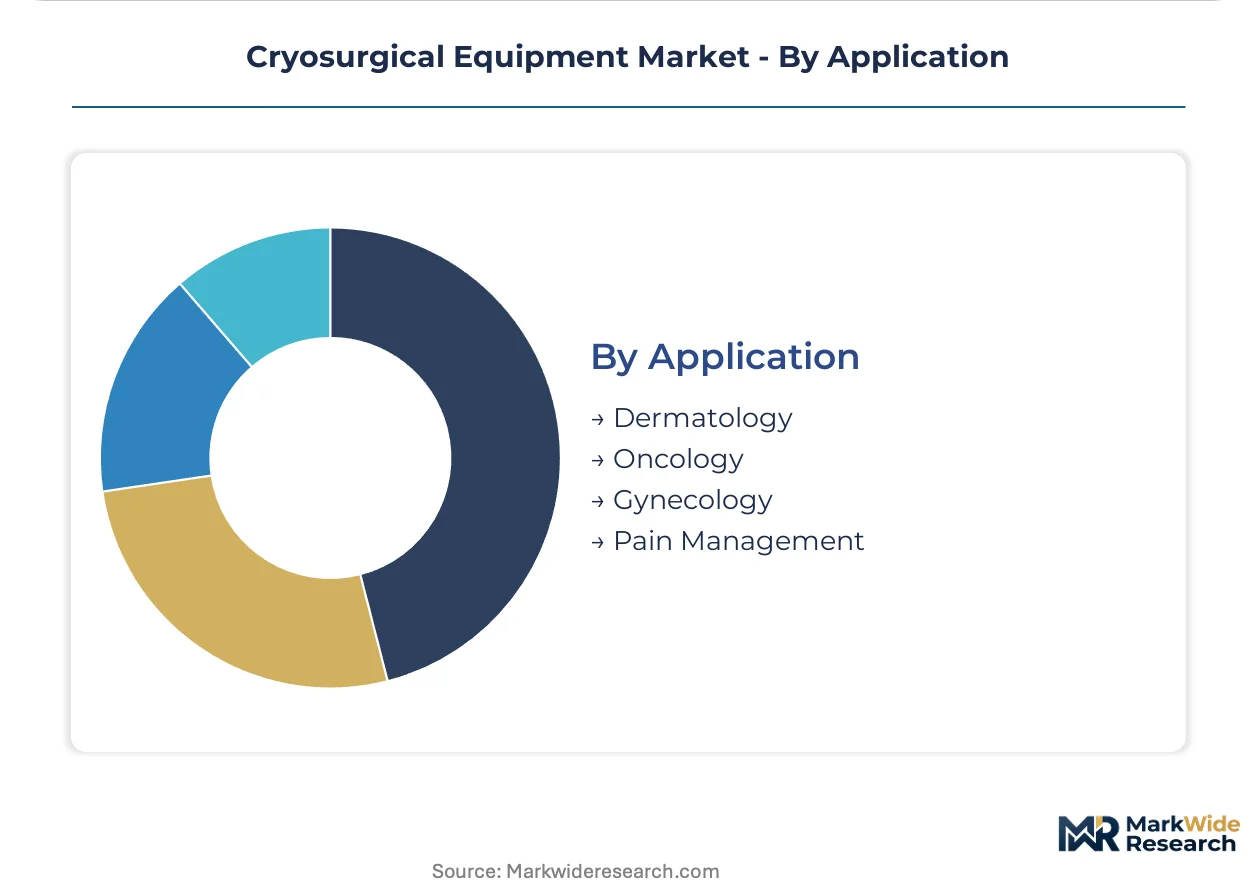
- Oncology:Percutaneous tumor ablation for liver, kidney, and lung malignancies drives the steepest expansion trajectory, with interventional radiology departments in the United States and Japan investing in navigation-integrated platforms.
- Dermatology:Benign and precancerous lesion treatment anchors liquid nitrogen system demand in high-volume outpatient settings with established procedural workflows.
- Gynecology:Cervical cryotherapy for precancerous lesions serves screening program infrastructure, particularly where national health systems mandate coverage.
- Pain Management:Cryoneurolysis for peripheral nerve ablation addresses chronic pain conditions, expanding through pain clinic networks seeking non-opioid alternatives.
Dermatology dominates installed base. Oncology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in cryosurgical equipment tilt toward net imports in emerging markets while the United States, Germany, and Japan maintain manufacturing surpluses. Regulatory harmonization pressures are reshaping cross-border equipment certification pathways.
United States
Tertiary hospital systems in Houston and Boston are expanding interventional radiology cryoablation programs for hepatic and renal malignancies. FDA 510(k) premarket notification requirements for Class II cryothermal devices mandate biocompatibility testing that extends approval timelines. The Texas Medical Center cluster anchors demand for closed-system platforms with integrated navigation capabilities.
Germany
University hospitals in Munich and Berlin are standardizing percutaneous tumor ablation workflows under EU Medical Device Regulation quality management mandates. The MDR's enhanced clinical evidence requirements filter out marginal suppliers and consolidate procurement around established manufacturers. The Baden-Württemberg medical technology corridor concentrates engineering expertise for cryoprobe thermal monitoring systems.
Japan
Metropolitan medical centers in Tokyo and Osaka are investing in navigation-integrated cryoablation platforms for lung and kidney tumors. PMDA thermal safety standards impose additional validation protocols that favor incumbent suppliers with dedicated regulatory infrastructure. The Kanto region's interventional radiology departments drive premium equipment adoption through stabilized reimbursement codes.
China
Provincial hospitals in Shanghai and Guangzhou are scaling cryoablation programs for hepatocellular carcinoma treatment. NMPA medical device registration requirements are tightening clinical trial documentation for imported cryosurgical platforms. The Yangtze River Delta medical device manufacturing base is developing domestic closed-system alternatives to reduce import dependence.
United Kingdom
NHS foundation trusts in London and Manchester are consolidating cryotherapy procurement through centralized medical equipment frameworks. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific approval pathways. The Oxford-Cambridge life sciences corridor supports experimental ablation research through academic medical center partnerships.
Cryosurgical Equipment Market Vendor Landscape
Listed leaders compete with private specialists across regulatory infrastructure and integrated imaging ecosystems. The vendor base stratifies into three tiers: diversified medical technology conglomerates with surgical navigation platforms, focused cryotherapy specialists with indication-specific portfolios, and regional equipment fabricators serving cost-sensitive outpatient segments. Dominant competitive moves include strategic partnerships with industrial gas suppliers and technology licensing agreements for Joule-Thomson probe architectures.
Within the diversified conglomerate tier, Medtronic and Cardinal Health exemplify scale-driven positions anchored by hospital system purchasing relationships. CooperSurgical occupies a specialization-focused position in gynecological applications. IceCure Medical represents the interventional radiology-focused archetype with percutaneous ablation platform development. These three companies illustrate the competitive spectrum from broad surgical ecosystem integration to narrow clinical indication dominance.
| Leading Market Players |
|---|
| Medtronic |
| CooperSurgical |
| CryoConcepts |
| Brymill Cryogenic Systems |
| AtriCure |
| Cardinal Health |
| IceCure Medical |
| Metrum Cryoflex |
| Cortex Technology |
| Others |
Supply Flow & Price Mechanics
Ninety-to-one-hundred-twenty-day probe replacement cycles concentrate pricing leverage with gas suppliers and probe fabricators in Germany and Japan, compressing margins for hospital procurement committees while elevating total cost-of-ownership negotiations. This inventory velocity ties equipment pricing power directly to argon-helium sourcing relationships and reusable shaft longevity claims.
Pricing Analysis
Hospital systems anchor equipment pricing through multi-year service bundling that separates capital acquisition from cryogen supply and preventive maintenance contracts. Pricing stratifies across navigation-integrated premium platforms, standard closed-system consoles, and modular outpatient configurations, with FDA 510(k) clearance tier and thermal monitoring precision as primary differentiation drivers. Cost compression in standard-tier systems is intensifying as Chinese manufacturers achieve EU MDR technical compliance. Ambulatory surgical centers exhibit highest price sensitivity; tertiary oncology departments with established CPT reimbursement demonstrate lowest.
Supply Chain Analysis
Just-in-time cryogen delivery dominates hospital procurement, though strategic probe stockpiling is emerging among United States integrated delivery networks facing argon supply volatility. Manufacturing concentrates in Germany, Japan, and the United States for precision thermal monitoring components, while China scales domestic closed-system assembly. Supply chains rest on argon-helium industrial gas contracts, reusable probe shaft alloys, and integrated imaging sensor modules. Single-source vulnerability runs through regional argon production hubs concentrated in Texas and Siberia. Distribution runs through surgical supply distributors for cryoprobes and medical device dealers for handheld cryoguns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryosurgical equipment markets reward service-attach strategies where maintenance contracts and cryogen supply agreements expand recurring revenue faster than hardware replacement cycles. Consumables and preventive service layers now outpace capital equipment growth in margin contribution.
For Market Incumbents: Shield installed base positions by deepening backward integration into probe shaft manufacturing and securing exclusive argon-helium supply agreements with industrial gas distributors. Radiofrequency ablation substitution in cost-sensitive hospital segments demands defensive bundling of navigation software with hardware refresh cycles. Prioritize PMDA thermal safety certification investment to lock out emerging Asian competitors from Japan's premium reimbursement environment.
For New Entrants and Emerging Players: Lead with modular outpatient configurations targeting ambulatory surgical centers in Germany and the United Kingdom where NHS framework contracting creates procurement entry points. Gynecological cryotherapy for cervical screening programs offers the most penetrable application with lower regulatory barriers than oncology ablation. Pursue distributor partnerships with established medical device dealers serving dermatology practices rather than direct hospital sales force builds.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core surgical device portfolios. Five-to-ten year viability hinges on navigation-integrated platform differentiation and regulatory infrastructure depth rather than commodity probe manufacturing. Watch for reimbursement code expansion for cryoablation in lung and bone metastases as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures long-term procurement commitments through integrated delivery network contracting. |
| CE Marking Pathway | EU MDR compliance filters competition and protects premium pricing in German hospital systems. |
| Reimbursement Strategy | CPT code stabilization in United States oncology departments accelerates physician training investment. |
| Software Companion Development | AI-integrated ice ball monitoring reduces procedure variability and elevates platform stickiness. |
| Backward Integration into Probe Manufacturing | Captive supply of reusable shafts insulates margin from argon-helium price volatility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across interventional radiologists, hospital biomedical engineers, GPO contracts managers, and industrial gas supply specialists. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up equipment shipment estimates and top-down healthcare capital expenditure patterns were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled cryoprobe unit economics, cryogen consumption patterns, and service contract attach rates alongside technology segmentation by closed versus open system architecture and application split across oncology, dermatology, gynecology, and pain management. CAGRs were derived from procedure volume elasticity to reimbursement stability and equipment replacement cycle compression in high-throughput tertiary settings.
The analysis sits within stated boundaries; outcomes outside sustained CPT code stability or argon-helium supply continuity would require recalibration. Forecasts reflect assumptions of regulatory pathway duration and physician training pipeline expansion without disruption. Revision becomes warranted when reimbursement determination delays or industrial gas supply shocks cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market