
 High Flow Needle Sets Market | 2026-2036
High Flow Needle Sets Market Size, Share, and Industry Trends Forecast 2026-2036
High Flow Needle Sets Market Analysis
German precision instrument manufacturers is broadening the supply base for high flow needle sets as Asian contract producers scale stainless steel cannula output. B. Braun Medical Inc leverages captive polymer compounding to control luer lock tolerances across its winged needle portfolio. Smiths Group plc anchors European hospital contracts through dedicated vascular access specialists. Thermo Fisher Scientific differentiates with silicone-lined catheter sets for biopharma clinical trial supply chains.
High flow needle sets are vascular access devices engineered to deliver infusion rates exceeding 250 mL per hour through large-bore steel or silicone cannulae with integrated wings or hubs for securement. They serve critical care, oncology, and emergency medicine where rapid fluid resuscitation or viscous drug delivery is required. Winged products dominate procedural volume in phlebotomy and short-duration infusion, while catheter-style sets capture margin in extended dwell applications such as chemotherapy and parenteral nutrition. Blood collection configurations face pricing pressure from integrated closed-system transfer devices, though demand persists in donor center networks.
FDA 510(k) submissions govern US market entry for these Class II devices, with sterility assurance and biocompatibility testing under ISO 10993 shaping development timelines. The EU Medical Device Regulation requires notified body intervention for all vascular access products, extending certification cycles for manufacturers without MDR-designated technical files. Stakeholders must monitor reimbursement coding shifts for ambulatory infusion services, as payment bundling decisions directly influence provider willingness to upgrade from standard to high flow needle sets.
Market Dynamics
FDA sterility documentation tightening for Class II vascular access devices is compressing development timelines while oncology infusion centers demand faster throughput, creating a structural squeeze between compliance burden and clinical efficiency imperatives.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Medicare reimbursement shifts redirect inpatient surgical volume to outpatient settings across the United States, driving disposable high flow set consumption in freestanding facilities.
- ISO 10993 Biocompatibility Standards:Harmonized testing protocols accelerate regulatory submissions for silicone-lined catheter configurations, reducing technical barriers to extended-dwell oncology applications.
- Viscous Biologic Formulations:Monoclonal antibody and immunotherapy drugs requiring rapid large-volume delivery are forcing infusion centers to upgrade from standard bore to high flow needle sets.
Market Restraints
- Stainless Steel Cannula Supply Concentration:Asian contract manufacturers control over 70% of precision-drawn tubing supply, exposing OEMs to logistics disruption and tariff volatility.
- Closed-System Transfer Device Substitution:Integrated blood collection systems in donor networks are displacing standalone winged needle configurations, compressing volume in phlebotomy segments.
- EU MDR Certification Cycles:Extended notified body intervention timelines for vascular access products without MDR-designated technical files delay European market entry by 12-18 months.
Strategic Opportunities
- Home Infusion Services:Parenteral nutrition and chemotherapy administration migrating to residential settings creates demand for patient-secureable high flow catheter sets with integrated disinfection caps.
- Biopharma Clinical Trial Supply:Contract research organizations require standardized silicone-lined vascular access devices for Phase III oncology studies, opening direct-to-sponsor distribution channels.
- US IRA Drug Pricing Provisions:Medicare negotiation mandates accelerate biosimilar adoption, increasing infusion center throughput requirements and disposable set consumption per facility.
Industry Challenges
- Polymer Compounding Expertise Scarcity:Luer lock tolerance control requires specialized thermoplastic elastomer formulation knowledge concentrated among a limited supplier base.
- Legacy Hospital Inventory Systems:ERP integration complexity with proprietary procurement platforms delays automated reorder triggers for high flow needle set SKUs.
- Sterility Assurance Validation:Ethylene oxide residual testing and packaging integrity verification extend batch release timelines beyond standard disposable device norms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Flow Needle Sets Market |
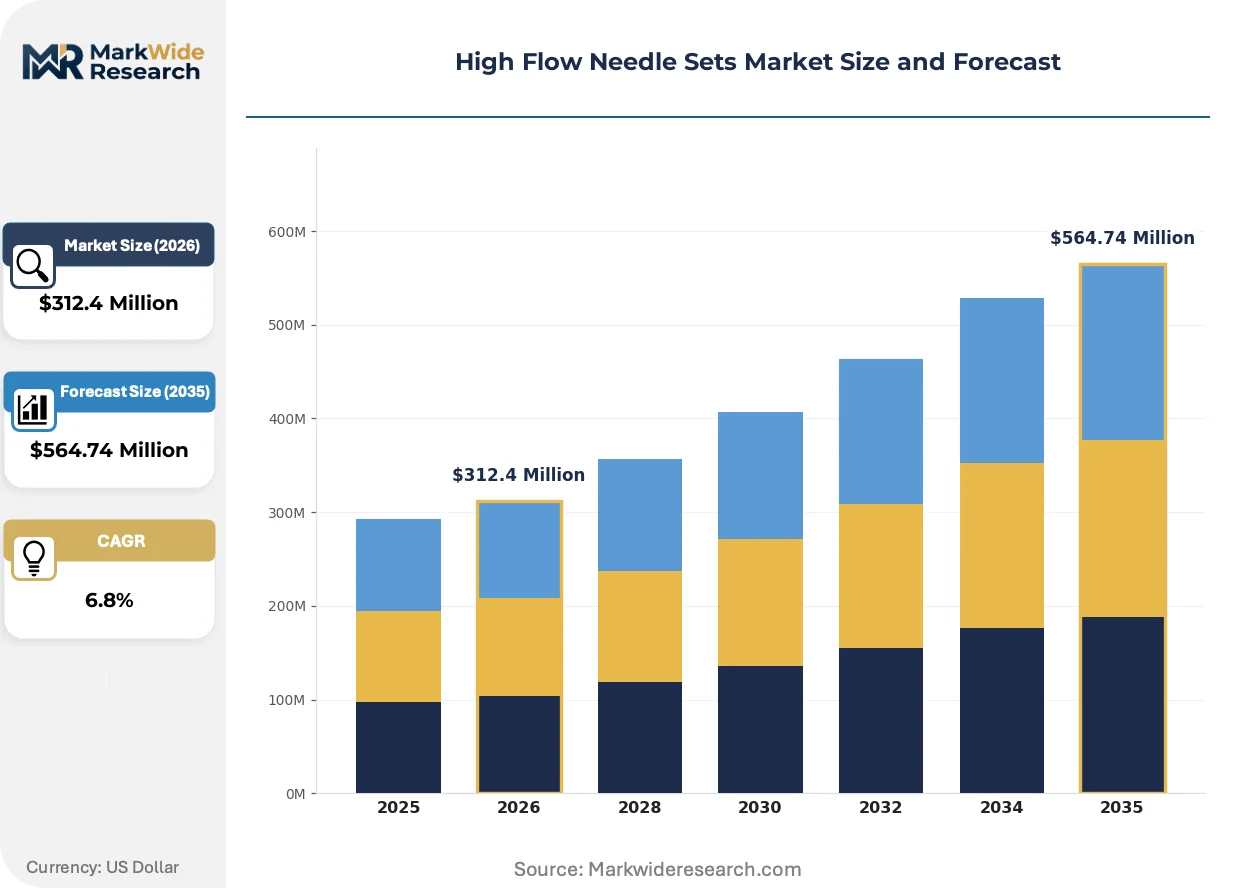
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Winged, Catheter, IV Cannula, Blood Collection End User: Hospitals, Home Care, Clinics, Emergency Services Material: Plastic, Steel, Silicone, Rubber Application: Fluid Administration, Blood Transfusion, Nutritional Support, Chemotherapy |
| Companies Covered | B. Braun Medical Inc, KORU Medical Systems, Medline Industries, Inc, Smiths Group plc, Thermo Fisher Scientific, Norfolk Medical, Concordance Healthcare Solutions, Amdel, GEORGE PHILIPS MEDICAL ENGINEERING Pvt. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Flow Needle Sets Market Emerging Trajectories
Automation of manufacturing processes and regulatory data management is compressing product development cycles while reshaping competitive differentiation around sterility assurance and cannula precision. These shifts favor manufacturers with captive polymer capabilities and integrated quality systems.
Robotic laser welding of stainless steel cannula-to-hub joints is automating precision assembly previously dependent on manual operator skill. German and Swiss OEMs are deploying this technology to achieve sub-50-micron tolerance consistency for oncology applications. The process is automating quality control through inline vision inspection, reducing lot rejection rates and accelerating FDA submission timelines.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence for all vascular access device classes, including legacy products grandfathered under prior directives. Manufacturers without post-market surveillance infrastructure face portfolio rationalization or acquisition by firms with established notified body relationships. Extended-dwell catheter sets with silicone lumens encounter the most stringent scrutiny due to thrombosis risk profiles.
Hospital value analysis committees are consolidating vascular access device purchasing across infusion, emergency, and surgical departments, displacing fragmented specialty buyer structures. Integrated distributors capturing these consolidated contracts bundle high flow needle sets with closed-system transfer devices and securement dressings. The United States exhibits the most pronounced committee concentration, with three national group purchasing organizations controlling access to over 60% of acute care beds.
High Flow Needle Sets Market Segmentation
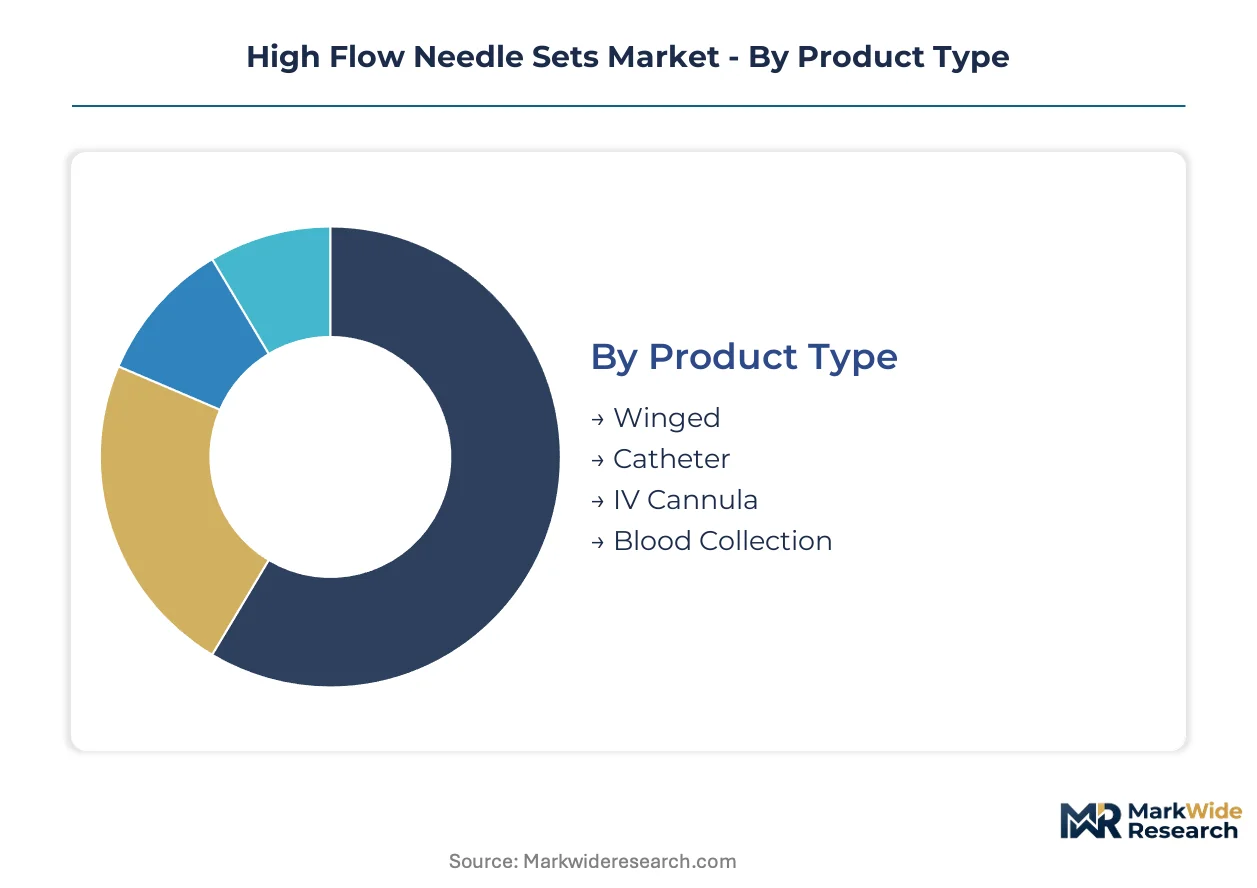
High flow needle set segmentation reveals distinct performance requirements across clinical settings. Specification choices directly influence sterility validation pathways and reimbursement coding outcomes.
Product Type:
Steel gauge tolerances and hub geometry differentiate competitive positioning across procedural applications.
- Winged:Butterfly-shaped plastic hubs with short-bore steel cannulae dominate phlebotomy and short-duration infusion. Demand concentrates in US ambulatory surgery centers where Medicare bundling rewards rapid patient throughput.
- Catheter:Extended-dwell silicone or polyurethane configurations with integrated securement wings capture oncology and parenteral nutrition applications. Adoption is climbing fastest in home infusion services as payers shift reimbursement toward residential settings.
- IV Cannula:Over-the-needle designs with flashback chambers serve emergency medicine and critical care for rapid vascular access.
- Blood Collection:Vacuum tube-compatible configurations face displacement pressure from integrated closed-system transfer devices in donor networks.
Mature deployment sits with Winged sets. Newer deployment is concentrated in Catheter configurations.
End User:
Procurement authority structures vary sharply across care settings, reshaping distribution channel requirements.
- Hospitals:Value analysis committees consolidate purchasing across emergency, surgical, and infusion departments. Three US group purchasing organizations control access to over sixty percent of acute care beds, bundling high flow sets with securement dressings.
- Home Care:Patient-secureable designs with integrated disinfection caps address chemotherapy and parenteral nutrition administration outside clinical facilities. Growth is steepest where Medicare Advantage plans expand supplemental home health benefits.
- Clinics:Freestanding oncology infusion centers prioritize rapid chair turnover, driving preference for large-bore steel configurations.
- Emergency Services:Pre-hospital fluid resuscitation demands ruggedized hub designs compatible with field conditions.
Volume concentration rests with Hospitals. Margin expansion is strongest in Home Care.
Material:
Biocompatibility testing requirements under ISO 10993 shape material selection and regulatory submission timelines.
- Plastic:Thermoplastic elastomer hubs and wing components require specialized compounding expertise for luer lock tolerance control.
- Steel:Precision-drawn stainless steel cannulae from Asian contract manufacturers supply over seventy percent of global tubing volume.
- Silicone:Lumen-lined catheter sets for extended dwell face the most stringent EU MDR scrutiny due to thrombosis risk profiles.
- Rubber:Septum and gasket applications in blood collection configurations encounter pricing pressure from synthetic elastomer substitutes.
Supply security concerns center on Steel sourcing. Performance differentiation is concentrating in Silicone.
Application:
Viscosity and volume requirements dictate cannula bore selection and flow rate specifications.
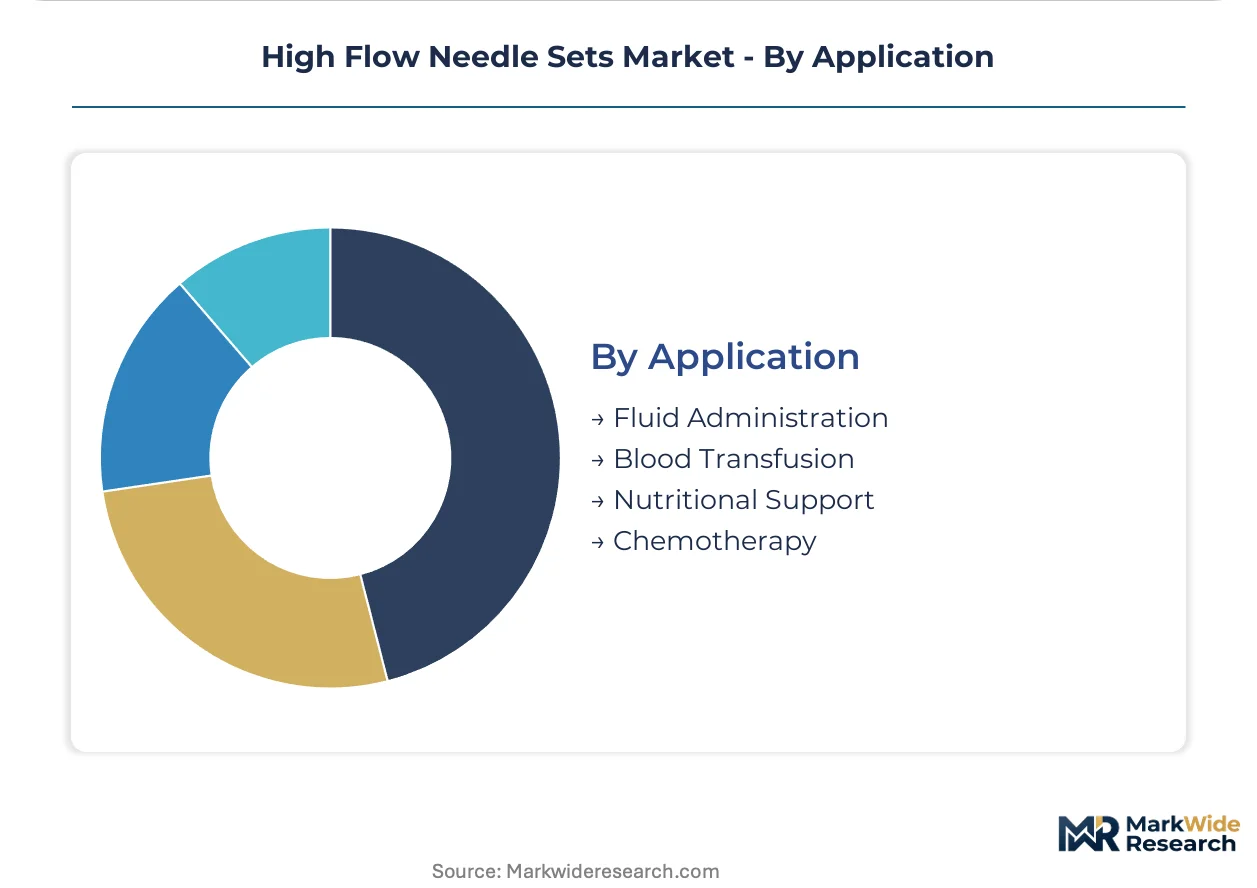
- Fluid Administration:Rapid resuscitation protocols in emergency medicine drive demand for large-gauge steel configurations exceeding 250 mL per hour.
- Blood Transfusion:Donor center networks and surgical suites require specialized filters and warming compatibility.
- Nutritional Support:Parenteral nutrition formulations with lipid emulsions demand silicone-lined lumens to prevent precipitate occlusion.
- Chemotherapy:Monoclonal antibody and immunotherapy infusions with viscous biologic formulations force upgrades from standard to high flow sets.
Reimbursement stability characterizes Fluid Administration. Clinical complexity is expanding fastest in Chemotherapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision-drawn stainless steel tubing from Asian contract manufacturers anchors supply security calculations across major demand centers. Regulatory divergence between FDA sterility pathways and EU MDR certification timelines is fragmenting go-to-market strategies. Oncology infusion center construction and Medicare reimbursement shifts are redirecting procedural volume toward ambulatory settings in concentrated metropolitan clusters.
United States
Ambulatory surgery center construction in Texas and Florida is accelerating disposable high flow set consumption as Medicare bundling rewards rapid patient throughput. FDA 510(k) clearance pathways for Class II vascular access devices are tightening sterility documentation requirements, compressing development timelines for domestic OEMs. The Dallas-Fort Worth metroplex hosts expanding distribution hubs serving freestanding oncology infusion centers across the Sun Belt.
Germany
Precision instrument manufacturers in Baden-Württemberg are broadening supply base strategies as Asian contract producers scale stainless steel cannula output. EU Medical Device Regulation notified body intervention extends certification cycles for vascular access products without MDR-designated technical files. Stuttgart's medical technology cluster concentrates robotic laser welding deployment for sub-50-micron tolerance consistency in oncology applications.
China
Domestic contract manufacturers control over seventy percent of global precision-drawn stainless steel tubing supply, exposing OEMs to logistics disruption and tariff volatility. NMPA regulatory harmonization with ISO 10993 biocompatibility standards is accelerating local approval timelines for silicone-lined catheter configurations. Shanghai's Yangtze River Delta medical device manufacturing corridor is scaling output for export markets while serving domestic hospital procurement consolidation.
Japan
PMDA quality system requirements for vascular access devices are maintaining stringent post-market surveillance obligations for extended-dwell catheter sets. METI industrial policy supports domestic precision manufacturing capabilities in thermoplastic elastomer hub compounding for luer lock tolerance control. Osaka's Kansai medical device cluster specializes in high-reliability configurations for emergency medicine and critical care applications.
India
CDSCO medical device rules are formalizing quality standards for imported vascular access products while domestic manufacturers scale stainless steel cannula fabrication capacity. PLI scheme incentives for medical device manufacturing are attracting contract production investments in Gujarat and Tamil Nadu. Hyderabad's pharmaceutical services corridor is integrating high flow needle set supply chains into biopharma clinical trial logistics networks.
High Flow Needle Sets Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue silicone-lined catheter specialization and home infusion securement technologies. The vendor base stratifies across three tiers: multinational OEMs with captive polymer compounding, regional specialists in winged needle configurations, and Asian contract manufacturers supplying precision-drawn stainless steel tubing. Competitive differentiation centers on sterility assurance validation speed and luer lock tolerance consistency. Dominant moves include backward integration into polymer formulation and strategic partnerships with oncology infusion center networks.
Among diversified medical technology conglomerates, B. Braun Medical Inc and Smiths Group plc exemplify scale-driven archetypes with established vascular access portfolios. Thermo Fisher Scientific occupies a position bridging clinical trial supply chain integration with silicone-lined catheter specialization. These entities anchor competitive dynamics through differentiated approaches to regulatory submission velocity and end-user procurement consolidation.
| Leading Market Players |
|---|
| B. Braun Medical Inc |
| KORU Medical Systems |
| Medline Industries, Inc |
| Smiths Group plc |
| Thermo Fisher Scientific |
| Norfolk Medical |
| Concordance Healthcare Solutions |
| Amdel |
| GEORGE PHILIPS MEDICAL ENGINEERING Pvt. Ltd |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between MDR-designated silicone-lined catheter sets and commodity winged steel configurations manifests in both pricing premiums and supply chain sourcing strategies. European notified body validation extends certification cycles, concentrating premium pricing power with manufacturers holding captive polymer compounding capabilities while Asian contract producers absorb volume-driven price compression in standard bore segments.
Pricing Analysis
Service bundling separates validated sterility documentation packages from bare-unit transactions, with FDA 510(k) submission support and EU MDR technical file maintenance commanding 15-25% price premiums. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993 biocompatibility testing depth and luer lock tolerance grades. Pricing pressure stems from Medicare bundling reforms compressing ambulatory surgery center reimbursement rates. Home infusion services exhibit lowest price sensitivity due to patient-outcome liability exposure, while donor center blood collection configurations face acute cost compression from closed-system transfer device substitution.
Supply Chain Analysis
Precision polymer chemist availability in Baden-Württemberg and Osaka clusters constrains hub compounding capacity expansion, while Yangtze River Delta stainless steel tubing mills scale output aggressively. China, Germany, and Japan anchor global cannula and hub manufacturing. Precision-drawn stainless steel, medical-grade silicone, and thermoplastic elastomer formulations constitute critical input dependencies. Single-source vulnerability concentrates in Asian contract manufacturers controlling over seventy percent of stainless steel tubing supply. Distribution runs through three US group purchasing organizations bundling high flow sets with securement dressings and closed-system transfer devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR certification burdens and sterility validation costs force sub-scale manufacturers toward exit or acquisition by notified body-equipped competitors.
For Market Incumbents: Deploy captive polymer compounding capabilities to defend margin structure against Asian contract manufacturer price aggression in standard winged needle segments. Accelerate robotic laser welding deployment in Stuttgart and Osaka manufacturing clusters to achieve sub-50-micron tolerance consistency that sustains oncology catheter premiums. Counter closed-system transfer device substitution threat in blood collection by bundling high flow sets with integrated securement technologies for home infusion services. For New Entrants and Emerging Players: Silicone-lined catheter specialization for biopharma clinical trial supply chains offers the most penetrable entry vector, bypassing entrenched hospital GPO relationships. Target direct-to-sponsor distribution channels with standardized vascular access device configurations meeting ISO 10993 and FDA 510(k) requirements for Phase III oncology studies. Pursue white-label manufacturing partnerships with established notified body holders to compress European market entry timelines. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists holding MDR-designated technical files and post-market surveillance infrastructure given EU regulatory enforcement acceleration. Long-term viability favors manufacturers with backward integration into polymer formulation and demonstrated FDA submission velocity. Monitor sterility assurance validation batch release timeline compression as the inflection signal distinguishing operational excellence from commodity players.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines capture oncology infusion center expansion before competitor sterilization documentation matures. |
| MDR Technical File Investment | Notified body relationships extend market access retention as EU enforcement eliminates grandfathered legacy portfolios. |
| Home Infusion Partnership | Patient-secureable catheter sets with disinfection caps capture Medicare Advantage reimbursement shift toward residential settings. |
| Biopharma Clinical Trial Supply Agreement | Direct CRO relationships bypass hospital GPO consolidation and establish silicone-lined catheter specification lock-in. |
| Robotic Laser Welding Deployment | Sub-50-micron tolerance automation reduces lot rejection rates and accelerates FDA sterility submission timelines. |
Methodological Framework
FDA 510(k) clearance databases, EU MDR notified body technical file registries, and CMS Medicare reimbursement coding records formed the secondary backbone. Primary interviews with vascular access device procurement managers at US group purchasing organizations, biomedical engineers at oncology infusion centers, regulatory affairs leads at German precision manufacturers, and GPO contracts managers validated demand assumptions. Bottom-up and top-down triangulation reconciled unit volume estimates with aggregate market value projections.
Bottom-up modeling aggregated procedure volume by clinical setting against high flow needle set consumption intensity per procedure, while top-down analysis tracked manufacturer revenue disclosures and distributor shipment patterns. Segmentation dimensions included product type, end user, material composition, and application across the analysis window. CAGRs derived from regression analysis of historical procedural volume growth and reimbursement rate trajectories. Forecast inputs incorporated Medicare bundling policy shifts, ambulatory surgery center construction permits, and biopharma clinical trial pipeline expansion.
Several conditions sit outside the modeled scope, including tariff rate volatility on Asian-sourced stainless steel tubing, sudden FDA sterility guidance revisions, and pandemic-era supply chain disruption recurrence. Forecasts reflect documented assumptions regarding regulatory timeline stability and reimbursement policy continuity. Material deviation in EU MDR enforcement intensity or Medicare Advantage home health benefit expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Global Laparoscopic Instruments Market