
 North America Adult Incontinence Products Market | 2026-2036
North America Adult Incontinence Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Adult Incontinence Products Market Analytics
Midwestern absorbent hygiene manufacturing capacity is rebalancing toward higher-output lines serving institutional buyers. Kimberly-Clark Corporation leverages its integrated pulp-to-pad supply chain to sustain margin stability across volatile raw material cycles. Essity AB anchors its North American position through specialized output for long-term care chains, while First Quality Enterprises, Inc. competes aggressively on private-label volume for pharmacy and supermarket channels.
Adult incontinence products comprise absorbent hygiene articles engineered with superabsorbent polymer cores, acquisition distribution layers, and breathable backsheet films designed to manage moderate-to-heavy urinary or fecal leakage in non-infant populations. These products serve medical, post-surgical, and age-related continence management needs across institutional and domestic settings. Protective underwear and disposable briefs command the largest share of the product type dimension, with protective underwear showing the fastest structural expansion as ambulatory users prioritize discretion and normalcy. The end user split reveals home care as the deepest margin pool, where recurring subscription-style purchasing and insurance reimbursement complexity create stickier supplier relationships than transactional retail or hospital procurement.
FDA medical device regulations govern absorbency claims and biocompatibility testing for products marketed with therapeutic intent, while EPA guidelines on fluff pulp bleaching and wastewater discharge constrain upstream environmental profiles. OSHA workplace standards in U.S. manufacturing facilities further shape production economics through dust control and chemical exposure protocols. Stakeholders must monitor how state-level Medicaid reimbursement rate adjustments and Medicare Advantage supplemental benefit expansions redistribute purchasing power between retail consumers and institutional buyers.
Market Dynamics
Medicaid reimbursement compression across U.S. states is forcing manufacturers to absorb margin erosion while maintaining output volumes for institutional buyers locked into multi-year supply agreements.
Growth Catalysts
- Medicare Advantage supplemental benefits:Private insurers in the United States now bundle incontinence supplies as covered benefits, redirecting purchasing volume from cash-pay retail toward reimbursed channels.
- Superabsorbent polymer formulation advances:Next-generation SAP cores with optimized cross-linking densities enable thinner profiles without absorbency sacrifice, meeting consumer preference for discretion.
- Great Lakes manufacturing corridor concentration:Integrated pulp-to-conversion facilities in Wisconsin and Michigan reduce logistics costs for bulk institutional shipments serving long-term care networks.
Market Restraints
- Fluff pulp price volatility:Softwood pulp contracts tied to Scandinavian and Brazilian supply sources expose margins to currency and freight fluctuations beyond producer control.
- FDA 510(k) clearance timelines:Products marketed with therapeutic absorbency claims face extended premarket review cycles averaging 180 days, delaying revenue recognition.
- Reusable garment substitution:Washable absorbent underwear with antimicrobial textile treatments gains traction among environmentally motivated home care users with laundering capacity.
Strategic Opportunities
- Canadian home care expansion:Provincial health authorities in Ontario and British Columbia are tendering centralized procurement contracts for community-based aging-in-place programs.
- Direct-to-consumer subscription channels:Automated replenishment platforms bypass pharmacy markups while capturing patient data for personalized absorbency recommendations.
- OSHA-compliant automation:Dust control and chemical exposure protocols drive capital investment in robotic stacking and packaging lines, reducing per-unit labor costs.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face backlog at certified laboratories, delaying product launches for novel backsheet adhesives.
- Legacy ERP integration:Long-term care chain customers demand EDI connectivity for automated reordering, forcing mid-tier suppliers to replace outdated inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Adult Incontinence Products Market |
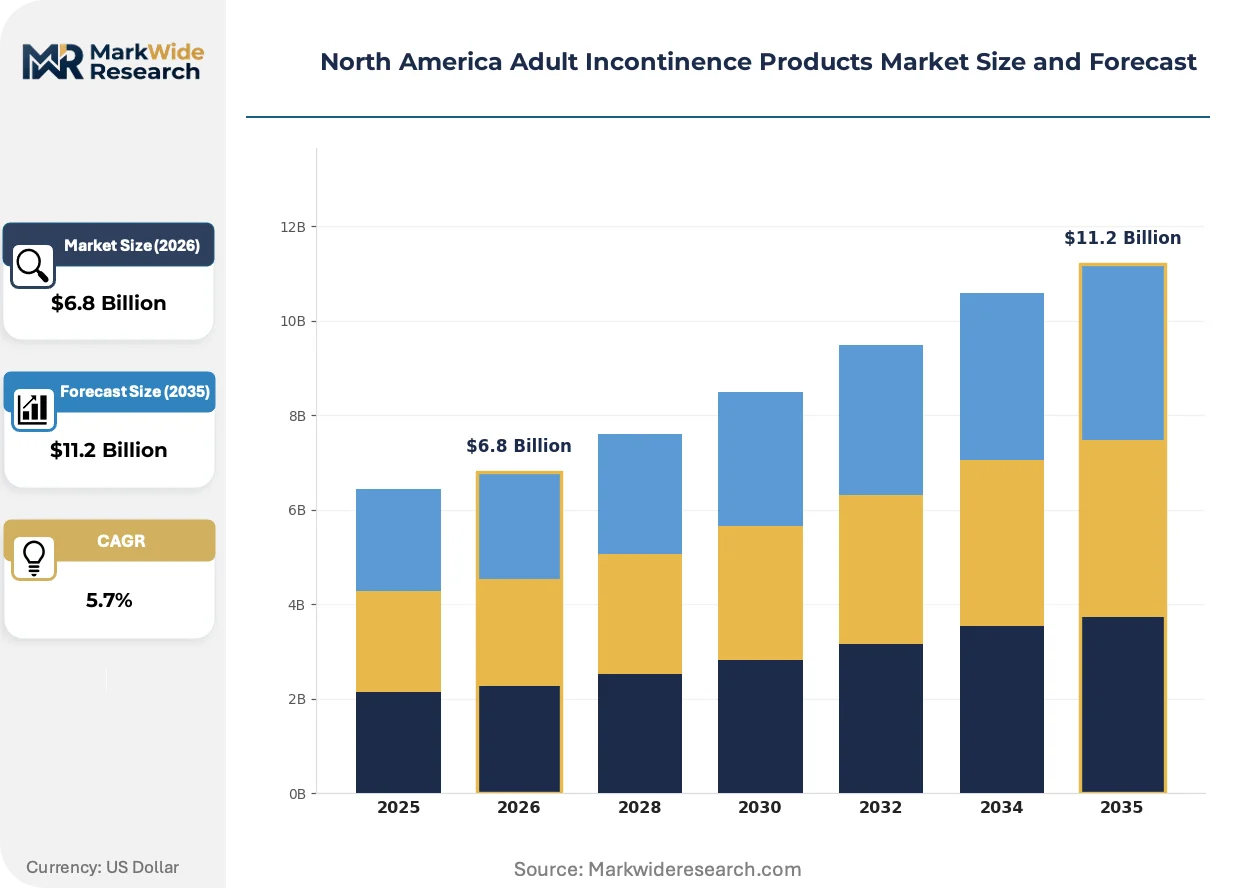
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Briefs, Pads, Protective Underwear, Bed Protectors End User: Healthcare Facilities, Home Care, Retail Consumers, Assisted Living Distribution Channel: Online Retail, Supermarkets, Pharmacies, Medical Supply Stores Price Tier: Economy, Mid-Range, Premium, Budget |
| Companies Covered | The Procter & Gamble Company, Kimberly-Clark Corporation, Essity AB, Cardinal Health, Inc., Ontex Group, First Quality Enterprises, Inc., Domtar Corporation, Medline Industries, LP, Principle Business Enterprises, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Adult Incontinence Products Market Evolving Landscape
Product architecture is thinning while functional performance intensifies, driven by polymer science breakthroughs and regulatory pressure on environmental claims.
Advanced superabsorbent polymers with gradient-density core structures are rewriting absorbency-to-bulk ratios. Ambulatory users in the home care segment adopt these profiles fastest, compressing demand for traditional thick brief designs in the premium channel.
EPA wastewater discharge guidelines for fluff pulp bleaching operations are tightening effluent standards. Mills serving the hygiene sector invest in oxygen-delignification and closed-loop systems, raising input costs that concentrate among non-integrated converters lacking captive pulp supply.
Subscription-based replenishment is displacing episodic pharmacy purchasing among reimbursed home care users. Automated reorder platforms with insurance pre-authorization integration capture recurring revenue in the Southeastern distribution hub anchored by Atlanta, while independent retailers lose walk-in traffic.
North America Adult Incontinence Products Market Segmentation
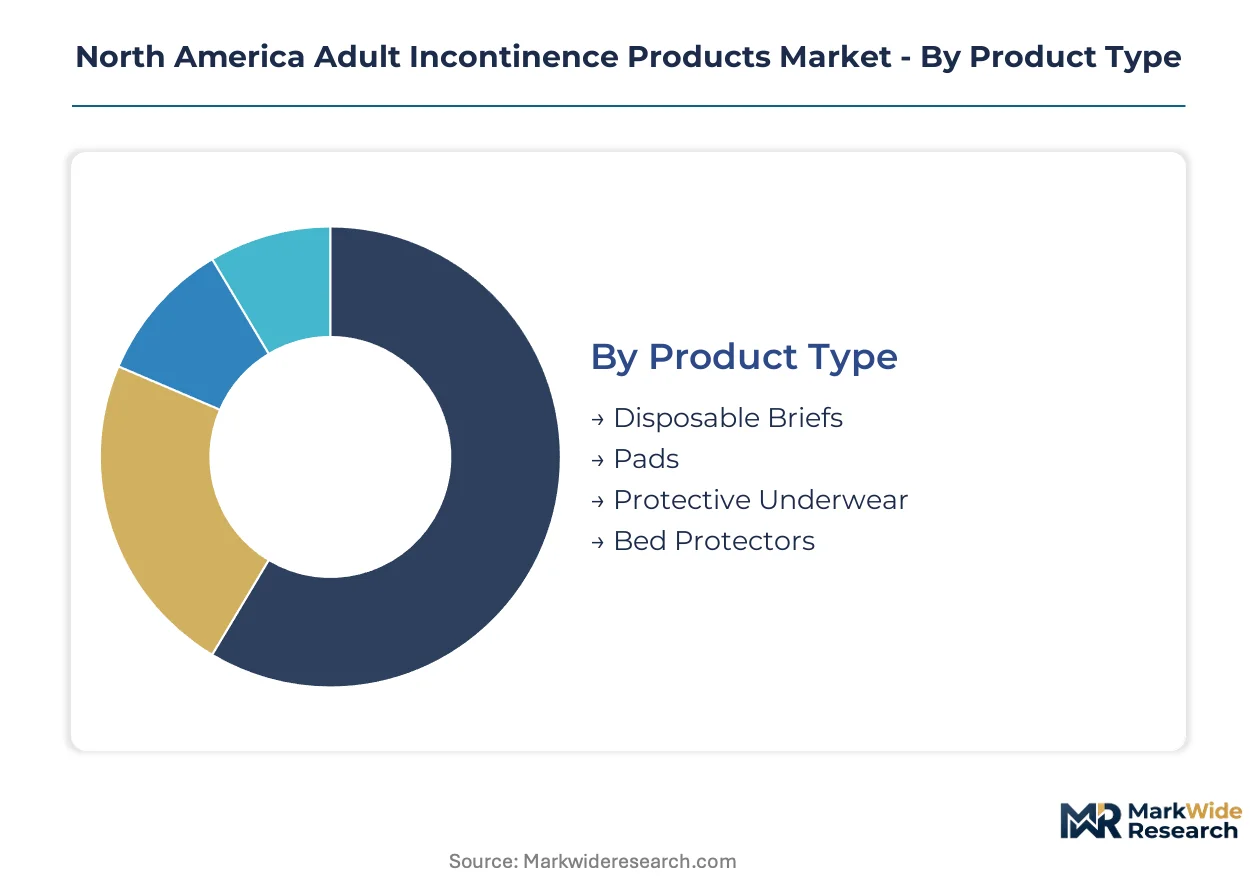
Segmentation in the North America Adult Incontinence Products Market reveals how product architecture, purchasing context, and channel economics split demand across distinct margin profiles. Each dimension carries implications for supply chain configuration and regulatory exposure.
Product Type:
Disposable briefs and protective underwear function as standalone solutions for heavy incontinence, while pads and bed protectors embed into broader hygiene routines or institutional protocols.
- Disposable Briefs:Tab-style designs with refastenable closures and superabsorbent polymer cores serve non-ambulatory patients in long-term care. Demand concentrates in the Southeastern distribution hub anchored by Atlanta, where Medicaid-funded nursing home networks purchase through centralized procurement.
- Protective Underwear:Pull-up designs with elastic waistbands and breathable side panels prioritize discretion for ambulatory home care users. Ontario and British Columbia provincial health authorities are expanding reimbursed access through community-based aging-in-place programs.
- Pads:Rectangular or contoured inserts with adhesive strips supplement lighter incontinence management within standard underwear. Retail pharmacy chains in the Great Lakes manufacturing corridor stock these as high-velocity SKUs.
- Bed Protectors:Waterproof underpads with absorbent cores and vapor-permeable backings protect mattress surfaces in home and institutional settings. Hospital discharge planners bundle these with brief prescriptions.
Volume placements concentrate in Disposable Briefs; the faster expansion belongs to Protective Underwear.
End User:
Cost tier and reimbursement complexity separate institutional buyers with negotiated supply agreements from cash-pay retail consumers managing out-of-pocket expenses.
- Healthcare Facilities:Acute care hospitals and skilled nursing facilities purchase through GPO contracts with stringent FDA biocompatibility documentation requirements. Medicare Advantage supplemental benefits are redirecting some post-acute volume toward reimbursed home delivery.
- Home Care:Family caregivers and paid home health aides represent the deepest margin pool, with recurring subscription-style purchasing and insurance pre-authorization complexity creating stickier supplier relationships. Automated replenishment platforms are displacing episodic pharmacy purchasing in this segment.
- Retail Consumers:Cash-pay buyers at supermarkets and pharmacies prioritize shelf visibility and unit pricing over clinical performance claims. Independent retailers are losing walk-in traffic to direct-to-consumer channels.
- Assisted Living:Residential care operators with semi-private rooms balance resident dignity preferences against bulk procurement economics. Wisconsin and Michigan integrated pulp-to-conversion facilities reduce logistics costs for these mid-volume institutional shipments.
Healthcare Facilities dominate current volume; Home Care is climbing the fastest as aging-in-place preferences harden.
Distribution Channel:
Channel selection determines margin capture, with online retail bypassing pharmacy markups while medical supply stores retain complex reimbursement processing capabilities.
- Online Retail:Direct-to-consumer platforms with automated replenishment and insurance pre-authorization integration capture recurring revenue and patient data for personalized absorbency recommendations.
- Supermarkets:Mass merchandisers compete on private-label volume and shelf space allocation, with Georgia and Florida distribution centers serving the Southeastern hub.
- Pharmacies:Chain drugstores with prescription counters handle Medicare Part B and Medicaid fee-for-service reimbursement workflows, though walk-in traffic is eroding.
- Medical Supply Stores:Durable medical equipment dealers with certified fitters serve complex cases requiring therapeutic absorbency claims and FDA 510(k) cleared products.
Pharmacies retain the largest volume footprint; Online Retail is gaining share fastest through subscription conversion.
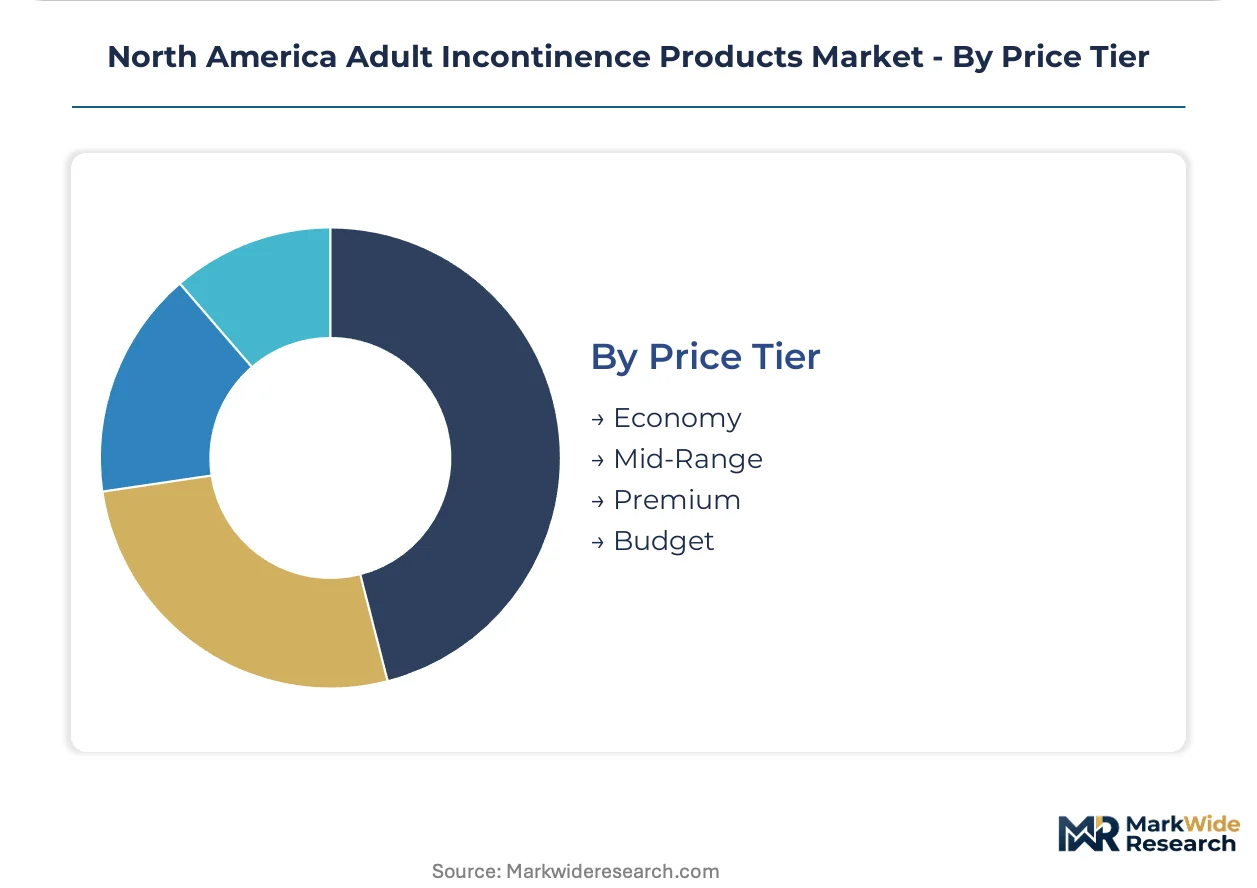
Price Tier:
Raw material integration depth and SAP formulation sophistication separate premium performance claims from economy positioning in competitive retail environments.
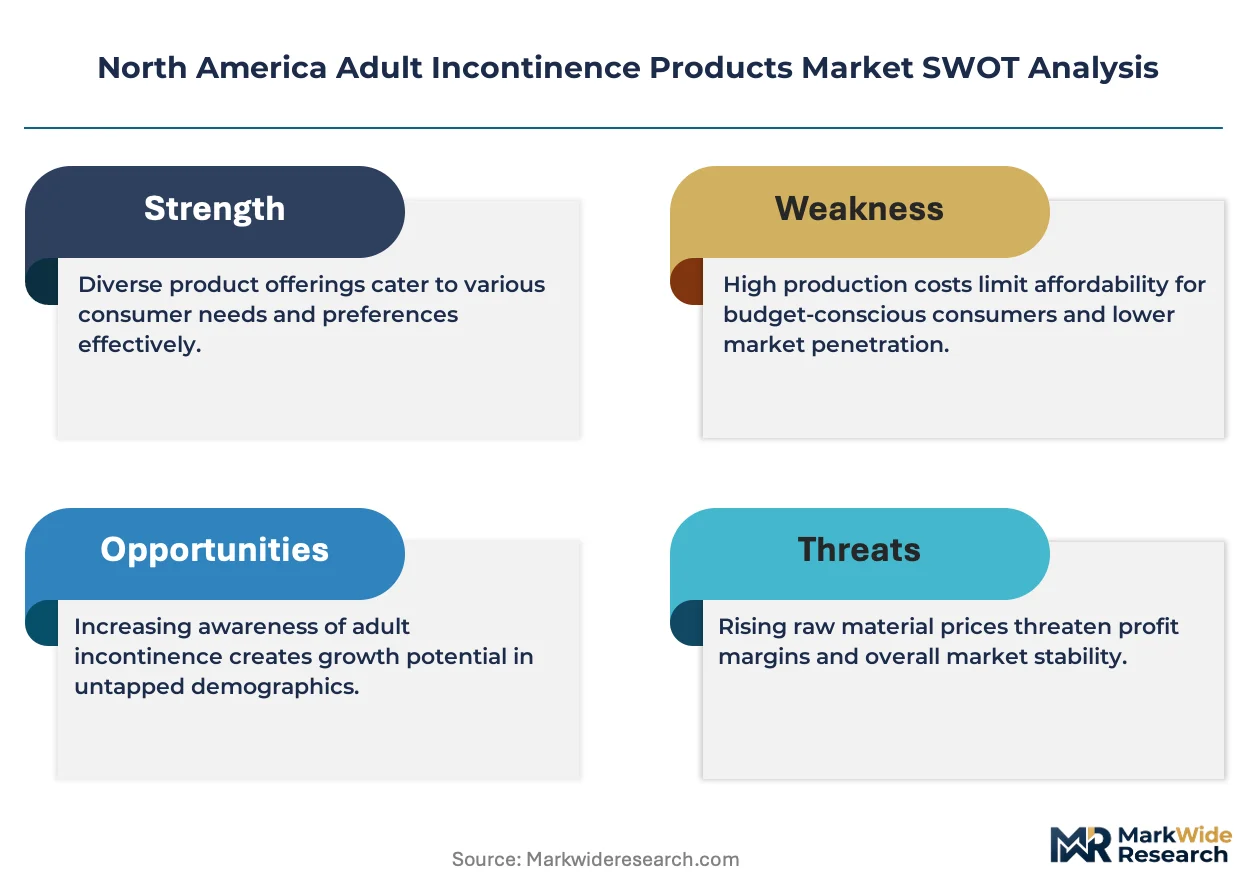
- Premium:Gradient-density SAP cores with optimized cross-linking densities and breathable backsheet films command price premiums for discretion and skin health claims.
- Mid-Range:Balanced absorbency-to-bulk ratios target reimbursed home care users with insurance coverage limits.
- Economy:Basic fluff pulp constructions with standard polypropylene backings serve price-sensitive institutional buyers locked into multi-year supply agreements.
- Budget:Thin-profile designs with reduced SAP loading compete for shelf space in dollar stores and discount chains.
Economy tier holds the greatest shipment volume; Premium is expanding most quickly as ambulatory users prioritize discretion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Softwood pulp mills in the Great Lakes basin anchor North American absorbent hygiene supply chains. Wisconsin and Michigan conversion corridors process this feedstock into finished briefs and protective underwear for institutional and home care distribution networks.
United States
Medicare Advantage supplemental benefit expansions redirect home care purchasing from cash-pay retail toward reimbursed channels. FDA medical device regulations govern absorbency claims and biocompatibility testing for therapeutic-grade products. The Southeastern distribution hub anchored by Atlanta concentrates Medicaid-funded nursing home procurement through centralized GPO contracts.
Canada
Provincial health authorities in Ontario and British Columbia tender centralized procurement for community-based aging-in-place programs. Health Canada and PMRA regulate medical device licensing and environmental discharge from pulp bleaching operations. Quebec-based integrated pulp-to-pad facilities serve Atlantic Canada long-term care networks with reduced freight exposure.
Mexico
Cross-border maquiladora operations near the Tijuana-San Diego corridor assemble components for U.S. retail private-label programs. Mexican environmental regulators enforce wastewater standards on imported fluff pulp processing. Nuevo León manufacturing parks attract hygiene converters seeking duty-advantaged access to Texas distribution centers.
North America Adult Incontinence Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and specialized institutional contracting. The vendor base clusters around three archetypes: integrated pulp-to-pad manufacturers with captive raw material supply, private-label specialists serving pharmacy and supermarket channels, and medical supply distributors with reimbursement processing capabilities. Capacity expansion and strategic partnerships dominate competitive moves, with players securing long-term care chain agreements and automating production lines to meet OSHA dust control mandates.
Within the integrated manufacturer tier, Kimberly-Clark Corporation and Essity AB exemplify scale-driven positioning through captive supply chain control. First Quality Enterprises, Inc. represents the private-label specialist archetype, competing on volume throughput for retail channels. These three anchors illustrate how raw material integration depth separates premium performance claims from economy positioning in institutional procurement.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Kimberly-Clark Corporation |
| Essity AB |
| Cardinal Health, Inc. |
| Ontex Group |
| First Quality Enterprises, Inc. |
| Domtar Corporation |
| Medline Industries, LP |
| Principle Business Enterprises, Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters with multi-generational ownership in Wisconsin and Michigan exercise pricing discipline through captive fluff pulp supply, insulating institutional contract rates from Scandinavian spot-market volatility while pressuring non-integrated competitors.
Pricing Analysis
Warranty and fit-guarantee bundling separates medical supply stores from transactional retail, with certified fitter consultations and Medicaid pre-authorization support justifying markup capture over supermarket private-label alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by SAP core density and breathability certification, with FDA 510(k) therapeutic claims commanding the widest spreads. Cost compression in the economy tier intensifies because Medicaid reimbursement compression across U.S. states forces manufacturers to absorb margin erosion on locked multi-year nursing home contracts. Retail consumers exhibit highest price sensitivity, while reimbursed home care users with Medicare Advantage supplemental benefits show lowest sensitivity due to insurance pre-authorization integration.
Supply Chain Analysis
Freight cost optimization drives concentration of integrated pulp-to-pad facilities in Wisconsin, Michigan, and Georgia, with Great Lakes basin softwood mills feeding conversion corridors that serve the Southeastern distribution hub anchored by Atlanta. Raw material dependencies center on Scandinavian and Brazilian fluff pulp contracts, superabsorbent polymer resin from Gulf Coast petrochemical complexes, and breathable polyethylene backsheet films. Single-source vulnerability in Scandinavian pulp supply exposes margins to currency and freight fluctuations beyond producer control. Distribution runs through GPO-contracted institutional channels for healthcare facilities, direct-to-consumer subscription platforms for home care, and mass merchandiser private-label programs for retail consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medicaid reimbursement compression across U.S. states is accelerating consolidation, forcing mid-tier converters without captive pulp supply or automated OSHA-compliant lines into distressed sales or exit.
For Market Incumbents: Anchor margin stability through backward integration into fluff pulp processing or robotic packaging automation that satisfies OSHA dust control mandates. Defensive consolidation moves include acquiring distressed private-label specialists in the Great Lakes corridor and securing exclusive long-term care chain agreements before Medicare Advantage supplemental benefits fully redirect volume toward reimbursed home delivery channels. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms with insurance pre-authorization integration represent the most penetrable white-space target, particularly in Ontario and British Columbia where provincial health authorities are tendering centralized community-based aging-in-place contracts. New entrants should pursue white-label manufacturing partnerships with Wisconsin-based integrated producers to bypass capital-intensive pulp procurement, then differentiate through automated replenishment algorithms and patient data capture for personalized absorbency recommendations. For Investors and Strategic Acquirers: Distressed-cycle entries favor non-integrated converters with established GPO relationships and FDA 510(k) cleared product portfolios in the Southeastern distribution hub anchored by Atlanta. Long-term viability hinges on five-to-ten year Medicare Advantage penetration trajectories and pulp price normalization. The critical inflection signal to watch is state-level Medicaid reimbursement rate adjustments that redistribute purchasing power between institutional buyers and reimbursed home care channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluff Pulp Processing | Captive supply from Wisconsin mills insulates margin stability from Scandinavian spot-market volatility. |
| Robotic Packaging Automation | OSHA-compliant dust control lines reduce per-unit labor costs while satisfying workplace exposure mandates. |
| Direct-to-Consumer Subscription Launch | Automated replenishment platforms with Medicare Advantage integration capture recurring revenue from reimbursed home care users. |
| Provincial Health Authority Contracting | Centralized procurement tenders in Ontario and British Columbia open reimbursed channels for community-based aging-in-place programs. |
| FDA 510(k) Therapeutic Claim Pathway | Premarket clearance for absorbency claims enables premium pricing in medical supply stores over retail pharmacy alternatives. |
Research Methodology
Multi-period observation of Medicaid reimbursement rate adjustments, Medicare Advantage supplemental benefit expansions, and fluff pulp contract pricing anchored the trend analysis, supplemented by interviews with GPO contracts managers, long-term care procurement directors, home health agency operators, and FDA regulatory affairs specialists. Secondary validation drew from CMS Medicare data, state Medicaid fee-for-service schedules, hospital procurement databases, and SEC 10-K filings of integrated hygiene manufacturers. Bottom-up volume modeling across product type, end user, distribution channel, and price tier dimensions was triangulated against top-down macroeconomic indicators.
Input-output matrices mapped SAP core formulation costs, fluff pulp input prices, and logistics expenditure indices to finished product pricing across the projection horizon. Segmentation dimensions modeled included product architecture, purchasing context, reimbursement complexity, and regional regulatory cluster. CAGRs were derived through regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated FDA 510(k) clearance timeline distributions and provincial health authority tender award patterns.
Caveats apply where FDA premarket review backlog extensions, Scandinavian pulp supply disruptions, or state-level Medicaid rate freezes could materially shift the outlook. Forecasts reflect documented assumptions about Medicare Advantage penetration speed and raw material price normalization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Nursing Products Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Organ Care Products Market