
 Global Hernia Repair Market | 2026-2036
Global Hernia Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hernia Repair Market Foresight
Mesh biocompatibility grade upgrades is redrawing procurement criteria across the Global Hernia Repair Market. Medtronic plc leverages its synthetic polymer portfolio to dominate ventral hernia mesh supply chains. Ethicon Inc. anchors its position through sustained R&D intensity in absorbable barrier technologies. B. Braun SE differentiates via geographic dominance across European hospital purchasing networks.
Hernia repair encompasses surgical restoration of abdominal wall defects using implantable meshes, fixation hardware, and closure systems, with polypropylene and composite barrier materials serving as the primary structural substrates to reinforce tissue while preventing visceral adhesion. The procedure's commercial purpose centers on reducing recurrence rates below native tissue repair thresholds. Mesh implants command the largest revenue pool due to recurring replacement cycles and premium composite pricing, while robotic-assisted surgery represents the fastest-growing delivery mode as capital equipment amortization accelerates across consolidated hospital systems. Ambulatory surgical centers are capturing volume share from inpatient settings as same-day discharge protocols standardize for inguinal and umbilical procedures.
The FDA enforces 510(k) clearance pathways with escalating biocompatibility testing for permanent synthetic meshes, while the EU Medical Device Regulation mandates enhanced clinical evidence under updated classification rules. Japan's PMDA imposes additional local bridging studies for imported mesh products, extending market access timelines. Stakeholders must monitor evolving reimbursement thresholds for robotic-assisted hernia repair as health technology assessment bodies in Germany and France recalibrate procedure tariffs.
Market Dynamics
Mesh biocompatibility grade upgrades are redrawing procurement criteria across hospital purchasing networks, forcing manufacturers to requalify polypropylene and composite barrier materials under escalating regulatory thresholds before contract renewal cycles.
Growth Catalysts
- EU Medical Device Regulation:Enhanced clinical evidence requirements under updated classification rules are accelerating R&D investment in next-generation composite meshes with superior adhesion resistance.
- Robotic-assisted surgery:Capital equipment amortization across consolidated US hospital systems is expanding addressable procedure volumes for complex ventral hernia repairs.
- Ambulatory surgical centers:Same-day discharge protocol standardization in Germany and Japan is shifting inguinal hernia volume toward outpatient settings with faster implant turnover.
Market Restraints
- Polypropylene raw material concentration:Petrochemical feedstock volatility and specialized polymer grade scarcity constrain margin flexibility for synthetic mesh producers.
- PMDA bridging study requirements:Japan's local clinical evidence mandates extend market access timelines by 18-24 months for imported mesh products.
- Biologic mesh substitution:Patient-specific factors and surgeon preference for autologous tissue repair limit addressable market expansion in select procedure categories.
Strategic Opportunities
- Absorbable barrier technology:Convergence of synthetic polymer engineering with bioabsorbable coating systems creates premium pricing tiers for recurrence-risk reduction.
- Rural hospital networks:Underpenetrated surgical infrastructure in India and Brazil offers volume expansion for standardized mesh kits with simplified fixation protocols.
- Direct-to-ASC distribution:Bypassing traditional hospital purchasing committees through specialized ambulatory supply channels captures faster decision cycles.
Industry Challenges
- Laparoscopic certification pipelines:Surgeon training program bottlenecks constrain robotic-assisted procedure rollout speed despite capital equipment availability.
- 510(k) biocompatibility testing backlogs:FDA clearance pathway congestion delays product iteration cycles for modified mesh geometries.
- Legacy ERP integration:Hospital supply chain systems require custom API development to track implant lot numbers under evolving traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hernia Repair Market |
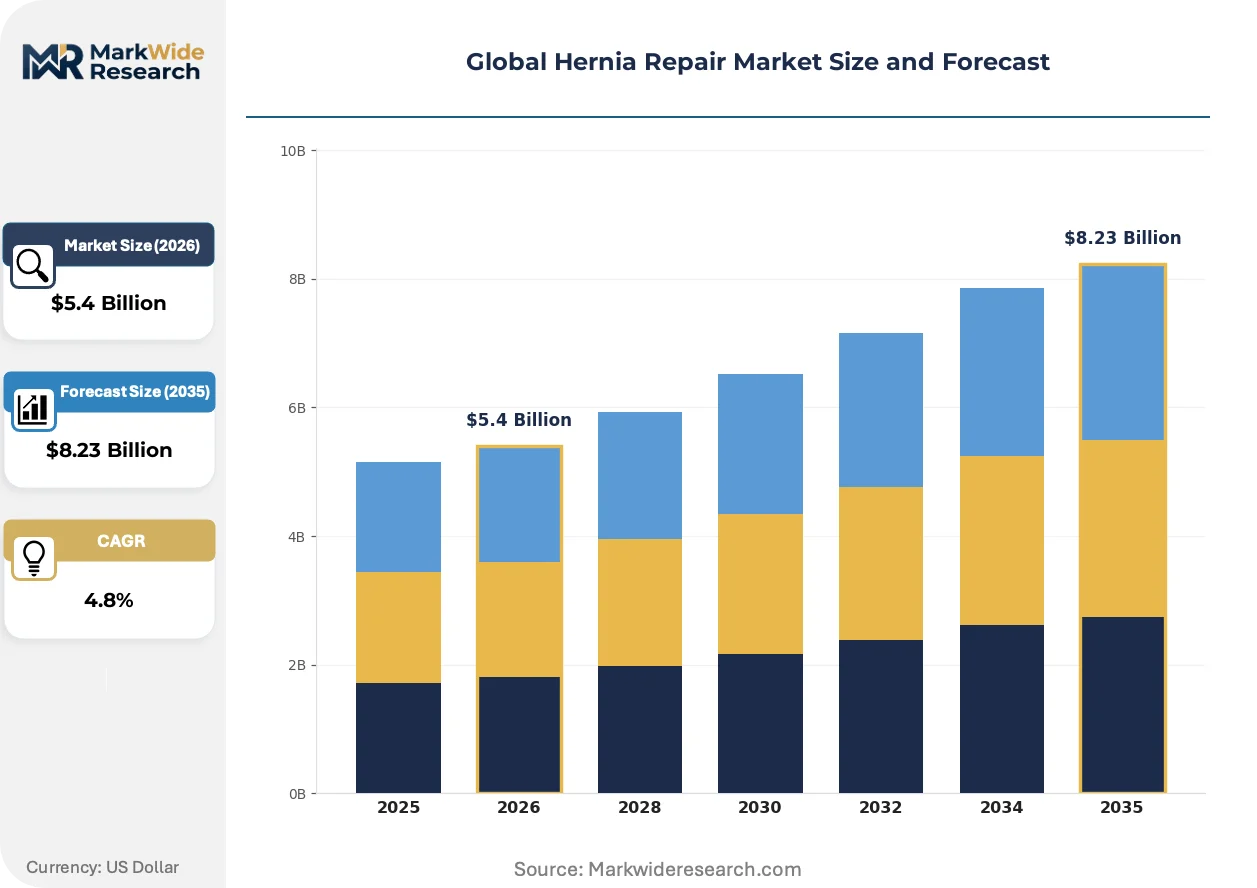
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh Implants, Sutures, Surgical Mesh, Fixation Devices, Hernia Patches Application: Inguinal Hernia, Incisional Hernia, Umbilical Hernia, Femoral Hernia, Hiatal Hernia End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Multi-specialty Clinics Delivery Mode: Open Surgery, Laparoscopic Surgery, Robotic-assisted Surgery, Minimally Invasive Surgery |
| Companies Covered | Medtronic plc, Ethicon Inc., Becton Dickinson and Company, B. Braun SE, W. L. Gore & Associates, Cook Medical, AbbVie Inc., Integra LifeSciences, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hernia Repair Market Shifts & Advancements
Three intersecting forces are restructuring competitive positioning: composite material science advances, regulatory evidence bar elevation, and site-of-care migration toward outpatient delivery models.
Self-fixating mesh designs incorporating integrated adhesive layers are fragmenting the traditional fixation hardware attachment market. Ambulatory surgical centers in the United States and Germany are adopting these systems at twice the rate of inpatient facilities. The technology is fragmenting procurement bundles that previously combined mesh implants with mechanical tacking devices.
REACH chemical substance restrictions and the EU Medical Device Regulation's updated classification rules are forcing reformulation of polypropylene catalyst residues and barrier coating chemistries. Manufacturers face requalification costs for existing product lines. Composite barrier meshes with permanent synthetic substrates face the steepest compliance burden in European notified body reviews.
Hospital purchasing committees are consolidating vendor contracts around full-procedure kits rather than discrete component sourcing. This behavior compresses standalone mesh and fixation device markets into bundled supply agreements. The shift is most visible in German and Japanese hospital systems where procurement centralization has advanced furthest.
Global Hernia Repair Market Segmentation
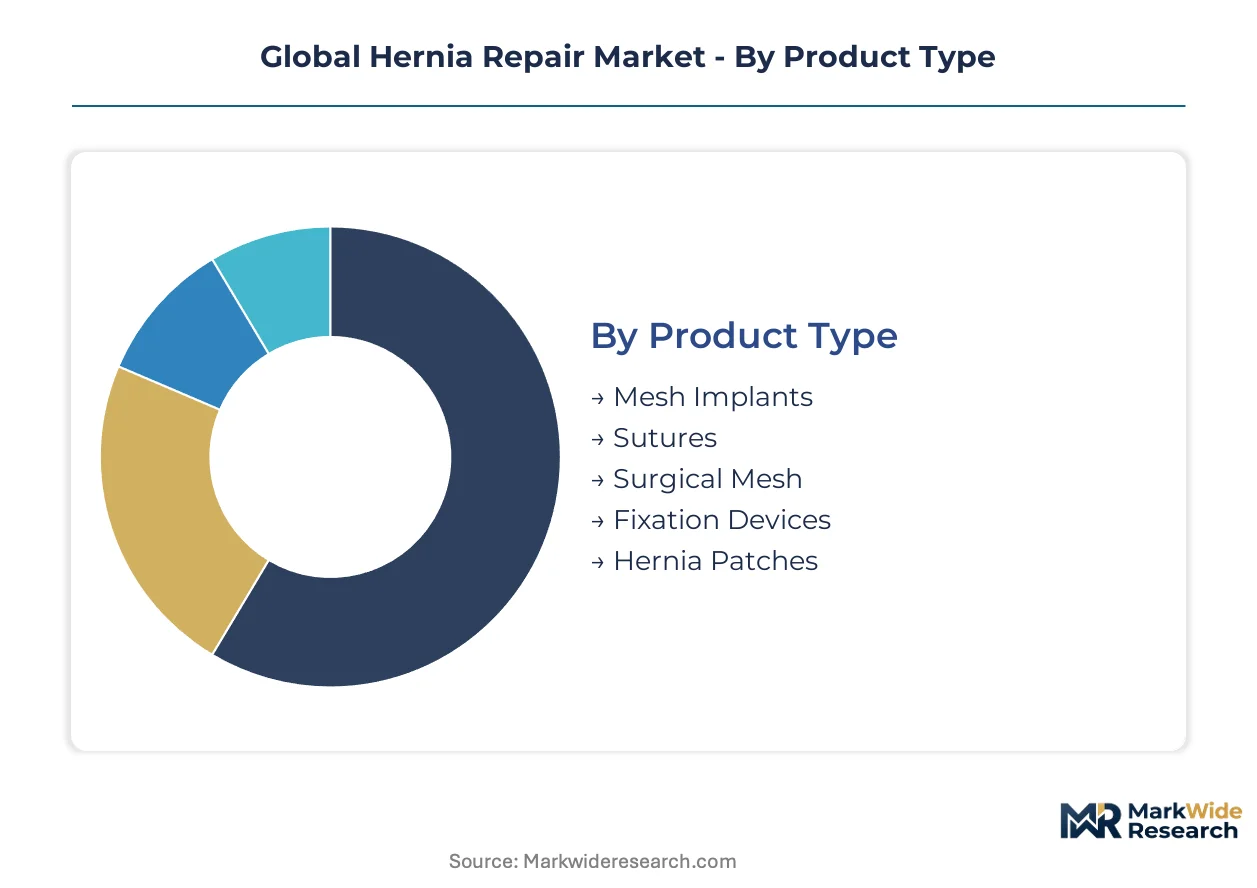
Segmentation in hernia repair reveals how procurement power, reimbursement pathways, and surgical training pipelines concentrate demand across distinct product and delivery categories. Each dimension carries different margin profiles and regulatory exposure.
Product Type:
FDA 510(k) clearance pathways and EU MDR classification rules create divergent compliance burdens across implantable versus non-implantable categories, reshaping manufacturer portfolio priorities.
- Mesh Implants:Permanent synthetic substrates—primarily polypropylene and composite barrier constructions—serve as the structural backbone for tension-free hernia repair. United States hospital purchasing committees dominate procurement volume for these devices, driven by bundled payment incentives that favor durable, recurrence-resistant materials.
- Fixation Devices:Mechanical tacking systems and absorbable fasteners secure mesh placement during laparoscopic and robotic procedures. German ambulatory surgical centers concentrate demand for these products, where same-day discharge protocols require rapid, reliable fixation to minimize operative time.
- Sutures:Absorbable and non-absorbable closure materials complement mesh reinforcement in selected repair techniques.
- Surgical Mesh:Biologic and biosynthetic alternatives address patient-specific contraindications to synthetic materials.
- Hernia Patches:Pre-shaped, self-fixating designs reduce operative complexity in standard inguinal repairs.
Mesh implants handle the majority of throughput; fixation devices are expanding most quickly on share as laparoscopic penetration deepens.
Application:
Recurrence risk profiles and reimbursement tiering stratify procedure economics, with complex ventral repairs commanding premium device pricing versus high-volume inguinal standards.
- Inguinal Hernia:The most prevalent abdominal wall defect type drives the highest absolute procedure volume globally. Japan's aging surgical population and established laparoscopic training infrastructure concentrate demand for tension-free mesh repair in this category.
- Incisional Hernia:Post-surgical defect repairs require larger mesh surfaces and more complex fixation strategies. United States consolidated hospital systems generate disproportionate volume here, where robotic-assisted platforms enable precise closure of challenging midline defects.
- Umbilical Hernia:Pediatric and adult presentations favor smaller mesh formats and simpler fixation protocols.
- Femoral Hernia:Lower prevalence and higher strangulation risk drive emergency procedure patterns with limited device selection time.
- Hiatal Hernia:Gastroesophageal junction repairs involve specialized mesh geometries and anti-reflux considerations.
Inguinal hernia repairs absorb the largest device volume; incisional hernia applications generate the steepest expansion trajectory as obesity-related surgical histories accumulate.
End User:
Capital equipment requirements and anesthesia infrastructure determine site-of-care eligibility, fragmenting purchasing authority between centralized hospital committees and decentralized ASC procurement officers.
- Hospitals:Inpatient facilities retain dominance for complex ventral and recurrent hernia repairs requiring extended monitoring. Germany's integrated hospital networks concentrate purchasing power through centralized tender processes that favor full-procedure kit contracts.
- Ambulatory Surgical Centers:Outpatient settings capture inguinal and umbilical volume through streamlined same-day protocols. United States Medicare reimbursement shifts accelerate ASC market share gains in standardized hernia categories.
- Specialty Clinics:Hernia-focused surgical practices in Brazil and India operate limited-procedure suites with selective mesh stocking.
- Multi-specialty Clinics:General surgery departments within larger clinic systems handle lower-acuity repairs with constrained device formularies.
Hospitals retain the dominant throughput position; ambulatory surgical centers are climbing the fastest on volume share as payer incentives realign.
Delivery Mode:
Surgeon certification pipelines and capital amortization schedules create friction in technique adoption, segmenting addressable procedure pools by institutional infrastructure investment.
- Laparoscopic Surgery:Minimally invasive techniques through multi-port or single-incision approaches have achieved standard-of-care status in inguinal hernia repair. Japanese surgical societies have driven particularly deep penetration through structured training mandates and equipment subsidies.
- Robotic-assisted Surgery:Da Vinci and competing platforms enable precise mesh placement in complex ventral repairs. United States hospital systems with amortized capital bases are expanding robotic hernia volumes fastest as fixed costs spread across growing procedure denominators.
- Open Surgery:Traditional incision techniques persist in emergency presentations and resource-constrained settings.
- Minimally Invasive Surgery:Umbrella category capturing evolving techniques between standard laparoscopy and full robotic platforms.
Laparoscopic surgery handles the majority of current throughput; robotic-assisted surgery is gaining share fastest as training pipelines mature and capital costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialized polypropylene grades tilts trade balances toward petrochemical-exporting nations while finished mesh device exports concentrate in established manufacturing clusters. The United States, Germany, Japan, and India absorb the majority of procedural volume, with regulatory stringency and reimbursement structures determining access timelines.
United States
Medicare reimbursement shifts toward ambulatory surgical centers accelerate same-day discharge protocols for inguinal repairs. The FDA enforces escalating 510(k) biocompatibility testing requirements for permanent synthetic meshes. Minneapolis-based purchasing networks consolidate vendor contracts around full-procedure kits, compressing standalone component markets.
Germany
Integrated hospital networks centralize tender processes that favor durable composite barrier meshes with enhanced adhesion resistance. The EU Medical Device Regulation mandates requalification of existing product lines under updated classification rules. Bavarian surgical clusters drive adoption of self-fixating designs that fragment traditional fixation hardware markets.
Japan
Aging surgical populations and established laparoscopic training infrastructure concentrate demand for tension-free mesh repair. PMDA bridging study requirements extend market access timelines by 18-24 months for imported products. Tokyo-Osaka metropolitan corridors generate disproportionate volume for robotic-assisted ventral hernia procedures.
India
Rural hospital network expansion creates volume opportunities for standardized mesh kits with simplified fixation protocols. CDSCO import licensing requirements and local clinical evidence thresholds moderate foreign manufacturer penetration. Maharashtra and Gujarat surgical hubs absorb the majority of domestic procedural growth as private hospital chains consolidate.
Global Hernia Repair Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage synthetic polymer portfolios and geographic purchasing network dominance. Three archetypes define competitive positioning: integrated polymer-to-device manufacturers, specialized surgical mesh developers, and regional hospital supply distributors. M&A activity targets absorbable barrier technology capabilities, while strategic partnerships with ambulatory surgical center chains bypass traditional hospital procurement committees.
Within the integrated conglomerate tier, Medtronic plc and Ethicon Inc. exemplify archetypes that anchor supply chain control through captive polymer sourcing and sustained R&D intensity in composite barrier formulations. B. Braun SE occupies a position representing European geographic dominance through consolidated hospital purchasing network relationships. These three entities collectively illustrate how scale-driven procurement consolidation and regulatory compliance infrastructure create defensive moats against mid-cap specialists.
| Leading Market Players |
|---|
| Medtronic plc |
| Ethicon Inc. |
| Becton Dickinson and Company |
| B. Braun SE |
| W. L. Gore & Associates |
| Cook Medical |
| AbbVie Inc. |
| Integra LifeSciences |
| Baxter International Inc. |
| Others |
Supply & Pricing Matrix
Specialized polypropylene resin capacity utilization above 85% in Texas and Rotterdam clusters concentrates polymer pricing power among three petrochemical conglomerates, compressing margin flexibility for downstream mesh converters while establishing durable price floors for medical-grade substrate contracts.
Pricing Analysis
Hospital purchasing committees anchor mesh implant pricing through multi-year procurement tenders that stratify across premium composite barrier, standard polypropylene, and economy uncoated tiers. Price differentiation rests on FDA 510(k) clearance tier and biocompatibility certification grade, with EU MDR Class III compliance commanding 15-20% premiums over legacy CE-marked equivalents. Cost compression in the economy tier intensifies as Indian and Brazilian manufacturers expand standardized kit volumes. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare bundled payment constraints, while German integrated hospital networks demonstrate lowest sensitivity through centralized tender processes that prioritize recurrence-rate performance over unit cost.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites petrochemical feedstock security for polypropylene production, with medical-grade resin supply concentrating in the United States, Germany, and Saudi Arabia. Raw material dependencies center on propylene monomer, catalyst systems for isotactic polymerization, and barrier coating chemistries subject to REACH substance restrictions. Single-source vulnerability in specialized polymer grades creates procurement exposure when notified body requalification delays interrupt contract renewals. Distribution runs through hospital purchasing committees in consolidated US systems, direct-to-ASC channels in German outpatient networks, and regional distributors in Indian private hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EU MDR compliance infrastructure and FDA 510(k) clearance backlogs create switching costs that cement incumbent positions against mid-cap challengers.
For Market Incumbents: Consolidate polymer-to-device vertical control through captive resin sourcing or long-term offtake agreements with Texas and Rotterdam petrochemical clusters. Deepen ambulatory surgical center penetration via direct distribution partnerships that bypass hospital purchasing committee bottlenecks, defending against biologic mesh substitution threats through sustained R&D in absorbable barrier coatings.
For New Entrants and Emerging Players: Self-fixating mesh design adoption gaps in rural Indian and Brazilian hospital networks offer white-space entry points where simplified fixation protocols reduce surgeon training barriers. Target standardized inguinal repair kits for ambulatory surgical centers in underpenetrated Maharashtra and Gujarat corridors, leveraging distributor partnerships with regional private hospital chains as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with absorbable barrier technology portfolios and established EU MDR technical documentation, supporting long-term viability through replacement cycle dependency. Prioritize acquisition targets with robotic-assisted surgery compatibility certifications and ASC direct-channel infrastructure. Watch PMDA bridging study timeline compression as the signal for accelerated Japanese market access and premium pricing capture.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body requalification accelerates competitive exclusion for non-compliant legacy portfolios. |
| Absorbable Barrier R&D Expansion | Premium pricing tiers emerge from recurrence-risk reduction validated in clinical evidence packages. |
| ASC Direct Distribution Partnership | Bypassing hospital purchasing committees captures faster decision cycles in Medicare-reimbursed settings. |
| Robotic-Assisted Surgery Compatibility Certification | Da Vinci platform integration opens complex ventral repair volumes in amortized US hospital systems. |
| Rural Hospital Network Kit Standardization | Simplified fixation protocols penetrate underpenetrated Indian and Brazilian surgical infrastructure. |
Research Methodology
Cross-validation between surgeon interviews and hospital procurement database analysis anchors the qualitative findings, with primary fieldwork encompassing hernia specialists, biomedical engineers, GPO contracts managers, and ASC procurement officers across the United States, Germany, and Japan. Secondary validation draws from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement filings, and hospital tender records. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue disclosures to establish segmentation integrity.
Sensitivity analysis around regulatory timeline scenarios and robotic-assisted surgery penetration curves shapes the analytical framework across the projection horizon. Segmentation dimensions model product type, application, end user, and delivery mode, with geographic regulatory cluster and reimbursement pathway as cross-cutting variables. CAGRs derive from procedure volume growth rates, device pricing trajectory assumptions, and site-of-care migration patterns informed by health technology assessment body tariff recalibrations.
Underlying assumptions cover EU MDR implementation consistency, PMDA bridging study duration stability, and petrochemical feedstock price normalization, with deviation risk concentrated in regulatory evidence requirement escalation and biologic mesh substitution acceleration. Practitioners should keep alternative scenarios live as reimbursement threshold revisions and REACH chemical restriction expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Suture Anchor Market