
 Iodine Deficiency Drug Market | 2026-2036
Iodine Deficiency Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Iodine Deficiency Drug Market Foresight
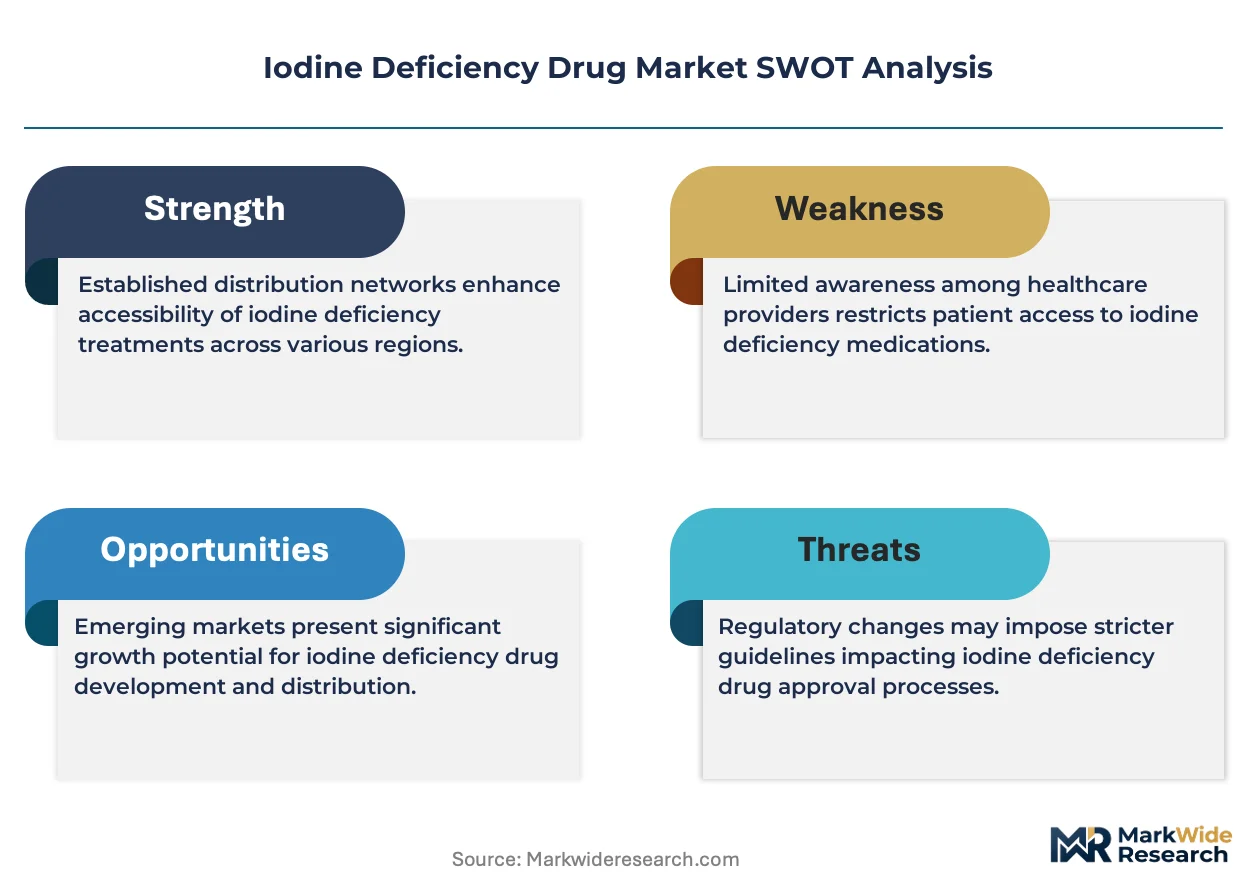
Project finance for large-scale iodine supplementation programs is tilting competitive dynamics toward manufacturers with balance-sheet capacity to absorb extended payment cycles from government tenders. Merck KGaA leverages its vertical integration into active pharmaceutical ingredient production to secure preferential contract terms. Pfizer Inc. competes through geographic dominance in Latin American public health procurement channels. Sanofi S.A. differentiates via specialized formulations for pediatric and prenatal populations with elevated bioavailability requirements.
Iodine deficiency drugs encompass potassium iodide, sodium iodide, iodine solution, and iodized salt preparations engineered to restore thyroid hormone synthesis through controlled iodine bioavailability, typically standardized to deliver microgram-level daily intake aligned with WHO nutritional thresholds. The primary commercial purpose centers on preventing endemic goiter, cretinism, and cognitive impairment in populations consuming iodine-depleted soil and water sources. Oral administration routes dominate volume flows due to cost efficiency in mass-distribution campaigns, while hospital pharmacy channels capture margin concentration through emergency thyroid-blocking applications. Home care segments are expanding fastest as over-the-counter potassium iodide registrations broaden retail accessibility.
FDA orphan drug designations and EPA environmental release protocols shape manufacturing compliance burdens for domestic producers, while WHO prequalification requirements govern access to UN agency procurement pools in low-income settings. The EU F-Gas Regulation and REACH chemical safety standards constrain iodine extraction and processing methods for suppliers serving European public health programs. Stakeholders must monitor evolving national salt iodization mandates and prequalification status changes to align inventory positioning with shifting tender eligibility criteria.
Market Dynamics
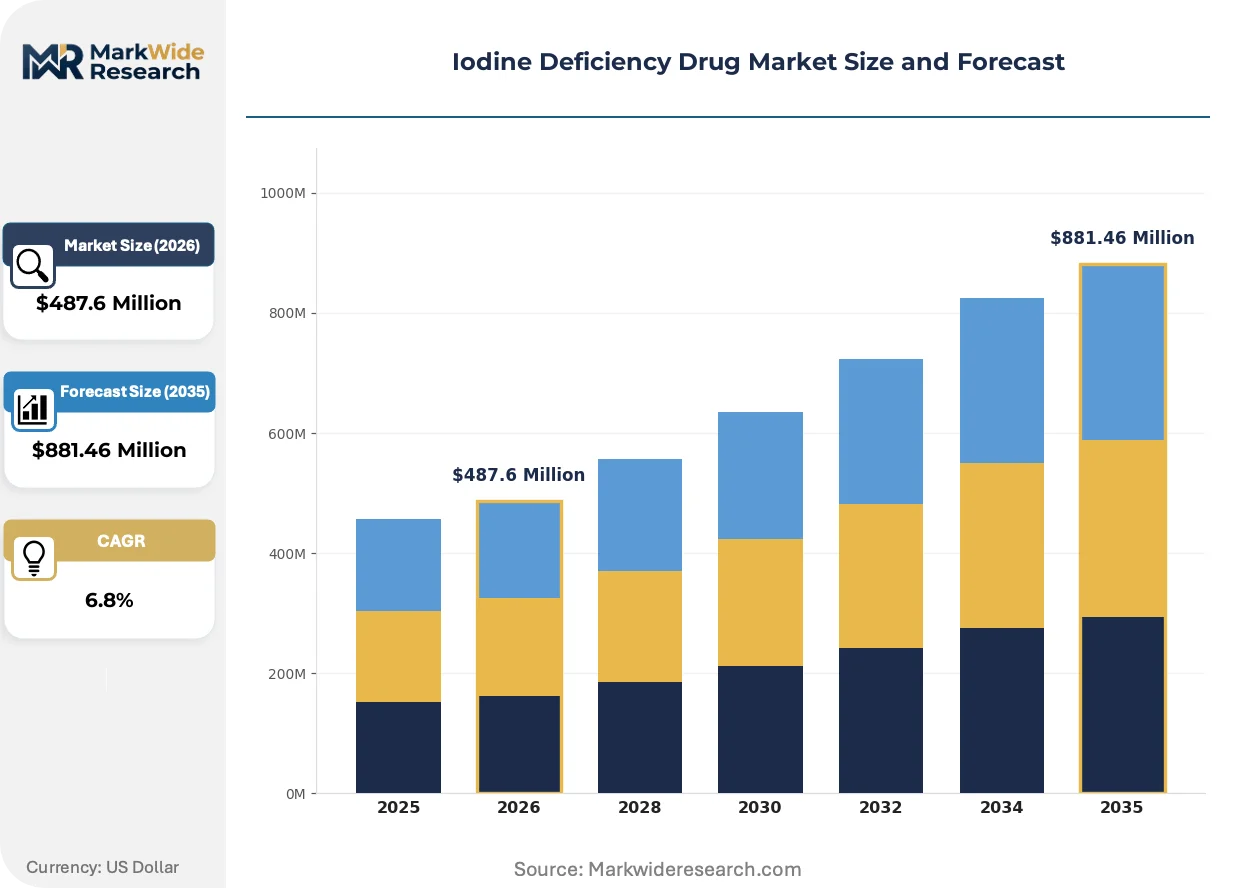
Public health procurement consolidation across sub-Saharan Africa and South Asia is compressing supplier margins while favoring manufacturers with working capital depth to absorb 180-day government payment cycles. WHO prequalification status has become the decisive gating credential for tender eligibility in low-income country programs.
Growth Catalysts
- Salt iodization mandates:National legislation in India, Nigeria, and Ethiopia requires universal fortification of edible salt, creating recurring bulk demand for potassium iodide premixes from state food safety authorities.
- WHO iodine nutrition guidelines:Updated recommendations on urinary iodine concentration thresholds are triggering program recalibrations and inventory restocking across maternal health initiatives.
- Emergency preparedness stockpiling:Nuclear regulatory agencies in East Asia and Eastern Europe are building strategic reserves of potassium iodide tablets for thyroid-blocking protocols around civilian reactor facilities.
Market Restraints
- Chilean caliche ore concentration:Over 60 percent of global iodine extraction depends on northern Chilean nitrate deposits, exposing supply chains to Atacama water scarcity and export licensing volatility.
- REACH compliance burden:EU chemical registration requirements for iodine derivatives impose documentation costs that disqualify small-scale API manufacturers from European public health tenders.
- Sea kelp substitution:Dietary supplement manufacturers are pivoting to organic seaweed-derived iodine for premium consumer segments, eroding addressable market for synthetic potassium iodide in retail pharmacy channels.
Strategic Opportunities
- Indonesia archipelago penetration:The national IDD elimination program has achieved only 72 percent household salt iodization coverage, leaving 78 million people in outer island provinces underserved.
- Prenatal nanoformulations:Liposomal encapsulation technologies enabling sub-100 nanometer particle delivery are opening pediatric and gestational segments with elevated bioavailability requirements.
- Direct-to-clinic e-procurement:Government health management information systems in Kenya and Tanzania are piloting digital tender platforms that bypass traditional distributor markups for essential medicines.
Industry Challenges
- Analytical chemist scarcity:WHO-prequalified laboratories capable of certifying iodine content in complex matrices remain concentrated in South Africa and India, creating testing bottlenecks for African manufacturers.
- Legacy salt iodization equipment:Batch mixing machinery installed during 1990s program rollouts lacks precision dosing controls required by current FSSAI and BIS standards, forcing capital-intensive retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iodine Deficiency Drug Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Iodide, Sodium Iodide, Iodine Solution, Iodized Salt End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Direct Sales Administration Route: Oral, Injectable, Sublingual, Topical |
| Companies Covered | Merck KGaA, Bristol-Myers Squibb, AbbVie Inc., Abbott Laboratories, GlaxoSmithKline plc, Pfizer Inc., Sanofi S.A., Bayer AG, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iodine Deficiency Drug Market Shifts & Advancements
Digitization of supply chain verification and precision dosing technologies are compressing quality assurance timelines while expanding access to last-mile distribution networks previously served by informal channels.
Near-infrared spectroscopy is virtualizing iodine content verification in salt fortification facilities, replacing wet chemistry titration methods that required 24-hour laboratory turnaround. UNICEF and national food safety authorities in Bangladesh and Pakistan are deploying portable NIR devices at production checkpoints, enabling real-time release decisions that reduce quarantine inventory by 40 percent. This virtualization of quality control is collapsing the traditional separation between manufacturing and regulatory inspection functions.
REACH authorization requirements for iodine-containing substances are tightening substance volume tracking obligations across EU pharmaceutical and food additive supply chains. ECHA's 2024 updated guidance on intermediate registration is forcing importers to reclassify potassium iodide shipments previously exempt under processing aid exemptions. German and French salt processors are responding by consolidating supplier relationships to reduce audit complexity, privileging vertically integrated Chilean producers over trading-house intermediaries.
Hospital pharmacy buyers in Brazil and Mexico are unbundling emergency potassium iodide stockpiles from comprehensive radioprotective kits, creating standalone procurement categories with distinct technical specifications. ANVISA's revised emergency pharmaceutical reserve guidelines now mandate tablet dissolution profiles specific to pediatric populations, displacing one-size-fits-all adult formulations previously accepted for all age groups. This specification fragmentation is most visible in São Paulo and Rio de Janeiro state health department tenders, where separate line items for neonatal, pediatric, and adult dosing now triple vendor qualification overhead.
Iodine Deficiency Drug Market Segmentation
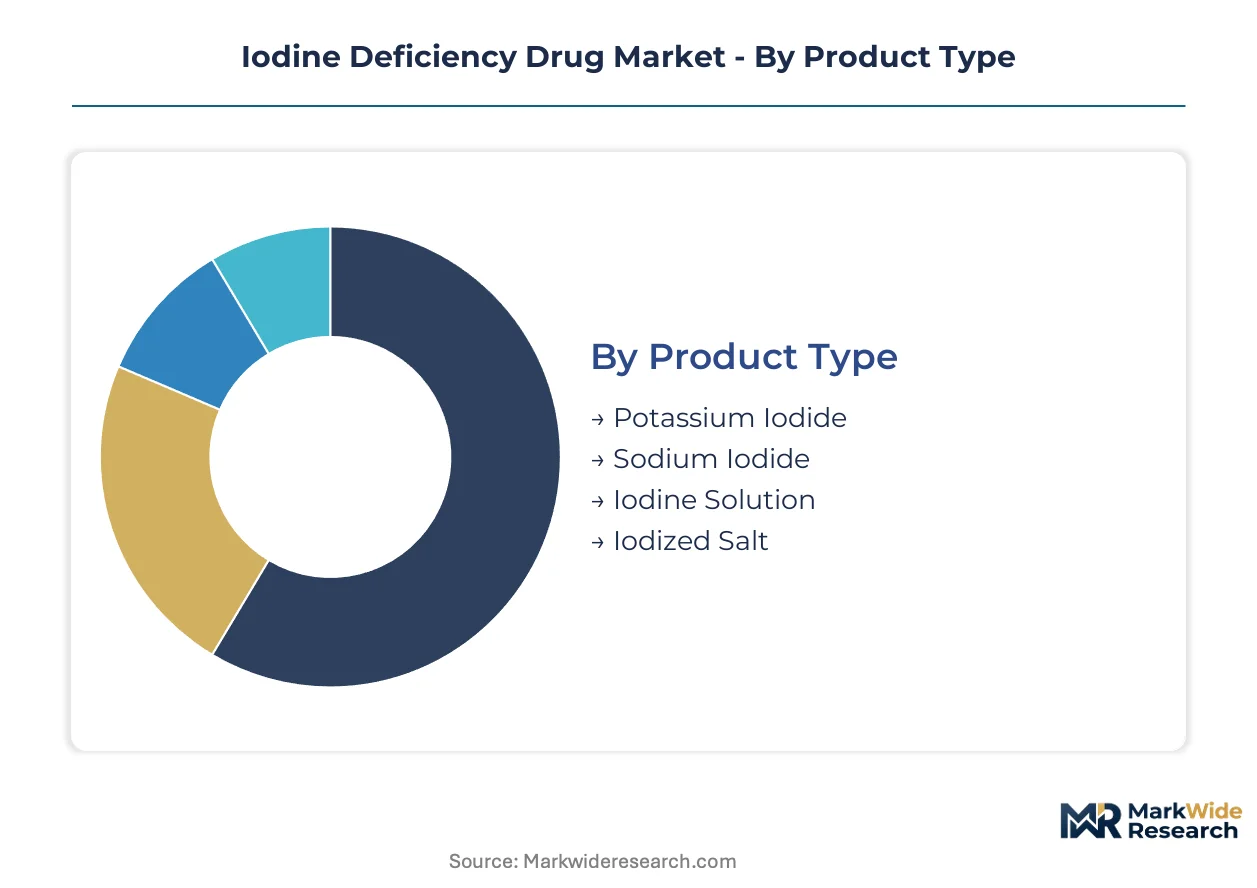
Iodine deficiency drug procurement patterns diverge sharply across product formulations and care settings. Hospital buyers prioritize emergency thyroid-blocking specifications, while retail channels emphasize over-the-counter accessibility for preventive supplementation.
Product Type:
The maturity spectrum spans established bulk commodities to emerging precision-delivery formats, with formulation chemistry determining regulatory pathway complexity and margin structure.
- Potassium Iodide:Crystalline salt compound standardized to 130mg or 65mg tablets for thyroid-blocking and daily prophylaxis. Indian state health departments and Nigerian food safety authorities drive bulk procurement through competitive tenders for salt fortification premixes.
- Sodium Iodide:Highly soluble ionic compound preferred for parenteral solutions and specialized prenatal formulations. Demand concentrates in Brazilian hospital pharmacies where ANVISA mandates dissolution-profile specifications for pediatric emergency reserves.
- Iodine Solution:Aqueous or alcoholic preparations delivering variable microgram dosing for laboratory and clinical applications.
- Iodized Salt:Sodium chloride fortified with potassium iodate or iodide at 15-40ppm concentration for population-level consumption.
Potassium Iodide retains volume leadership; Sodium Iodide holds the steepest expansion curve.
End User:
Customer type determines specification rigor, with institutional buyers imposing pharmacopeial compliance that informal channels cannot satisfy.
- Hospitals:Acute care facilities maintaining emergency radioprotective stockpiles and managing severe deficiency complications. Procurement in São Paulo and Rio de Janeiro state health systems now separates neonatal, pediatric, and adult dosing into distinct tender line items.
- Clinics:Primary care points conducting maternal health screening and targeted supplementation programs. Kenyan and Tanzanian government health management information systems are piloting direct-to-clinic e-procurement platforms.
- Home Care:Individual consumers accessing over-the-counter potassium iodide through retail channels.
- Pharmacies:Community dispensaries serving as last-mile distribution nodes for salt iodization verification and counseling.
Hospitals dominate value capture; Home Care is expanding most quickly.
Distribution Channel:
Channel selection reflects urgency requirements and regulatory documentation burdens, with emergency procurement bypassing standard retail intermediaries.
- Online Pharmacy:Digital platforms enabling direct consumer access to potassium iodide tablets. Regulatory fragmentation across Indian state pharmacy councils creates compliance complexity for interstate shipments.
- Retail Pharmacy:Brick-and-mortar dispensaries capturing walk-in demand for preventive supplementation. Bangladesh and Pakistan food safety authorities deploy portable near-infrared spectroscopy devices at production checkpoints served by these channels.
- Hospital Pharmacy:Institutional procurement units managing formulary compliance and emergency reserve rotation.
- Direct Sales:Manufacturer-to-institution contracts for bulk salt premixes and government tender fulfillment.
Retail Pharmacy maintains the broadest reach; Online Pharmacy is climbing the fastest.
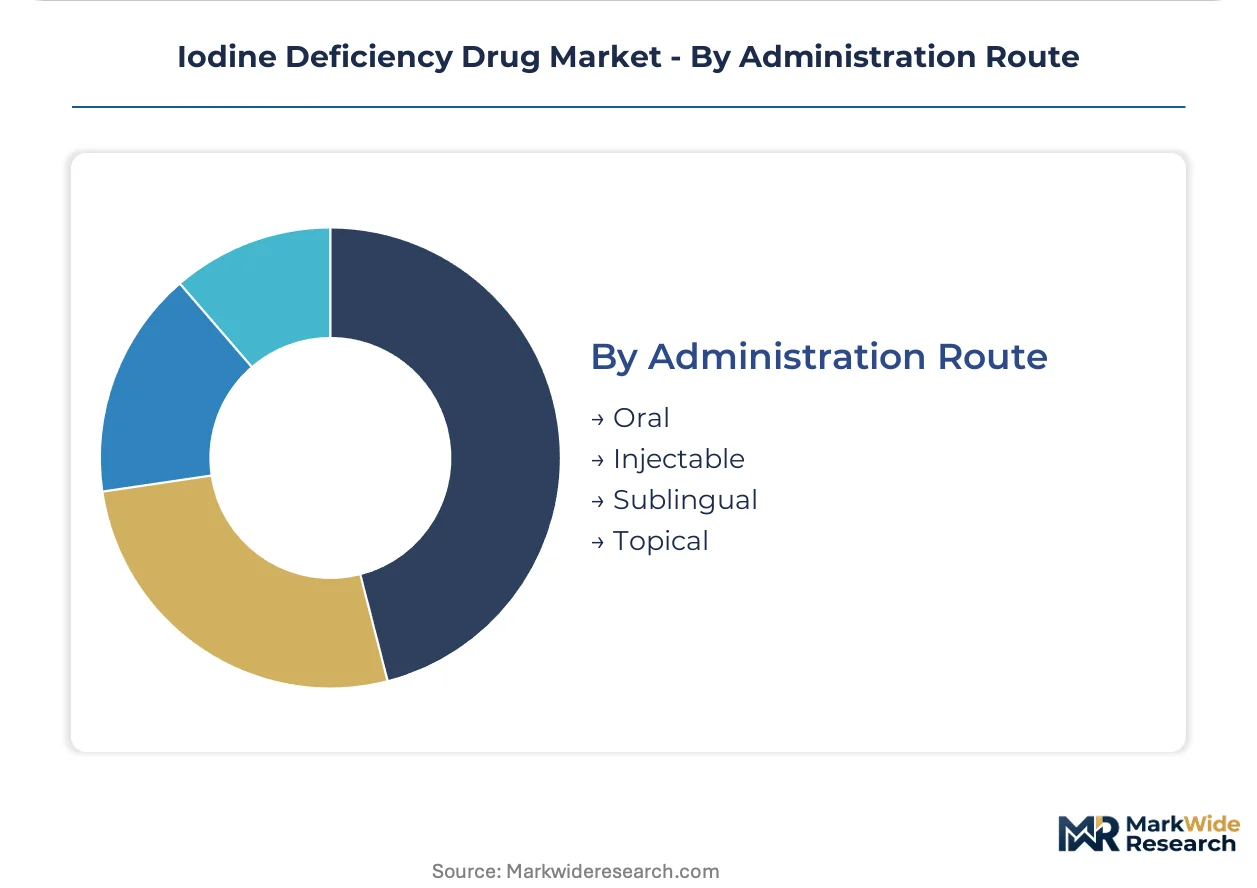
Administration Route:
Route selection trades bioavailability precision against logistical feasibility in resource-constrained settings.
- Oral:Tablets, capsules, and fortified salt for gastrointestinal absorption. Dominates mass-distribution campaigns in Ethiopia and Indonesia due to cost efficiency and storage stability.
- Injectable:Intravenous sodium iodide for severe deficiency states and perioperative thyroid management. Concentrated in tertiary hospital settings with cold chain infrastructure.
- Sublingual:Rapid-dissolving formulations bypassing first-pass hepatic metabolism for emergency applications.
- Topical:Cutaneous iodine preparations for localized antiseptic and limited systemic absorption applications.
Oral administration commands volume dominance; Injectable holds premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State health departments and nuclear regulatory agencies concentrate procurement authority, channeling volume through tender systems that favor suppliers with extended payment-cycle capacity.
India
The National Iodine Deficiency Disorders Control Program drives bulk purchasing through state health departments in Maharashtra and Gujarat. FSSAI mandates 15-40 ppm iodization standards for edible salt, forcing retrofit investments in legacy mixing equipment. Pharmaceutical formulation clusters in Hyderabad and Ahmedabad supply potassium iodide tablets for maternal health initiatives.
United States
Emergency preparedness stockpiling by nuclear regulatory agencies sustains demand for thyroid-blocking potassium iodide around civilian reactor facilities. FDA orphan drug designations shape manufacturing compliance burdens for domestic API producers. Hospital pharmacy buyers in Texas and Florida unbundle radioprotective stockpiles from comprehensive emergency kits.
Brazil
ANVISA's revised emergency pharmaceutical reserve guidelines mandate pediatric-specific dissolution profiles for potassium iodide tablets. State health departments in São Paulo and Rio de Janeiro now tender separate line items for neonatal, pediatric, and adult dosing. This specification fragmentation triples vendor qualification overhead for hospital pharmacy procurement.
Indonesia
The national IDD elimination program has achieved only 72 percent household salt iodization coverage, leaving 78 million people in outer island provinces underserved. Ministry of Health procurement concentrates in Java-based distributors with limited reach to Papua and Maluku archipelago communities. Salt fortification premix demand is accelerating in Surabaya and Makassar processing hubs.
Germany
ECHA's 2024 updated guidance on intermediate registration forces importers to reclassify potassium iodide shipments previously exempt under processing aid exemptions. Salt processors in Bavaria and North Rhine-Westphalia consolidate supplier relationships to reduce audit complexity. REACH authorization requirements privilege vertically integrated Chilean producers over trading-house intermediaries.
Iodine Deficiency Drug Market Competitive Landscape
Channel-controlling players compete with product-specialist players for access to government tender pools and hospital formulary slots. The structure tilts toward manufacturers with balance-sheet depth to absorb 180-day payment cycles from public health procurement. Three archetypes dominate: vertically integrated API producers securing preferential contract terms, geographic specialists capturing regional tender channels, and formulation innovators targeting pediatric and prenatal bioavailability requirements. Competitive moves concentrate on strategic partnerships with national food safety authorities and technology licensing for precision-delivery formats.
Within the integrated-manufacturing tier, Merck KGaA exemplifies upstream control over active pharmaceutical ingredient production. Pfizer Inc. and Sanofi S.A. occupy positions reflecting geographic dominance in Latin American public health channels and specialized formulation capabilities for populations with elevated bioavailability needs. These three anchors illustrate how competitive positioning depends on matching operational scale to procurement system requirements.
| Leading Market Players |
|---|
| Merck KGaA |
| Bristol-Myers Squibb |
| AbbVie Inc. |
| Abbott Laboratories |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Sanofi S.A. |
| Bayer AG |
| Amgen Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in Chilean caliche ore processing capacity drives both supplier allocation discipline and upward pricing pressure for potassium iodide API. This utilization squeeze concentrates negotiating leverage among vertically integrated producers while forcing tender-dependent buyers into longer contract durations.
Pricing Analysis
Cost-plus contracts with Chilean nitrate indexation dominate long-term salt premix agreements for Indian and Nigerian state tenders. Price differentiation hinges on WHO prequalification status and FSSAI certification tier, with qualified suppliers commanding 15-20 point premiums over unqualified competitors. Pricing pressure stems from public health procurement consolidation compressing margins to single-digit territory. Government health departments exhibit extreme price sensitivity, while nuclear emergency stockpile buyers prioritize dissolution-profile specifications over unit cost.
Supply Chain Analysis
Export licensing volatility around Atacama water restrictions constrains iodine derivative flows to European and Asian pharmaceutical manufacturers. Extraction concentrates in northern Chile, with secondary processing anchored in Germany and India. Supply chains draw from caliche ore, sodium hydroxide, and potassium carbonate feedstocks. Single-source vulnerability pervades the API tier, where three Chilean producers control 60 percent of global iodine supply. Distribution runs through government tender platforms and UN procurement pools for low-income country programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across pediatric formulation specifications, as ANVISA and state health departments unbundle emergency stockpiles into age-segmented tenders. This specification proliferation creates niche entry points for specialized manufacturers.
For Market Incumbents: Pre-empt margin erosion in bulk potassium iodide by securing backward integration into Chilean caliche offtake agreements. Lock in 5-year indexation contracts with Maharashtra and Gujarat state health departments before REACH authorization burdens reshape European supplier eligibility. Prioritize liposomal nanoformulation R&D to capture unbundled pediatric tender categories. For New Entrants and Emerging Players: Build out direct-to-clinic e-procurement capabilities targeting Kenyan and Tanzanian government health management information system pilots. Indonesia's outer island provinces offer the most penetrable geography, with 78 million underserved consumers and limited Java-based distributor reach. Position through portable NIR spectroscopy partnerships with Bangladesh and Pakistan food safety authorities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across liposomal encapsulation manufacturing, as equipment modularization reduces minimum viable scale thresholds. Five-to-ten year viability favors acquisition targets with WHO prequalification status and existing state tender relationships in India or Nigeria. Monitor ANVISA dissolution-profile enforcement as the signal indicating specification fragmentation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caliche Ore | Secures preferential contract terms with Indian state health departments facing 180-day payment cycles. |
| Pediatric Nanoformulation Development | Captures unbundled tender line items in São Paulo and Rio de Janeiro state health systems. |
| Direct-to-Clinic E-Procurement Platform | Bypasses traditional distributor markups in Kenyan and Tanzanian government health systems. |
| Portable NIR Spectroscopy Deployment | Enables real-time release decisions with UNICEF and Bangladesh food safety authorities. |
| WHO Prequalification Investment | Unlocks UN agency procurement pools and low-income country tender eligibility. |
Research Methodology
Desk research of WHO prequalification databases, FSSAI salt iodization standards, and ANVISA emergency pharmaceutical guidelines preceded structured interviews with state health department procurement officers, pharmaceutical formulation R&D directors, and Chilean caliche mining operations managers. Secondary validation drew from FDA orphan drug filings, ECHA REACH authorization records, and UNICEF supply division tender documents. Bottom-up segment sizing triangulated against top-down public health expenditure forecasts.
Assumptions held fixed include prevailing WHO urinary iodine concentration thresholds, existing salt iodization mandate enforcement intensity, and Chilean export licensing stability. Segmentation modeling spanned product formulation, administration route, end-user facility type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Forecast inputs incorporated maternal health program budget trajectories and nuclear emergency preparedness stockpile rotation cycles.
Stress conditions across Atacama water availability, Indian state fiscal capacity, and REACH authorization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in Chilean caliche ore export policy or WHO iodine nutrition guideline revision would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Global Lipid Disorder Treatment Market