
 I.V. Fluid Warmer Market | 2026-2036
I.V. Fluid Warmer Market Size, Share, and Industry Trends Forecast 2026-2036
I.V. Fluid Warmer Market Foresight
CE-marked and FDA-cleared specification tiers is reorganizing procurement criteria across acute care settings. Smiths Medical leverages its anesthesia delivery heritage to sustain channel access in surgical suites. Stryker Corporation anchors its position through integrated operating room ecosystems that bundle warming with visualization and surgical table systems. GE Healthcare differentiates via connected device platforms that feed fluid temperature data into central monitoring architectures.
An intravenous fluid warmer is a regulated medical device that maintains parenteral solutions within a narrow therapeutic temperature band, typically 37°C to 41°C, using conductive, convective, or radiant heat transfer mechanisms to prevent perioperative hypothermia and associated coagulopathy. The device serves critical functions in trauma resuscitation, elective surgery, and neonatal care where cold fluid infusion risks patient destabilization. Portable warmers command premium placement in emergency services and military field medicine where point-of-care mobility outweighs throughput capacity. Electric technology dominates installed base economics while fiber optic warming gains traction in MRI-compatible applications where electromagnetic interference must be eliminated. Dual purpose warmers that handle both crystalloid and blood product warming are capturing margin pools as hospitals consolidate device categories to reduce capital expenditure and training overhead.
FDA 510(k) premarket notification requirements, EU MDR technical documentation mandates, and ISO 80601-2-35 particular standards for body-warming equipment collectively elevate compliance costs and filter marginal competitors from commercial distribution. Japan's PMDA enforces Japan Industrial Standards compatibility testing that extends approval timelines but rewards persistent entrants with protected market access. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA guidance on software-as-a-medical-device classifications that could reclassify connected warming platforms.
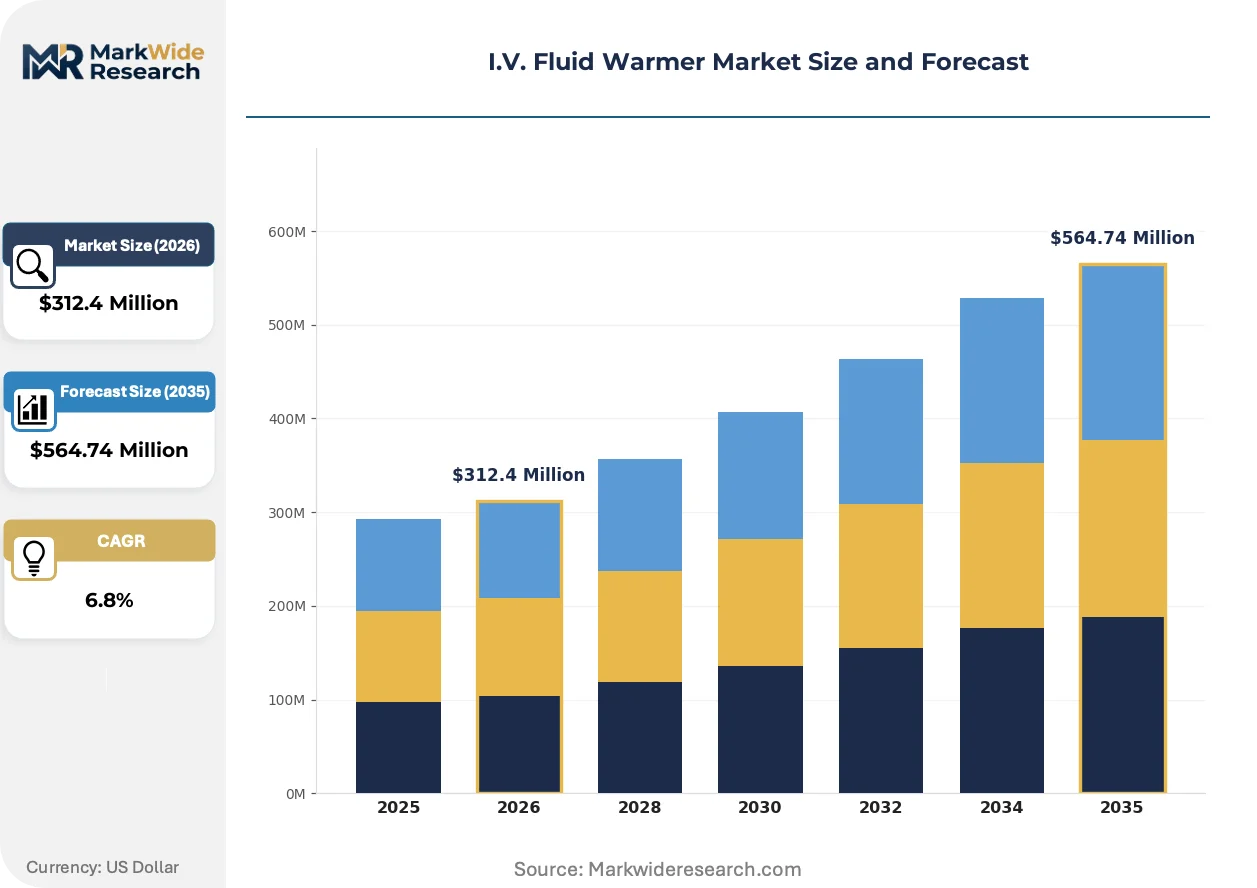
Market Dynamics
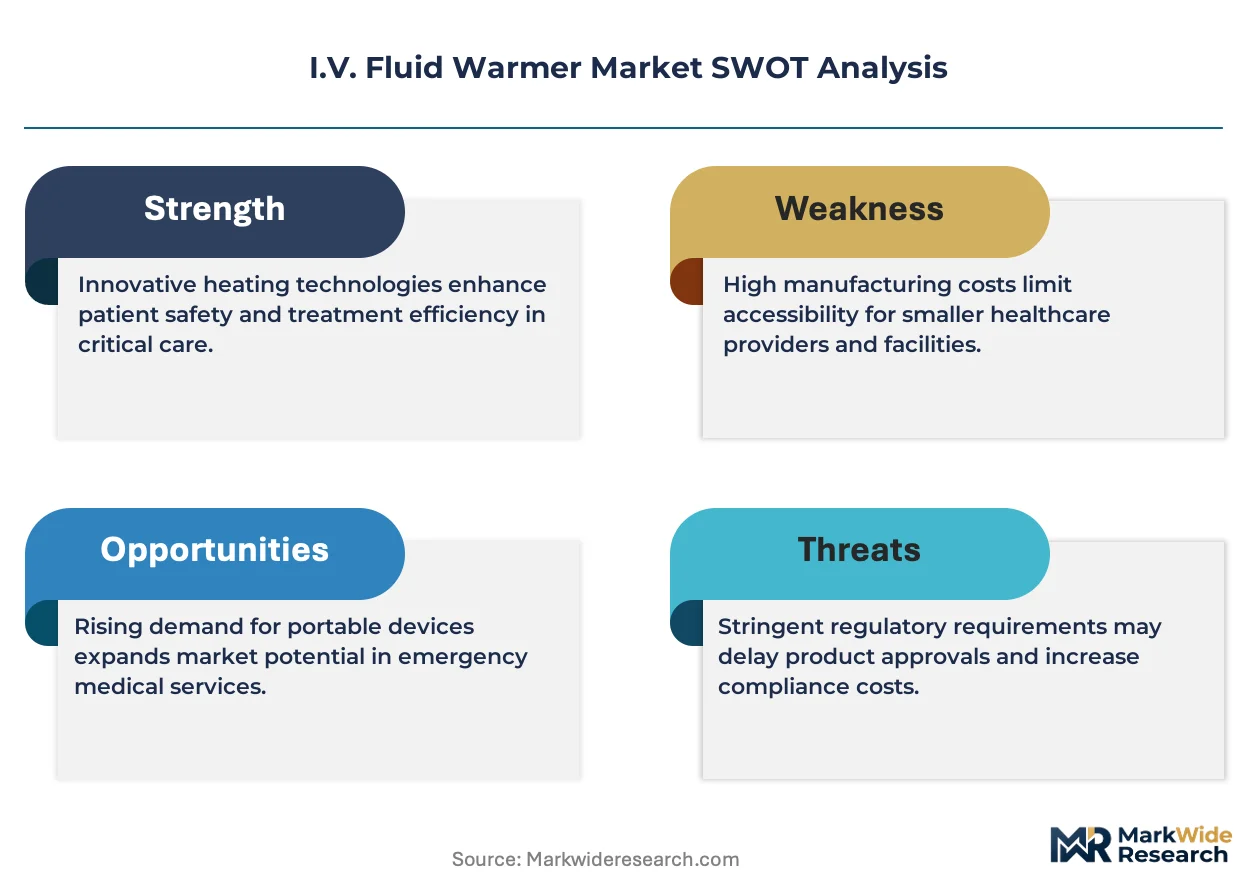
EU MDR notified body capacity constraints are filtering marginal competitors from commercial distribution while concentrating procurement authority within integrated health systems that demand bundled device ecosystems.
Growth Catalysts
- Perioperative hypothermia protocols:Surgical suites in tertiary hospitals are expanding warmer deployment as part of enhanced recovery after surgery pathways. Elective procedure backlogs are accelerating capital equipment refresh cycles.
- FDA 510(k) pathway maturation:Clearance requirements for patient-warming devices are tightening performance documentation standards, rewarding established manufacturers with robust quality management systems.
- Fiber optic warming:MRI-compatible applications where electromagnetic interference must be eliminated are driving adoption in radiology-interventional suites.
Market Restraints
- Copper and semiconductor input volatility:Heating element manufacturing faces raw material cost pressure from energy-intensive supply chains concentrated in East Asia.
- EU MDR technical documentation mandates:Compliance costs for body-warming equipment under ISO 80601-2-35 particular standards are elevating barriers to market entry for smaller device manufacturers.
- Passive warming blankets:Low-cost alternatives for normothermia maintenance in ambulatory settings are capturing cases where fluid warming represents clinical overengineering.
Strategic Opportunities
- Military field medicine:Portable warmers command premium placement in combat casualty care where point-of-care mobility outweighs throughput capacity.
- Japan PMDA protected access:Japan Industrial Standards compatibility testing extends approval timelines but rewards persistent entrants with defended market positions.
- Neonatal intensive care:Precision temperature control for low-birth-weight infant resuscitation represents an underserved application with distinct technical specifications.
Industry Challenges
- Biomedical engineering talent scarcity:Device manufacturers face recruitment pressure for specialists capable of integrating thermal control systems with connected monitoring architectures.
- Software-as-a-medical-device reclassification risk:FDA guidance evolution on connected warming platforms could trigger substantial compliance timeline extensions for cloud-enabled temperature data systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | I.V. Fluid Warmer Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Warmers, Portable Warmers, Stationary Warmers, Dual Purpose Warmers End User: Hospitals, Ambulatory Surgical Centers, Home Care, Emergency Services Technology: Electric, Water Heating, Fiber Optic, Microwave Application: Trauma Care, Surgery, Pediatric Care, Geriatric Care |
| Companies Covered | 3M, Smiths Medical, Stryker Corporation, Belmont Medical Technologies, ICU Medical, GE Healthcare, Becton Dickinson and Company, Baxter International, Vyaire Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
I.V. Fluid Warmer Market Shifts & Advancements
Fluid warming technology is fragmenting across specialized performance tiers as electromagnetic compatibility requirements and connectivity demands reshape hardware architecture decisions.
Dual-purpose warming systems handling both crystalloid and blood product temperature management are decomposing the historical separation between infusion therapy and transfusion service equipment categories. Blood banks and emergency departments are consolidating procurement specifications to reduce capital expenditure and training overhead. This convergence is compressing margin pools for single-purpose device manufacturers while expanding addressable market scope for adaptable platform vendors.
EU MDR Article 10 technical documentation requirements are elevating clinical evidence standards for body-warming equipment classifications. Manufacturers must now submit post-market surveillance plans and risk management files to notified bodies with diminished assessment capacity. Surgical suite procurement committees in Germany and France are prioritizing CE-marked devices with established vigilance databases over newer market entrants.
Hospital value analysis committees are unbundling after-sales service contracts from capital equipment purchases, forcing device manufacturers to compete on discrete service line-item pricing. Integrated delivery networks in the United States are consolidating vendor rosters to reduce procurement complexity. This compression is most visible in multi-hospital systems standardizing on single-source warming platforms across perioperative, emergency, and labor-and-delivery departments.
I.V. Fluid Warmer Market Segmentation
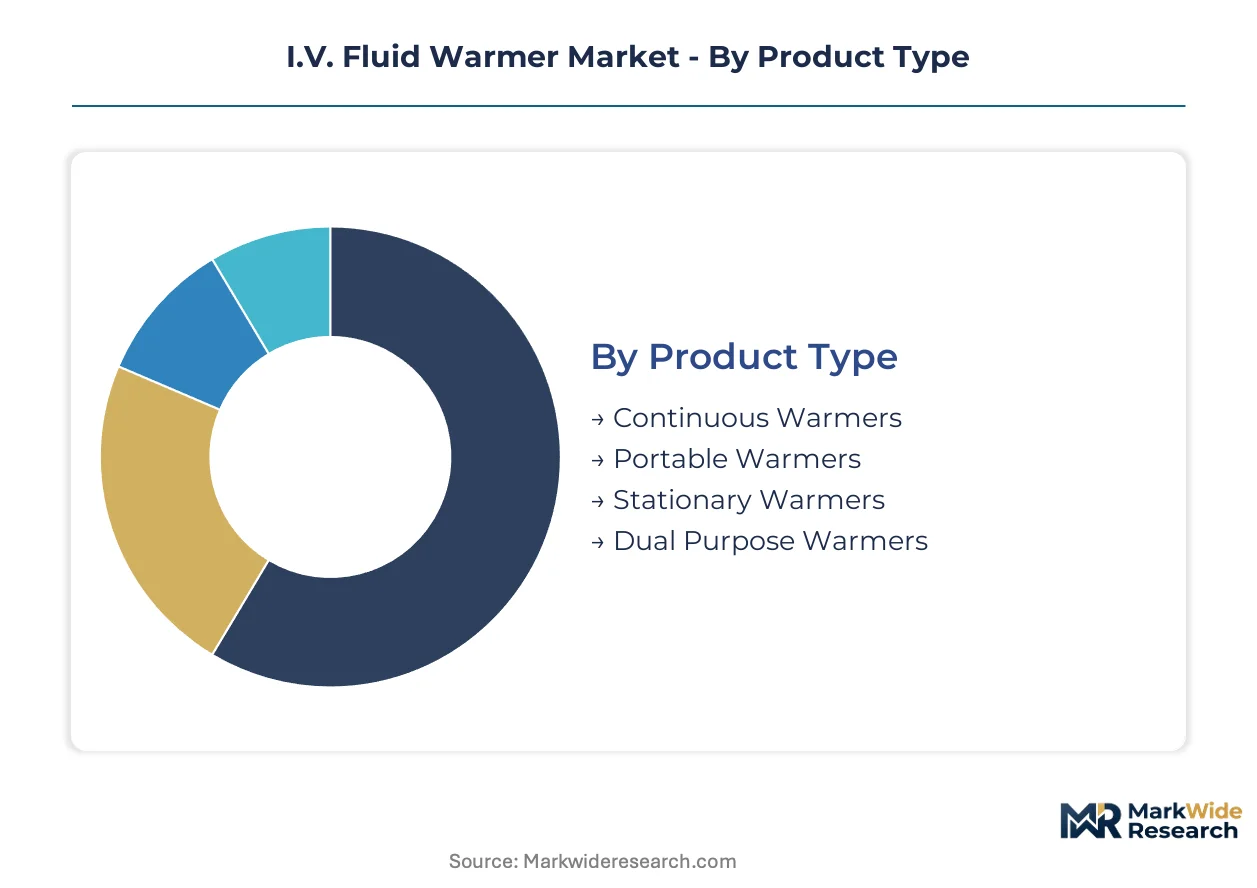
I.V. fluid warmer segmentation reflects divergent thermal engineering requirements across care settings. Product architecture choices directly determine electromagnetic compatibility profiles, mobility constraints, and capital recovery timelines for procurement committees.
Product Type:
Portable warmers face acute substitution pressure from passive thermal blankets in low-acuity transport scenarios, while stationary systems defend installed base positions through EMR integration dependencies.
- Continuous Warmers:Inline heating elements maintain fluid temperature across extended infusion durations using conductive heat transfer mechanisms. Tertiary hospital surgical suites in the United States specify these for elective procedure backlogs requiring sustained normothermia protocols.
- Portable Warmers:Battery-powered or vehicle-integrated units prioritize field mobility over throughput capacity. Military combat casualty care and civilian emergency medical services in Germany command premium placement despite higher per-procedure operational costs.
- Stationary Warmers:Fixed-installation devices anchor perioperative infrastructure with centralized monitoring connectivity.
- Dual Purpose Warmers:Single-platform systems handle crystalloid solutions and blood products simultaneously, consolidating device categories for capital-constrained facilities.
Continuous warmers retain volume leadership; portable warmers hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive integrated delivery networks from price-sensitive standalone facilities, reshaping vendor contracting structures.
- Hospitals:Multi-department standardization drives bulk procurement of connected warming platforms feeding central monitoring architectures. Value analysis committees in Japan unbundle service contracts from equipment purchases, intensifying price competition on discrete line items.
- Ambulatory Surgical Centers:Lean staffing models favor single-operator devices with minimal training overhead. United States outpatient procedure volume growth concentrates demand for compact, rapid-deployment warmers compatible with fast-turnover suites.
- Home Care:Reimbursement limitations restrict device deployment to high-complexity infusion therapy cases.
- Emergency Services:Prehospital trauma resuscitation protocols mandate point-of-care warming capability independent of facility infrastructure.
Hospitals dominate absolute unit demand; ambulatory surgical centers are expanding most quickly.
Technology:
Application-specific electromagnetic constraints fragment engineering investment across incompatible hardware architectures.
- Electric:Resistive heating elements dominate installed base economics through mature supply chains and straightforward regulatory pathways. ISO 80601-2-35 particular standards govern thermal control safety documentation for body-warming equipment classifications.
- Fiber Optic:Non-conductive heat transfer eliminates electromagnetic interference for MRI-compatible deployment. Radiology-interventional suites in tertiary hospitals specify these for hybrid operating rooms where magnetic field compatibility is non-negotiable.
- Water Heating:Circulating warm water baths provide gentle temperature modulation for sensitive biological fluids.
- Microwave:Rapid volumetric heating targets military field medicine scenarios where speed outweighs precision control requirements.
Electric technology commands current installed base share; fiber optic warming gains share fastest.
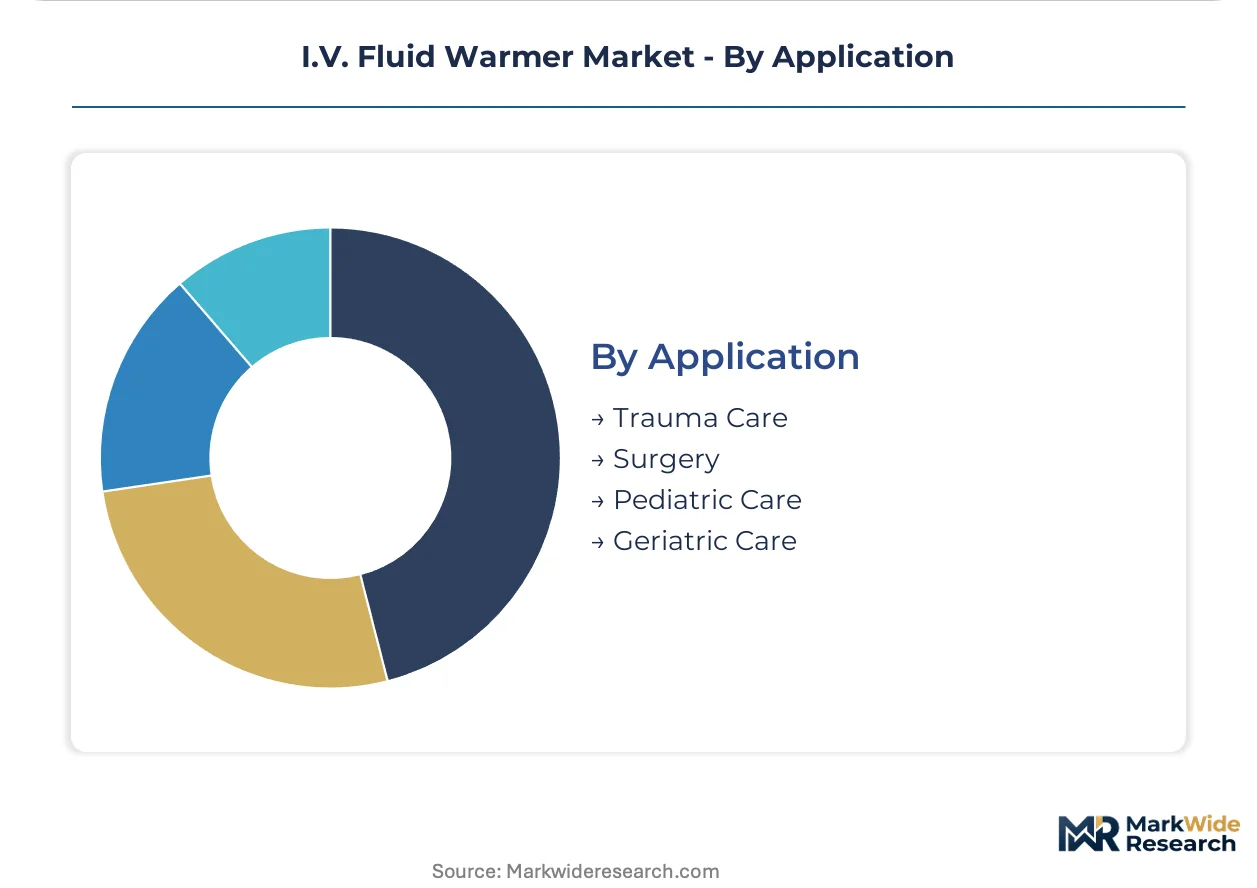
Application:
Clinical outcome risk profiles determine reimbursement eligibility and thus equipment procurement priority rankings across patient populations.
- Surgery:Perioperative hypothermia prevention drives protocol-mandated warmer deployment in enhanced recovery after surgery pathways. Elective procedure scheduling in German university hospitals incorporates fluid warming as standard anesthesia workflow.
- Trauma Care:Massive transfusion protocols require immediate availability of warmed blood products and crystalloids. Emergency department resuscitation bays in United States Level I trauma centers specify dual-purpose warmers for coagulopathy mitigation.
- Pediatric Care:Neonatal intensive care demands precision temperature control distinct from adult specifications.
- Geriatric Care:Impaired thermoregulation in elderly surgical candidates elevates hypothermia risk profiles.
Surgery maintains revenue concentration; trauma care shows the steepest volume trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heating element supply chains concentrate in East Asian manufacturing clusters, yet device assembly and regulatory clearance gravitate toward established medical technology corridors in North America, Western Europe, and Japan. Procurement authority is consolidating within integrated health systems that demand bundled device ecosystems.
United States
Elective procedure backlogs at tertiary hospitals are accelerating capital equipment refresh cycles for perioperative infrastructure. FDA 510(k) clearance pathways for patient-warming devices are tightening performance documentation requirements, rewarding established manufacturers with robust quality management systems. Value analysis committees in multi-hospital systems across the Midwest and Southeast are unbundling after-sales service contracts from equipment purchases.
Germany
Surgical suites in university hospitals are expanding warmer deployment as part of enhanced recovery after surgery pathways. EU MDR technical documentation mandates under ISO 80601-2-35 particular standards are elevating compliance costs and filtering marginal competitors from commercial distribution. Procurement committees in Bavaria and North Rhine-Westphalia prioritize CE-marked devices with established vigilance databases.
Japan
PMDA enforces Japan Industrial Standards compatibility testing that extends approval timelines but rewards persistent entrants with protected market access. METI-backed perioperative infrastructure upgrades are driving demand for connected device platforms feeding central monitoring architectures. Tokyo and Osaka medical device clusters concentrate regulatory expertise and distribution channel access for warming equipment.
China
NMPA medical device registration pathways are harmonizing with international standards, though provincial procurement tendering favors domestic manufacturers for hospital infrastructure. Dual carbon goals are pressuring energy-intensive heating element supply chains concentrated in Yangtze River Delta manufacturing zones. Shanghai and Shenzhen hubs are consolidating device assembly capabilities for regional distribution.
I.V. Fluid Warmer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium-tier vendors commanding integrated operating room ecosystems while value-tier competitors compete on discrete line-item pricing. The market structure reflects moderate consolidation around diversified medical technology conglomerates with anesthesia delivery heritage. Three strategic archetypes dominate: integrated platform vendors bundling warming with surgical table and visualization systems; connected device specialists feeding temperature data into central monitoring architectures; and portable equipment manufacturers serving military field medicine and emergency services. Dominant competitive moves include portfolio diversification into dual-purpose crystalloid and blood product warming, and geographic expansion through regulatory-first market entry strategies.
Among diversified medical technology conglomerates, 3M, Stryker Corporation, and GE Healthcare exemplify distinct competitive positioning archetypes. 3M occupies a position within the patient-warming equipment segment leveraging materials science heritage. Stryker Corporation anchors the integrated platform tier through surgical suite ecosystem bundling. GE Healthcare sits within the connected device specialist archetype, representing hospital information system integration capabilities. These three entities collectively illustrate the technology-cost segmentation that structures procurement committee evaluations across tertiary hospital systems.
| Leading Market Players |
|---|
| 3M |
| Smiths Medical |
| Stryker Corporation |
| Belmont Medical Technologies |
| ICU Medical |
| GE Healthcare |
| Becton Dickinson and Company |
| Baxter International |
| Vyaire Medical |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for heating element components concentrate procurement leverage among East Asian contract manufacturers, translating directly into tiered pricing power for device assemblers in North America and Western Europe. FDA 510(k) documentation requirements and EU MDR technical file mandates impose fixed compliance cost layers that manufacturers recover through premium positioning, while raw material volatility in copper and semiconductor markets compresses margin buffers for mid-tier competitors.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across the I.V. fluid warmer landscape. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors with bundled surgical suite ecosystems from standalone device manufacturers and private-label suppliers. Price differentiation hinges on ISO 80601-2-35 certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because hospital value analysis committees increasingly unbundle service contracts from equipment purchases. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with multi-hospital standardization mandates show lowest sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies dominate heating element procurement for electric warmers, while strategic stockpiling of fiber optic components buffers against extended lead times for MRI-compatible devices. Manufacturing concentration centers on China, South Korea, and Japan for resistive heating elements, with Germany and the United States anchoring final assembly and regulatory certification. Raw material dependencies include copper wire, semiconductor thermal controllers, and medical-grade polymer housings. Single-source vulnerability in East Asian semiconductor supply chains represents the dominant structural risk. Distribution runs through group purchasing organizations and integrated delivery network procurement committees that consolidate vendor rosters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The I.V. fluid warmer market functions as a regulatory entrenchment story where FDA 510(k) clearance databases and EU MDR vigilance files create switching costs that protect incumbent positions. Network effects in connected device platforms compound this defensive moat.
For Market Incumbents: Shield installed base positions by deepening backward integration into heating element manufacturing and accelerating software companion development for central monitoring architectures. Marginal competitors with limited quality management system documentation face exclusion as FDA tightens performance validation requirements. Prioritize certification investment in Japan PMDA pathways to defend market access. For New Entrants and Emerging Players: Anchor in neonatal intensive care applications where precision temperature specifications remain underserved by incumbent product portfolios. Military field medicine and civilian emergency medical services represent the most penetrable segments due to mobility requirements that favor portable form factors. Pursue regulatory-first market entry through Japan PMDA or FDA 510(k) clearance to establish credibility with procurement committees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across connected warming platforms with cloud-enabled temperature data architectures. Long-term viability favors diversified medical technology conglomerates with anesthesia delivery heritage and established hospital information system integration capabilities. Monitor FDA guidance evolution on software-as-a-medical-device classifications as the critical inflection signal for compliance timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Purpose Platform Development | Consolidates crystalloid and blood product warming to capture margin pools from category reduction. |
| FDA 510(k) Pathway Acceleration | Robust quality management systems reward established manufacturers with faster clearance timelines. |
| Japan PMDA Regulatory Entry | JIS compatibility testing extends timelines but yields protected market positions for persistent entrants. |
| Connected Device Architecture | Cloud-enabled temperature data feeds central monitoring systems and raises switching costs. |
| Military Field Medicine Partnership | Combat casualty care protocols prioritize point-of-care mobility over throughput capacity. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and anesthesia department heads anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, EU MDR notified body registers, hospital procurement contract filings, and ISO 80601-2-35 technical documentation standards. Bottom-up demand modeling across product type, technology, end user, and application segments triangulated with top-down market sizing.
Sensitivity analysis frameworks tested forecast outputs against alternative scenarios for raw material cost trajectories and regulatory approval timeline variations. Segmentation dimensions modeled include product architecture, heat transfer mechanism, care setting acuity, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, procedure volume growth, and technology substitution rates. Fiber optic warming penetration curves and dual-purpose device adoption rates served as industry-specific forecast inputs across the projection horizon.
Material uncertainties — copper and semiconductor price volatility, EU MDR notified body capacity constraints, FDA software-as-a-medical-device reclassification — sit outside the modeled envelope. Forecasts reflect assumptions about perioperative protocol standardization and military procurement continuity. Revision becomes warranted when regulatory guidance on connected device platforms crosses thresholds that trigger substantial compliance timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Diabetes Devices Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Neurostimulation Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market