
 Minimally Invasive Glaucoma Surgery (MIGS) Devices Market | 2026-2036
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market Analysis
Ophthalmic surgeon training capacity is reorganizing how quickly MIGS procedures diffuse into community practice settings. Glaukos Corporation dominates the trabecular micro-bypass segment with sustained R&D investment in sustained-release drug-device combinations. Alcon Inc. leverages its global cataract platform to bundle MIGS devices with phacoemulsification workflows. Johnson & Johnson Vision competes through integrated visualization systems that anchor surgeon loyalty in premium surgical suites.
Minimally Invasive Glaucoma Surgery devices employ micro-scale implants and precision instruments to reduce intraocular pressure through enhanced aqueous humor outflow, typically functioning at dimensions below 1 millimeter to preserve conjunctival tissue integrity. Implantable devices, particularly drainage and shunt implants, command the largest revenue share due to recurring procedural volume and premium pricing tied to biocompatible material specifications. Canaloplasty procedures within the procedure-type dimension are gaining traction fastest among early adopters seeking alternatives to trabecular bypass in complex anatomy cases.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape device development timelines and clinical evidence thresholds for MIGS manufacturers entering commercial distribution. The US national pharmaceutical regulator maintains stringent biocompatibility testing protocols for permanent implants, while Japan's PMDA applies supplemental NDB review standards for novel microstent materials. Stakeholders must monitor evolving reimbursement decisions by CMS and parallel health technology assessment bodies, as coverage determinations for standalone versus combined cataract-MIGS procedures will directly influence surgeon adoption curves and capital allocation across product portfolios.
Market Dynamics
Surgeon training capacity constraints are fragmenting how quickly MIGS devices penetrate community ophthalmology practices, creating a two-speed adoption curve between academic medical centers and independent surgical suites.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The premarket notification framework accelerates clearance timelines for microstent iterations, reducing commercialization lag for iterative device improvements.
- Aqueous Humor Outflow Enhancement:Canaloplasty techniques preserve conjunctival tissue integrity while achieving target intraocular pressure reductions, expanding eligible patient pools beyond trabecular bypass candidates.
- Japan PMDA NDB Review Standards:Novel biocompatible materials for permanent implants receive structured evaluation pathways, incentivizing material science investment for micro-scale shunt development.
Market Restraints
- Biocompatible Material Cost Volatility:Medical-grade silicone and heparin-coated substrates face supply concentration among specialty chemical producers in Germany and Switzerland.
- EU MDR Technical Documentation Burden:Clinical evidence thresholds for Class III implantable devices extend development timelines and inflate regulatory compliance expenditures.
- Trabeculectomy Substitution Persistence:Established filtration surgery maintains cost advantage and long-term efficacy data in advanced glaucoma cases, limiting MIGS penetration in severe disease stages.
Strategic Opportunities
- Standalone MIGS Reimbursement Expansion:CMS coverage determinations for procedures uncoupled from cataract surgery unlock outpatient surgical volume in United States ambulatory surgery centers.
- Drug-Device Combination Convergence:Sustained-release pharmaceutical delivery integrated with microstent platforms creates differentiated therapeutic profiles against standalone mechanical implants.
- India CDSCO Regulatory Harmonization:Alignment with international standards for ophthalmic implants accelerates market access for CE-marked devices in South Asian surgical networks.
Industry Challenges
- Gonioscopy Skill Deficiency:Anterior segment angle visualization proficiency requirements limit surgeon eligibility for canaloplasty and trabecular bypass procedures.
- ISO 10993 Biocompatibility Testing Capital Intensity:Cytotoxicity, sensitization, and implantation studies for permanent ocular implants demand specialized laboratory infrastructure and extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Glaucoma Surgery (MIGS) Devices Market |
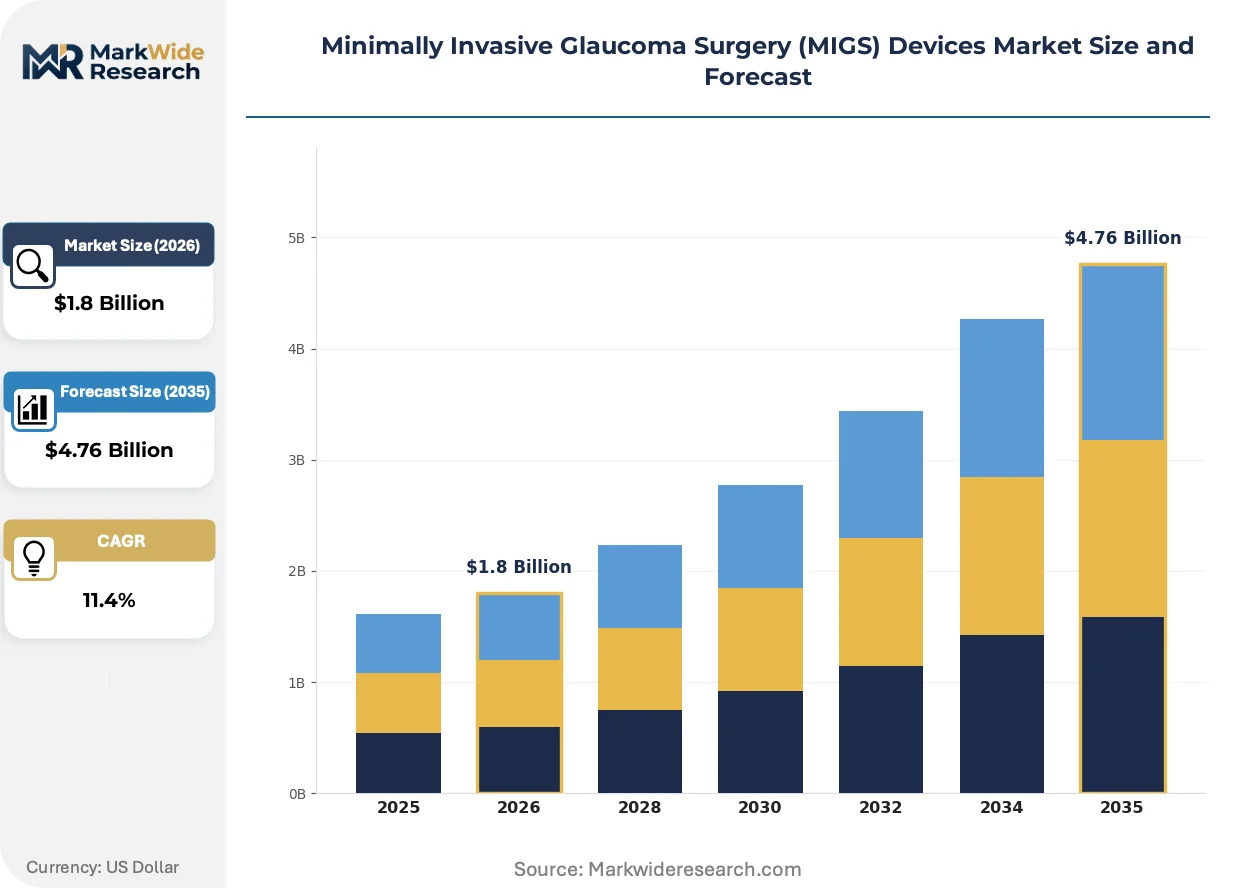
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, Injectable Materials, Surgical Instruments, Diagnostic Tools End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Technology: Microcatheterization, Drainage Implants, Shunt Implants, Laser Treatment Procedure Type: Trabecular Bypass, Canaloplasty, Stent Implantation, Glaucoma Filtration Surgery |
| Companies Covered | Ivantis, Carl Zeiss Meditec AG, Alcon Inc., iStar Medical, Lumenis, Glaukos Corporation, Johnson & Johnson Vision, New World Medical, Allergan Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market Emerging Trajectories
Micro-scale implant engineering and integrated visualization systems are redrawing competitive boundaries between standalone device manufacturers and comprehensive surgical platform providers.
Ultrathin polymeric stent materials are fragmenting traditional titanium and silicone dominance in trabecular micro-bypass segments. Early-adopting ophthalmology clinics in the United States and Germany are prioritizing flexibility and biointegration profiles over legacy material stiffness. This material transition is fragmenting supplier relationships as device makers cultivate captive polymer synthesis partnerships.
EU MDR post-market surveillance obligations are intensifying clinical follow-up requirements for permanently implanted glaucoma devices. Manufacturers must now maintain active implant registries and periodic safety update reports across distributed European surgical networks. The canaloplasty device segment faces particular documentation burden given its emerging status and limited long-term outcome databases.
Service unbundling is separating device procurement from surgical training and after-sales technical support. Ambulatory surgery centers in the United States are negotiating direct device purchasing while sourcing surgeon education through independent continuing medical education providers. This procurement pattern shift compresses traditional bundled pricing power among integrated platform vendors.
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market Segmentation
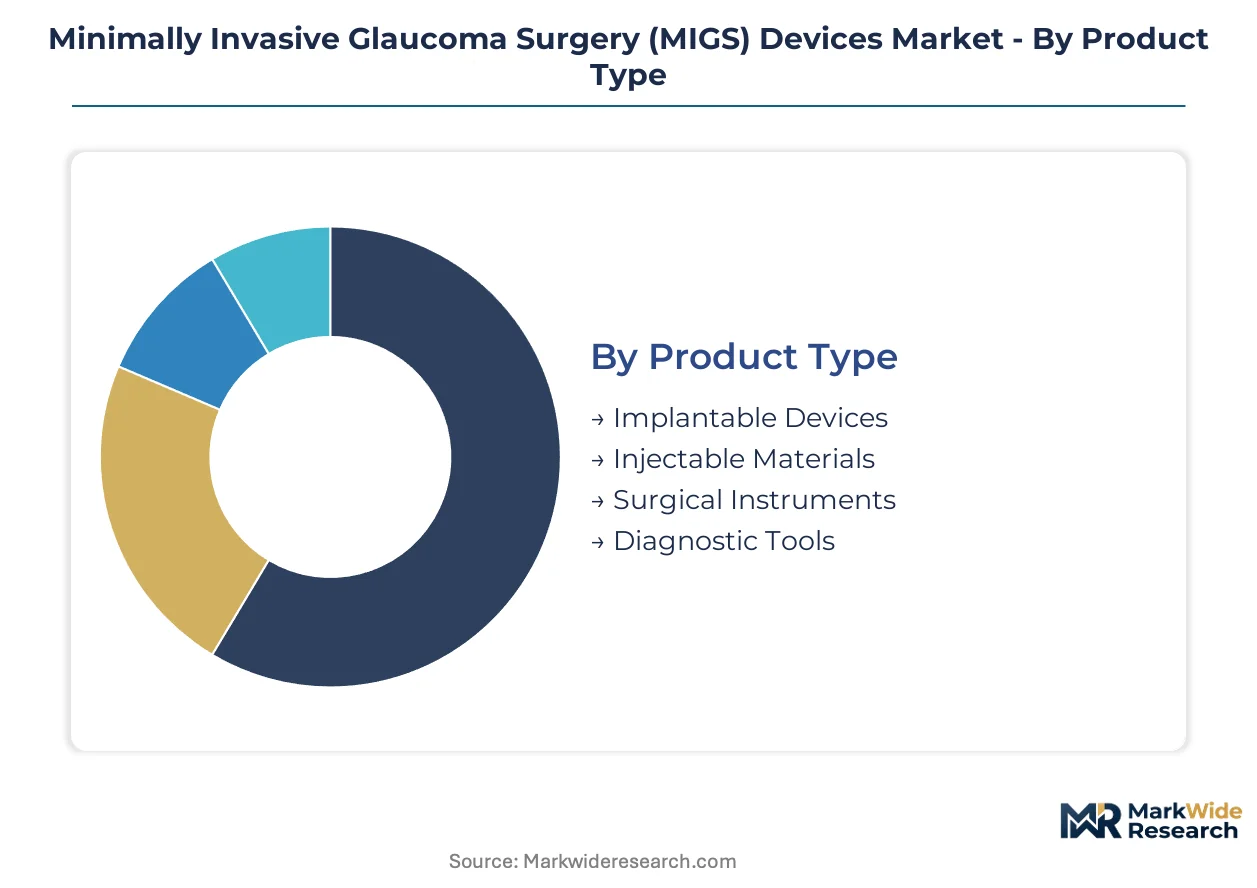
MIGS device segmentation reveals distinct procurement patterns across clinical settings and reimbursement environments. Each dimension carries specific regulatory burdens and surgeon training requirements that shape commercial strategy.
Product Type:
Implantable devices concentrate revenue in the United States and Western Europe where premium pricing for permanent biocompatible materials is sustainable. Injectable materials and surgical instruments follow distinct geographic diffusion curves.
- Implantable Devices:Drainage stents and micro-bypass shunts fabricated from medical-grade silicone or titanium alloys achieve premium pricing through FDA 510(k) and CE marking differentiation. Demand clusters in US ambulatory surgery centers where standalone MIGS reimbursement has expanded coverage.
- Surgical Instruments:Precision micro-forceps, gonioscopic lenses, and angle visualization systems require specialized manufacturing in Germany and Switzerland. Export volumes to Japan and South Korea are climbing as PMDA and MFDS harmonize with international biocompatibility standards.
- Injectable Materials:Viscocanalostomy agents and space-maintaining gels serve niche applications in complex anatomy cases.
- Diagnostic Tools:Anterior segment imaging and intraocular pressure monitoring devices support preoperative screening workflows.
Implantable devices hold the largest share; momentum sits with surgical instruments as visualization technology upgrades accelerate replacement cycles.
End User:
Procurement authority varies sharply across settings, with cost tier and procedure volume determining vendor access.
- Ophthalmology Clinics:Independent specialty practices in the United States drive adoption of combined cataract-MIGS workflows. These facilities prioritize device bundles that include surgeon training and technical support.
- Ambulatory Surgical Centers:US outpatient facilities are expanding standalone MIGS capacity as CMS coverage determinations clarify reimbursement. Direct device purchasing without bundled services is becoming standard.
- Hospitals:Academic medical centers in Germany and Japan maintain gonioscopy training programs that feed community practice pipelines.
- Research Institutions:Clinical trial sites generate long-term safety data required under EU MDR post-market surveillance obligations.
Ophthalmology clinics anchor current volume; ambulatory surgical centers represent the steepest expansion trajectory.
Technology:
Material science investment and regulatory pathway complexity create divergent margin profiles across technology categories.
- Drainage Implants:Permanent microstents with heparin-coated or drug-eluting surfaces command premium pricing tied to biointegration performance. FDA biocompatibility testing protocols and ISO 10993 validation requirements concentrate manufacturing among specialized suppliers.
- Shunt Implants:Suprachoroidal and subconjunctival drainage devices preserve conjunctival tissue for future filtration surgery. Adoption in France and the United Kingdom is accelerating as ANSM and MHRA streamline CE-marked device recognition.
- Microcatheterization:Canaloplasty systems require advanced gonioscopy skills that limit addressable surgeon populations.
- Laser Treatment:Selective laser trabeculoplasty competes with mechanical MIGS in early glaucoma stages.
Drainage implants dominate revenue; shunt implants are gaining share fastest as complex anatomy indications expand.
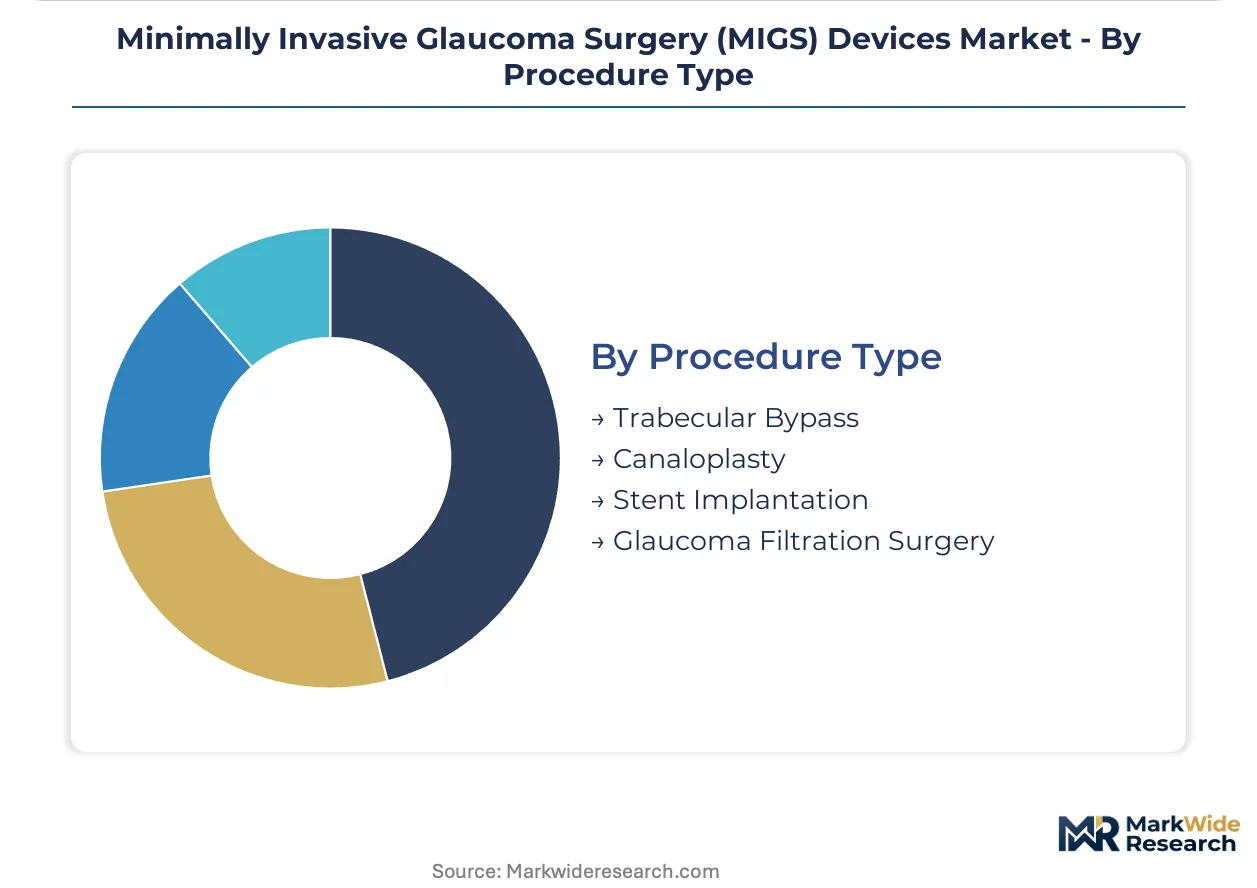
Procedure Type:
Surgeon training infrastructure and long-term outcome databases shape competitive positioning across procedural categories.
- Trabecular Bypass:Schlemm's canal microstent placement has the deepest clinical evidence base and broadest surgeon familiarity. US procedural volume concentrates in cataract-surgery bundling arrangements.
- Canaloplasty:Circumferential viscodilation of Schlemm's canal preserves future surgical options. German and Swiss clinics are building specialized training capacity for this technique.
- Stent Implantation:Standalone trabecular micro-bypass is expanding as payer coverage for procedures uncoupled from cataract surgery matures.
- Glaucoma Filtration Surgery:Traditional trabeculectomy maintains cost advantage in advanced disease despite MIGS encroachment.
Trabecular bypass holds the largest share; canaloplasty shows the most rapid adoption curve among early-adopting surgical networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German levels by roughly 40% for comparable trabecular micro-bypass stents, while Japanese procurement through PMDA-negotiated channels compresses margins for foreign manufacturers. This asymmetry shapes where device makers prioritize regulatory submissions and direct sales investment.
United States
Medicare reimbursement clarity for standalone MIGS procedures drives ambulatory surgery center expansion in Florida and Texas. FDA 510(k) pathway streamlining accelerates iterative device approvals for microstent manufacturers. The Cleveland Clinic and Bascom Palmer Eye Institute anchor surgeon training pipelines that feed community practice adoption.
Germany
Statutory health insurance coverage for canaloplasty procedures sustains procedural volume in Baden-Württemberg and Bavaria. EU MDR technical documentation requirements extend CE marking timelines for permanent implantable devices. Tübingen and Heidelberg host specialized gonioscopy training programs that diffuse surgical technique across Central European networks.
Japan
Aging demographics and glaucoma prevalence concentrate demand in Tokyo and Osaka metropolitan corridors. PMDA NDB review standards apply supplemental scrutiny to novel biocompatible materials for permanent microstents. Nagoya University Hospital maintains longitudinal implant registries that satisfy post-market surveillance obligations under harmonized standards.
India
Private ophthalmology chains in Maharashtra and Karnataka expand MIGS capacity for affluent patient segments. CDSCO regulatory harmonization with ISO 13485 and CE marking standards accelerates import pathways for established device makers. Chennai and Hyderabad emerge as surgical training hubs for South Asian ophthalmology networks.
Switzerland
Medical-grade silicone and heparin-coated substrate suppliers concentrate production around Basel and Zurich chemical clusters. Swissmedic recognition of FDA and CE approvals streamlines market entry for predicate devices. University Hospital Zurich generates clinical evidence supporting canaloplasty outcomes in complex anatomy cases.
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium-tier manufacturers concentrate on drug-device combinations and sustained-release platforms, while mid-tier competitors emphasize surgical instrument bundles and training services. Three archetypes dominate: integrated ophthalmic platform providers, standalone MIGS device specialists, and precision surgical instrument fabricators. M&A activity targets visualization technology assets, and strategic partnerships between device makers and academic medical centers secure surgeon training pipelines.
Among integrated platform providers, Alcon Inc. and Johnson & Johnson Vision occupy positions anchored by global cataract surgery infrastructure. Glaukos Corporation exemplifies the standalone MIGS specialist archetype, with sustained investment in trabecular micro-bypass innovation. Carl Zeiss Meditec AG represents the precision visualization and surgical instrument tier, leveraging German optical engineering heritage. These three companies collectively illustrate how competitive positioning fragments across technology integration, therapeutic focus, and manufacturing specialization vectors.
| Leading Market Players |
|---|
| Ivantis |
| Carl Zeiss Meditec AG |
| Alcon Inc. |
| iStar Medical |
| Lumenis |
| Glaukos Corporation |
| Johnson & Johnson Vision |
| New World Medical |
| Allergan Plc |
| Others |
Supply Flow & Price Mechanics
Scale economies in medical-grade polymer synthesis concentrate production among German and Swiss specialty chemical clusters, creating asymmetric pricing power that elevates floor prices for biocompatible microstent materials while compressing margins for device assemblers lacking captive supply arrangements.
Pricing Analysis
The customization-premium spread in MIGS devices separates standard trabecular micro-bypass stents from patient-matched canaloplasty systems with integrated drug-eluting surfaces. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) predicate status and ISO 10993 certification completeness. Cost compression in standard-tier mechanical stents is intensifying because ambulatory surgery centers are unbundling procurement from training services. Price sensitivity concentrates among US outpatient facilities negotiating direct device purchases, while academic medical centers absorb premium pricing for drug-device combination platforms.
Supply Chain Analysis
Germany and Switzerland anchor medical-grade silicone and heparin-coated substrate production for permanent ocular implants, with Basel and Zurich chemical clusters feeding specialized polymer specifications to device manufacturers. Raw material dependencies center on medical-grade silicone elastomers, titanium alloys for structural components, and pharmaceutical-grade coatings for biointegration enhancement. Single-source vulnerability runs through concentrated specialty chemical producers subject to REACH regulatory restrictions. Distribution runs through authorized device distributors with GPO contracts to hospital purchasing committees and direct sales teams for ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIGS device economics are shifting toward platform-based competition where visualization system interoperability determines surgeon workflow capture, with integrated surgical suites displacing standalone device vendors.
For Market Incumbents: Consolidate surgeon training pipeline control through exclusive partnerships with academic medical centers in Cleveland and Miami, defending against emerging entrants offering unbundled device pricing. Deepen backward integration into polymer synthesis through captive supply agreements with Swiss chemical producers, securing material cost stability against biocompatible substrate volatility.
For New Entrants and Emerging Players: Differentiate on canaloplasty-specific instrumentation for complex anatomy cases where gonioscopy skill scarcity limits incumbent penetration. Target independent ophthalmology clinics in Texas and Florida seeking alternatives to bundled cataract-MIGS workflows. Deploy direct-to-facility sales teams emphasizing standalone reimbursement pathway expertise.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors visualization platform providers with installed base expansion potential over pure-play device manufacturers facing commoditization pressure. Long-term viability hinges on drug-device combination convergence and sustained-release therapeutic integration. Acquisition focus should center on microcatheter engineering specialists with CE marking momentum. The signal to watch is CMS coverage determination timing for standalone MIGS procedures uncoupled from cataract surgery.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated clearance timelines compress commercialization lag for iterative microstent designs against predicate devices. |
| Drug-Device Combination Development | Sustained-release pharmaceutical integration creates differentiated therapeutic profiles against standalone mechanical implants. |
| Surgeon Training Network Expansion | Academic medical center partnerships in Florida and Texas anchor community practice adoption pipelines. |
| CE Marking Under EU MDR | Technical documentation compliance for Class III implants secures European market access amid post-market surveillance intensification. |
| Standalone Reimbursement Strategy | CMS coverage determination advocacy unlocks ambulatory surgery center volume independent of cataract bundling. |
Methodological Framework
Operator-level perspectives from ophthalmic surgeons, ambulatory surgery center administrators, hospital purchasing committee members, and biomedical engineering directors anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement determinations, and hospital procurement contract records. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Sensitivity analysis around reimbursement scenario variations and regulatory pathway timelines shaped the analytical framework. Segmentation dimensions modeled include product type, end-user facility category, technology platform, and procedure type across the projection horizon. CAGRs derived from procedure volume elasticity to coverage expansion and pricing trajectory assumptions for biocompatible material cost inputs.
Forecasts assume regulatory continuity in FDA 510(k) clearance standards and EU MDR post-market surveillance obligations; material policy shifts in CMS coverage determinations or PMDA NDB review standards would require re-modeling. Recalibration cycles align with material shifts in standalone MIGS reimbursement decisions and novel biocompatible material approval pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Smart Patches Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Bowel Irrigation System Market