
 Cardiac Ablation Devices Market | 2026-2036
Cardiac Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Ablation Devices Market Analysis
Software-defined mapping and navigation subscriptions is restructuring how cardiac ablation platforms generate recurring revenue beyond hardware placement. Medtronic plc leverages its integrated ecosystem of catheters and mapping systems to sustain high switching costs in electrophysiology suites. Abbott Laboratories anchors its competitive position through specialized cryoablation balloon technology that dominates pulmonary vein isolation workflows. Johnson & Johnson (Biosense Webster) differentiates via advanced 3D electroanatomical mapping platforms that command premium placement in tier-one cardiac centers.
Cardiac ablation devices are therapeutic instruments designed to destroy arrhythmogenic cardiac tissue through controlled energy delivery, typically operating at radiofrequency ranges of 300-750 kHz or cryothermal temperatures below minus 40 degrees Celsius, with primary purpose of restoring normal sinus rhythm in patients with drug-refractory tachyarrhythmias. Radiofrequency ablation systems occupy the largest installed base due to decades of clinical validation and broad operator familiarity across atrial fibrillation and ventricular tachycardia indications. Cryoablation devices represent the fastest-expanding segment as single-shot pulmonary vein isolation protocols reduce procedure complexity and training barriers in community hospital settings. 3D mapping systems concentrate margin pools through software licensing and proprietary catheter compatibility that locks institutions into recurring platform expenditures.
FDA premarket approval pathways and European MDR conformity assessments shape cardiac ablation device development timelines and clinical trial investment requirements, with both regulators demanding extensive long-term safety databases for Class III implantable and interventionally placed technologies. Japan's PMDA maintains distinct technical documentation standards that extend market access preparation for foreign manufacturers seeking reimbursement listing under the national health insurance framework. Stakeholders must monitor evolving real-world evidence expectations from regulators and payer technology assessment bodies that increasingly condition coverage on comparative effectiveness against catheter ablation alternatives.
Market Dynamics
Software-defined mapping platforms are restructuring revenue architecture in cardiac ablation, converting one-time hardware sales into recurring subscription streams that deepen vendor lock-in across electrophysiology suites.
Growth Catalysts
- Pulmonary vein isolation protocols:Single-shot cryoablation workflows reduce procedure time and training barriers, expanding treatable patient pools in community hospital settings across the United States and Germany.
- European MDR clinical evidence requirements:Stricter conformity assessments for Class III devices accelerate consolidation toward established manufacturers with robust safety databases.
- Aging demographics in Japan:Expanding elderly populations with drug-refractory atrial fibrillation drive procedural volumes in tertiary cardiac centers.
Market Restraints
- Input cost concentration:Specialized catheter materials and precision sensor components face supply bottlenecks from concentrated Asian manufacturing clusters.
- Regulatory friction:FDA premarket approval timelines extend development cycles, demanding extensive long-term safety databases that strain mid-tier development budgets.
- Technical limitation:Persistent recurrence rates in complex ventricular tachycardia cases limit addressable indications despite expanding atrial fibrillation volumes.
Strategic Opportunities
- Underpenetrated ambulatory surgical centers:United States outpatient settings remain underserved for catheter-based ablation, presenting channel expansion potential.
- Technology convergence:Integration of artificial intelligence-driven arrhythmia detection with robotic catheter navigation promises workflow automation.
- Japan reimbursement alignment:PMDA national health insurance listing pathways reward comparative effectiveness data against pharmacological alternatives.
Industry Challenges
- Electrophysiologist training pipelines:Procedural complexity and length of specialized fellowship programs create workforce constraints in high-volume markets.
- Legacy system integration:New mapping platforms must interface with installed base catheter inventories, complicating hospital upgrade decisions.
- Certification timeline compression:Simultaneous FDA and European MDR submissions demand redundant clinical evidence generation, stretching regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Ablation Devices Market |
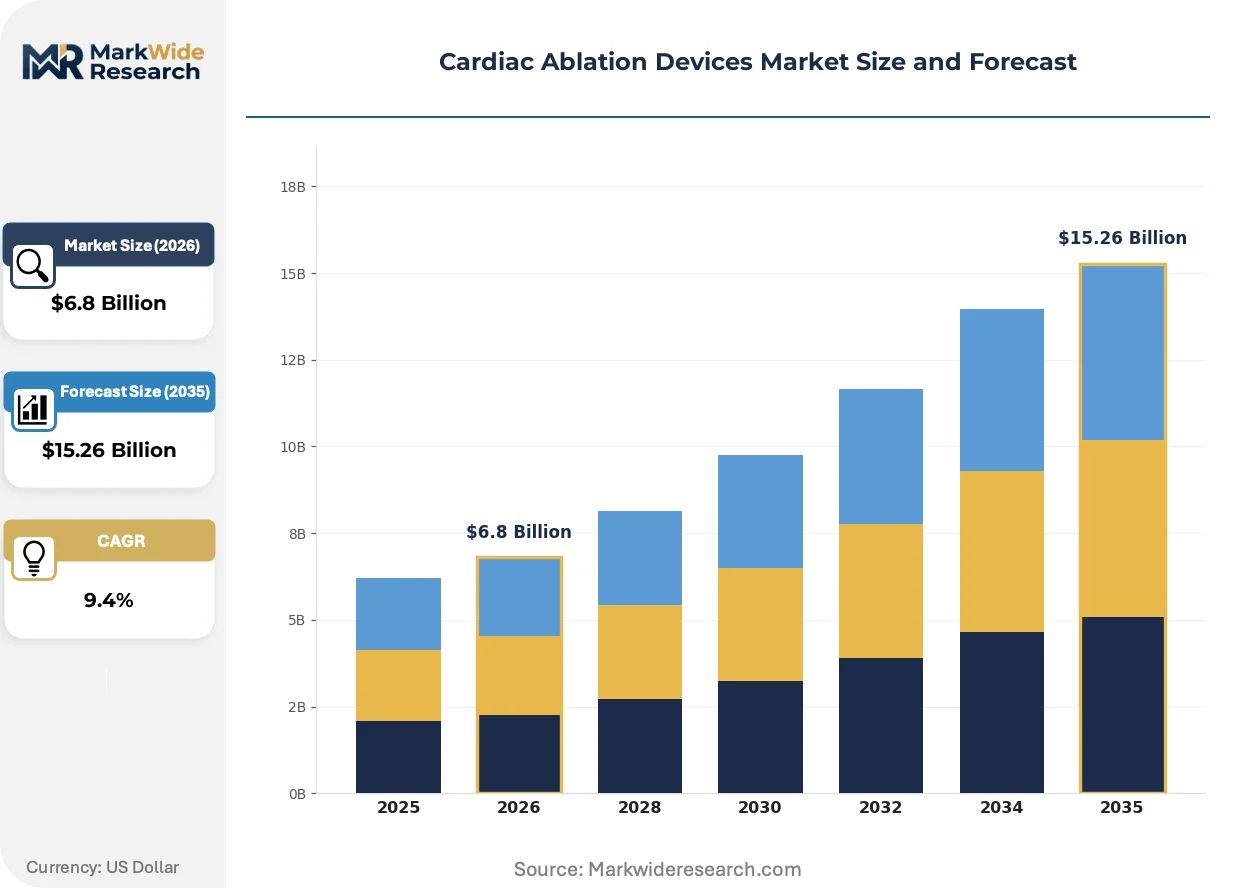
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation Systems, Cryoablation Devices, Laser Ablation Systems, Microwave Ablation Devices Technology: Endocardial, Epicardial, 3D Mapping Systems, Intracardiac Ultrasound End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Application: Atrial Fibrillation, Atrial Flutter, Ventricular Tachycardia, Supraventricular Tachycardia |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson (Biosense Webster), Biotronik SE & Co. KG, MicroPort Scientific Corporation, AtriCure, Inc., CardioFocus, AngioDynamics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Ablation Devices Market Emerging Trajectories
Cardiac ablation technology is pivoting from hardware-centric competition toward ecosystem dominance, where software platforms and disposable compatibility determine vendor selection more than device performance alone.
Robotic catheter navigation systems are modularizing procedure workflows by decoupling manual dexterity requirements from therapeutic outcomes. Community hospitals with limited electrophysiology experience adopt these platforms to standardize pulmonary vein isolation quality. The technology is modularizing training pathways, enabling faster operator certification and expanding treatable geography beyond academic medical centers.
European MDR post-market surveillance requirements now mandate systematic collection of long-term safety data for Class III cardiac devices. Manufacturers must maintain updated clinical evaluation reports across entire product portfolios. High-complexity mapping systems face the steepest compliance burden, favoring vendors with established quality management infrastructure.
Hospital procurement committees increasingly bundle catheter purchases with multi-year mapping system licenses, unbundling hardware from software access. Tier-one cardiac centers in Germany and Japan negotiate enterprise-wide platform commitments that lock in disposable volumes. This contract restructuring concentrates purchasing power among integrated delivery networks and reduces spot-market flexibility for smaller institutions.
Cardiac Ablation Devices Market Segmentation
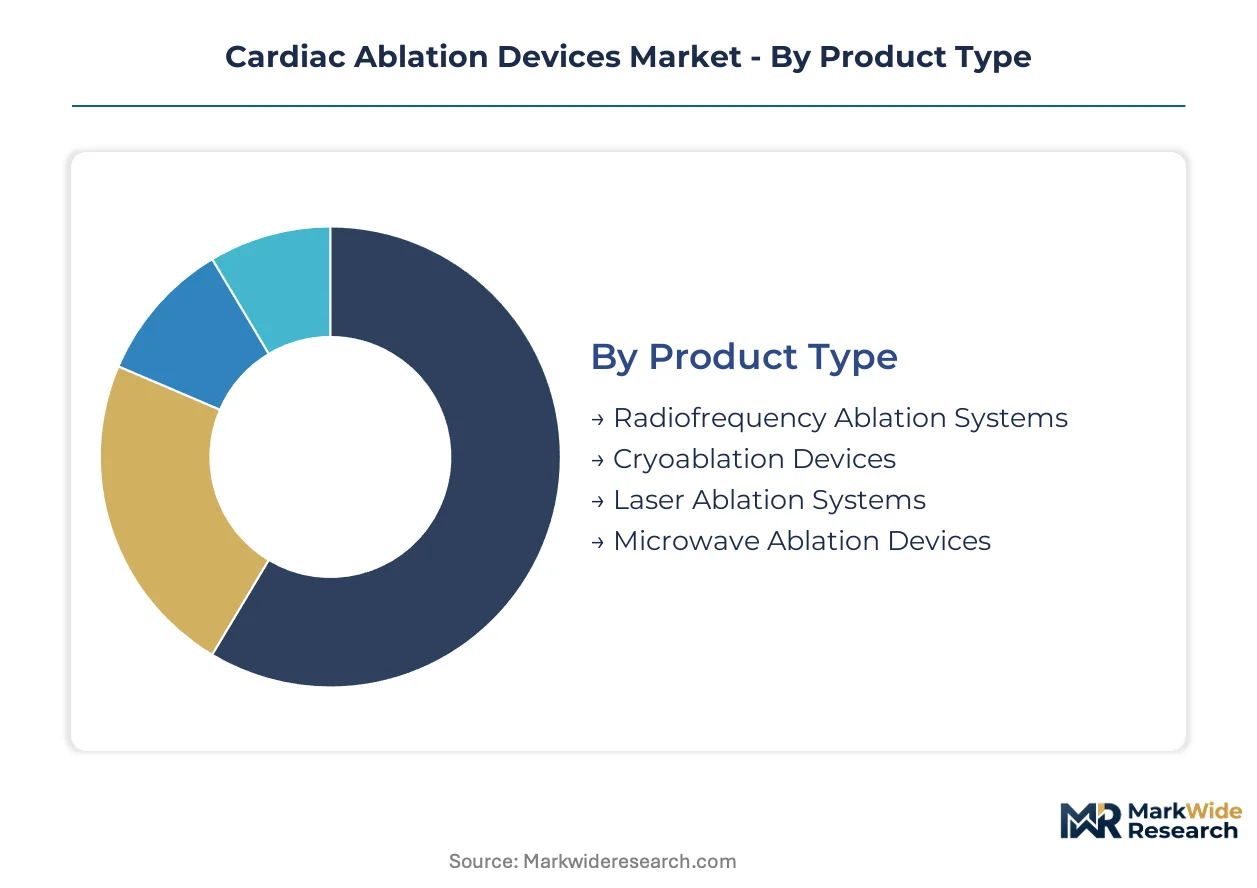
Cardiac ablation device segmentation reveals how procedural workflows, anatomical targets, and care delivery settings determine purchasing priorities. Upgrade cycles vary dramatically across these dimensions, with mapping platforms demanding shorter replacement timelines than capital-intensive generator systems.
Product Type:
Replacement cycles in cardiac ablation hardware stretch from five-year generator refreshes to annual catheter consumable turnover, creating divergent vendor engagement models across the installed base.
- Radiofrequency Ablation Systems:Thermal energy delivery platforms operating at 300-750 kHz dominate procedural volumes in tertiary cardiac centers across the United States and Germany. Operator familiarity and extensive catheter compatibility sustain loyalty despite longer procedure times compared to alternative modalities.
- Cryoablation Devices:Balloon-based cryothermal systems operating below minus 40 degrees Celsius enable single-shot pulmonary vein isolation protocols. Community hospitals in the United States adopt these systems to reduce training barriers and standardize atrial fibrillation outcomes.
- Laser Ablation Systems:Optical energy delivery platforms serve niche indications requiring precise tissue penetration depth control.
- Microwave Ablation Devices:Electromagnetic heating systems generate larger lesion footprints for select ventricular tachycardia applications.
Radiofrequency Ablation Systems sits at the top of the volume ranking, with Cryoablation Devices climbing the fastest.
Technology:
Technology selection in cardiac ablation tracks directly to lesion set complexity and anatomical access route, with software-enabled platforms commanding premium positioning over hardware-only alternatives.
- 3D Mapping Systems:Electroanatomical reconstruction platforms integrate magnetic or impedance-based localization with real-time catheter tracking. German electrophysiology suites prioritize these systems for complex atrial arrhythmia cases requiring precise ablation line continuity.
- Endocardial:Transcatheter approaches accessing the cardiac chambers through venous or arterial puncture represent the default technique for atrial fibrillation and supraventricular tachycardia. Japanese tertiary centers concentrate procedural volume here due to reimbursement alignment with catheter-based workflows.
- Epicardial:Surgical or percutaneous epicardial access enables ablation of arrhythmogenic substrates unreachable from the endocardial surface.
- Intracardiac Ultrasound:Real-time imaging modalities guide transseptal puncture and monitor lesion formation during energy delivery.
Endocardial approaches anchor the technology mix by procedure count, while 3D Mapping Systems capture the steepest expansion trajectory through software subscription models.
End User:
Site-of-care migration in cardiac ablation follows reimbursement incentives and capital availability, with outpatient settings gaining capacity as procedure complexity standardizes.
- Hospitals:Integrated health systems with electrophysiology labs maintain the deepest procedure mixes across atrial and ventricular indications. United States hospital systems bundle catheter purchases with multi-year mapping platform licenses to secure disposable volume commitments.
- Ambulatory Surgical Centers:Outpatient facilities in the United States expand catheter ablation capacity as pulmonary vein isolation protocols simplify anesthesia and recovery requirements. CMS reimbursement alignment supports this channel shift for uncomplicated atrial fibrillation cases.
- Specialty Clinics:Cardiovascular-focused outpatient centers concentrate follow-up and repeat procedure volumes.
- Research Institutions:Academic medical centers drive investigational device evaluations and next-generation technology validation.
Hospitals retain the dominant share of installed base value, though Ambulatory Surgical Centers are gaining share fastest as site-of-care economics shift.
Application:
Anatomical target selection determines device configuration, energy modality, and mapping complexity, with atrial indications supporting higher procedural volumes than ventricular applications.
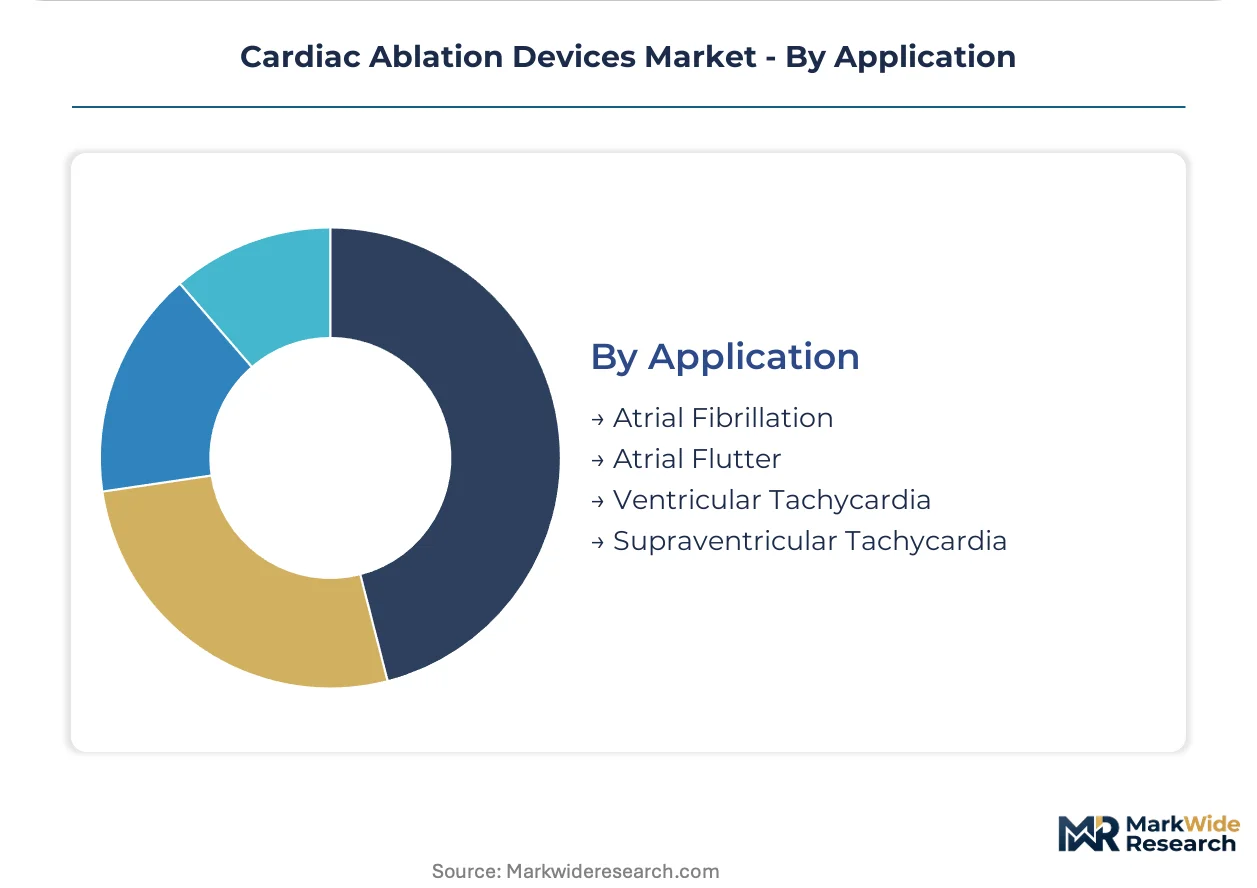
- Atrial Fibrillation:Irregular atrial electrical activity requiring pulmonary vein isolation or substrate modification drives the largest addressable patient population. Aging demographics in Japan expand treatable pools as drug-refractory cases accumulate in elderly cohorts.
- Ventricular Tachycardia:Life-threatening ventricular arrhythmias demand precise scar-border zone mapping and often combined endocardial-epicardial approaches. Recurrence rates in complex substrates limit penetration despite unmet clinical need.
- Atrial Flutter:Macroreentrant atrial circuits yield to simpler cavotricuspid isthmus ablation with high acute success rates.
- Supraventricular Tachycardia:Accessory pathway and atrioventricular nodal reentrant tachycardias respond to straightforward catheter ablation with excellent long-term outcomes.
Atrial Fibrillation leads application segmentation by procedure volume, while Ventricular Tachycardia represents the most technically demanding frontier with significant unmet need.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's electrophysiology suites deploy 3D mapping systems at higher density than Japan's tertiary centers, yet both markets concentrate procurement power within integrated hospital networks that negotiate multi-year platform commitments.
United States
Ambulatory surgical centers expand catheter ablation capacity as CMS reimbursement alignment supports outpatient pulmonary vein isolation. FDA premarket approval pathways demand extensive long-term safety databases for Class III devices. The Cleveland Clinic and Mayo Clinic anchor electrophysiology training pipelines that standardize procedure workflows across community hospital networks.
Germany
European MDR conformity assessments accelerate consolidation toward established manufacturers with robust quality management infrastructure. Aging demographics in Bavaria and North Rhine-Westphalia expand drug-refractory atrial fibrillation patient pools. Berlin-based procurement consortia negotiate enterprise-wide mapping platform licenses that bundle catheter purchases across hospital systems.
Japan
PMDA national health insurance listing pathways reward comparative effectiveness data against pharmacological alternatives. METI industrial policy supports domestic catheter manufacturing clusters in the Kansai region. Tokyo and Osaka tertiary cardiac centers concentrate the deepest procedure mixes across atrial and ventricular indications.
China
NMPA regulatory timelines extend market access preparation for foreign manufacturers seeking reimbursement under provincial health insurance frameworks. Domestic catheter producers in the Yangtze River Delta scale manufacturing capacity for radiofrequency ablation systems. Shanghai and Beijing academic medical centers drive investigational device evaluations for next-generation mapping technologies.
India
CDSCO medical device rules classify cardiac ablation catheters as Class C products requiring import licenses and local clinical data. Private hospital chains in Maharashtra and Karnataka expand electrophysiology lab infrastructure to capture medical tourism flows. Delhi-NCR tertiary centers concentrate training capacity for complex ventricular tachycardia ablation procedures.
Cardiac Ablation Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device ecosystems commanding premium positioning over standalone component suppliers. The vendor base concentrates around three tiers: diversified medtech conglomerates with full catheter-to-mapping platform portfolios, mid-scale specialists dominating single-modality niches, and regional manufacturers serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships between mapping software developers and catheter producers, plus backward integration into precision sensor component manufacturing.
Within the diversified conglomerate tier, Medtronic plc and Abbott Laboratories anchor competitive positioning through integrated hardware-software ecosystems that generate recurring subscription revenue beyond initial system placement. Johnson & Johnson's Biosense Webster unit exemplifies the premium-tier mapping specialist archetype. Biotronik SE & Co. KG represents the European-origin diversified player competing on regulatory compliance depth.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson (Biosense Webster) |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| AtriCure, Inc. |
| CardioFocus |
| AngioDynamics Inc. |
| Others |
Supply Flow & Price Mechanics
Precision sensor components and specialized catheter polymers originating in Japanese and German specialty chemical clusters cascade through three-tier pricing structures before reaching electrophysiology suites, with raw material concentration upstream amplifying margin capture at the mapping platform tier.
Pricing Analysis
Capacity additions in Chinese catheter manufacturing hubs are reshaping price floors for standard radiofrequency devices while premium 3D mapping systems sustain subscription-based pricing power through software lock-in. Pricing stratifies across premium, standard, and economy tiers driven by FDA approval tier and institutional volume scale. Cost compression in mid-tier generators is intensifying because procurement committees bundle hardware with multi-year disposable commitments. Community hospitals exhibit highest price sensitivity; tier-one cardiac centers demonstrate lowest.
Supply Chain Analysis
Microelectromechanical sensor supply rests on Taiwanese semiconductor foundries and Japanese precision component specialists. Raw material dependencies include platinum-iridium electrode alloys, biocompatible polymers, and cryogenic coolant gases. Single-source vulnerability concentrates in impedance-sensing chipsets. Distribution runs through GPO-negotiated contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electrophysiology suites prioritize integrated platform ecosystems over standalone hardware performance.
For Market Incumbents: Extend software-defined mapping subscriptions into ambulatory surgical centers to capture site-of-care migration before competitors establish footholds. Deepen backward integration into precision sensor manufacturing to offset Asian supply bottlenecks. Lock in catheter volume through enterprise-wide platform commitments that raise switching costs for hospital systems. For New Entrants and Emerging Players: Underserved community hospitals in the United States present the most penetrable entry point for robotic navigation systems that reduce training barriers. Target cryoablation balloon niches where procedural standardization enables faster certification pathways. Pursue regulatory-first positioning by prioritizing European MDR conformity to access consolidated procurement channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale mapping software specialists because hospital procurement consolidation demands full-stack platform capabilities. Five-to-ten-year viability hinges on recurring revenue conversion rates. Watch FDA breakthrough device designations as signals of platform-tier competitive shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Premarket approval pathways for Class III devices demand extensive clinical evidence investment. |
| CE Marking Pathway | European MDR conformity assessments favor established quality management infrastructure. |
| Hospital System Partnership | Enterprise-wide platform licenses bundle catheter purchases across integrated delivery networks. |
| Software Companion Development | AI-driven arrhythmia detection integration enables workflow automation premium pricing. |
| Reimbursement Strategy | PMDA national health insurance listing in Japan rewards comparative effectiveness data. |
Methodological Framework
Bottom-up electrophysiology lab modeling reconciled against top-down catheter production tracking forms the analytical core of this study. Primary interviews with electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) and PMA filings, European MDR notified body databases, CMS Medicare procedure data, and hospital procurement records. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map catheter consumption to procedural volumes across energy modality, anatomical target, and site-of-care dimensions over the projection horizon. CAGRs derive from installed base turnover rates and disposable pull-through coefficients. Forecast inputs incorporate electrophysiologist training pipeline capacity and reimbursement alignment trajectories by national health system.
Underlying measurement precision varies by segment; 3D mapping system revenue carries tighter precision than laser ablation niche volumes. Forecasts reflect assumptions about regulatory timeline stability and supply chain resiliency that regulatory friction or raw material constraints could revise. A small set of triggers—FDA breakthrough designations, European MDR enforcement actions, and Japanese reimbursement revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Global Photomedicine Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Dosing Units Market