
 Unilateral Biportal Endoscopy Market | 2026-2036
Unilateral Biportal Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Unilateral Biportal Endoscopy Market Intelligence
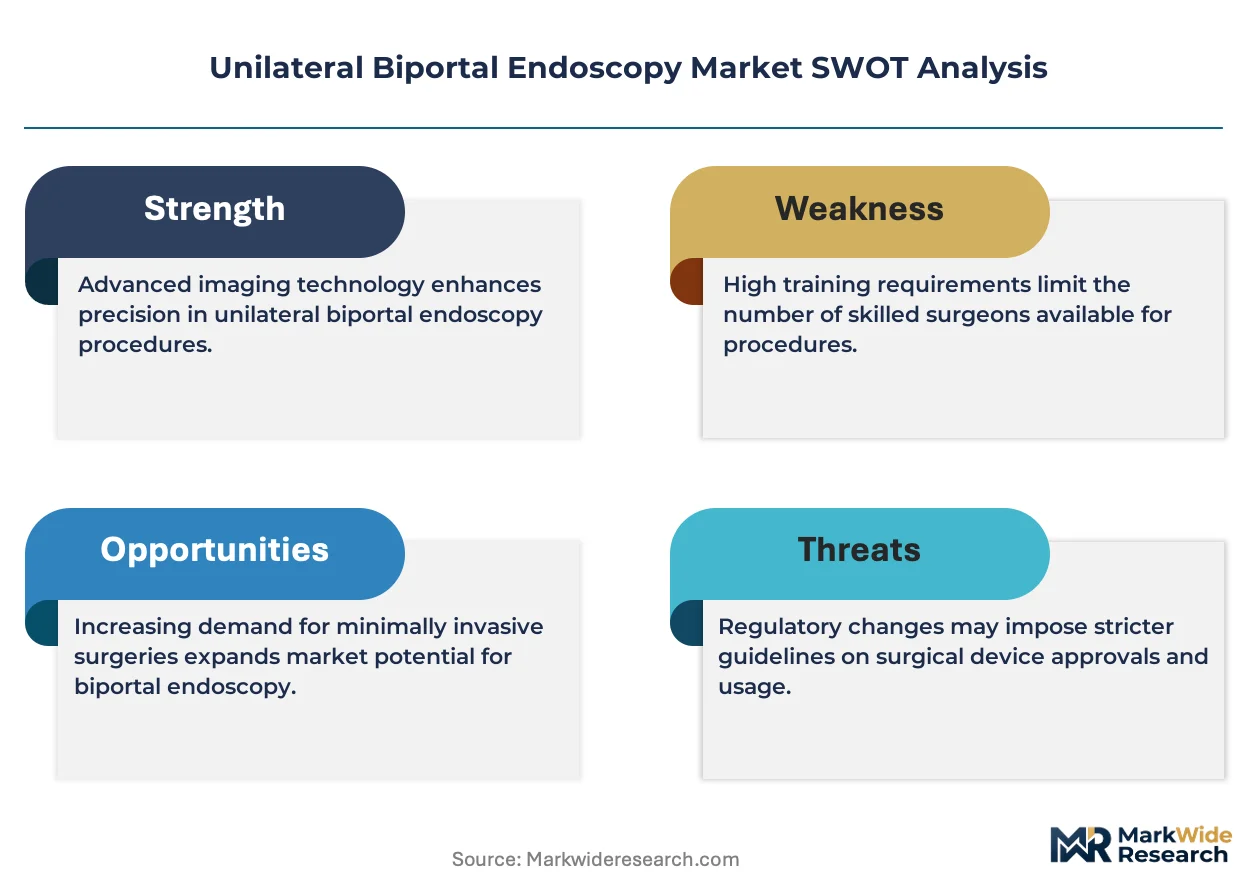
Modularization of visualization and instrument bundles is decoupling capital expenditure from per-procedure costs, giving hospitals flexibility to phase adoption. Stryker Corporation leverages its integrated operating room ecosystem to anchor premium system placements. Karl Storz competes through rigid endoscope specialization and optical precision. Joimax GmbH differentiates via dedicated spine endoscopy portfolios and surgeon education infrastructure.
Unilateral biportal endoscopy employs two independent portals—one for visualization and one for instrumentation—to access the spinal canal through a unilateral approach, typically utilizing a working channel diameter of 4.2 mm to 6.0 mm and high-definition or 3D camera systems to enable decompression and discectomy with preserved contralateral structures. The technology serves primarily to reduce paraspinal muscle damage and accelerate postoperative recovery relative to conventional open surgery. Endoscopes and high-definition imaging systems capture the dominant share of product type revenue, while robotic assistance represents the fastest-expanding technology segment as manufacturers integrate navigation and haptic feedback. Hospitals remain the largest end user category by installed base, though ambulatory surgical centers are expanding fastest as reimbursement and anesthesia protocols enable same-day discharge.
FDA 510(k) clearance requirements and EU MDR conformity assessments govern device commercialization and predicate-comparison standards for biportal spinal systems in the United States and Europe. South Korea's MFDS and Japan's PMDA maintain distinct technical documentation requirements that shape regional product registration timelines and clinical evidence thresholds. Surgeons, procurement committees, and device manufacturers must monitor evolving CMS outpatient procedure codes and national health insurance reimbursement decisions that will determine site-of-care economics and capital allocation priorities.
Market Dynamics
CMS reimbursement shifts for outpatient spine surgery are accelerating procedural migration from inpatient hospitals to ambulatory surgical centers, compressing capital deployment timelines and forcing manufacturers to reconfigure service models around same-day discharge protocols.
Growth Catalysts
- Outpatient Procedure Codes:CMS reimbursement decisions for ambulatory surgical centers are expanding site-of-care economics and enabling same-day discharge protocols for spinal decompression procedures.
- South Korea:MFDS regulatory pathways and dedicated surgeon training programs at Seoul-based spine centers are accelerating procedural adoption and device placement volumes.
- Visualization Modularity:Decoupled endoscope and instrument bundles allow hospitals to phase capital expenditure without per-procedure cost penalties, lowering adoption barriers for mid-tier facilities.
Market Restraints
- Optical Component Supply:German and Japanese precision optics suppliers concentrate high-definition camera sensor production, creating single-source vulnerability for 4K and 3D imaging systems.
- EU MDR Conformity:Extended clinical evidence requirements and notified body capacity constraints are lengthening biportal spinal system registration timelines by 12-18 months versus prior CE marking pathways.
- Open Microdiscectomy:Established surgical familiarity and lower capital requirements for conventional open procedures sustain competitive pressure in cost-sensitive hospital procurement environments.
Strategic Opportunities
- Germany:Underpenetrated outpatient spine networks in Bavaria and North Rhine-Westphalia present expansion potential as DRG reimbursement reforms incentivize ambulatory migration.
- Robotic Navigation Convergence:Integration of haptic feedback systems with biportal visualization platforms is opening premium positioning for next-generation surgical workstations.
- Direct-to-Facility Distribution:Bypassing traditional distributor networks for instrument bundle replenishment is capturing margin and accelerating inventory turns for high-volume surgical centers.
Industry Challenges
- Surgeon Training Bottlenecks:Cadaver lab capacity and proctored case requirements limit the pipeline of qualified biportal practitioners, constraining procedural volume growth in newly equipped facilities.
- Legacy OR Integration:Biportal visualization systems require incompatible video routing and insufflation infrastructure versus standard laparoscopic towers, forcing costly operating room retrofits or dedicated suite construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unilateral Biportal Endoscopy Market |
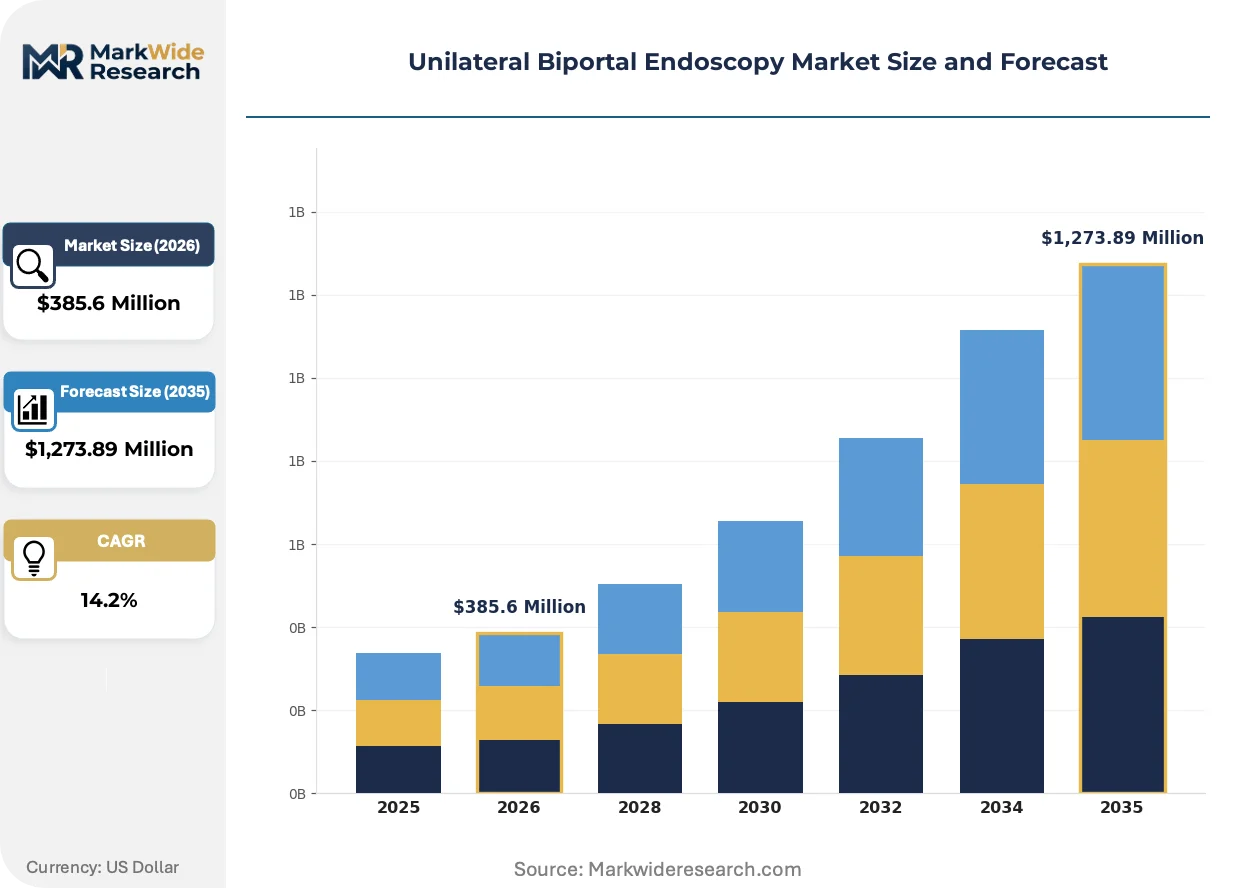
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,273.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Cameras, Light Sources, Accessories Application: Surgical Procedures, Diagnostics, Therapeutic Treatments, Tumor Resection End User: Hospitals, Ambulatory Surgical Centers, Outpatient Clinics, Research Institutions Technology: 3D Visualization, High-Definition Imaging, Wireless Connectivity, Robotic Assistance |
| Companies Covered | Stryker Corporation, Karl Storz, Smith & Nephew, Richard Wolf, Joimax GmbH, CONMED Corporation, Endovision Co. Ltd., Maxer Endoscopy GmbH, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unilateral Biportal Endoscopy Market Strategic Shifts & Innovations
Three interconnected developments are compressing the innovation cycle in minimally invasive spinal surgery: optical system evolution, regulatory pathway restructuring, and procurement model fragmentation. Each trend is reshaping how technology reaches the surgical suite.
High-definition and 3D camera systems are absorbing the functional demands previously met by operating microscopes, enabling binocular depth perception through endoscopic visualization alone. Ambulatory surgical centers in the United States are adopting these platforms fastest, driven by space constraints and capital efficiency requirements. This absorption is compressing the addressable market for standalone microscope manufacturers while expanding the premium tier of integrated biportal workstations.
The EU MDR framework is recasting clinical evidence requirements for spinal endoscopy systems, mandating extended follow-up data and stricter predicate device comparisons than prior CE marking directives. Manufacturers must now compile prospective registries or controlled studies to support conformity assessments, elevating documentation costs and extending time-to-market. Small and mid-sized device firms without existing clinical infrastructure face the steepest compliance burden, consolidating competitive advantage among established players with dedicated trial capabilities.
Hospital procurement committees are fragmenting purchasing authority between capital equipment committees and operating room supply managers, creating dual-track negotiation dynamics for biportal system vendors. Bundled visualization and instrument contracts are displacing standalone capital sales in integrated delivery networks, while ambulatory surgical centers favor per-procedure leasing arrangements with full service inclusion. This bifurcation is most pronounced in United States metropolitan markets where health system consolidation has concentrated buying power among regional networks.
Unilateral Biportal Endoscopy Market Segmentation
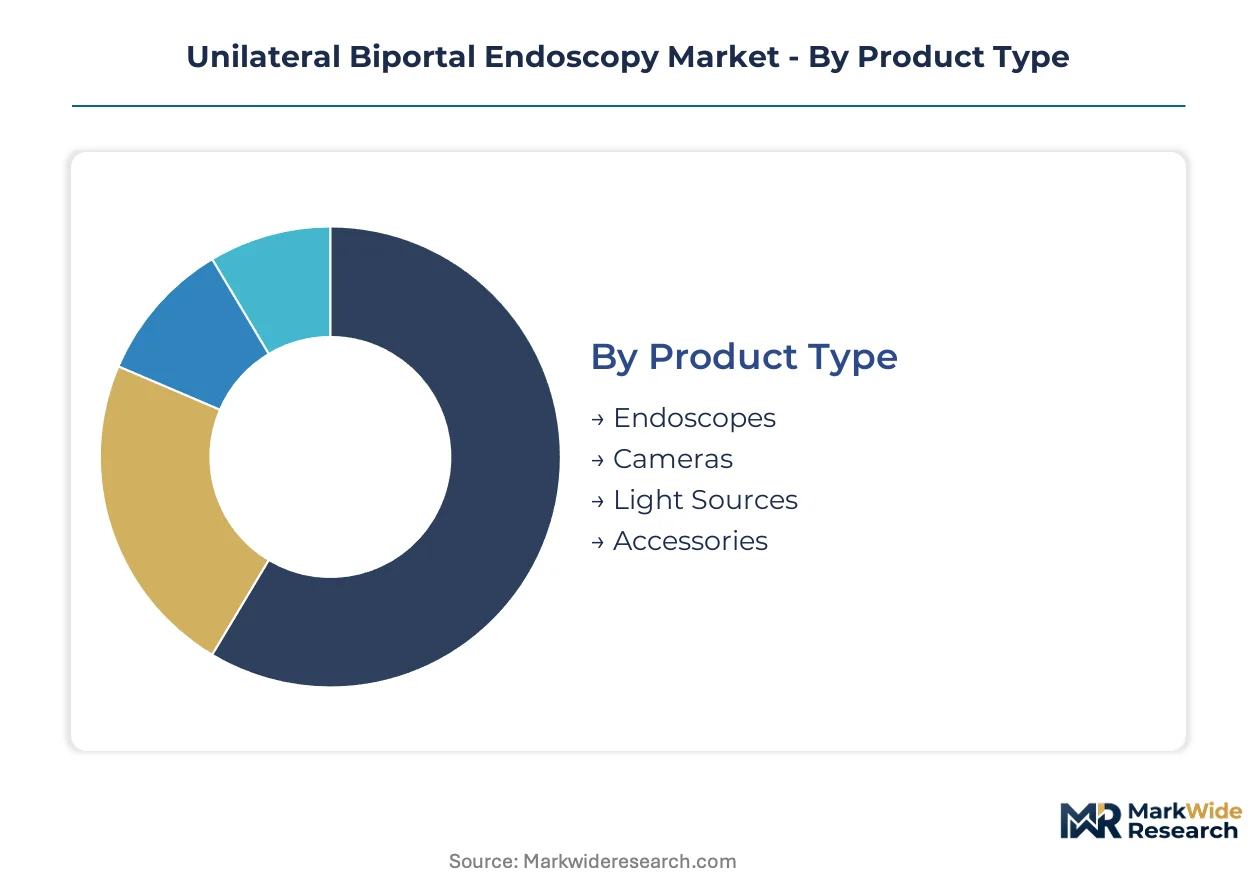
Segmentation in unilateral biportal endoscopy reveals how capital deployment, procedural site migration, and technology integration create divergent purchasing behaviors across healthcare facilities. Understanding these splits enables manufacturers to align product bundling and service models with specific customer economics.
Product Type:
Endoscopes and cameras function as the embedded core of every biportal procedure, while light sources and accessories operate as modular extensions that facilities phase based on case volume maturity.
- Endoscopes:Rigid rod-lens systems with 4.2 mm to 6.0 mm working channels deliver the optical pathway for unilateral canal access. Demand concentrates in Seoul and German spine centers where high-volume surgeons require dedicated instrument sets per operating room. Supply constraints from German and Japanese precision optics manufacturers create procurement bottlenecks for 4K and 3D configurations.
- Cameras:High-definition and 3D camera heads capture binocular depth perception previously requiring operating microscopes, enabling full endoscopic visualization. United States ambulatory surgical centers adopt these most aggressively due to space constraints and capital efficiency mandates, compressing standalone microscope addressable markets.
- Light Sources:LED and xenon illumination systems provide consistent intensity for deep spinal canal visualization.
- Accessories:Instrument bundles, irrigation tubing, and disposable sheaths complete the procedural setup.
Endoscopes lead volumes today; cameras are gaining share fastest.
Application:
Procedure type determines reimbursement coding, site-of-care eligibility, and the capital intensity of required instrumentation.
- Surgical Procedures:Lumbar decompression and discectomy via biportal access reduces paraspinal muscle disruption versus open approaches. United States ambulatory surgical centers drive procedural volume as CMS reimbursement shifts enable same-day discharge protocols.
- Diagnostics:Diagnostic biportal exploration supports preoperative planning and intraoperative confirmation of neural decompression completeness.
- Therapeutic Treatments:Epidural adhesiolysis and targeted drug delivery leverage the dual-portal approach for precise anatomical access.
- Tumor Resection:Intradural and extradural tumor removal via biportal corridors demands advanced hemostasis and dural repair capabilities.
Surgical procedures dominate current case volumes; tumor resection applications are expanding most quickly as optical and hemostatic technologies mature.
End User:
Facility type shapes procurement authority, capital availability, and service model expectations for biportal system vendors.
- Hospitals:Inpatient institutions maintain the largest installed base of biportal systems, though procedural migration pressures mount. Integrated delivery networks in United States metropolitan markets concentrate purchasing power, favoring bundled visualization and instrument contracts over standalone capital sales.
- Ambulatory Surgical Centers:Outpatient facilities represent the fastest-expanding end user category as anesthesia protocols and reimbursement codes enable same-day spinal surgery. These centers prefer per-procedure leasing with full service inclusion, forcing manufacturers to reconfigure pricing and support structures.
- Outpatient Clinics:Office-based settings adopt limited diagnostic and minor therapeutic applications.
- Research Institutions:Academic medical centers drive technique refinement and surgeon training pipeline development.
Hospitals retain the largest equipment base; ambulatory surgical centers are climbing the fastest.
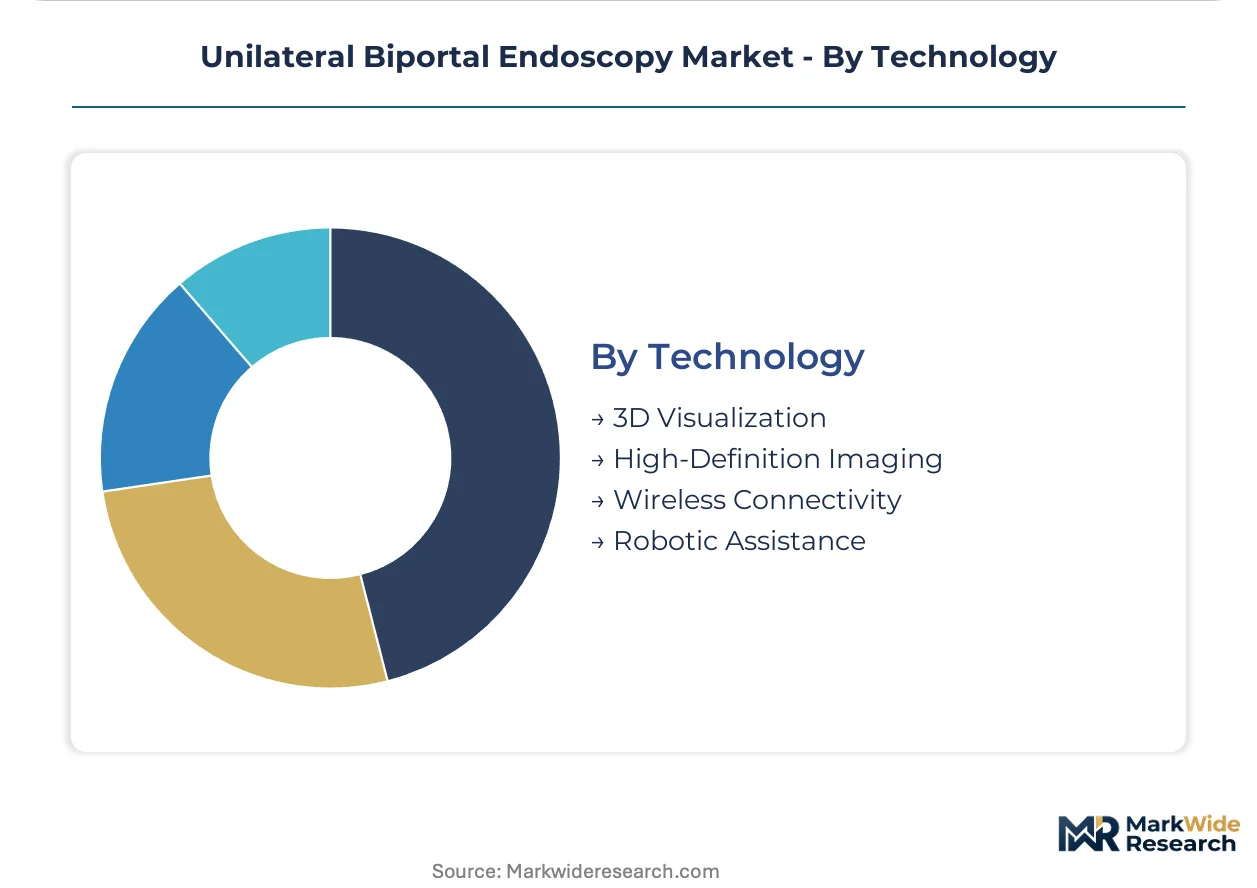
Technology:
Technology tier determines system positioning across premium integrated workstations and phased adoption pathways for cost-constrained facilities.
- 3D Visualization:Stereoscopic camera systems deliver binocular depth perception without operating microscope dependency. South Korean spine centers at Seoul National University Hospital and affiliated training networks pioneer clinical validation and surgeon education for these platforms.
- High-Definition Imaging:1080p and 4K resolution systems constitute the current standard for most newly deployed biportal platforms. German and Japanese component suppliers dominate sensor production, creating geographic concentration risk for manufacturers.
- Wireless Connectivity:Cable-free camera and display links reduce operating room clutter and sterilization burden.
- Robotic Assistance:Navigation integration and haptic feedback systems enable the steepest expansion trajectory among technology segments, opening premium positioning for next-generation surgical workstations.
High-definition imaging leads deployment volumes today; robotic assistance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unilateral biportal endoscopy originated in South Korean spine surgery centers during the early 2010s, where specialized training programs and high-volume surgical corridors first validated the dual-portal approach. From this foundation, adoption has diffused through surgeon education networks and regulatory harmonization efforts across three continents.
United States
Ambulatory surgical centers in Texas, Florida, and Arizona drive procedural volume as CMS reimbursement shifts enable same-day discharge protocols for spinal decompression. FDA 510(k) clearance pathways govern device commercialization, with predicate-comparison standards shaping submission strategies. The Dallas-Fort Worth metroplex hosts concentrated biportal surgery adoption where integrated delivery networks favor bundled visualization contracts.
South Korea
Seoul-based spine centers at Seoul National University Hospital and affiliated training networks pioneered clinical validation of 3D visualization platforms. MFDS regulatory pathways maintain distinct technical documentation requirements that shape regional product registration timelines. The Seoul Capital Area concentrates surgeon training infrastructure and dedicated biportal surgery centers that export technique protocols internationally.
Germany
Bavaria and North Rhine-Westphalia present underpenetrated outpatient spine networks where DRG reimbursement reforms incentivize ambulatory migration. EU MDR conformity assessments mandate extended clinical evidence requirements, lengthening registration timelines versus prior CE marking pathways. German precision optics suppliers concentrate high-definition camera sensor production, creating geographic concentration risk for 4K and 3D imaging systems.
Japan
PMDA technical documentation requirements establish clinical evidence thresholds distinct from US and European frameworks, shaping regional product registration strategies. Tokyo and Osaka metropolitan areas concentrate high-volume spine surgery centers where surgeon training bottlenecks constrain procedural growth. Japanese component suppliers dominate sensor production for advanced imaging systems, creating single-source vulnerability for manufacturers.
Unilateral Biportal Endoscopy Market Key Industry Players
Premium-margin players sit above commodity-margin players across visualization technology tiers, with integrated workstation vendors commanding pricing power over modular component suppliers. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with operating room ecosystem integration, specialized endoscopy manufacturers with optical precision heritage, and dedicated spine surgery firms with surgeon education infrastructure. Dominant competitive moves include strategic partnerships for robotic navigation convergence and direct-to-facility distribution models that bypass traditional networks.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic occupy positions anchoring premium system placements through integrated operating room ecosystems. Specialized endoscopy manufacturers Karl Storz and Richard Wolf exemplify optical precision heritage, with rigid endoscope specialization representing their competitive positioning. Dedicated spine surgery specialists Joimax GmbH and Maxer Endoscopy GmbH sit within the focused portfolio tier, with surgeon education infrastructure serving as their differentiation anchor.
| Leading Market Players |
|---|
| Stryker Corporation |
| Karl Storz |
| Smith & Nephew |
| Richard Wolf |
| Joimax GmbH |
| CONMED Corporation |
| Endovision Co. Ltd. |
| Maxer Endoscopy GmbH |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Modularization of visualization and instrument bundles is simultaneously compressing per-procedure cost economics and redistributing pricing power toward German and Japanese precision optics suppliers who control 4K and 3D camera sensor production. This decoupling of capital expenditure from consumable costs creates bifurcated procurement negotiations where hospitals phase adoption while ambulatory surgical centers demand full-service leasing models.
Pricing Analysis
Per-procedure leasing with full service inclusion dominates ambulatory surgical center procurement, while integrated delivery networks favor bundled visualization and instrument contracts over standalone capital sales. Pricing stratifies across premium integrated workstations, modular component systems, and economy-tier phased adoption pathways. Cost compression in mid-tier configurations is intensifying because procurement committees fragment purchasing authority between capital equipment and operating room supply managers. Ambulatory surgical centers exhibit highest price sensitivity; premium integrated workstation buyers show least.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and the United States maintain hub-and-spoke patterns for instrument bundle replenishment. High-definition camera sensor production concentrates in Germany and Japan, while rigid endoscope manufacturing anchors in South Korea and Germany. Single-source vulnerability for 4K and 3D imaging systems creates structural risk. Distribution runs through direct-to-facility channels that bypass traditional distributor networks for high-volume surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR conformity assessment delays create 12-18 month registration advantages for manufacturers with established clinical infrastructure in South Korea and the United States.
For Market Incumbents: Extend surgeon education infrastructure to constrain competitor access to qualified practitioners, and deepen backward integration into precision optics supply to mitigate German and Japanese sensor concentration risk. Robotic navigation convergence threatens standalone visualization margins; anchor premium positioning through haptic feedback integration. For New Entrants and Emerging Players: The gap between premium robotic-assisted workstations and economy-tier modular systems offers white-space entry. Target underpenetrated outpatient spine networks in Bavaria and North Rhine-Westphalia where DRG reforms incentivize ambulatory migration. Pursue direct-to-facility distribution partnerships to capture margin and accelerate inventory turns. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized endoscopy manufacturers lacking integrated robotic navigation capabilities. The five-to-ten year viability window favors acquisition of dedicated spine surgery firms with established surgeon training infrastructure. Watch CMS outpatient procedure code expansions as the inflection signal for ambulatory surgical center capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Surgeon Education Infrastructure Expansion | Proctored case requirements and cadaver lab capacity constrain qualified practitioner pipelines. |
| Robotic Navigation Integration | Haptic feedback convergence with biportal visualization opens premium workstation positioning. |
| Direct-to-Facility Distribution | Bypassing traditional distributors captures margin and accelerates inventory turns for high-volume centers. |
| EU MDR Conformity Investment | Extended clinical evidence requirements favor established players with dedicated trial capabilities. |
| Per-Procedure Leasing Model | Ambulatory surgical center preference for full-service inclusion forces pricing structure reconfiguration. |
Research Approach
Bottom-up ambulatory surgical center and hospital procurement modeling reconciled against top-down precision optics and endoscope manufacturing tracking forms the analytical core. Primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, MFDS registration databases, CMS outpatient procedure code releases, and EU MDR notified body capacity reports. Triangulation between demand-side facility adoption curves and supply-side component production constraints anchors volume estimates.
Historical trendline analysis of procedural migration patterns from inpatient to outpatient settings informs the projection framework. Segmentation dimensions modeled include product type, application, end user, technology tier, and regional regulatory cluster. CAGRs derive from fitted adoption curves applied to reimbursement-code-enabled site-of-care shifts. Forecast inputs incorporate surgeon training pipeline constraints and operating room retrofit requirements.
The model assumes a particular technology adoption path; alternative pathways for robotic assistance integration would alter the outlook. Forecasts reflect documented assumptions around CMS reimbursement decisions, EU MDR notified body capacity, and precision optics supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Radiology Devices Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Bone Power Tools Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Canada Aesthetic Devices Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
T-Piece Resuscitator Market