
 Global Stereotactic Surgery Devices Market | 2026-2036
Global Stereotactic Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stereotactic Surgery Devices Market Analysis
A shortage of fellowship-trained neuro-navigation specialists is unwinding capacity constraints at major academic medical centers. Medtronic plc leverages its integrated surgical ecosystem to dominate cranial navigation installations across North American hospital networks. Elekta AB anchors its position through sustained R&D intensity in gamma knife platform evolution, while Brainlab AG differentiates via software-centric workflows that reduce intraoperative imaging dependencies.
Stereotactic surgery devices comprise precision instruments, integrated imaging systems, and planning software that enable sub-millimeter targeting of intracranial structures using fixed coordinate frames or frameless optical tracking. These systems typically achieve spatial accuracy below one millimeter through rigid skull fixation or adhesive fiducial arrays, serving primary purposes in tumor biopsy, deep brain stimulation electrode placement, and radiosurgical lesion creation. Systems hardware captures the dominant value pool given capital intensity and replacement cycles, while robotic-assisted delivery modes represent the fastest-expanding segment as hospitals seek to reduce operative time and improve trajectory reproducibility. Software modules command premium margins due to recurring license structures and AI-enhanced planning algorithms that integrate multimodal imaging.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern device commercialization, with both frameworks intensifying clinical evidence requirements for software-as-medical-device components. The EPA and national radiation safety agencies in Germany and Japan further regulate cobalt-60 source handling and linear accelerator shielding specifications. Stakeholders must monitor evolving MDR notified body capacity and FDA guidance on machine learning-enabled surgical planning tools to anticipate compliance timelines and competitive positioning shifts.
Market Dynamics
Robotic-assisted delivery systems are compressing operative timelines and forcing traditional frame-based manufacturers to accelerate software integration roadmaps or cede high-volume academic accounts.
Growth Catalysts
- FDA 510(k) streamlining:Expedited review pathways for Class II surgical navigation devices are shortening commercialization timelines for robotic biopsy platforms entering United States hospital networks.
- Gamma knife center proliferation:Dedicated stereotactic radiosurgery facilities in Germany and Japan are generating installed base expansion and recurring cobalt-60 source replacement demand.
- Frameless optical tracking:Adhesive fiducial arrays eliminating skull fixation hardware are broadening eligible patient populations and reducing anesthesia requirements in outpatient settings.
Market Restraints
- Cobalt-60 supply concentration:Radioisotope sourcing depends on aging nuclear reactor infrastructure concentrated in Russia and South Africa, creating shipment volatility and sterilization certification delays.
- EU MDR notified body bottleneck:Software-as-medical-device components face extended clinical evidence reviews under intensified post-market surveillance requirements, stretching compliance timelines to 18-24 months.
- Linear accelerator shielding costs:Concrete bunker construction and radiation safety compliance for intraoperative MRI suites add fixed costs exceeding standard operating room retrofit budgets.
Strategic Opportunities
- Pediatric neuro-oncology expansion:Minimally invasive biopsy trajectories enabled by frameless navigation are opening pediatric cases previously excluded from stereotactic protocols due to cranial immaturity.
- AI-enhanced planning modules:Machine learning algorithms integrating diffusion tensor imaging with functional MRI are creating premium software licensing tiers with recurring revenue structures.
- India tertiary hospital buildout:Government medical college expansion programs in Maharashtra and Tamil Nadu are creating first-mover advantages for navigation platform vendors offering training-intensive installation packages.
Industry Challenges
- Fellowship-trained specialist scarcity:Neuro-navigation credentialing programs at academic medical centers in the United States and Germany are producing fewer qualified operators than installed base expansion requires.
- Legacy PACS integration complexity:Hospital information system architectures built on DICOM variants predating multimodal imaging fusion are forcing costly middleware development for seamless surgical planning workflows.
- Cobalt-60 disposal liability:End-of-life source return logistics and decommissioning bonds for gamma knife units are creating balance sheet contingencies that distort equipment financing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stereotactic Surgery Devices Market |
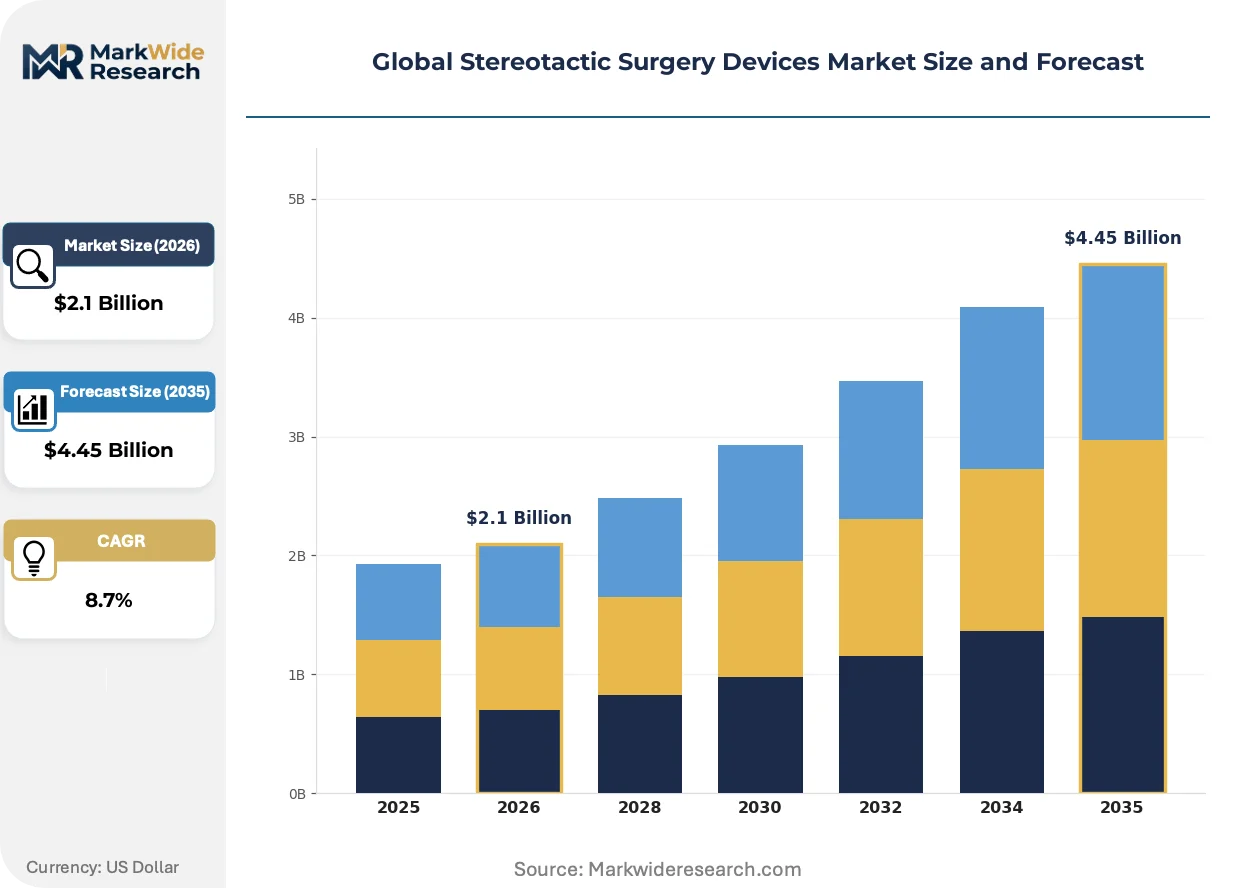
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systems, Instruments, Accessories, Software Technology: Magnetic Resonance, Computed Tomography, Ultrasound, Electromagnetic Delivery Mode: Open Surgery, Minimally Invasive, Robotic-Assisted, Image-Guided End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions |
| Companies Covered | Medtronic plc, IBA, Elekta AB, Micromar, Siemens AG, Accuray Incorporated, Brainlab AG, Monteris Medical, Varian Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stereotactic Surgery Devices Market Emerging Trajectories
Convergence of intraoperative imaging with autonomous trajectory planning is redistributing value capture from hardware vendors toward algorithm developers and clinical workflow integrators.
Intraoperative MRI guidance is fragmenting the traditional distinction between diagnostic imaging suites and sterile surgical fields. Tertiary neurosurgical departments in the United States and Germany are installing 3-tesla scanners with magnetically compatible navigation instruments, collapsing the feedback loop between lesion resection and anatomical verification. This architecture is fragmenting procurement decisions as radiology and surgery departments negotiate shared capital allocation and staffing models.
EU MDR Article 10 clinical evidence requirements for software-as-medical-device components are elevating post-market surveillance burdens for surgical planning algorithms. Manufacturers must now maintain active implant registries and periodic safety update reports for AI-enabled targeting systems, shifting competitive advantage toward vendors with established quality management systems. European notified bodies are prioritizing review capacity for stereotactic applications given patient risk classification, creating queue advantages for early filers.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing vendors to compete on discrete maintenance pricing and training fee transparency. Academic medical centers in Japan are piloting outcome-indexed service agreements where annual software license fees adjust based on system uptime and navigation accuracy metrics. This model is concentrating vendor selection authority within biomedical engineering departments rather than surgeon preference alone.
Global Stereotactic Surgery Devices Market Segmentation
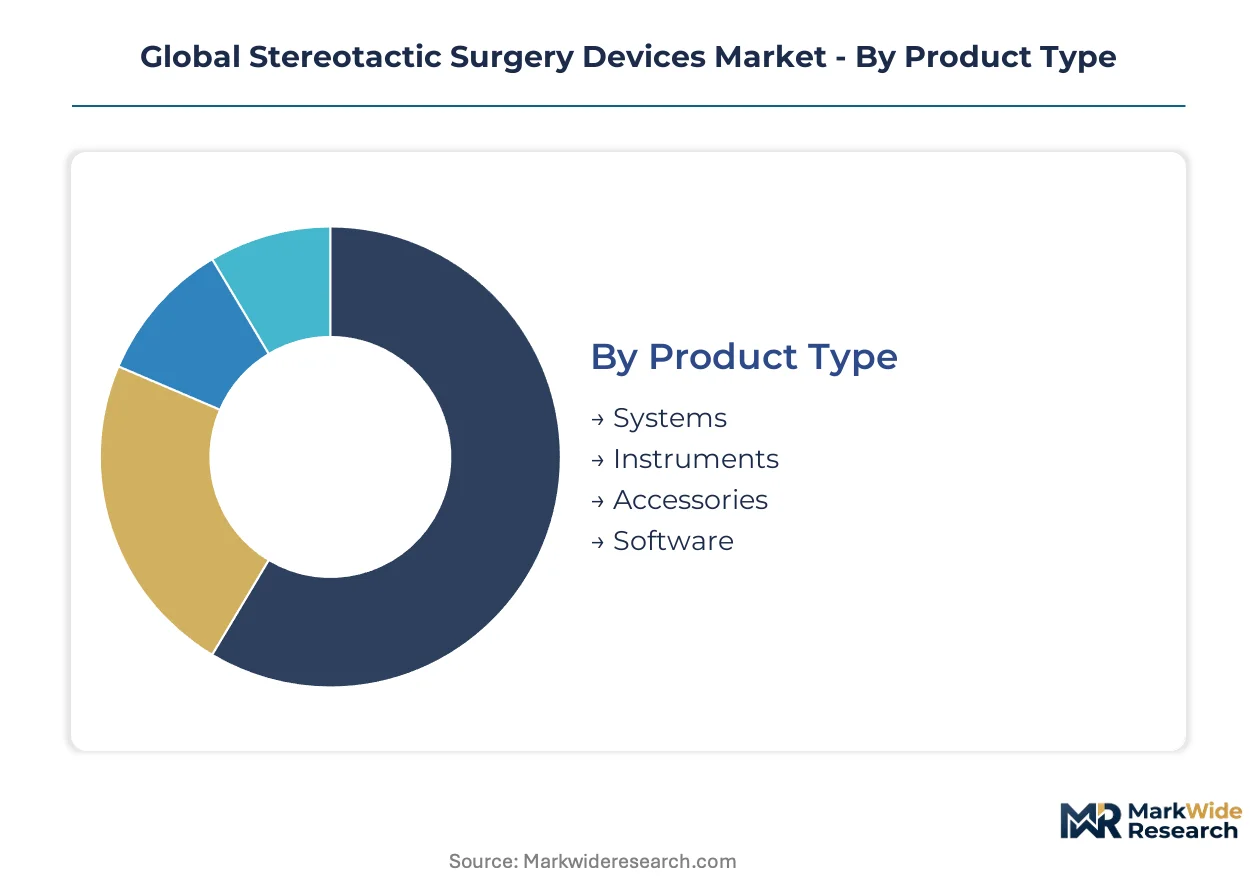
Stereotactic surgery devices fragment across four dimensions that reshape procurement patterns and vendor positioning. Product type determines capital intensity and replacement cycles. Technology selection governs imaging fusion capabilities and spatial accuracy thresholds.
Product Type:
Systems hardware faces substitution pressure from modular software upgrades that extend legacy platform lifecycles without full capital replacement.
- Systems:Capital-intensive platforms integrating imaging interfaces, navigation workstations, and robotic arms achieve sub-millimeter accuracy through rigid coordinate frames or optical tracking arrays. Demand concentrates in tertiary neurosurgical departments across the United States, Germany, and Japan as these institutions build dedicated radiosurgery centers requiring cobalt-60 or linear accelerator infrastructure.
- Software:Planning modules with AI-enhanced multimodal imaging fusion and trajectory optimization command premium licensing fees through recurring subscription structures. Academic medical centers in North America and Europe prioritize software procurement for frameless navigation workflows that reduce intraoperative imaging dependencies.
- Instruments:Biopsy needles, electrode introducers, and fixation hardware with sterilization-compatible materials.
- Accessories:Disposable fiducial arrays, adhesive markers, and patient-specific mounting interfaces.
Systems anchor the volume base while software gains share at the steepest rate.
Technology:
Cost tier stratification separates premium magnetic resonance integration from budget ultrasound alternatives in emerging hospital markets.
- Magnetic Resonance:Intraoperative 3-tesla scanners with magnetically compatible navigation instruments collapse the feedback loop between lesion resection and anatomical verification. Tertiary departments in Germany and the United States lead installed base expansion as radiology and surgery departments negotiate shared capital allocation models.
- Computed Tomography:Rapid bone-optimized imaging enables real-time trajectory verification during spinal and cranial procedures. Demand clusters in Japan and the United States where outpatient stereotactic protocols require fast acquisition times incompatible with lengthy MRI sequences.
- Ultrasound:Portable, low-cost guidance for ventricular catheter placement and soft tissue targeting.
- Electromagnetic:Wire-based tracking without line-of-sight constraints for flexible endoscopic applications.
Magnetic resonance commands the premium tier while ultrasound expands most quickly in cost-constrained settings.
Delivery Mode:
Application severity dictates delivery selection, with high-accuracy intracranial procedures demanding robotic precision that open approaches cannot match.
- Robotic-Assisted:Autonomous trajectory planning with haptic feedback and reproducible positioning reduces operative time and improves electrode placement consistency. Academic medical centers in the United States and Germany accelerate adoption as fellowship-trained specialist scarcity forces technology-mediated skill amplification.
- Minimally Invasive:Frameless optical tracking with adhesive fiducial arrays eliminates skull fixation hardware, broadening eligible patient populations. Outpatient settings in Japan and Germany favor this modality for reduced anesthesia requirements and same-day discharge protocols.
- Image-Guided:Real-time navigation overlay on preoperative scans without robotic manipulation.
- Open Surgery:Traditional frame-based stereotaxy with rigid skull fixation for complex trajectories.
Minimally invasive approaches anchor current volume while robotic-assisted delivery climbs the fastest as hospitals seek operative efficiency gains.
End User:
Customer type concentration favors hospitals with integrated neurosurgical departments over fragmented clinic networks lacking capital procurement authority.
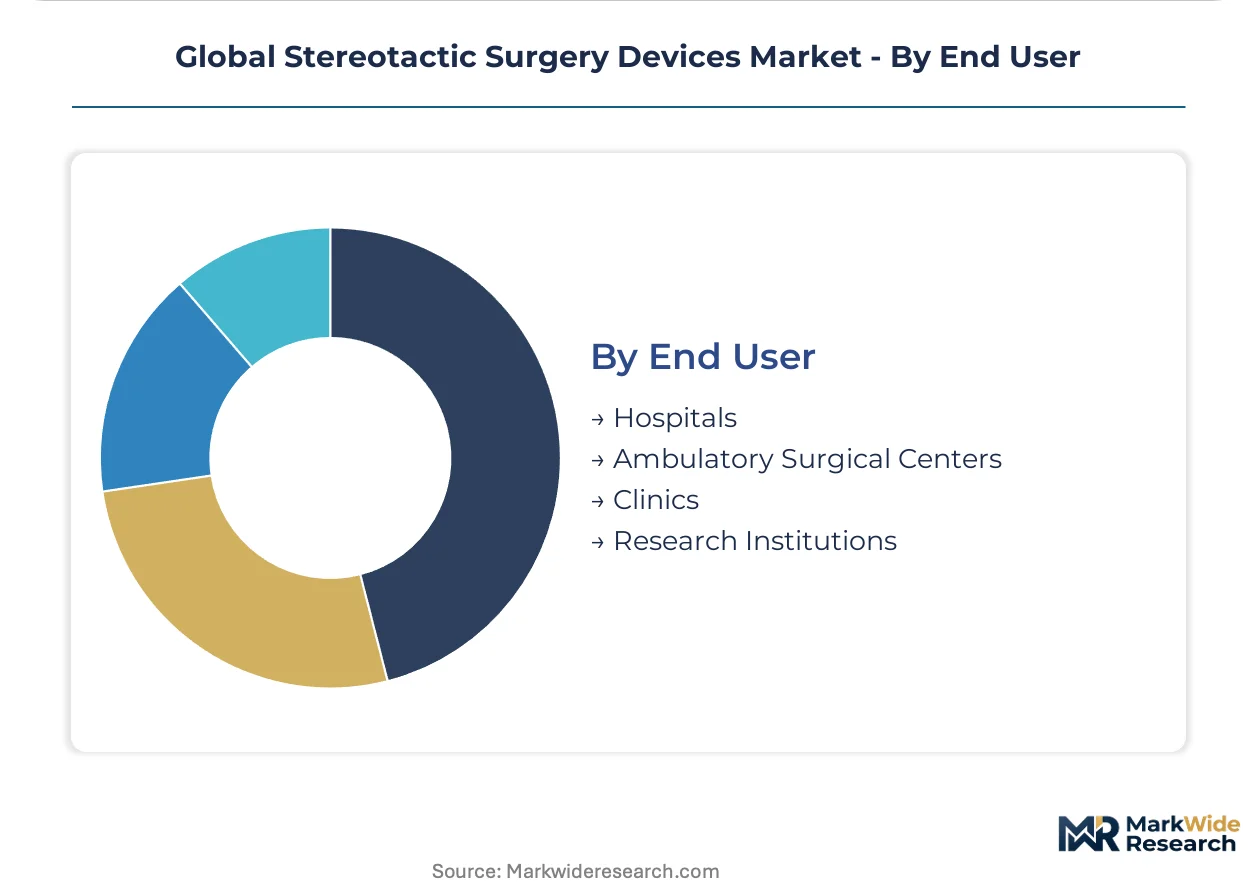
- Hospitals:Tertiary academic centers with fellowship-trained neuro-navigation specialists and dedicated radiosurgery suites capture the dominant installed base. Institutions in the United States, Germany, and Japan lead gamma knife center proliferation and intraoperative MRI suite construction.
- Ambulatory Surgical Centers:Frameless navigation platforms enabling outpatient biopsy and deep brain stimulation electrode placement expand addressable procedure volumes. Medicare reimbursement alignment in the United States and private payer contracts in Germany accelerate site-of-service migration.
- Clinics:Limited to consultation and follow-up without capital-intensive surgical capabilities.
- Research Institutions:Preclinical validation and algorithm development for AI-enhanced planning tools.
Hospitals retain the volume anchor while ambulatory surgical centers show the steepest expansion trajectory as reimbursement frameworks shift toward lower-acuity settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography, while CE marking under EU MDR and Japan's PMDA shape commercialization timelines across other major markets. Germany and Japan follow as concentrated demand centers for gamma knife infrastructure and robotic navigation platforms.
United States
Medicare reimbursement alignment for outpatient stereotactic procedures and dedicated radiosurgery center construction at academic medical centers drive installed base expansion. FDA 510(k) streamlining for Class II surgical navigation devices shortens commercialization timelines for robotic biopsy platforms. The Greater Boston and Pacific Northwest clusters concentrate gamma knife center proliferation and intraoperative MRI suite investments.
Germany
Government-funded medical college expansion and tertiary hospital neurosurgical department buildout generate demand for frameless navigation platforms. CE marking under EU MDR intensifies clinical evidence requirements for software-as-medical-device components, stretching compliance timelines. The Bavaria and North Rhine-Westphalia regions anchor gamma knife center concentration and fellowship-trained specialist training programs.
Japan
PMDA regulatory frameworks and aging demographics accelerate adoption of minimally invasive biopsy protocols in outpatient settings. METI industrial policy supports domestic medical device manufacturing and robotic-assisted delivery system development. The Kanto and Kansai regions concentrate dedicated stereotactic radiosurgery facilities and university hospital navigation platform installations.
India
Government medical college expansion programs in Maharashtra and Tamil Nadu create first-mover advantages for navigation platform vendors offering training-intensive installation packages. CDSCO device registration pathways govern commercialization for imported stereotactic systems. The Delhi-NCR and Karnataka clusters emerge as tertiary hospital buildout centers with integrated neurosurgical department investments.
United Kingdom
NHS England specialized commissioning frameworks for stereotactic radiosurgery concentrate procurement decisions at designated cancer centers. MHRA post-Brexit regulatory alignment with EU MDR creates transitional compliance complexity for software-enabled planning tools. The London/Southeast and Midlands regions anchor academic medical center investments in frameless optical tracking platforms.
Global Stereotactic Surgery Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational conglomerates controlling hardware ecosystems while software-centric vendors capture recurring licensing revenue. The market structure favors vendors with established quality management systems and active implant registries under EU MDR surveillance requirements. Two strategic archetypes dominate: integrated surgical ecosystem providers spanning imaging-to-navigation workflows, and focused software vendors differentiating through AI-enhanced planning algorithms. Competitive moves concentrate on M&A for navigation software capabilities and strategic partnerships for cobalt-60 source security.
Within the integrated ecosystem tier, Medtronic plc and Siemens AG exemplify multinational conglomerates leveraging imaging and surgical navigation integration. Elekta AB and Brainlab AG occupy positions as focused specialists, with the former representing gamma knife platform evolution and the latter exemplifying software-centric workflow reduction of intraoperative imaging dependencies. Accuray Incorporated and Varian Medical Systems sit within the radiation therapy convergence archetype, bridging traditional linear accelerator expertise with stereotactic delivery modes.
| Leading Market Players |
|---|
| Medtronic plc |
| IBA |
| Elekta AB |
| Micromar |
| Siemens AG |
| Accuray Incorporated |
| Brainlab AG |
| Monteris Medical |
| Varian Medical Systems |
| Others |
Supply Flow & Price Mechanics
Ninety-day cobalt-60 source replacement cycles concentrate pricing power among vendors with secured radioisotope supply contracts, while hospitals absorb bunker construction costs that exceed standard operating room retrofit budgets by substantial margins. This lead-time rigidity forces procurement committees toward outcome-indexed service agreements where software license fees adjust based on system uptime metrics.
Pricing Analysis
United States hospital networks pay premium licensing fees compared to German and Japanese equivalents due to Medicare reimbursement alignment for outpatient procedures. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced planning modules from basic navigation software and open-source alternatives. Cost compression in software tiers intensifies as hospitals unbundle after-sales service contracts from capital equipment purchases. Academic medical centers show least price sensitivity given fellowship-trained specialist scarcity, while ambulatory surgical centers negotiate aggressively on discrete maintenance pricing.
Supply Chain Analysis
Aging nuclear reactor infrastructure in Russia and South Africa creates chokepoint vulnerability for cobalt-60 radioisotope sourcing, forcing gamma knife manufacturers into long-term sterilization certification commitments. Magnet manufacturing for intraoperative MRI compatibility draws from China and Germany, while precision optical tracking arrays source from Japan and the United States. Single-source vulnerability concentrates in radioisotope supply given reactor decommissioning schedules. Distribution runs through hospital procurement committees with radiology and surgery department joint decision-making authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control scarce fellowship-trained neuro-navigation specialists and secured cobalt-60 supply chains, while penalizing those dependent on aging PACS integration architectures.
For Market Incumbents: Secure exclusive training partnerships with academic medical centers in Bavaria and North Rhine-Westphalia to lock in specialist pipeline access before EU MDR compliance timelines stretch further. Deepen backward integration into cobalt-60 source logistics through decommissioning bond structures that distort competitor financing. Frameless optical tracking substitution threatens traditional frame-based hardware revenue; software license recurring structures offer defensive margin protection. For New Entrants and Emerging Players: Lead with AI-enhanced planning modules targeting pediatric neuro-oncology expansion in Maharashtra and Tamil Nadu, where government medical college buildout creates first-mover training relationships. Minimally invasive frameless navigation shows deepest underpenetration in Indian tertiary hospitals lacking legacy PACS integration burdens. Go-to-market through training-intensive installation packages that embed clinical workflow expertise. For Investors and Strategic Acquirers: Long-term, this sits as a quality-management-system play because EU MDR Article 10 surveillance requirements elevate post-market registry maintenance burdens that favor established vendors with active implant tracking infrastructure. Acquisition target archetype: software-centric workflow vendors with AI-enhanced multimodal imaging fusion and hospital system validation. Signal to watch: FDA guidance publication on machine learning-enabled surgical planning tools as inflection indicator for compliance timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body prioritization for stereotactic applications creates queue advantages for early filers. |
| Hospital System Partnership | Shared capital allocation models between radiology and surgery departments fragment traditional procurement authority. |
| Software Companion Development | AI-enhanced planning algorithms integrating diffusion tensor imaging command premium recurring license tiers. |
| Reimbursement Strategy | Medicare alignment for outpatient stereotactic procedures accelerates site-of-service migration to ambulatory settings. |
| Regulatory Approval Pathway | FDA 510(k) streamlining for Class II surgical navigation devices shortens robotic platform commercialization timelines. |
Methodological Framework
Operator-level perspectives from neurosurgeons, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, CE marking databases under EU MDR, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up installed base modeling triangulated against top-down market sizing across systems hardware, software licensing, and service revenue streams.
Sensitivity analysis tested forecast outputs against variable adoption rates for robotic-assisted delivery modes and frameless optical tracking penetration. Segmentation dimensions modeled include product type, technology platform, delivery mode, and end-user facility tier across the projection horizon. CAGRs derived from procedure volume growth, replacement cycle dynamics, and software subscription expansion. Industry-specific inputs incorporated cobalt-60 source availability constraints and fellowship program graduation rates.
The analysis sits within stated boundaries; outcomes outside sustained gamma knife center construction in Germany and Japan or accelerated FDA guidance on AI-enabled planning tools would require recalibration. Forecasts reflect documented assumptions regarding reimbursement alignment and regulatory clearance timelines. Practitioners should keep alternative scenarios live as EU MDR notified body capacity and radioisotope reactor decommissioning schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Recanalization System Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Pelvic Muscle Probes Market