
 Ultrasonic Aspirator Market | 2026-2036
Ultrasonic Aspirator Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Aspirator Market Analysis
Aftermarket service revenue is reshaping profitability in the ultrasonic aspirator landscape. Stryker Corp. leverages its integrated hospital service contracts to capture recurring revenue streams. Olympus Corp. sustains competitive positioning through specialized endoscope-aspirator bundling. Richard Wolf GmbH anchors its presence in rigid endoscopy hubs across Central Europe.
An ultrasonic aspirator is a surgical device that employs high-frequency mechanical vibrations, typically at 23-36 kHz, to fragment and simultaneously aspirate tissue with minimal thermal damage to adjacent structures. Piezoelectric technology leads the technology segment due to superior frequency stability and energy efficiency in neurosurgical applications. Fixed units dominate the product type category in tertiary hospitals, while portable units represent the fastest-growing configuration as ambulatory surgical centers expand their neurosurgical and otolaryngology service lines.
The FDA's Class II 510(k) clearance framework and the EU Medical Device Regulation (MDR) impose stringent biocompatibility and electromagnetic compatibility standards on ultrasonic aspirator manufacturers. Japan's PMDA and METI coordinate premarket approval processes that extend development cycles but ensure clinical validation rigor. Stakeholders must monitor evolving reimbursement pathways for outpatient neurosurgical procedures as site-of-care shifts accelerate.
Market Dynamics
Aftermarket service revenue streams are restructuring competitive economics in ultrasonic aspirators as manufacturers pivot from capital sales to recurring income models. Piezoelectric transducer reliability improvements and ambulatory surgical center expansion are compressing replacement cycles while expanding addressable procedure volumes.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient neurosurgical and otolaryngology procedure migration drives portable ultrasonic aspirator demand. Medicare reimbursement pathway evolution for site-of-care shifts accelerates capital deployment in freestanding surgery centers.
- EU MDR Harmonization:Consolidated biocompatibility and electromagnetic compatibility standards streamline multi-country market access for manufacturers holding CE marking. Regulatory clarity reduces redundant testing burdens across member states.
- Piezoelectric Frequency Stability:Superior energy efficiency at 23-36 kHz operating ranges enables precise tissue fragmentation with minimized thermal spread. Neurosurgical adoption concentrates in tertiary hospital upgrades of integrated operating suites.
Market Restraints
- Piezoelectric Ceramic Supply Concentration:High-purity lead zirconate titanate sourcing depends on limited specialty chemical suppliers in East Asia. Input cost volatility transmits directly to transducer manufacturing economics.
- Capital Equipment Replacement Cycles:Fixed ultrasonic aspirator installations in established tertiary hospitals exhibit decade-long depreciation schedules. Extended useful lives suppress recurring revenue from replacement sales.
- CO2 Laser Substitution:Alternative soft tissue ablation technologies compete for otolaryngology and neurosurgical applications where thermal precision requirements are less stringent. Price-sensitive buyers evaluate total cost of ownership tradeoffs.
Strategic Opportunities
- India Surgical Infrastructure Buildout:Government hospital modernization programs and medical device PLI scheme incentives create import substitution openings. Domestic manufacturing partnerships with Tuttlingen precision instrument clusters accelerate technology transfer.
- Endoscope-Aspirator Convergence:Integrated visualization-aspiration platforms reduce operative time and instrument exchange frequency. Manufacturers with rigid endoscopy competencies capture bundled procurement contracts.
- Japan PMDA Streamlining:METI-coordinated premarket approval process revisions target cycle time reduction for Class II surgical devices. Early entrants gain first-mover positioning in aging-demography-driven neurosurgical demand expansion.
Industry Challenges
- Electromagnetic Interference Certification:IEC 60601-1-2 electromagnetic compatibility testing for operating room equipment requires specialized compliance engineering. Timeline compression for EU MDR transition strains regulatory affairs capacity.
- Legacy Hospital IT Integration:Fixed ultrasonic aspirator connectivity with proprietary surgical documentation systems demands custom interface development. Fragmented electronic health record architectures obstruct standardized data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Aspirator Market |
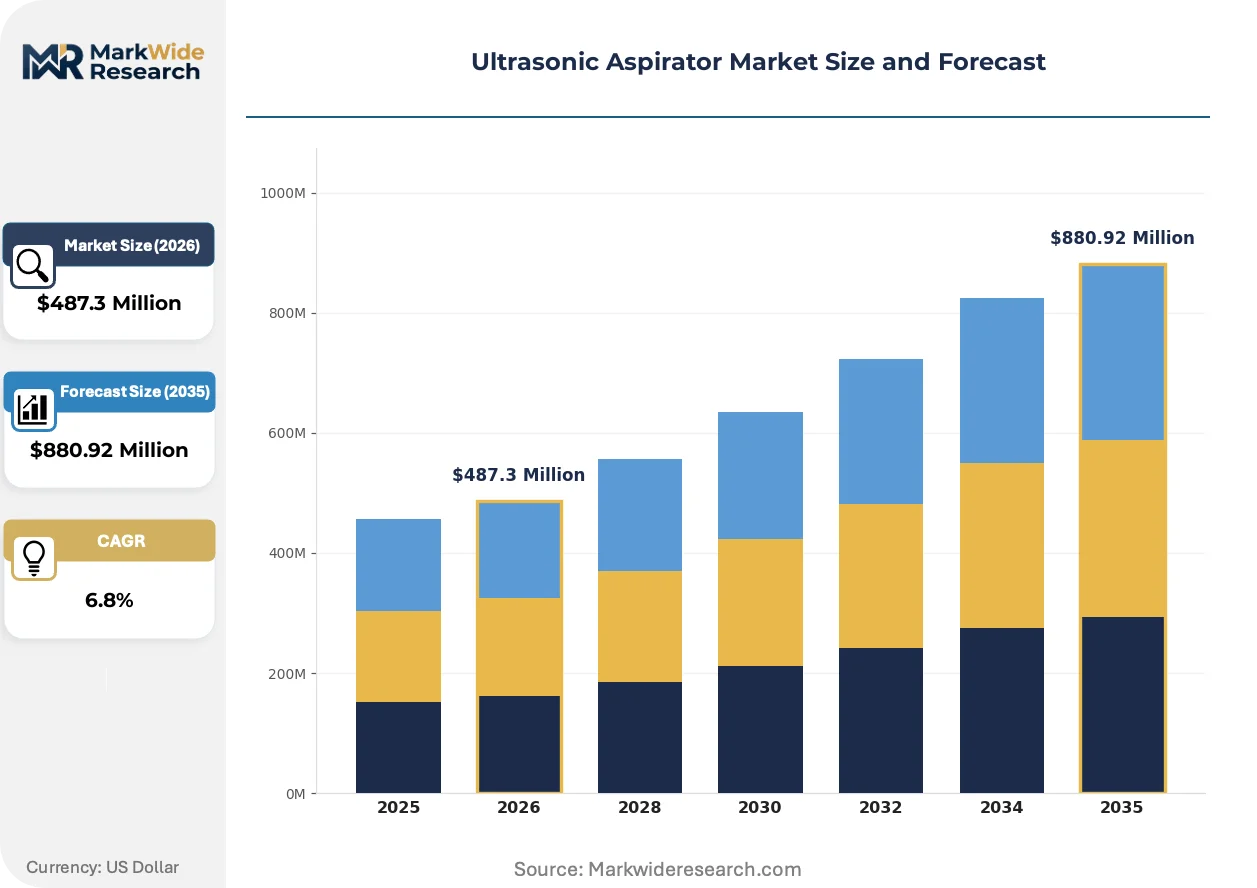
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Fixed Units, Handheld Devices, Surgical Aspirators End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Application: Maxillofacial Surgery, Gynecological Procedures, Otolaryngology, Neurosurgery Technology: Piezoceramic, Piezoelectric, Electromagnetic, Ultrasonication |
| Companies Covered | Bioventus LLC, B.Braun SE, Stryker Corp., Richard Wolf GmbH, KARL STORZ SE and Co. KG, Integra LifeSciences Corp., Medtronic Plc, Soering GmbH, Olympus Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Aspirator Market Emerging Trajectories
Digital integration and regulatory harmonization are compressing product development cycles while reshaping how surgical teams interact with aspiration platforms. Three forces merit particular attention.
Sensor-embedded ultrasonic aspirator handpieces are digitizing intraoperative tissue characterization through real-time impedance feedback and automated power modulation. Tertiary hospital neurosurgical departments are piloting these systems to reduce operator-dependent variability in soft tissue removal. The technology is digitizing surgical training protocols by enabling haptic feedback capture and procedural replay for resident education.
EU MDR Article 10 technical documentation requirements are extending clinical evidence obligations for Class IIa surgical devices. Manufacturers must demonstrate sustained performance across intended use conditions rather than relying on predicate equivalence alone. High-risk neurosurgical applications face the steepest compliance cost escalation as notified body capacity constraints lengthen certification timelines.
Integrated service contracts are displacing transactional equipment sales in German and US hospital procurement. Purchasing committees now evaluate total cost per procedure across device lifecycle rather than capital expenditure alone. This behavioral shift concentrates vendor selection authority in materials management departments with multi-year contract negotiation mandates.
Ultrasonic Aspirator Market Segmentation
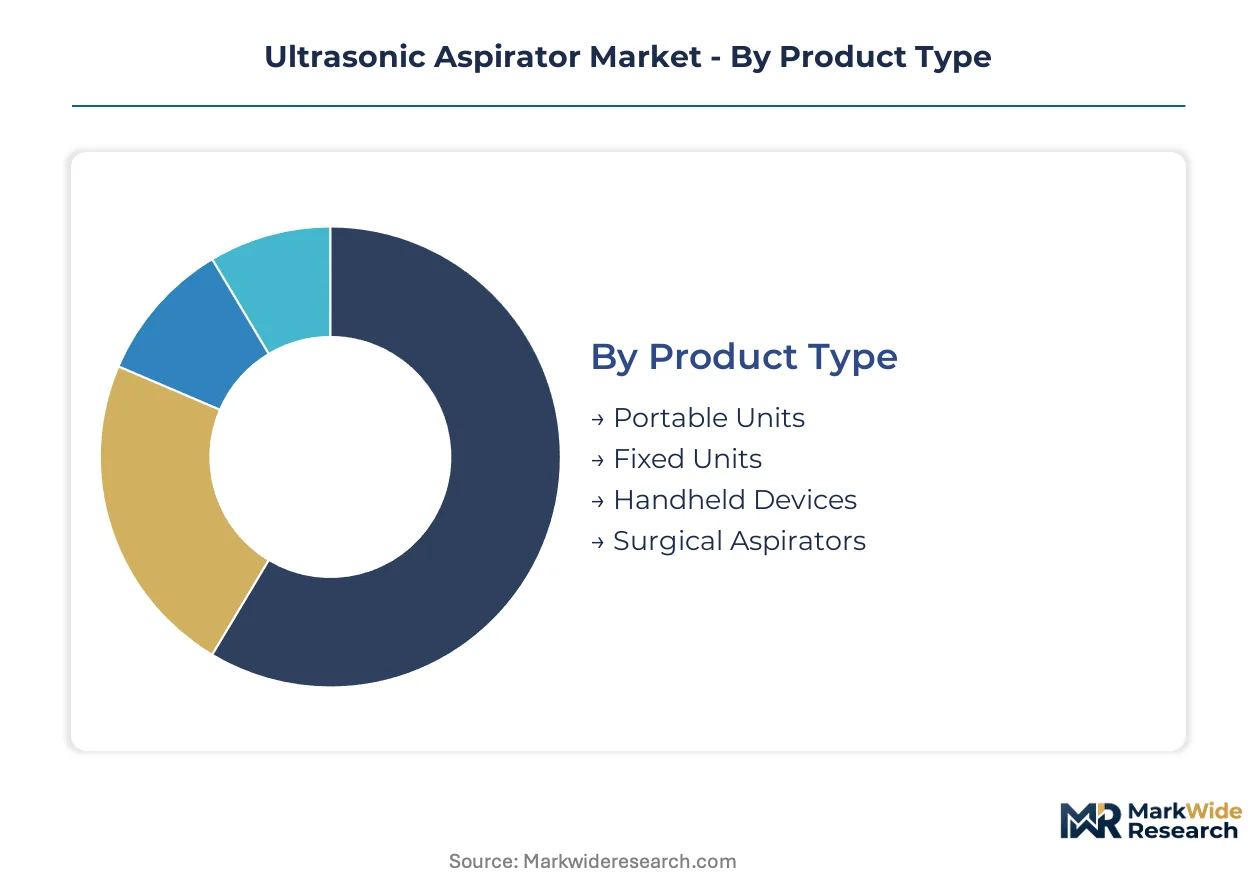
Ultrasonic aspirator segmentation reveals how clinical setting, surgical specialty, and energy delivery technology partition demand. Procurement committees evaluate capital intensity against procedure volume when matching product configurations to service line economics.
Product Type:
Capital deployment intensity and mobility requirements differentiate how surgical facilities acquire aspiration platforms across site-of-care tiers.
- Fixed Units:Permanent operating room installations integrate with surgical boom systems and centralized suction infrastructure. Tertiary hospital neurosurgical suites in Germany's Tuttlingen manufacturing corridor specify these for high-volume craniotomy workflows.
- Portable Units:Compact chassis designs with battery backup enable intra-hospital transport and freestanding surgical center deployment. Ambulatory surgical centers in the United States are expanding otolaryngology service lines using these configurations to avoid fixed infrastructure costs.
- Handheld Devices:Pistol-grip ergonomics target microsurgical applications requiring single-operator control.
- Surgical Aspirators:General-purpose suction systems without ultrasonic fragmentation capability serve basic tissue evacuation needs.
Fixed units hold installed capacity. Portable units are rotating up the share rankings.
End User:
Reimbursement pathway complexity and capital budget scale shape purchasing authority across institutional customer types.
- Hospitals:Integrated delivery networks negotiate multi-year service contracts covering ultrasonic aspirator fleets across surgical departments. Medicare reimbursement rate differentials between inpatient and outpatient settings influence whether hospitals centralize or distribute equipment.
- Ambulatory Surgical Centers:Freestanding facilities prioritize lease-based acquisition models to preserve liquidity for facility expansion. Site-of-care shift acceleration in the United States is compressing replacement cycles as these centers build neurosurgical capabilities.
- Specialty Clinics:Focused otolaryngology and plastic surgery practices favor single-procedure-room configurations.
- Research Laboratories:Academic medical centers acquire units for translational studies and resident training protocols.
Hospitals retain procurement volume leadership. Ambulatory surgical centers are climbing the fastest.
Application:
Surgical precision requirements and tissue density characteristics determine frequency stability and power modulation specifications.
- Neurosurgery:Brain and spinal cord procedures demand 23-36 kHz frequency control with real-time impedance feedback to minimize thermal injury to eloquent cortex. Tertiary hospital upgrades in Japan's aging-demography markets concentrate demand for sensor-integrated handpieces.
- Otolaryngology:Sinonasal and laryngeal applications balance fragmentation efficiency with mucosal preservation. Ambulatory surgical centers in the United States are migrating functional endoscopic sinus surgery to outpatient settings.
- Maxillofacial Surgery:Bone-cutting applications require higher amplitude settings than soft tissue work.
- Gynecological Procedures:Hysteroscopic and laparoscopic applications compete with electrosurgical alternatives.
Neurosurgery anchors technology premium. Otolaryngology is gaining share fastest.
Technology:
Transducer materials and energy conversion efficiency separate performance tiers in tissue fragmentation applications.
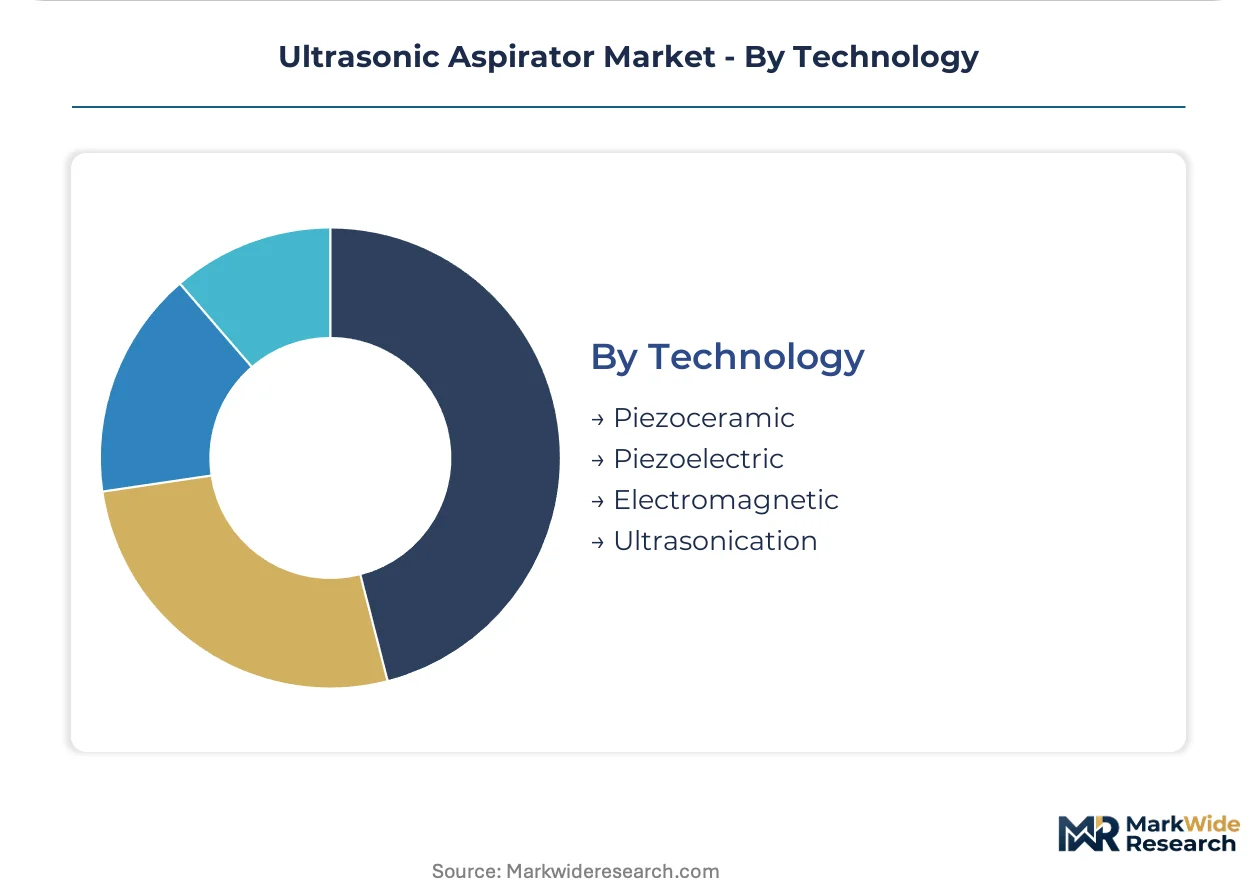
- Piezoelectric:Lead zirconate titanate crystals deliver superior frequency stability and energy efficiency at neurosurgical operating ranges. Supply concentration among East Asian specialty chemical producers creates input cost volatility for transducer manufacturers.
- Piezoceramic:Sintered ceramic formulations offer cost advantages in high-volume manufacturing but exhibit greater thermal drift under sustained load.
- Electromagnetic:Inductive coupling systems sacrifice precision for durability in general surgical environments.
- Ultrasonication:Bath-based non-contact applications serve laboratory and industrial processing rather than clinical surgery.
Piezoelectric holds technology leadership. Piezoceramic is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's precision manufacturing corridor exhibit the lowest price elasticity, while procurement committees in India's government hospital sector drive hard on total cost of ownership metrics. Japan's aging-demography hospitals prioritize sensor-integrated platforms regardless of premium positioning. The United States sits between these extremes, with Medicare reimbursement differentials shaping capital deployment timing.
United States
Ambulatory surgical centers are building neurosurgical service lines using portable configurations to avoid fixed infrastructure costs. The FDA's Class II 510(k) clearance pathway shapes product development timelines for manufacturers targeting outpatient procedure migration. Hospital procurement in the Midwest and Southeast concentrates purchasing authority in integrated delivery networks with multi-year service contract mandates.
Germany
Tertiary hospital operating suite upgrades in the Tuttlingen precision instrument manufacturing corridor sustain demand for fixed-unit installations with surgical boom integration. The EU MDR harmonization of biocompatibility standards streamlines CE marking retention for manufacturers headquartered in Baden-Württemberg. Academic medical centers in Bavaria pilot sensor-embedded handpieces for resident training protocol digitization.
Japan
Neurosurgical demand expansion driven by aging demographics concentrates in Tokyo and Osaka metropolitan hospital districts. METI-coordinated PMDA premarket approval processes extend development cycles but ensure clinical validation rigor for Class II surgical devices. Kansai-region manufacturers supply piezoelectric transducer components to domestic and export markets.
India
Government hospital modernization programs under the Ayushman Bharat scheme create import substitution openings for ultrasonic aspirator procurement. The medical device PLI scheme incentivizes domestic manufacturing partnerships with foreign precision instrument clusters. Maharashtra and Karnataka state health authorities evaluate lease-based acquisition models to preserve liquidity for facility expansion.
China
Provincial hospital tier-upgrading initiatives in the Yangtze River Delta and Pearl River Delta drive fixed-unit demand for neurosurgical departments. NMPA Class II medical device registration requirements impose biocompatibility testing burdens that extend market entry timelines for foreign manufacturers. Shanghai-based distributors serve as gatekeepers for tertiary hospital procurement committees.
Ultrasonic Aspirator Market Vendor Landscape
Integrated service contract providers and precision instrument specialists split the market along capital-deployment versus recurring-revenue business models. The vendor base concentrates among surgical equipment conglomerates with endoscopy portfolios and German mid-cap manufacturers with regional manufacturing footprints. Three archetypes dominate: diversified surgical technology platforms, rigid endoscopy bundling specialists, and piezoelectric component-integrated device makers. Competitive moves center on multi-year hospital service contract capture and endoscope-aspirator platform convergence.
Within the diversified surgical technology tier, Stryker Corp. and Medtronic Plc occupy positions anchored by integrated hospital service contract infrastructures. Olympus Corp. exemplifies the rigid endoscopy bundling archetype through visualization-aspiration platform integration. Richard Wolf GmbH and KARL STORZ SE and Co. KG represent German precision instrument specialists with manufacturing presence in the Tuttlingen corridor. These named entities serve as structural anchors for understanding how procurement committee evaluation criteria favor vendors with multi-product portfolios and regional service density.
| Leading Market Players |
|---|
| Bioventus LLC |
| B.Braun SE |
| Stryker Corp. |
| Richard Wolf GmbH |
| KARL STORZ SE and Co. KG |
| Integra LifeSciences Corp. |
| Medtronic Plc |
| Soering GmbH |
| Olympus Corp. |
| Others |
Supply Flow & Price Mechanics
East Asian specialty chemical suppliers of high-purity lead zirconate titanate concentrate pricing power in piezoelectric transducer manufacturing, anchoring margin pools in aftermarket service contracts rather than capital equipment sales. Stryker Corp. and Olympus Corp. capture recurring revenue streams through multi-year hospital service agreements that offset transactional pricing pressure on fixed-unit installations.
Pricing Analysis
Aftermarket service contracts and replacement handpiece sales drive lifetime value in ultrasonic aspirator economics. Three-tier pricing structure across premium sensor-integrated platforms, standard fixed installations, and economy portable configurations segments buyers by procedure volume and IT integration requirements. Pricing pressure stems from CO2 laser substitution in otolaryngology applications where thermal precision requirements are less stringent. Ambulatory surgical centers exhibit highest price sensitivity, while German tertiary hospitals in the Tuttlingen corridor show lowest elasticity for premium configurations with surgical boom integration.
Supply Chain Analysis
High-purity lead zirconate titanate feedstock draws from Japanese and Chinese specialty chemical producers, with sintered piezoceramic components sourced from South Korean and German precision ceramics manufacturers. Critical dependencies include electromagnetic compatibility testing facilities, surgical-grade titanium for handpiece housings, and proprietary impedance sensor microelectronics. Single-source vulnerability concentrates in East Asian piezoelectric ceramic supply, exposing transducer manufacturers to input cost volatility. Distribution runs through authorized surgical equipment distributors with field service engineering capabilities, hospital GPO contracts, and direct procurement relationships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of regulatory affairs capacity for EU MDR Article 10 compliance and electromagnetic interference certification engineering concentrates competitive advantage among incumbent manufacturers with dedicated compliance infrastructure. The market rewards vendors who internalize these capability gaps rather than outsource them.
For Market Incumbents: Entrench multi-year service contract coverage across hospital fleets before portable unit replacement cycles accelerate in ambulatory surgical centers. Deepen backward integration into piezoelectric transducer manufacturing to offset East Asian ceramic supply volatility. Prioritize electromagnetic compatibility testing infrastructure expansion as EU MDR transition strains notified body capacity and extends rival certification timelines. For New Entrants and Emerging Players: Build out India-focused manufacturing partnerships under the medical device PLI scheme to capture government hospital modernization procurement. Target Maharashtra and Karnataka state health authorities with lease-based acquisition models that preserve buyer liquidity. Penetrate through domestic assembly joint ventures with Tuttlingen precision instrument clusters rather than direct import competition. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap German precision instrument specialists with established CE marking portfolios and regional service density in Central European rigid endoscopy hubs. Long-term viability hinges on endoscope-aspirator convergence capabilities and software companion development for surgical training digitization. Watch for METI-coordinated PMDA streamlining announcements as inflection indicators for accelerated Japan market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Article 10 technical documentation requirements extend clinical evidence obligations for Class IIa surgical devices beyond predicate equivalence. |
| Hospital System Partnership | Integrated delivery network multi-year service contracts displace transactional sales and concentrate vendor selection authority. |
| Software Companion Development | Haptic feedback capture and procedural replay capabilities digitize resident training protocols in academic medical centers. |
| Backward Integration Strategy | In-house piezoelectric transducer production insulates margin pools from lead zirconate titanate supply concentration in East Asia. |
| Reimbursement Strategy | Medicare outpatient procedure pathway evolution accelerates capital deployment timing for ambulatory surgical center expansion. |
Methodological Framework
Operator-level perspectives from neurosurgeons, otolaryngologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, Medicare reimbursement pathway filings, and hospital procurement contract records. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type, application specialty, technology tier, and end-user facility configuration dimensions. CAGRs derived from segmented growth rate synthesis and cross-referenced against macro surgical procedure migration trends. Forecast inputs incorporated site-of-care shift velocity, EU MDR transition timeline compression, and piezoelectric ceramic supply elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified surgical technology platforms or rigid endoscopy bundling specialists would shift outcomes. Material shifts in PMDA premarket approval streamlining, Medicare outpatient neurosurgical reimbursement rates, or lead zirconate titanate supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Neuroprosthetics Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Global Medical Dynamometer Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Treatment Pumps Market
Medical Devices
Medical Device Tester Market
Medical Devices
Transport Chairs Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Artificial Pancreas Market