
 Brain-On-Chip Model Market | 2026-2036
Brain-On-Chip Model Market Size, Share, and Industry Trends Forecast 2026-2036
Brain-On-Chip Model Market Insights
Modular assay platform bundling is expanding as pharmaceutical buyers demand configurable systems that combine microfluidic devices with integrated electrophysiology readouts. Emulate leverages its vertical integration across chip design and organ-specific cell sourcing to anchor premium positioning. CN Bio Innovations sustains technology leadership through specialized liver-brain axis models. Mimetas competes via its OrganoPlate platform, which controls perfusion geometry without pumps.
Brain-on-chip models integrate living neuronal cultures with engineered microenvironments, typically featuring channel dimensions of 10–100 micrometers and continuous perfusion rates of 1–10 microliters per minute to mimic blood-brain barrier dynamics and neural circuit electrophysiology. These systems serve primarily to reduce animal testing while improving predictive validity in neurological drug development. Microfluidic devices occupy the largest revenue pool among product types due to their foundational role in every workflow, while 3D tissue models represent the fastest-expanding category as spheroid and organoid integration protocols mature. Drug discovery applications dominate current deployment, though toxicology testing is gaining share as EPA and EMA guidance evolves.
The FDA's Modernization Act 2.0 authorizes alternatives to animal testing, directly stimulating validation investments in brain-on-chip platforms for IND submissions. EMA's qualification opinion pathway and EPA's New Approach Methodologies framework further shape product standards and market access requirements across jurisdictions. Stakeholders must monitor regulatory acceptance criteria for specific neurological indications to time capital deployment and partnership strategies effectively.
Market Dynamics
Microfluidic perfusion engineering is compressing assay turnaround times from weeks to days, forcing incumbent platform providers to rearchitect their fluidic control layers or cede high-throughput screening contracts to modular competitors.
Growth Catalysts
- FDA Modernization Act 2.0:This US legislation authorizes non-animal alternatives for IND submissions, directly validating brain-on-chip data packages and accelerating pharmaceutical qualification timelines.
- Electrophysiology integration:Multi-electrode array embedding into microfluidic channels enables real-time neural circuit monitoring, expanding addressable applications beyond static toxicity readouts.
- German regulatory clustering:The country's maturing organ-on-chip qualification pathway through BfArM and Fraunhofer consortiums is concentrating European validation investment in Baden-Württemberg and Munich research corridors.
Market Restraints
- Primary cell sourcing volatility:Human iPSC-derived neuronal precursor costs fluctuate with donor tissue availability, compressing gross margins for platform operators lacking captive bioreactor capacity.
- PDMS material lock-in:Polydimethylsiloxane remains the dominant substrate despite its hydrophobic analyte absorption, trapping manufacturers in process chemistry they cannot easily displace without full protocol revalidation.
- EMA qualification timeline uncertainty:The agency's case-by-case opinion pathway for novel methodologies creates forecasting risk for sponsors planning multi-year IND strategies.
Strategic Opportunities
- Japan's PMDA innovation review:The regulator's Sakigake designation system offers accelerated assessment for brain-on-chip platforms demonstrating superior blood-brain barrier permeability prediction, opening premium pricing headroom for first movers.
- 3D organoid-vascular co-culture:Converging spheroid self-assembly protocols with endothelialized microchannels addresses the neurovascular unit gap in current models, unlocking stroke and neuroinflammation applications.
- Cloud-based assay marketplaces:Digital platforms connecting biopharma sponsors with distributed brain-on-chip testing capacity are emerging as alternatives to capital-intensive in-house laboratory buildouts.
Industry Challenges
- Microfluidic engineering talent scarcity:The intersection of cell biology and precision manufacturing expertise remains concentrated in Boston, Basel, and Singapore, constraining platform scale-up outside these clusters.
- ISO 10993 biocompatibility certification:Extended timelines for material safety validation delay product launches, particularly for novel thermoplastic substrates displacing legacy PDMS.
- Cross-platform data harmonization:Absence of standardized neural activity reporting formats complicates multi-site studies and regulatory submission packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain-On-Chip Model Market |
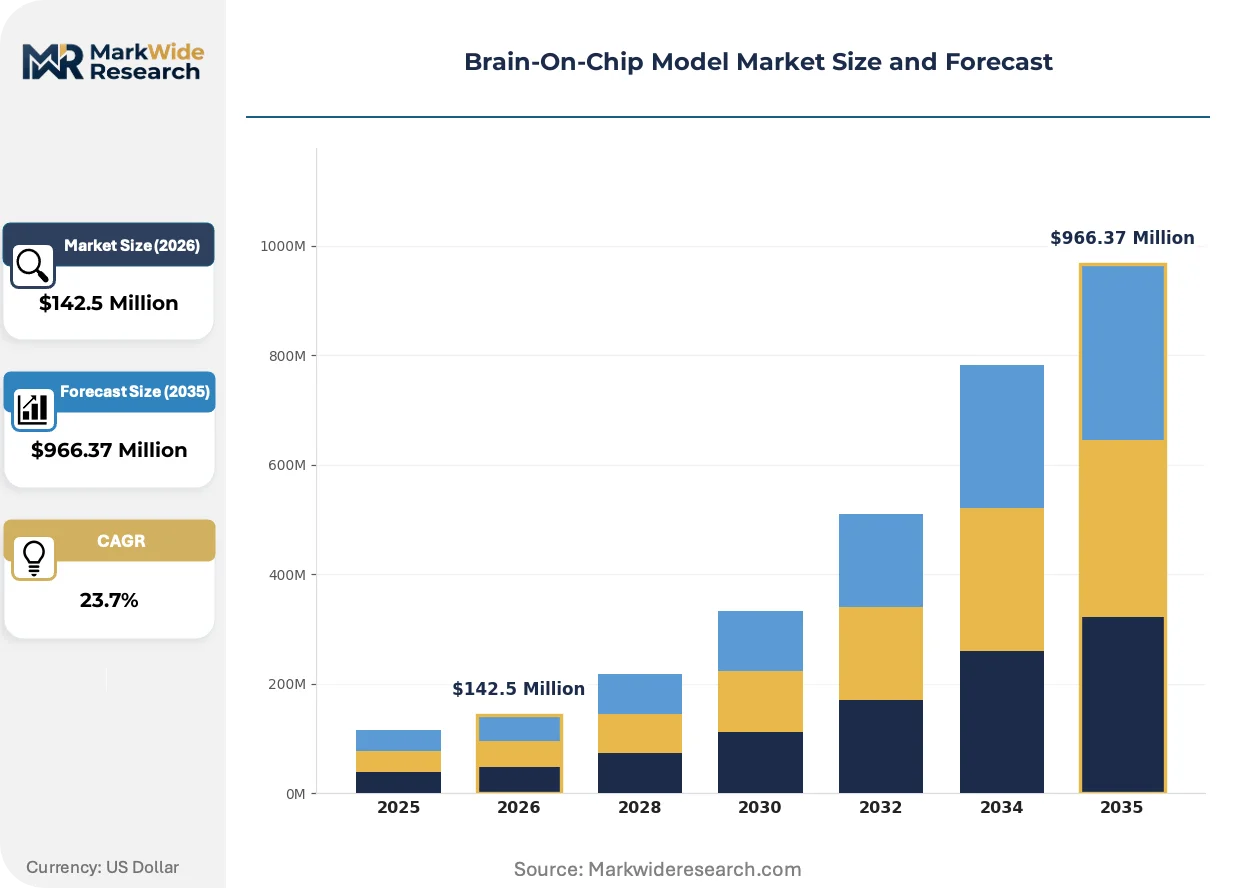
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $966.37 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Devices, Neuronal Cultures, 3D Tissue Models, Assay Platforms Application: Drug Discovery, Neurological Research, Toxicology Testing, Disease Modeling Technology: Biofabrication, Electrophysiology, Imaging Systems, Bioinformatics End User: Research Institutions, Biotechnology Firms, Pharmaceutical Companies, Academic Laboratories |
| Companies Covered | Emulate, CN Bio Innovations, Mimetas, Tissuse, Nortis, Hesperos, Kirkstall, Cherry Biotech, AxoSim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain-On-Chip Model Market Trends and Innovations
Bioprinting resolution advances and organoid maturation protocols are converging to produce self-assembling neural tissues that replicate layered cortical architecture, shifting competitive advantage toward vendors controlling both fabrication and cell sourcing capabilities.
Organ-on-chip platforms are integrating machine learning-driven image analysis pipelines that classify neuronal morphologies and network firing patterns without manual electrophysiology intervention. Contract research organizations in the United States and Germany are adopting these automated readouts to compress study timelines. This capability compression is integrating high-content screening workflows into standard toxicology service menus, blurring the historical boundary between discovery and safety assessment.
REACH regulatory pressure on animal testing alternatives is compelling European pharmaceutical sponsors to pre-validate brain-on-chip submissions through ECHA's New Approach Methodologies dialogue. The industrial consequence is a surge in joint qualification studies between platform vendors and major sponsors. Blood-brain barrier permeability assays are most affected, with sponsors in Switzerland and the Netherlands leading protocol standardization initiatives.
Pharmaceutical procurement functions are unbundling integrated brain-on-chip service contracts into discrete cell sourcing, device fabrication, and analytical readout components. This disaggregation favors specialized vendors with ISO 13485 device manufacturing certification over full-stack platform providers. The pattern is most visible in Massachusetts and North Carolina, where biotech sponsors are building multi-vendor qualified supplier panels rather than single-source dependencies.
Brain-On-Chip Model Market Segmentation
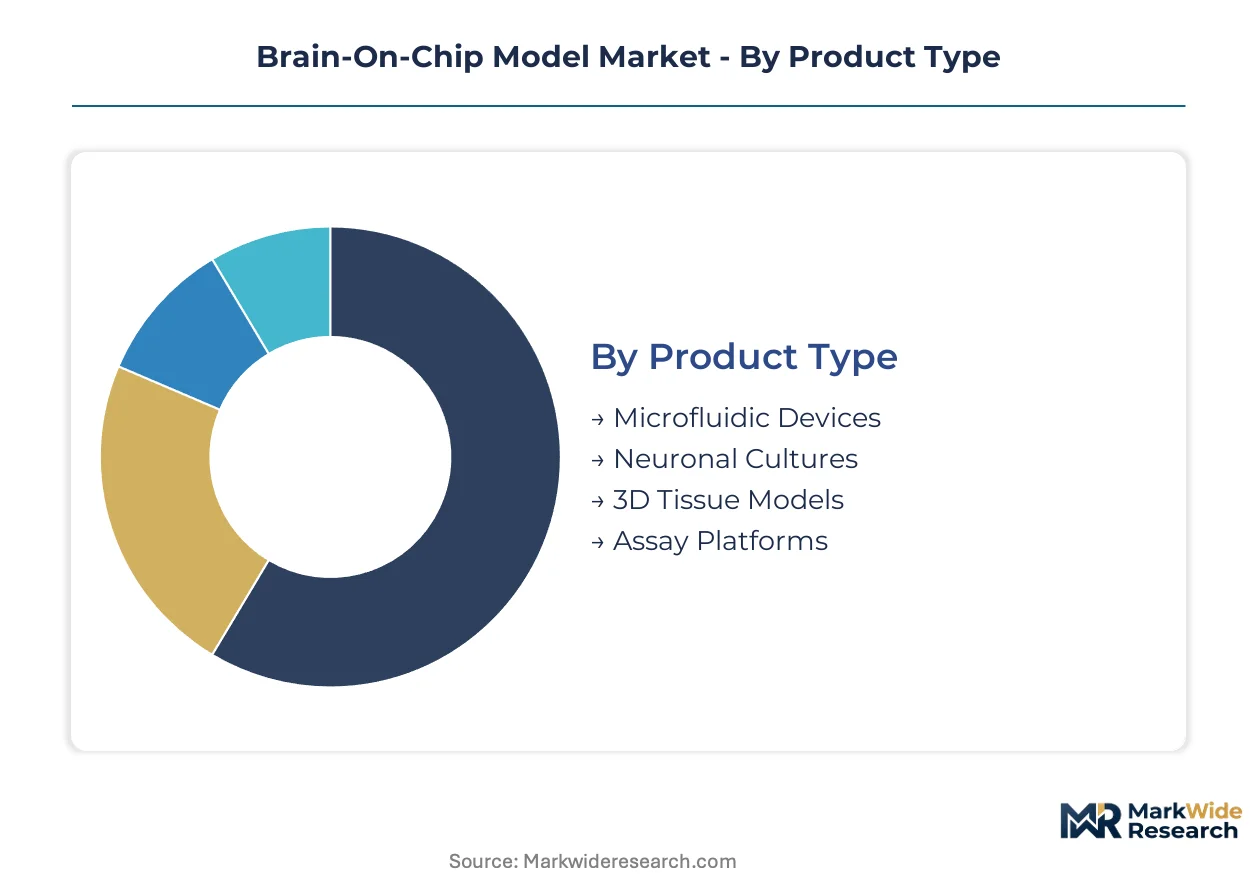
Segmentation in the brain-on-chip model market reveals how technical capabilities, user requirements, and regulatory pathways fragment procurement patterns. Buyers prioritize different performance attributes depending on whether they seek high-throughput screening, mechanistic research, or regulatory submission packages.
Product Type:
Supply concentration in fabrication expertise shapes competitive dynamics across hardware categories, with microfluidic engineering talent clustering in specific research corridors.
- Microfluidic Devices:These systems feature channel dimensions of 10–100 micrometers with continuous perfusion rates of 1–10 microliters per minute. Pharmaceutical companies in the United States and Germany anchor procurement volumes as they rebuild screening infrastructure around organ-on-chip workflows. The FDA Modernization Act 2.0 accelerates validation investments specifically for these platforms.
- 3D Tissue Models:Self-assembling neural tissues replicate layered cortical architecture through converging bioprinting and organoid maturation protocols. Demand concentrates among biotechnology sponsors seeking blood-brain barrier permeability assays for neurodegenerative drug programs.
- Neuronal Cultures:Human iPSC-derived neuronal precursors face sourcing volatility tied to donor tissue availability.
- Assay Platforms:Modular systems bundling microfluidic devices with integrated electrophysiology readouts serve configurable screening workflows.
Today's leader: Microfluidic Devices. Tomorrow's challenger: 3D Tissue Models.
Application:
Cost tier differentiation separates high-volume screening contracts from premium mechanistic studies, with pricing stratifying across throughput scale and data depth.
- Drug Discovery:High-throughput screening of compound libraries against neural circuit models dominates current deployment volumes. Pharmaceutical sponsors in Massachusetts and North Carolina are unbundling service contracts into discrete components to build multi-vendor qualified supplier panels.
- Toxicology Testing:Real-time neural activity monitoring for safety assessment is gaining share as EPA and EMA guidance on New Approach Methodologies matures. REACH regulatory pressure compels European sponsors to pre-validate submissions through ECHA dialogue.
- Neurological Research:Mechanistic studies of synaptic plasticity and network formation serve academic laboratories.
- Disease Modeling:Patient-derived iPSC models replicate specific pathologies for precision medicine applications.
Drug Discovery commands the largest revenue pool. Toxicology Testing shows the steepest expansion trajectory as regulatory pathways formalize.
Technology:
Volume concentration in automated readout capabilities is compressing study timelines and integrating high-content screening into standard service menus.
- Electrophysiology:Multi-electrode array embedding enables real-time neural circuit monitoring beyond static toxicity readouts. Contract research organizations in Germany and the United States adopt these automated pipelines to classify neuronal morphologies without manual intervention.
- Imaging Systems:Machine learning-driven analysis classifies network firing patterns, blurring boundaries between discovery and safety assessment workflows.
- Biofabrication:Resolution advances in 3D bioprinting produce self-assembling tissues with architectural fidelity.
- Bioinformatics:Cloud-based platforms connect sponsors with distributed testing capacity as alternatives to capital-intensive laboratory buildouts.
Electrophysiology anchors premium positioning. Bioinformatics represents the emerging capability layer.
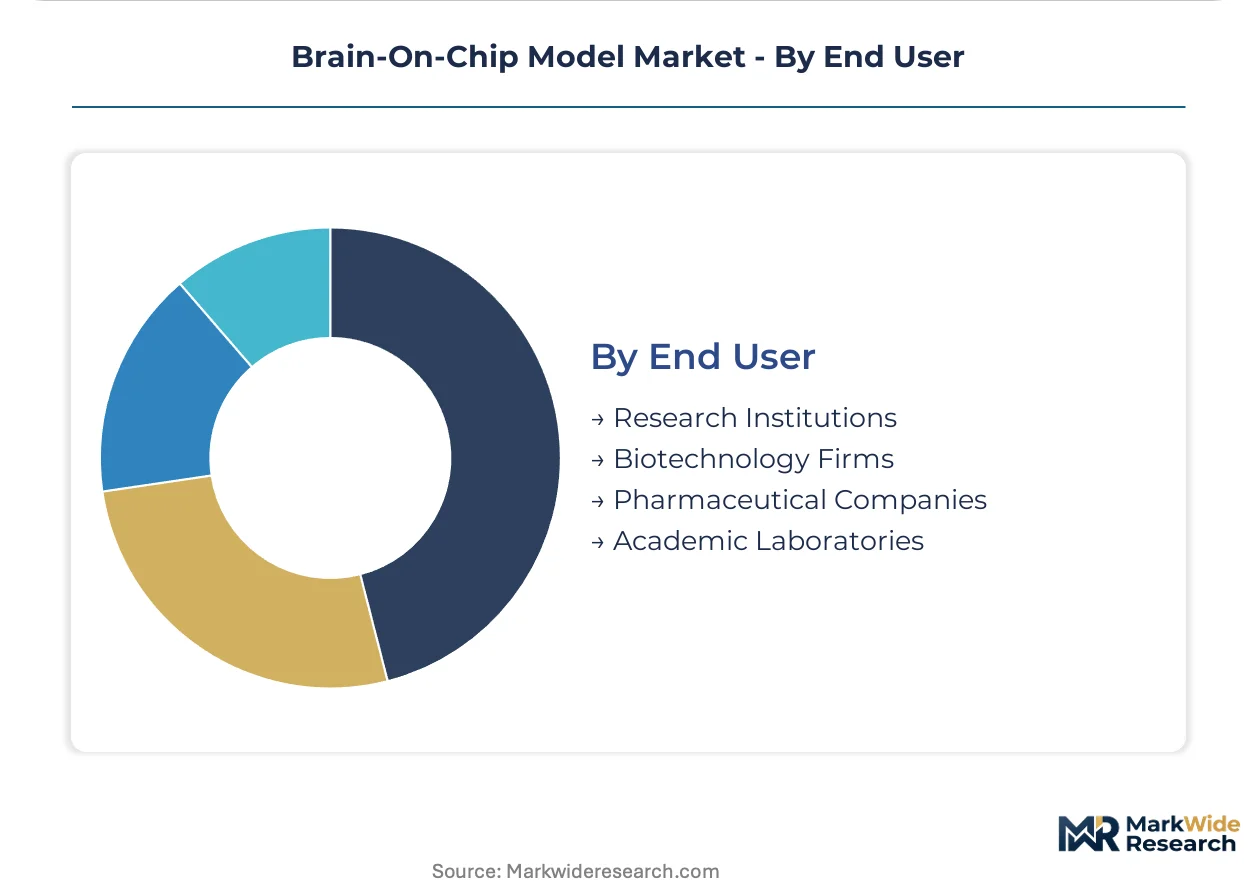
End User:
Customer type determines procurement sophistication, with pharmaceutical buyers demanding ISO 13485 certification while academic laboratories prioritize protocol flexibility.
- Pharmaceutical Companies:These sponsors drive qualification timelines for IND submissions, requiring vendors to demonstrate regulatory acceptance across FDA, EMA, and PMDA jurisdictions. Procurement functions favor specialized vendors with device manufacturing certification over full-stack providers.
- Biotechnology Firms:Mid-cap developers concentrate European validation investment in Baden-Württemberg and Munich research corridors through Fraunhofer consortium partnerships.
- Research Institutions:National laboratories and institutes advance protocol standardization for blood-brain barrier assays.
- Academic Laboratories:University groups pioneer organoid-vascular co-culture methods for neurovascular unit modeling.
Pharmaceutical Companies dominate contract value. Biotechnology Firms are expanding fastest as pipeline maturation accelerates platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brain-on-chip technology originated in United States academic laboratories during the early microfluidics revolution, then commercialized through Massachusetts and California research corridors before expanding to European precision manufacturing centers and Japanese regulatory innovation hubs.
United States
FDA Modernization Act 2.0 validates non-animal IND submissions, accelerating pharmaceutical qualification timelines for platform vendors. EPA New Approach Methodologies framework shapes toxicology testing standards for neurological drug candidates. Massachusetts and North Carolina biotech clusters drive procurement of modular assay systems with ISO 13485 certification requirements.
Germany
Fraunhofer consortium partnerships concentrate European validation investment in organ-on-chip qualification pathways. BfArM maturing regulatory dialogue reduces forecasting uncertainty for sponsors planning multi-year IND strategies. Baden-Württemberg and Munich research corridors anchor mid-cap biotechnology firm adoption through specialized liver-brain axis model development.
Japan
PMDA Sakigake designation system offers accelerated assessment for platforms demonstrating superior blood-brain barrier permeability prediction. METI innovation review programs channel public research funding toward neurovascular unit modeling capabilities. Tokyo and Osaka metropolitan areas concentrate electrophysiology integration expertise for real-time neural circuit monitoring applications.
United Kingdom
UK Research and Innovation funding streams support academic organoid-vascular co-culture protocol development. MHRA alignment with EMA qualification opinions facilitates cross-border regulatory submission strategies. Cambridge and Oxford research triangles pioneer 3D tissue model standardization for precision medicine applications.
Switzerland
Swissmedic early dialogue programs attract sponsors seeking regulatory clarity for novel methodology submissions. Federal innovation grants sustain bioprinting resolution advances in self-assembling neural tissue fabrication. Basel pharmaceutical corridor drives demand for configurable screening workflows combining microfluidic devices with integrated readouts.
Brain-On-Chip Model Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory qualification depth and captive cell sourcing capabilities. The vendor base stratifies into three tiers: full-stack platform providers with vertical integration, specialized device fabricators with ISO 13485 certification, and modular service vendors unbundling assay components. Dominant competitive moves include strategic partnerships for joint qualification studies and geographic expansion through distributed cloud-based assay marketplaces.
Within the full-stack platform tier, Emulate exemplifies premium positioning through chip design and organ-specific cell sourcing integration. Among specialized device fabricators, CN Bio Innovations occupies a position representing technology leadership in liver-brain axis models, while Mimetas anchors the perfusion geometry control segment through its OrganoPlate platform. These three companies represent the strategic archetypes reshaping procurement patterns as pharmaceutical buyers build multi-vendor qualified supplier panels.
| Leading Market Players |
|---|
| Emulate |
| CN Bio Innovations |
| Mimetas |
| Tissuse |
| Nortis |
| Hesperos |
| Kirkstall |
| Cherry Biotech |
| AxoSim |
| Others |
Pricing and Supply Chain Analysis
Microfluidic engineering talent clustering in Boston, Basel, and Singapore establishes labor-cost differentials that widen pricing-tier spreads between premium integrated platforms and modular component suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-stack platform providers with captive cell sourcing from ISO 13485-certified device fabricators and unbundled service vendors. Price differentiation hinges on regulatory qualification depth and vertical integration extent, with pharmaceutical sponsors in Massachusetts and North Carolina showing lowest price sensitivity for IND-ready packages. Cost compression in the standard tier is intensifying because biotechnology firms are disaggregating service contracts into discrete supplier panels. Academic laboratories represent the most price-sensitive buyer segment, prioritizing protocol flexibility over certification grade.
Supply Chain Analysis
ISO 10993 biocompatibility certification gates material sourcing, extending timelines for thermoplastic substrates displacing legacy PDMS. Manufacturing concentrates in the United States, Germany, and Japan where precision fabrication expertise and regulatory validation infrastructure coexist. The supply chain draws from polydimethylsiloxane resin suppliers, human iPSC-derived neuronal precursor bioreactors, and multi-electrode array fabricators. Single-source vulnerability in primary cell sourcing compresses gross margins for platform operators lacking captive bioreactor capacity. Distribution runs through direct pharmaceutical procurement channels and emerging cloud-based assay marketplaces connecting sponsors with distributed testing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in brain-on-chip platforms rests on automation-driven cost compression in electrophysiology readouts and premium-tier pull from FDA Modernization Act 2.0 qualification timelines.
For Market Incumbents: Deepen backward integration into human iPSC-derived neuronal precursor bioreactors to insulate margins from donor tissue volatility. Anchor premium positioning through joint qualification studies with pharmaceutical sponsors seeking IND-ready data packages, while defending against modular competitors by embedding machine learning-driven image analysis into standard toxicology workflows. For New Entrants and Emerging Players: Begin with cloud-based assay marketplaces connecting biopharma sponsors with distributed testing capacity, bypassing capital-intensive laboratory buildouts. Japan's PMDA Sakigake designation pathway offers the most penetrable regulatory entry point for blood-brain barrier permeability platforms, with METI innovation review programs providing public research funding access. For Investors and Strategic Acquirers: Pharmaceutical contract research organizations are the most active acquirer in this space, seeking electrophysiology integration capabilities to compress study timelines. Target specialized device fabricators with ISO 13485 certification and organoid-vascular co-culture protocols, as these assets command premium multiples in a market where capability scarcity constrains scale-up. Watch for EMA qualification opinion formalization as the inflection signal for European validation investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Qualification Studies | EMA's case-by-case opinion pathway rewards vendor-sponsor collaboration on IND submission packages. |
| Electrophysiology Integration | FDA Modernization Act 2.0 validates real-time neural circuit monitoring for toxicology applications. |
| Cloud-Based Assay Marketplaces | Biopharma sponsors in Massachusetts and North Carolina adopt distributed capacity models over in-house buildouts. |
| Organoid-Vascular Co-Culture Development | Neurovascular unit modeling unlocks stroke and neuroinflammation applications for precision medicine. |
| ISO 13485 Certification Investment | Procurement functions favor certified device fabricators over full-stack providers in unbundled contracting. |
Research Methodology
Bottom-up pharmaceutical procurement modeling reconciled against top-down microfluidic device production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, platform engineers, and GPO contracts managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Cross-referencing sponsor qualification timelines against vendor certification status enables demand-side triangulation with supply-side capacity assessments.
Input-output matrices map electrophysiology integration adoption rates, 3D tissue model maturation protocols, and cloud-based assay marketplace penetration across product type, application, technology, and end-user segmentation dimensions. CAGRs derive from regression analysis of historical platform deployment and forward projection of regulatory acceptance criteria. Forecast inputs include PMDA Sakigake designation velocity, EMA qualification opinion issuance patterns, and iPSC-derived neuronal precursor cost curves.
Several conditions sit outside the modeled scope, including unforeseen material science breakthroughs displacing PDMS substrates and abrupt shifts in EPA New Approach Methodologies enforcement posture. Forecasts reflect documented assumptions about regulatory pathway maturation timelines and pharmaceutical R&D budget allocation stability. A model refresh is warranted upon material change in FDA organ-on-chip validation guidance or EMA formal methodology qualification standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
Hearing Loop Market
Medical Devices
Blood Thawing System Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Self-Injections Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Global Breast Pumps Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Global Casting Devices Market
Medical Devices
Breathing Circuits Market