
 Global Otoscopes Market | 2026-2036
Global Otoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Otoscopes Market Foresight
The otoscope category is restructuring around a sharp split between premium digital-video systems and commodity-priced conventional models. Welch Allyn leverages its established distribution in North American hospitals to sustain dominance in wired examination suites. Heine Optotechnik anchors its position through precision optics manufacturing in Germany, while Olympus Corporation competes by extending its endoscopy expertise into video otoscopy for ENT surgical workflows.
An otoscope is a handheld diagnostic instrument designed for visual examination of the external auditory canal and tympanic membrane, typically incorporating a speculum, light source, and magnification lens with focal lengths optimized for otologic inspection. The device serves primary care physicians and otolaryngologists in detecting infections, perforations, and cerumen impactions that guide treatment decisions. Digital otoscopes now command attention as health systems prioritize image capture and electronic health record integration, while portable otoscopes with rechargeable battery technology gain traction in field-based and home-care settings where mobility constrains equipment choice. Conventional otoscopes retain volume share in price-sensitive procurement channels, though margin pools have shifted decisively toward CMOS sensor-based platforms that enable telemedicine consultation.
FDA clearance pathways shape product development timelines for manufacturers targeting the United States, while the EU MDR and CE marking requirements determine access to European clinical markets. The EU AI Act introduces additional scrutiny for otoscopes incorporating automated diagnostic algorithms, potentially segmenting regulatory complexity between basic visualization tools and AI-augmented systems. Stakeholders must track how reimbursement policies for remote ENT consultation evolve, as these will determine whether connected otoscope investments convert to sustainable revenue streams or remain pilot-program expenditures.
Market Dynamics
CMOS sensor miniaturization and AI-augmented diagnostic algorithms are compressing the traditional divide between examination-grade and surgical-grade visualization systems, forcing manufacturers to recalibrate R&D roadmaps and pricing architectures simultaneously.
Growth Catalysts
- EU MDR framework:The Medical Device Regulation's stricter quality requirements for CE marking are accelerating hospital procurement cycles for certified digital otoscopy platforms across Germany, France, and Italy.
- Telemedicine infrastructure:Integrated health systems in the United States now mandate EHR-compatible image capture, pulling wired examination suites toward connected diagnostic platforms.
- Rechargeable lithium-polymer batteries:Portable otoscopes with extended field endurance are displacing conventional models in home-care and rural outreach programs.
Market Restraints
- Optical glass supply concentration:Precision lens manufacturing remains concentrated in German and Japanese optical clusters, exposing margins to raw material volatility and single-source fragility.
- EU AI Act compliance friction:Automated diagnostic algorithms embedded in video otoscopes face additional conformity assessment layers, extending time-to-market for AI-augmented systems by 12-18 months.
- Conventional otoscope substitution:Commodity-priced pneumatic and standard otoscopes retain procurement share in budget-constrained primary care networks across emerging markets.
Strategic Opportunities
- Underpenetrated Indian outpatient network:Ayushman Bharat's expansion of health and wellness centers creates procurement channels for portable, battery-operated diagnostic tools in tier-2 and tier-3 cities.
- Wearable otoscopy convergence:Integration of miniature CMOS sensors with smartphone-based telehealth platforms enables remote ENT consultation in home-care settings.
- US reimbursement tailwind:CMS evaluation of remote diagnostic service codes for otologic conditions could convert connected otoscope investments from pilot expenditures to sustainable revenue streams.
Industry Challenges
- ISO 13485 quality management certification:Smaller manufacturers face 18-24 month compliance timelines to meet medical device quality system requirements for European market access.
- Legacy EHR integration complexity:Hospital IT departments struggle with DICOM and HL7 FHIR interoperability when deploying video otoscopes into heterogeneous electronic health record environments.
- Optomechanical engineering talent scarcity:The convergence of precision optics, sensor electronics, and software diagnostics requires hybrid skill sets that remain concentrated in German and Japanese manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Otoscopes Market |
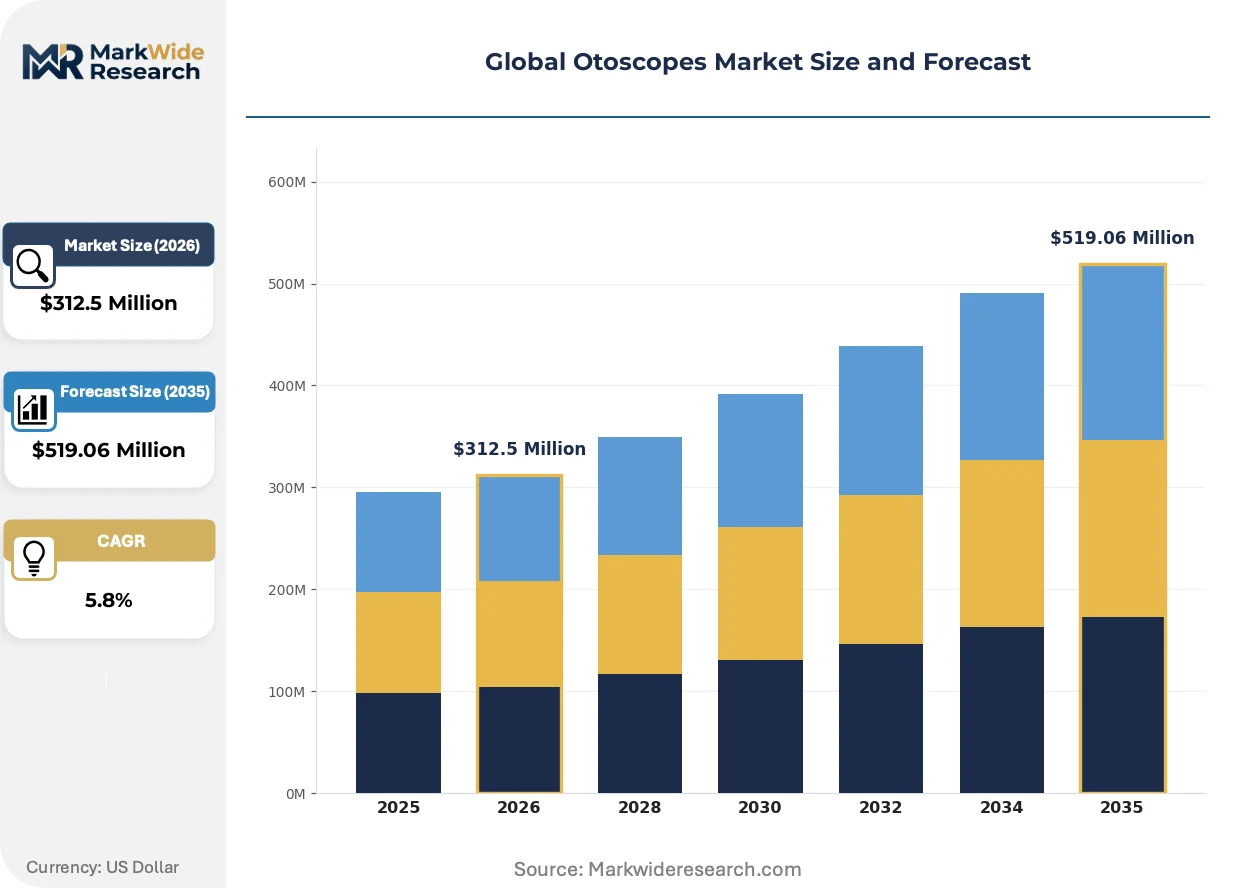
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Otoscopes, Video Otoscopes, Conventional Otoscopes, Wireless Otoscopes, Portable Otoscopes Technology: LED Illumination, Fiber Optic, CMOS Sensor, LCD Display, Rechargeable Battery Application: ENT Clinics, Audiology Centers, Telemedicine, Pediatric Care, Primary Care Facilities End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialist Clinics |
| Companies Covered | Welch Allyn, Heine Optotechnik, Olympus Corporation, 3M, American Diagnostic Corporation, Rudolf Riester, Orlvision, SyncVision Technology Corporation, Midmark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Otoscopes Market Shifts & Advancements
Three distinct vectors are restructuring competitive positioning: sensor technology is compressing device form factors, regulatory frameworks are segmenting product categories by algorithmic content, and procurement centralization is privileging platform vendors over component suppliers.
Wireless CMOS-based video otoscopes with integrated Wi-Fi transmission are decentralizing diagnostic capability from hospital ENT suites to primary care clinics and home-based settings. Rural health networks in Australia and Canada are deploying these devices for asynchronous telemedicine consultation. The structural consequence is a compression in the addressable market for conventional wired examination systems as point-of-care image capture becomes standard.
The EU AI Act's risk-classification framework for medical devices incorporating automated diagnostic algorithms is segmenting regulatory complexity between basic visualization tools and AI-augmented systems. Manufacturers must now maintain parallel conformity assessment pathways for algorithm-enabled and algorithm-free product variants. Video otoscopy platforms with embedded machine learning for tympanic membrane classification face the steepest compliance burden, with notified body backlogs extending certification timelines.
Hospital procurement departments are consolidating vendor relationships around integrated diagnostic platforms rather than standalone devices. IDNs in the United States now specify otoscopes as components of enterprise-wide telehealth infrastructure, not as discrete capital equipment. This behavioral shift privileges manufacturers with established EHR partnerships and compresses margins for component specialists lacking platform integration capabilities.
Global Otoscopes Market Segmentation
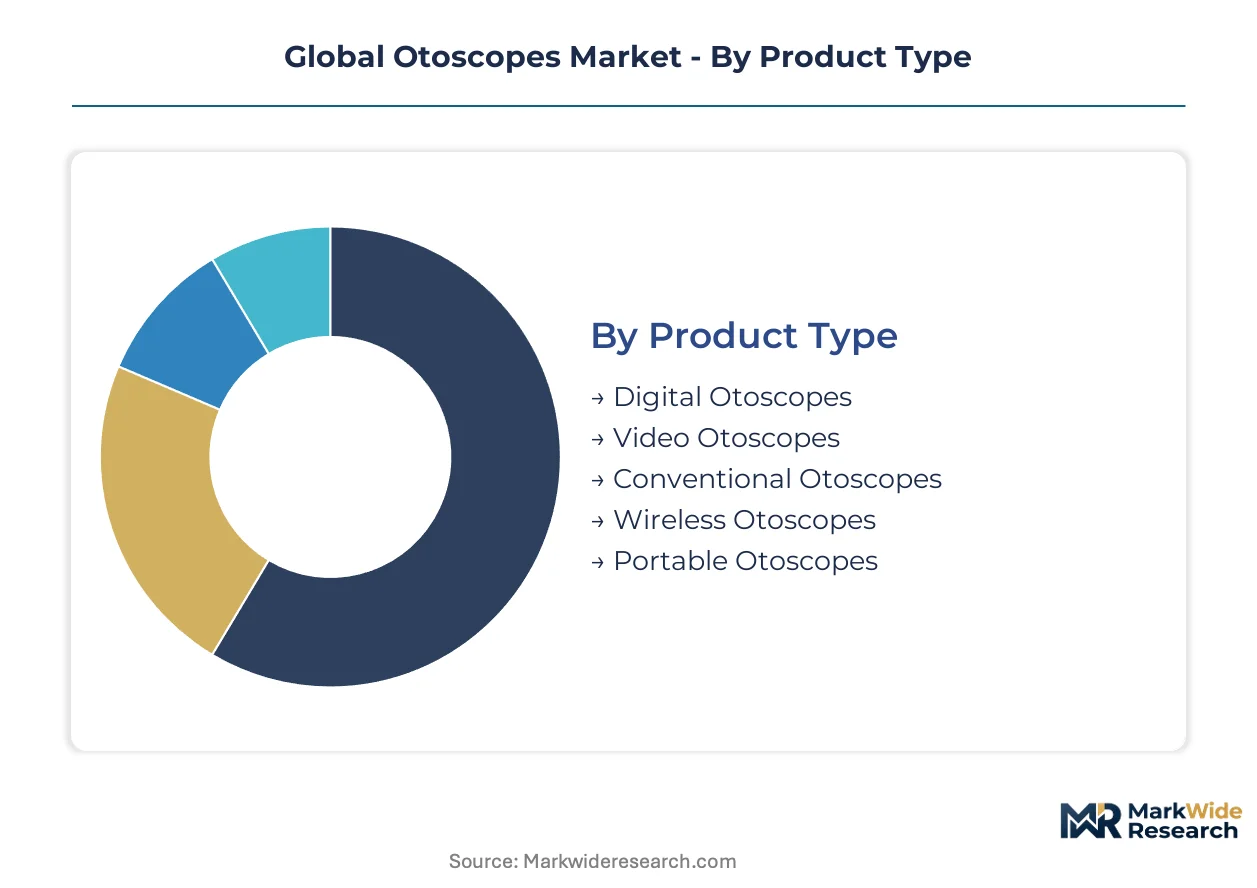
Otoscope procurement splits sharply between standalone examination tools and embedded diagnostic platforms. Health system IT integration mandates now determine which segments capture margin pools versus volume share.
Product Type:
Integration depth separates segments that function as discrete devices from those wired into enterprise telehealth infrastructure.
- Digital Otoscopes:CMOS sensor-based systems with direct EHR connectivity dominate hospital procurement in the United States. Integrated delivery networks specify these for synchronous telemedicine workflows.
- Video Otoscopes:High-definition capture modules with LCD displays serve ENT surgical suites where image documentation supports operative planning. German university hospitals drive specification intensity here.
- Conventional Otoscopes:Pneumatic and standard lens-based models retain procurement share in budget-constrained primary care networks across India and Southeast Asia.
- Wireless Otoscopes:Wi-Fi-enabled devices with smartphone pairing enable asynchronous consultation in Australian rural health networks and Canadian remote outposts.
- Portable Otoscopes:Lithium-polymer battery systems with field endurance specifications serve home-care programs and mobile health outreach in tier-2 Indian cities under Ayushman Bharat.
Conventional otoscopes lead volumes today; wireless variants are gaining share fastest.
Technology:
Cost tier stratification concentrates premium margins in sensor-electronics combinations while commoditized illumination technologies compete on unit economics.
- LED Illumination:Solid-state white-light sources with 50,000-hour lifespans have displaced halogen in mid-tier and premium device tiers across Japanese and South Korean manufacturing.
- CMOS Sensor:Miniaturized image sensors with 1080p resolution enable video otoscopy at price points approaching conventional optical systems; FDA 510(k) clearances cluster here.
- Fiber Optic:Cold-light transmission through glass bundles persists in surgical-grade instruments where heat management affects tissue safety margins.
- LCD Display:Integrated screens with adjustable viewing angles serve point-of-care settings where external monitors prove impractical.
- Rechargeable Battery:Lithium-polymer cells with USB-C charging protocols support cordless operation in German home-care and French mobile nursing deployments.
LED illumination commands the largest installed base; CMOS sensor configurations show the steepest expansion trajectory.
Application:
Customer type determines whether procurement prioritizes diagnostic throughput, pediatric accommodation, or remote consultation capability.
- ENT Clinics:Specialized otolaryngology practices in Germany and the United States specify video otoscopy with image archiving for operative documentation and medicolegal protection.
- Telemedicine:Asynchronous consultation platforms in Australia and Canada require Wi-Fi transmission and cloud storage integration for rural primary care connectivity.
- Audiology Centers:Co-located hearing assessment workflows drive demand for otoscopes with cerumen management compatibility.
- Pediatric Care:Smaller speculum diameters and ergonomic grips address anatomical constraints in neonatal and infant examinations.
- Primary Care Facilities:Volume procurement across India's health and wellness centers emphasizes battery longevity and field durability over image resolution.
ENT clinics anchor current revenue concentration; telemedicine applications are expanding most quickly.
End User:
Maturity gradients separate established hospital capital equipment cycles from emerging ambulatory and laboratory procurement channels.
- Hospitals:Integrated delivery networks in the United States consolidate otoscope procurement within enterprise telehealth platform contracts, privileging vendors with established EHR partnerships.
- Ambulatory Surgical Centers:Freestanding ENT procedure facilities in Germany and France prioritize compact video otoscopy with rapid sterilization turnaround.
- Diagnostic Laboratories:Reference lab networks with occupational health contracts specify digital capture for remote physician interpretation.
- Specialist Clinics:Independent otolaryngology and audiology practices in Japan and South Korea drive demand for precision optics with minimal maintenance requirements.
Hospitals dominate absolute unit demand; ambulatory surgical centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems prioritize EHR-integrated diagnostic platforms, while German ENT clinics drive specification intensity for precision optics. Japan's aging demographic and South Korea's telehealth infrastructure create divergent procurement patterns across developed markets.
United States
Integrated delivery networks mandate connected otoscopy platforms for enterprise telehealth contracts. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting hospital procurement cycles. The Boston-Cambridge medical technology cluster concentrates R&D activity for CMOS sensor miniaturization.
Germany
University hospitals in Bavaria and Baden-Württemberg specify video otoscopy with operative documentation capabilities. EU MDR framework tightens quality requirements for CE marking, accelerating certified digital platform adoption. The Jena-Heidelberg optical manufacturing corridor anchors precision lens production for examination-grade instruments.
Japan
Specialist otolaryngology practices in Tokyo and Osaka drive demand for maintenance-minimal precision optics. PMDA regulatory pathways determine market access timelines for sensor-enabled diagnostic devices. The Nagoya-Chubu region concentrates optomechanical engineering talent for surgical-grade visualization systems.
India
Ayushman Bharat health and wellness centers in tier-2 and tier-3 cities create procurement channels for portable battery-operated tools. CDSCO medical device regulations govern import and domestic manufacturing compliance. The Bengaluru-Hyderabad medtech corridor incubates smartphone-integrated diagnostic platform development.
Australia
Rural health networks deploy wireless otoscopes for asynchronous telemedicine consultation in remote outposts. TGA conformity assessment requirements structure product registration for video capture platforms. The Sydney-Melbourne healthcare procurement axis consolidates diagnostic equipment purchasing for regional distribution.
Global Otoscopes Market Competitive Landscape
Top-tier vendors anchor hospital IDN contracts, while mid-tier specialists occupy niche optical segments. The vendor base stratifies across three tiers: multinational platform integrators, regional precision optics manufacturers, and commodity device assemblers. Dominant competitive moves include EHR partnership consolidation and CMOS sensor supply chain capture.
Within the precision optics tier, Heine Optotechnik GmbH and Rudolf Riester GmbH represent German engineering archetypes. Welch Allyn anchors North American hospital distribution networks. Olympus Corporation exemplifies endoscopy-to-otoscopy capability extension. These three named entities occupy positions across distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Welch Allyn |
| Heine Optotechnik |
| Olympus Corporation |
| 3M |
| American Diagnostic Corporation |
| Rudolf Riester |
| Orlvision |
| SyncVision Technology Corporation |
| Midmark Corporation |
| Others |
Supply & Pricing Matrix
Optomechanical engineering talent concentration in the Jena-Heidelberg corridor feeds directly into labor-cost differentials that separate German-manufactured precision optics from Asian-assembled commodity devices, widening pricing-tier spreads across certification grades.
Pricing Analysis
Bundled telehealth platform contracts versus unbundled device procurement splits the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with FDA-cleared CMOS systems commanding substantial premiums over CE-only equivalents. Cost compression in economy tiers intensifies because Indian and Southeast Asian procurement channels prioritize unit economics over image resolution. Primary care networks across emerging markets exhibit highest price sensitivity, while United States integrated delivery networks demonstrate lowest sensitivity due to enterprise contract bundling.
Supply Chain Analysis
ISO 13485 and EU MDR certification gating restricts component sourcing to qualified optical manufacturers in Germany, Japan, and South Korea. Precision glass lens production draws from Schott AG substrates in Mainz and Hoya Corporation optical blanks in Tokyo, while CMOS sensor supply rests on Sony Semiconductor and OmniVision foundry output. Single-source vulnerability concentrates in German precision optics clusters, where Jena-based lens grinding capacity serves multiple competing device brands. Distribution runs through hospital group purchasing organizations in North America and specialized medical device distributors in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
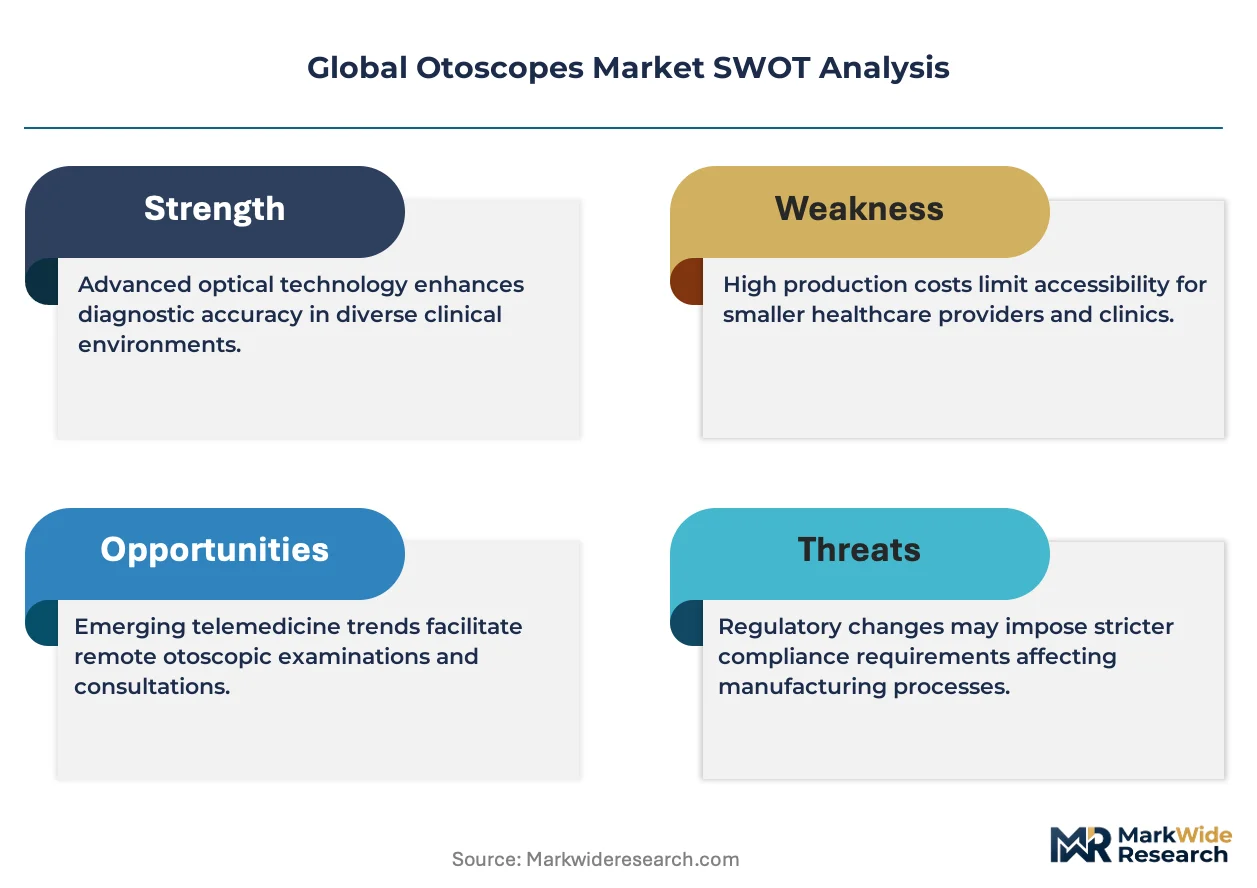
This market functions as a geographic-arbitrage play between EU MDR compliance costs in Europe and CDSCO pathway efficiencies in India, where regulatory timelines compress development expenditure by half.
For Market Incumbents: Deepen backward integration into CMOS sensor supply chains to offset Sony Semiconductor allocation constraints. Capture in-house production of lithium-polymer battery modules to defend margin position against portable device commoditization. Fortify EHR partnership moats against software-native entrants targeting hospital IDN contracts. For New Entrants and Emerging Players: Launch via smartphone-integrated diagnostic platforms targeting Australian rural health networks and Canadian remote outposts where asynchronous telemedicine infrastructure outpaces incumbent penetration. Prioritize Ayushman Bharat procurement channels in tier-2 Indian cities for highest volume accessibility. Differentiate through USB-C charging protocol standardization and field durability specifications absent in legacy vendor portfolios. For Investors and Strategic Acquirers: Platform integrators with established hospital system relationships are the most active acquirer in this space, seeking precision optics specialists to fill capability gaps. Long-term viability hinges on algorithm-enabled diagnostic differentiation rather than hardware margin capture alone. Watch CMS reimbursement determinations for remote ENT consultation codes as the critical inflection signal converting pilot expenditures to sustainable revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates United States hospital procurement cycles for CMOS-enabled platforms. |
| CE Marking Under EU MDR | Determines European market access timelines for algorithm-augmented otoscopy systems. |
| Hospital System Partnership | Locks in enterprise telehealth contracts with integrated delivery networks. |
| Software Companion Development | Enables AI-augmented tympanic membrane classification under EU AI Act frameworks. |
| Reimbursement Strategy | Aligns connected otoscope investments with CMS remote diagnostic service codes. |
Research Methodology
Multiple input streams — primary interviews with ENT clinicians and hospital purchasing committees, secondary validation through FDA 510(k) filings and GPO contract databases, and trade data reconciliation — were synthesized through bottom-up and top-down triangulation. Stakeholder engagement encompassed biomedical engineers at German university hospitals, GPO contracts managers at United States integrated delivery networks, and CDSCO regulatory consultants advising Indian market entrants. Secondary sources included CMS Medicare reimbursement data, EU MDR notified body registries, and hospital procurement platform disclosures.
Data-stream reconciliation across product type, technology tier, application setting, and end-user facility scale produced volume and value estimates throughout the forecast period. Segmentation modeling captured integration depth, sensor resolution specifications, and regional regulatory cluster variations. CAGRs were derived from installed base replacement cycles, telemedicine infrastructure deployment trajectories, and reimbursement policy evolution patterns.
Several conditions sit outside the modeled scope, including pandemic-disrupted supply chain events, abrupt tariff reconfigurations affecting optical component trade flows, and breakthrough sensor technologies rendering CMOS architectures obsolete. Forecasts reflect documented assumptions about regulatory pathway stability and procurement centralization trends. A model refresh is warranted upon material change in CMS remote diagnostic reimbursement determinations or EU AI Act implementation guidance for algorithm-enabled medical devices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Radiology Devices Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Infusion Pump Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market