
 Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market | 2026-2036
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market Outlook
CE-marked implant-grade biocompatibility is unwinding older titanium-alloy benchmarks across the Asia-Pacific MIGS landscape. Alcon Inc. leverages its canaloplasty-microstent hybrid platforms to anchor premium positioning in Australian and Japanese surgical suites. Glaukos Corporation sustains R&D intensity around its trabecular meshwork bypass systems, while Santen Pharmaceutical dominates distribution through its entrenched ophthalmic pharma relationships across East Asia.
Micro Invasive Glaucoma Surgery devices constitute miniature implantable or disposable instruments—typically sub-millimeter stents, biocompatible shunts, or precision cannulas—designed to reduce intraocular pressure through trabecular or suprachoroidal outflow enhancement without conjunctival dissection. Stent-based platforms command the dominant revenue share due to established reimbursement and surgeon familiarity, while shunt categories represent the fastest-expanding margin pool as suprachoroidal drainage protocols gain clinical traction. Office-based delivery modes are accelerating fastest among delivery mode segments, driven by capital-light clinic models in India and South Korea seeking to decouple procedural economics from hospital infrastructure.
PMDA in Japan, TGA in Australia, and CDSCO in India each enforce distinct biocompatibility and sterilization validation requirements that fragment registration timelines and shape regional product launch sequencing. The EU MDR's extraterritorial influence on CE-marked reference devices further complicates pathway planning for manufacturers targeting multiple Asia-Pacific jurisdictions. Stakeholders must monitor regulatory divergence between ASEAN harmonization initiatives and national-level premarket approval frameworks to optimize capital deployment across manufacturing and clinical trial infrastructure.
Market Dynamics
Canaloplasty-microstent hybrid platforms are forcing a recalibration of surgical training protocols and capital allocation across Asia-Pacific ophthalmology departments, as these dual-mechanism devices demand distinct instrumentation and reimbursement coding compared to standalone trabecular meshwork bypass systems.
Growth Catalysts
- Streamlined PMDA pathways:Japan's Pharmaceuticals and Medical Devices Agency reduced ophthalmic implant review cycles, accelerating device registration timelines and enabling faster commercialization for minimally invasive glaucoma interventions.
- Metropolitan clinic networks:Australia's private eye care centers in Sydney and Melbourne are expanding MIGS procedural volume through dedicated surgical suites and direct-to-patient marketing channels.
- Biocompatibility validation:CE-marked implant-grade materials are displacing older titanium-alloy benchmarks, reducing foreign-body response rates and enabling broader surgeon adoption across Southeast Asian hospital systems.
Market Restraints
- Silicone supply concentration:Medical-grade silicone sourcing depends on a limited supplier base concentrated in Northeast Asia, creating vulnerability to input cost volatility and batch consistency issues.
- CDSCO sterilization requirements:India's Central Drugs Standard Control Organization enforces distinct terminal sterilization validation protocols that extend registration timelines and fragment product launch sequencing.
- Laser trabeculoplasty substitution:Selective laser trabeculoplasty remains a lower-cost first-line intervention for early-stage glaucoma, limiting MIGS penetration among price-sensitive patient populations.
Strategic Opportunities
- South Korean office-based delivery:Capital-light clinic models in Seoul and Busan are decoupling procedural economics from hospital infrastructure, creating demand for portable MIGS instrumentation.
- Suprachoroidal drainage protocols:Shunt-based platforms targeting the suprachoroidal space represent an emerging application with faster pressure reduction kinetics than trabecular alternatives.
- ASEAN harmonization initiatives:Regional regulatory alignment efforts are reducing redundant clinical trial requirements and enabling centralized manufacturing strategies for multi-country distribution.
Industry Challenges
- Microsurgical skill scarcity:Sub-millimeter stent placement requires specialized gonioscopic visualization training that outpaces current fellowship program output across Asia-Pacific teaching hospitals.
- EU MDR extraterritorial compliance:CE-marked reference devices must satisfy updated Medical Device Regulation documentation standards, complicating pathway planning for manufacturers targeting multiple Asia-Pacific jurisdictions simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market |
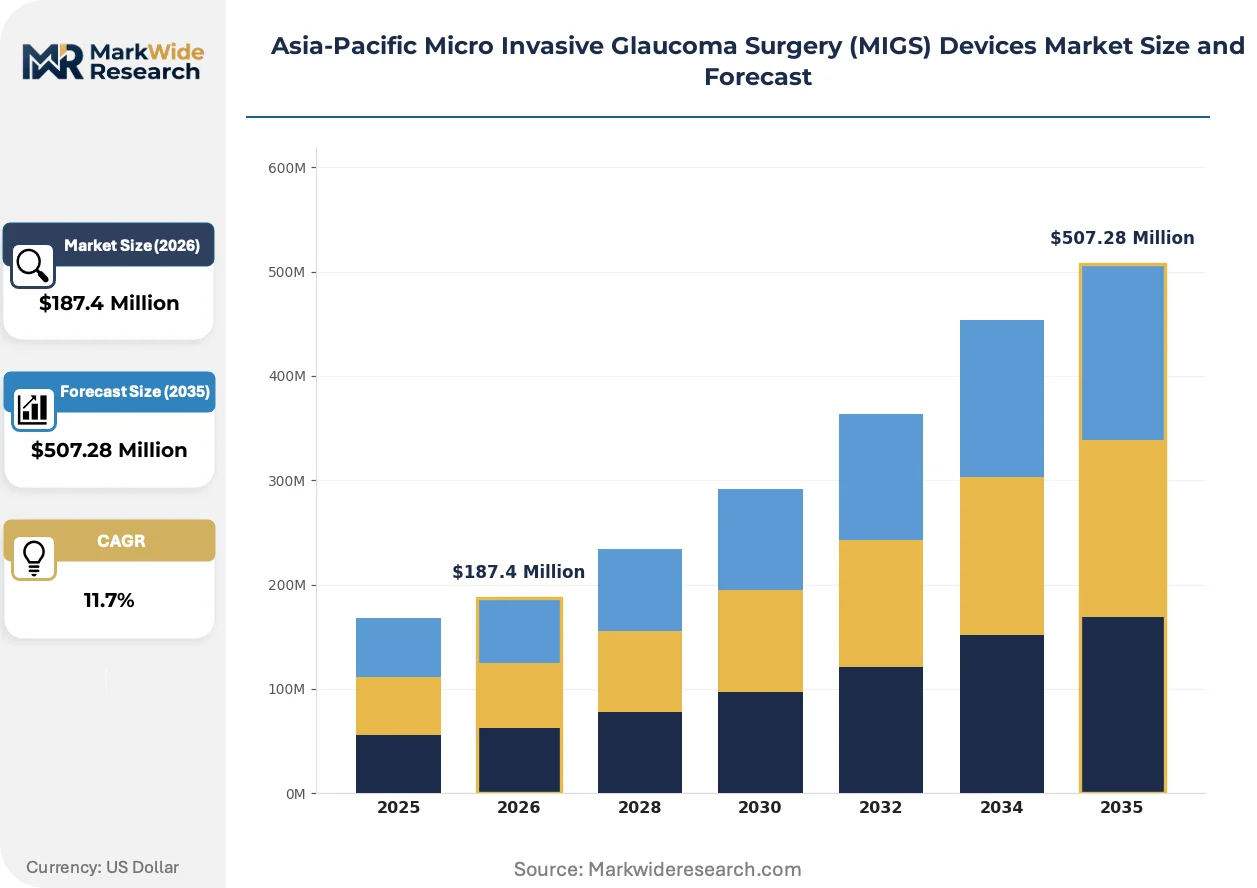
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Implants, Shunts, Cannulas Delivery Mode: Surgical, Office-Based, Ambulatory, Hybrid End User: Hospitals, Clinics, Research Facilities, Eye Care Centers Application: Open-Angle Glaucoma, Angle-Closure Glaucoma, Refractory Glaucoma, Others |
| Companies Covered | Alcon Inc., Glaukos Corporation, Johnson & Johnson, AbbVie Inc., Santen Pharmaceutical, New World Medical, Carl Zeiss Meditec AG, Ellex, Lumenis, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market Strategic Shifts
Active technological differentiation is compressing product lifecycles across the Asia-Pacific MIGS landscape, with manufacturers racing to establish clinical evidence libraries before reimbursement frameworks solidify around specific device categories.
Hybrid canaloplasty-microstent systems are bifurcating the premium device tier from standalone trabecular bypass offerings, as Japanese and Australian surgical suites prioritize dual-mechanism pressure reduction. Hospital-based ophthalmology departments in Singapore and Hong Kong are adopting these platforms at accelerated cadence. This bifurcation is compressing pricing power for single-mechanism devices while expanding the addressable surgical population to earlier disease stages.
PMDA's streamlined approval pathways for minimally invasive ophthalmic implants are compressing device registration timelines and reshaping competitive entry sequencing. Japanese manufacturers are leveraging domestic regulatory familiarity to accelerate clinical trial completion. Foreign device makers are responding by establishing Tokyo-based regulatory affairs subsidiaries and prioritizing Japan as their Asia-Pacific launch market.
Buyer concentration in Australia's metropolitan eye care centers is consolidating procurement leverage among private clinic networks, displacing fragmented hospital purchasing committees. These networks are negotiating direct manufacturer relationships and volume-based service agreements. The shift is most visible in Sydney and Melbourne, where consolidated procurement is compressing distributor margins and reshaping field service deployment models.
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market Segmentation
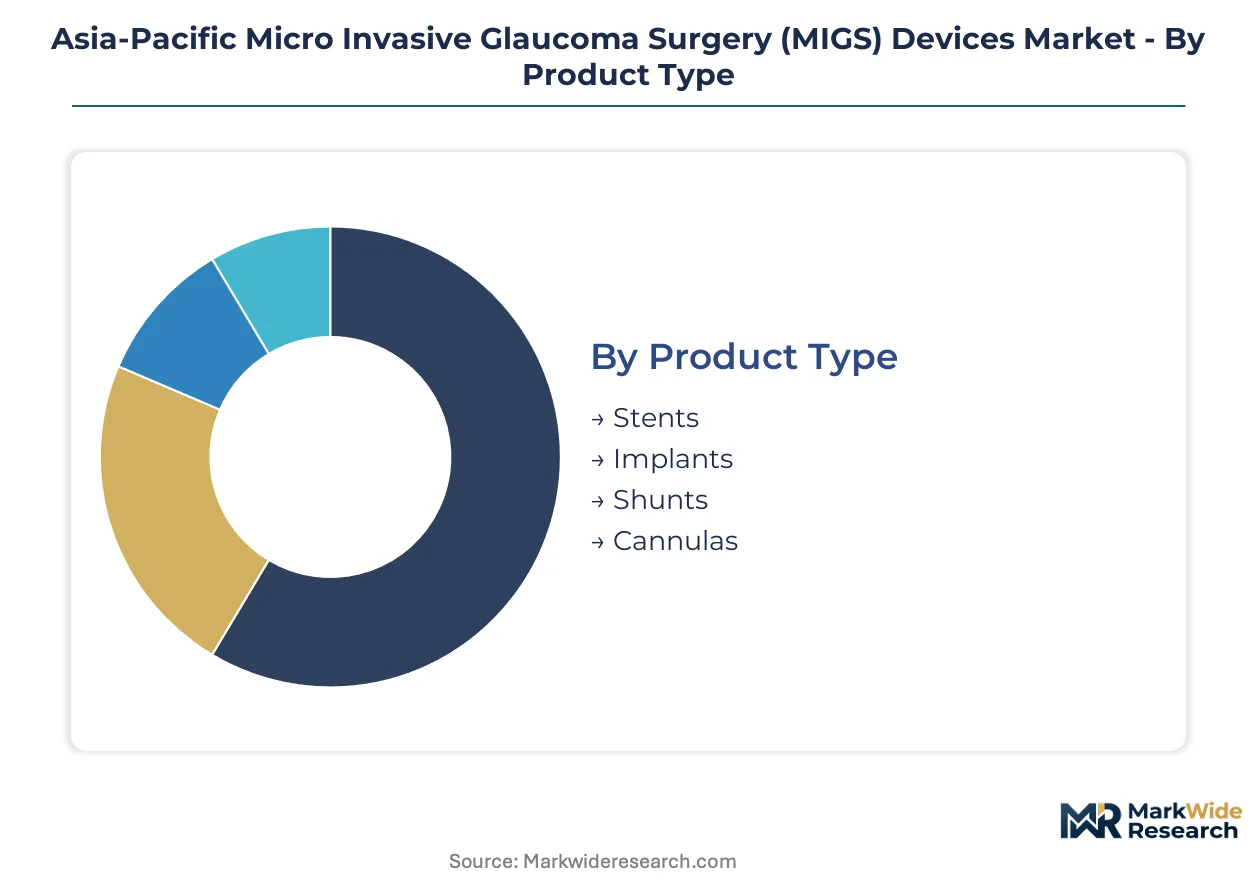
MIGS device segmentation across Asia-Pacific reflects divergent reimbursement frameworks and surgical infrastructure maturity. Product categories align with distinct regulatory pathways, while delivery modes track capital availability across healthcare systems.
Product Type:
PMDA in Japan, TGA in Australia, and CDSCO in India each enforce biocompatibility standards that favor specific material platforms, fragmenting product launch sequencing across submillimeter implant categories.
- Stents:Submillimeter trabecular meshwork bypass devices constructed from implant-grade silicone or nitinol alloys. Australian metropolitan eye care centers concentrate demand through private clinic networks negotiating direct manufacturer relationships. Established reimbursement codes and surgeon familiarity sustain procedural volume.
- Shunts:Suprachoroidal drainage devices redirecting aqueous humor through alternative outflow pathways. Southeast Asian hospital ophthalmology departments are expanding adoption as first-line surgical intervention for refractory cases. Faster pressure reduction kinetics drive emerging clinical traction.
- Implants:Sustained-release drug delivery systems combined with mechanical outflow enhancement.
- Cannulas:Precision micro-instruments for viscodilation and trabecular meshwork access.
Established volume favors stents; emerging adoption favors shunts.
Delivery Mode:
Capital intensity requirements separate hospital-dependent surgical suites from capital-light clinic models proliferating in South Korea and India.
- Surgical:Operating room-based procedures requiring full anesthesia support and gonioscopic microscopy infrastructure. Japanese and Australian hospital ophthalmology departments maintain dominant procedural share through dedicated surgical suites and fellowship-trained specialists.
- Office-Based:Local-anesthesia procedures decoupled from hospital infrastructure. Seoul and Busan clinic networks are accelerating this segment fastest through portable instrumentation and streamlined patient throughput.
- Ambulatory:Same-day discharge facilities with intermediate capital requirements.
- Hybrid:Flexible protocols adapting surgical intensity to patient risk profiles.
Capital concentration sustains surgical dominance; margin expansion favors office-based conversion.
End User:
Procurement authority fragmentation shapes pricing leverage across institutional categories.
- Hospitals:Integrated ophthalmology departments with centralized purchasing committees and established sterilization protocols. Southeast Asian public hospital systems drive volume through government reimbursement frameworks.
- Eye Care Centers:Dedicated ophthalmic facilities with specialized surgical suites. Sydney and Melbourne private networks are consolidating procurement leverage through volume-based service agreements.
- Clinics:General practice or multi-specialty settings with limited glaucoma surgical capacity.
- Research Facilities:Academic medical centers conducting device trials and training programs.
Procurement scale favors hospitals; pricing compression concentrates in eye care center networks.
Application:
Disease severity and anatomy determine device selection and reimbursement eligibility.
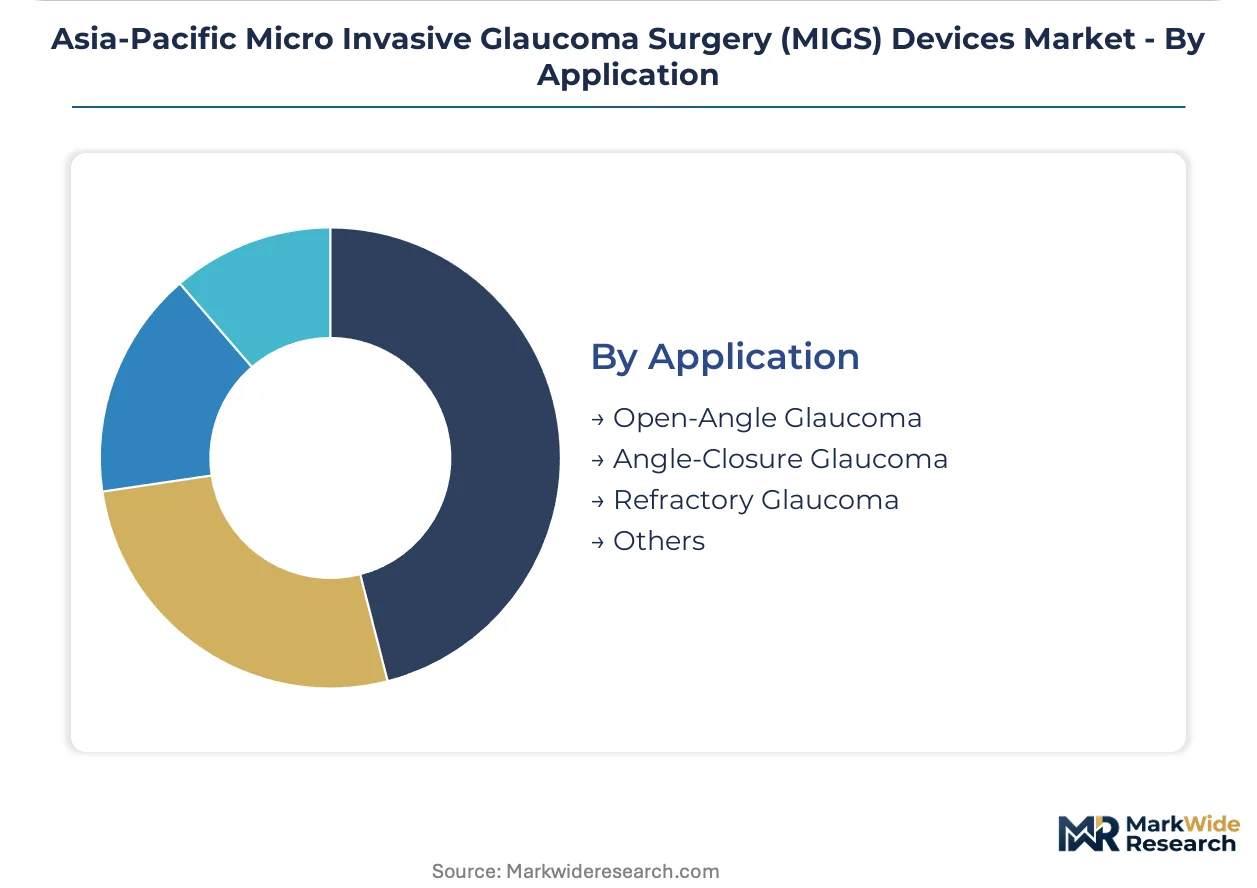
- Open-Angle Glaucoma:Trabecular meshwork dysfunction with preserved anterior chamber anatomy. Australian and Japanese surgical suites prioritize canaloplasty-microstent hybrid platforms for this indication.
- Refractory Glaucoma:Cases failing pharmaceutical or laser intervention. Suprachoroidal shunt platforms are expanding fastest here due to superior pressure reduction kinetics.
- Angle-Closure Glaucoma:Anatomical iris-cornea apposition limiting conventional outflow.
- Others:Pigmentary, pseudophakic, and traumatic glaucoma variants.
Procedure volume concentrates in open-angle cases; technology differentiation targets refractory segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian device imports flow into Southeast Asian hospital systems as regional supply chains consolidate around Japanese regulatory benchmarks. Metropolitan surgical clusters in Sydney and Melbourne negotiate directly with manufacturers, bypassing traditional distributor networks.
Japan
PMDA's streamlined ophthalmic implant pathways compress registration timelines for minimally invasive devices. Tokyo-based regulatory affairs subsidiaries enable foreign manufacturers to accelerate clinical trial completion. The Kanto surgical corridor concentrates dual-mechanism platform adoption in teaching hospitals.
Australia
Private clinic networks in Sydney and Melbourne consolidate procurement leverage through volume-based service agreements. TGA biocompatibility standards favor CE-marked implant-grade materials over legacy titanium benchmarks. Metropolitan eye care centers drive procedural volume through dedicated surgical suites.
South Korea
Capital-light clinic models in Seoul and Busan decouple MIGS economics from hospital infrastructure. MFDS sterilization protocols shape device validation requirements for domestic manufacturers. The Seoul Capital Area anchors portable instrumentation demand for office-based delivery.
India
CDSCO terminal sterilization requirements extend registration timelines for imported devices. Government hospital ophthalmology departments in Maharashtra and Karnataka drive volume through public reimbursement frameworks. Mumbai and Bangalore surgical clusters adopt suprachoroidal drainage protocols for refractory cases.
Singapore
Hospital-based ophthalmology departments adopt hybrid canaloplasty-microstent systems at accelerated cadence. The national health system prioritizes dual-mechanism devices through centralized procurement committees. The island's surgical training programs address microsurgical skill scarcity across Southeast Asia.
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market Competitive Environment
Listed leaders compete with private specialists across regulatory familiarity and distribution infrastructure. The vendor base stratifies into three tiers: multinational ophthalmic conglomerates with hybrid platform portfolios, mid-cap device specialists focused on trabecular meshwork bypass, and regional distributors leveraging entrenched pharma relationships. Dominant competitive moves include Tokyo-based regulatory subsidiary establishment and direct procurement negotiations with Australian clinic networks.
Within the multinational tier, Alcon Inc. and Glaukos Corporation exemplify divergent strategic positioning. Alcon anchors premium-tier presence through canaloplasty-microstent hybrid platforms. Glaukos occupies a position emphasizing trabecular meshwork bypass specialization. Santen Pharmaceutical represents the distribution-centric archetype, leveraging East Asian ophthalmic pharma relationships to sustain market access without captive device manufacturing.
| Leading Market Players |
|---|
| Alcon Inc. |
| Glaukos Corporation |
| Johnson & Johnson |
| AbbVie Inc. |
| Santen Pharmaceutical |
| New World Medical |
| Carl Zeiss Meditec AG |
| Ellex |
| Lumenis |
| Others |
Value Chain & Pricing Dynamics
CE marking and PMDA biocompatibility certifications simultaneously gate supplier qualification and stratify price tiers across Asia-Pacific MIGS procurement. Regulatory compliance costs concentrate pricing power among implant-grade silicone processors while filtering out legacy titanium-alloy suppliers from premium contracting.
Pricing Analysis
Private clinic networks in Sydney and Melbourne anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on dual-mechanism hybrid platforms versus standalone trabecular devices, with after-sales service bundling widening spreads. Cost compression in the standard tier intensifies as Korean and Indian manufacturers expand CE-marked output. Government hospital systems across Southeast Asia exhibit highest price sensitivity; Japanese teaching hospitals show lowest sensitivity due to reimbursement adequacy.
Supply Chain Analysis
Medical-grade silicone feedstock dependence on Northeast Asian chemical processors creates single-source vulnerability for submillimeter stent manufacturers. Raw material flows draw from Japan, South Korea, and specialized German polymer houses, with nitinol alloy sourcing tethered to American and Chinese titanium processors. Distribution runs through regional ophthalmic distributors in East Asia and direct manufacturer relationships in Australian metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selective laser trabeculoplasty substitutes threaten MIGS volume in early-stage glaucoma segments, forcing incumbents to defend surgical indication expansion while new entrants seek white-space in refractory case protocols.
For Market Incumbents: Consolidate procurement relationships with Australian clinic networks through volume-based service agreements before Korean office-based competitors establish portable instrumentation standards. Deepen backward integration into medical-grade silicone compounding to offset Northeast Asian supply concentration. Prioritize PMDA regulatory affairs subsidiary expansion to compress Japanese registration timelines against domestic rivals.
For New Entrants and Emerging Players: Differentiate on suprachoroidal drainage kinetics for refractory glaucoma segments where established stent platforms underperform. Target Indian government hospital systems through CDSCO sterilization validation partnerships. Pursue go-to-market alignment with Santen Pharmaceutical's East Asian distribution infrastructure rather than direct hospital contracting.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across office-based delivery instrumentation as Korean and Indian clinic models decouple from surgical suite infrastructure. Long-term viability favors device specialists with hybrid platform pipelines and regulatory affairs capabilities spanning PMDA, TGA, and CDSCO pathways. Monitor ASEAN harmonization treaty ratification as signal for centralized manufacturing investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Regulatory Subsidiary Establishment | Tokyo-based affairs teams compress ophthalmic implant review cycles against domestic competitors. |
| CE Marking Pathway Completion | Implant-grade biocompatibility certification displaces titanium-alloy benchmarks across Southeast Asian hospital procurement. |
| Hospital System Partnership | Singapore national health system centralized committees prioritize dual-mechanism hybrid platform adoption. |
| Backward Integration into Silicone Compounding | In-house polymer processing mitigates Northeast Asian medical-grade silicone supply concentration risk. |
| Reimbursement Strategy | Australian private clinic network direct contracting bypasses fragmented distributor margin structures. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, hospital procurement databases, and GPO contract repositories. Interviews with glaucoma surgeons, biomedical engineers, hospital purchasing committee members, and ophthalmic distributor principals inform demand-side validation. Secondary sources include PMDA approval summaries, TGA device registration records, CDSCO import notifications, and CMS-equivalent reimbursement schedules across Asia-Pacific jurisdictions. Bottom-up procedural volume estimates triangulate against top-down manufacturer shipment data.
Segmentation dimensions modeled span product type, delivery mode, end user, and application across the projection horizon. The analytical framework incorporates disease severity staging, surgical infrastructure maturity, and regulatory pathway differentiation throughout the forecast period. CAGRs derive from installed base expansion rates, replacement cycles for disposable instrumentation, and reimbursement framework evolution. Forecast inputs include fellowship-trained surgeon pipeline output and office-based clinic capital deployment patterns.
The analysis sits within stated boundaries; outcomes outside sustained PMDA streamlining, ASEAN regulatory harmonization, or silicone supply stability would require recalibration. Forecasts assume continued reimbursement adequacy in Australian private networks and Japanese universal coverage. Practitioners should keep alternative scenarios live as selective laser trabeculoplasty protocol refinements and suprachoroidal drainage clinical evidence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Integration Systems Market
Medical Devices
Enteral Stents Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Stool Management Systems Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Global Laparoscopy Devices Market