
 Unmanned Ground Vehicle Market | 2026-2036
Unmanned Ground Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Ground Vehicle Market Intelligence
The interoperability standard demanded by frameworks like the US Department of Defense's JADC2 is collapsing the distinction between proprietary and open-architecture UGV systems. General Dynamics Corporation leverages its extensive experience in military vehicle production to secure large-scale contracts. Teledyne FLIR differentiates through its advanced thermal imaging and sensor payloads, critical for reconnaissance missions. QinetiQ Group plc specializes in developing highly modular and remote-controlled robotic platforms for hazardous environment operations.
An Unmanned Ground Vehicle is a land-based vehicle operating without a human onboard, using technologies like Lidar and computer vision for navigation. Its core industrial purpose is to execute tasks deemed too dangerous or inefficient for personnel, such as carrying sensor payloads for military reconnaissance or inspecting construction sites. Military reconnaissance applications continue to command the largest market share, driven by defense modernization programs. The agricultural monitoring segment, however, represents the fastest-growing application as farming enterprises adopt autonomous solutions for crop management.
Regulations from bodies like the US Federal Aviation Administration (FAA) for ground-to-air coordination and the EU's upcoming AI Act are shaping operational parameters. These frameworks influence data security protocols and establish liability standards, directly impacting market access for UGV manufacturers. Stakeholders must now decide whether to prioritize developing highly specialized, single-task UGVs or to invest in versatile, multi-mission platforms with modular capabilities.
Market Dynamics
The central tension in the Unmanned Ground Vehicle market is the divergence between highly specialized, ruggedized military platforms and the scalable, cost-sensitive demands of emerging commercial sectors like agriculture and logistics, driven by advancements in autonomous navigation.
Growth Catalysts
- Defense Modernization Programs:Mandates like the US JADC2 framework create sustained demand for interoperable UGVs in reconnaissance and logistics roles.
- Agricultural Automation:The farming sector adopts UGVs for precision tasks like crop monitoring, addressing labor shortages and improving resource efficiency.
- Sensor Technology Gains:Lidar and computer vision advancements enhance navigational autonomy, enabling UGVs to operate reliably in complex, unstructured environments.
Market Restraints
- High Capital Expenditure:The significant cost of UGVs and advanced sensor payloads limits adoption, particularly in budget-sensitive commercial sectors.
- Evolving Regulatory Frameworks:Regulations like the EU AI Act create compliance uncertainty and market access challenges regarding liability and autonomous decision-making.
- Power Source Limitations:Battery life and energy density constrain the operational range and endurance of electric UGVs, especially those carrying heavy payloads.
Strategic Opportunities
- Last-Mile Delivery Services:The logistics sector offers a growth avenue for small, autonomous UGVs to automate package delivery in urban settings.
- Swarm Intelligence Platforms:Combining 5G and edge computing enables collaborative UGV swarms for complex tasks like coordinated search or mapping.
- Hazardous Environment Operations:Australian mining and nuclear sites present opportunities for specialized UGVs to perform inspection and material handling tasks.
Industry Challenges
- Systems Integration Complexity:Integrating new UGV platforms with disparate, legacy command and control infrastructures remains a significant technical hurdle for defense and industrial users.
- Specialized Talent Scarcity:A persistent shortage of technicians and engineers skilled in robotics, AI, and mechatronics impedes the deployment and maintenance of advanced UGV fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Ground Vehicle Market |
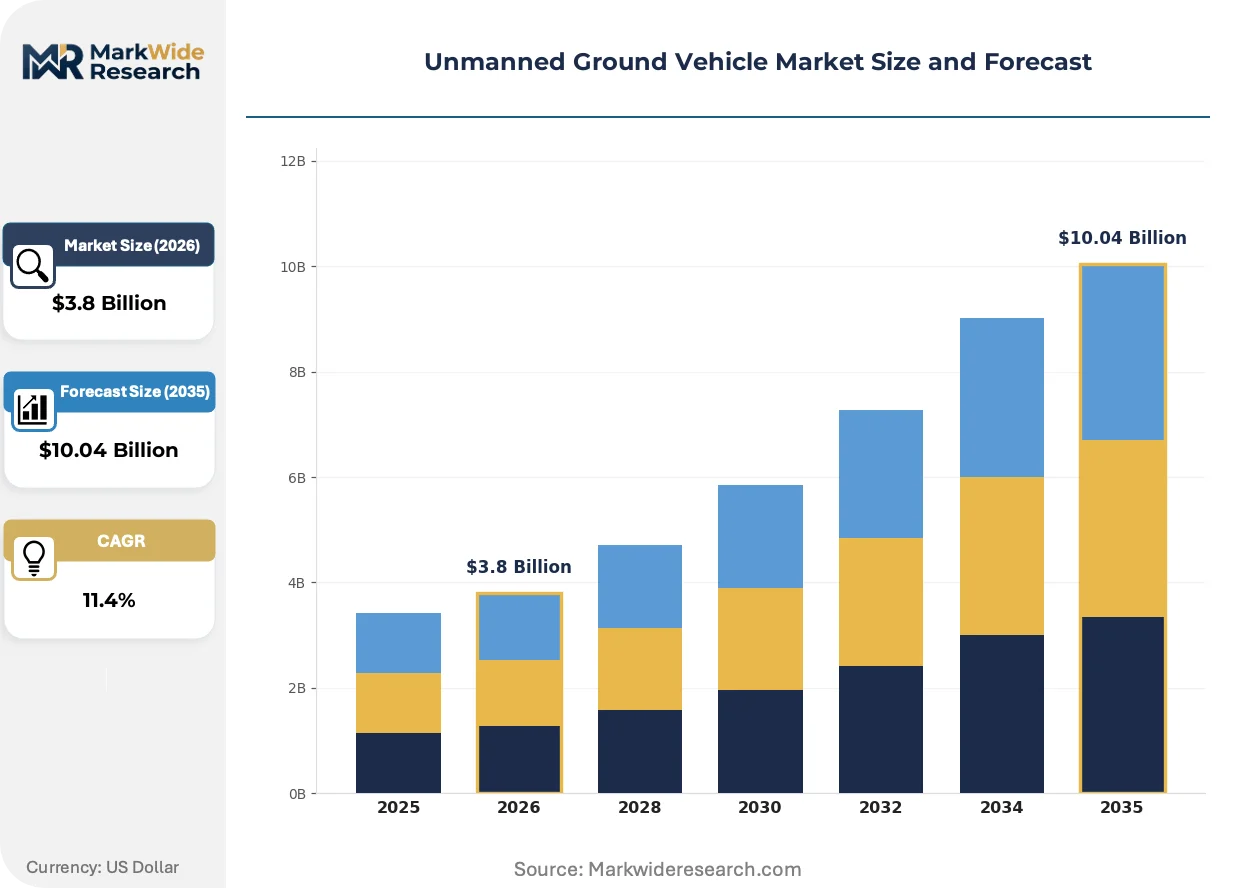
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Autonomous, Remote Controlled, Hybrid, Semi-autonomous Application: Military Reconnaissance, Agricultural Monitoring, Search & Rescue, Law Enforcement Patrols, Construction Site Inspection Technology: GPS Navigation, Computer Vision, Lidar, Infrared Sensors, Machine Learning End User: Defense Departments, Farming Enterprises, Emergency Services, Public Safety Agencies |
| Companies Covered | Teledyne FLIR, QinetiQ Group plc, General Dynamics Corporation, L3Harris Technologies, Lockheed Martin, BAE Systems, Northrop Grumman Corporation, Leonardo S.p.A., Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Ground Vehicle Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from hardware-centric design to software-defined autonomy. This shift prioritizes modularity, advanced algorithms, and data processing capabilities over the physical platform itself.
Modular, open-architecture software serves as the central nervous system for modern UGVs. Defense and commercial logistics operators are rapidly adopting these systems to enable platform-agnostic payload integration. This trend is fragmenting the traditionally monolithic and proprietary UGV market, creating opportunities for specialized software and sensor providers.
Europe's AI Act establishes a risk-based framework for artificial intelligence systems. This regulation mandates strict transparency, data quality, and human oversight requirements for high-risk applications, including autonomous vehicles. UGV manufacturers targeting European civilian markets must now redesign their development processes to ensure auditable compliance, impacting product roadmaps.
A notable shift in acquisition strategy involves the adoption of Robots-as-a-Service (RaaS) models over direct capital purchases. This model disrupts traditional equipment sales by offering subscription-based access to UGV capabilities, including maintenance and software updates. The trend is most prominent within the warehouse automation and agricultural monitoring segments where operational flexibility is valued.
Unmanned Ground Vehicle Market Segmentation
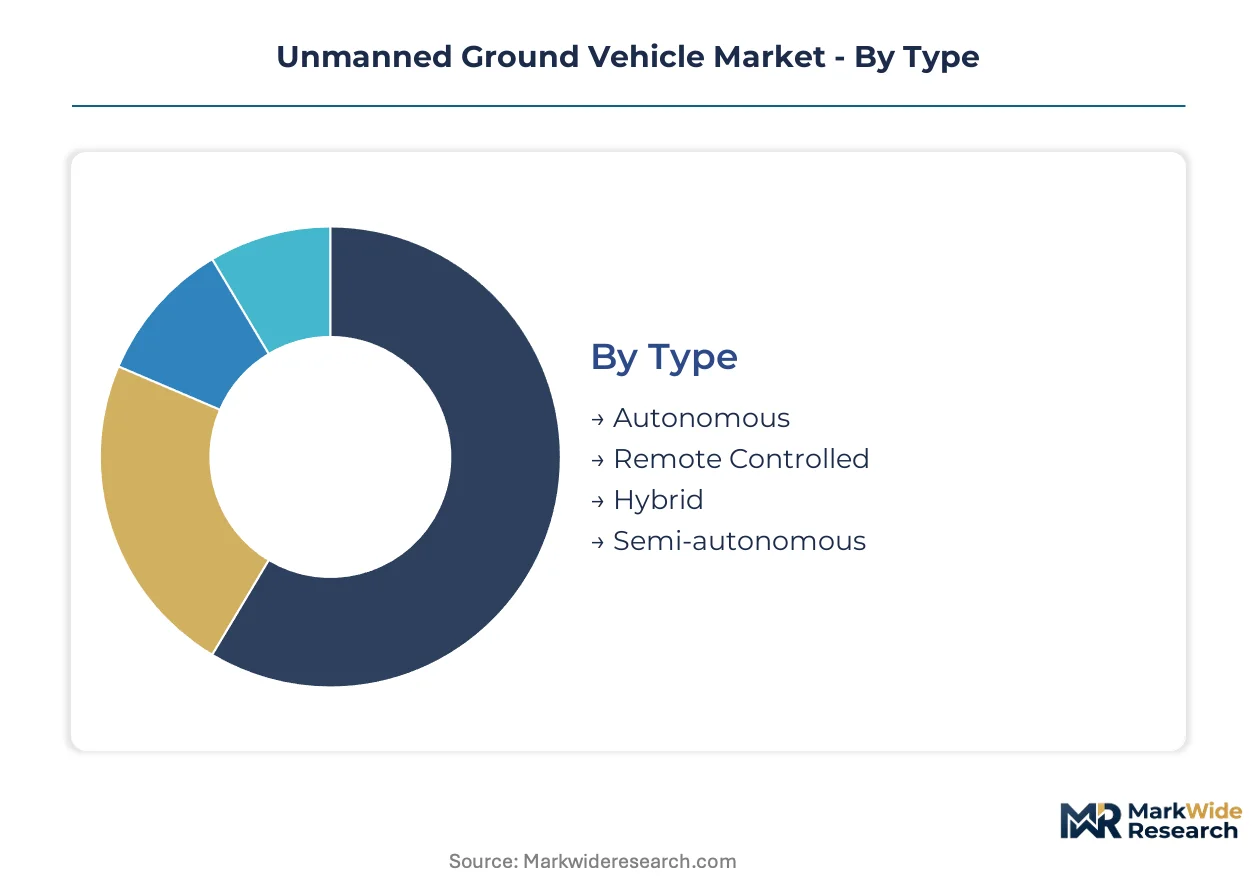
Understanding the Unmanned Ground Vehicle market through its segmentation reveals the diverse operational requirements and technological drivers shaping its evolution. This granular view highlights where value creation is concentrated and how different applications demand specialized solutions.
Type:
Margin pools within the UGV Type category increasingly concentrate in solutions offering advanced autonomy and specialized functionality.
- Autonomous:These UGVs operate without direct human control, utilizing sophisticated AI and sensor fusion for navigation and task execution in dynamic environments. Demand concentrates in sectors requiring continuous operation and complex decision-making, such as advanced military reconnaissance and precision agriculture.
- Remote Controlled:Operators directly command these UGVs from a distance, often through a secure communication link, providing precise real-time intervention for hazardous tasks. Demand remains strong in bomb disposal and initial survey missions where human oversight is critical for safety.
- Hybrid:Combining autonomous capabilities with remote override options, these UGVs offer operational flexibility for varied mission profiles. Public safety agencies often deploy hybrid systems for incident response, balancing efficiency with human control.
- Semi-autonomous:These systems perform specific tasks autonomously but require human input for higher-level decision-making or navigation in complex scenarios. Construction site inspection benefits from semi-autonomous UGVs for routine data collection.
The dominant share belongs to Remote Controlled systems, while Autonomous platforms are closing the gap fastest.
Application:
Cost tier differentiation significantly influences adoption across various UGV applications, with specialized military uses tolerating higher capital expenditure.
- Military Reconnaissance:UGVs equipped with advanced sensors gather intelligence and survey hazardous areas, reducing human risk in combat zones. The United States defense sector is a primary buyer, driven by modernization programs.
- Agricultural Monitoring:These UGVs collect data on crop health, soil conditions, and livestock, enabling precision farming practices to optimize yields. Farming enterprises in North America adopt these systems to address labor shortages and enhance efficiency.
- Search & Rescue:UGVs navigate dangerous terrains or collapsed structures to locate survivors, providing critical support in disaster relief operations. Emergency services utilize these platforms for rapid assessment in inaccessible environments.
- Law Enforcement Patrols:UGVs assist in surveillance, perimeter security, and crowd control, enhancing situational awareness for public safety agencies. Urban areas are exploring these platforms for routine monitoring.
- Construction Site Inspection:Autonomous UGVs monitor progress, inspect structural integrity, and ensure safety compliance on large-scale building projects. These systems reduce the need for manual inspections in hazardous zones.
Military Reconnaissance commands the largest revenue share, with Agricultural Monitoring demonstrating the steepest expansion trajectory.
Technology:
Technology advancements directly enable new UGV applications, with sensor integration critical for complex environmental understanding.
- Machine Learning:Algorithms enable UGVs to learn from data, improving object recognition, path planning, and autonomous decision-making in unstructured environments. This technology underpins advanced autonomy for next-generation platforms.
- Lidar:These sensors create high-resolution 3D maps of surroundings, crucial for precise navigation and obstacle avoidance, especially in low-light conditions. Autonomous UGVs heavily rely on Lidar for accurate environmental perception.
- GPS Navigation:Global Positioning System provides fundamental location data for UGV movement and waypoint following in outdoor environments. This technology forms the baseline for most UGV operational frameworks.
- Computer Vision:Cameras and image processing allow UGVs to detect objects, interpret visual cues, and track movement, supporting tasks like crop analysis or security surveillance.
- Infrared Sensors:These sensors detect heat signatures, enabling UGVs to operate in darkness, fog, or smoke, vital for search and rescue or military night operations.
GPS Navigation forms the foundational layer, while Machine Learning is increasingly integral for advanced autonomy.
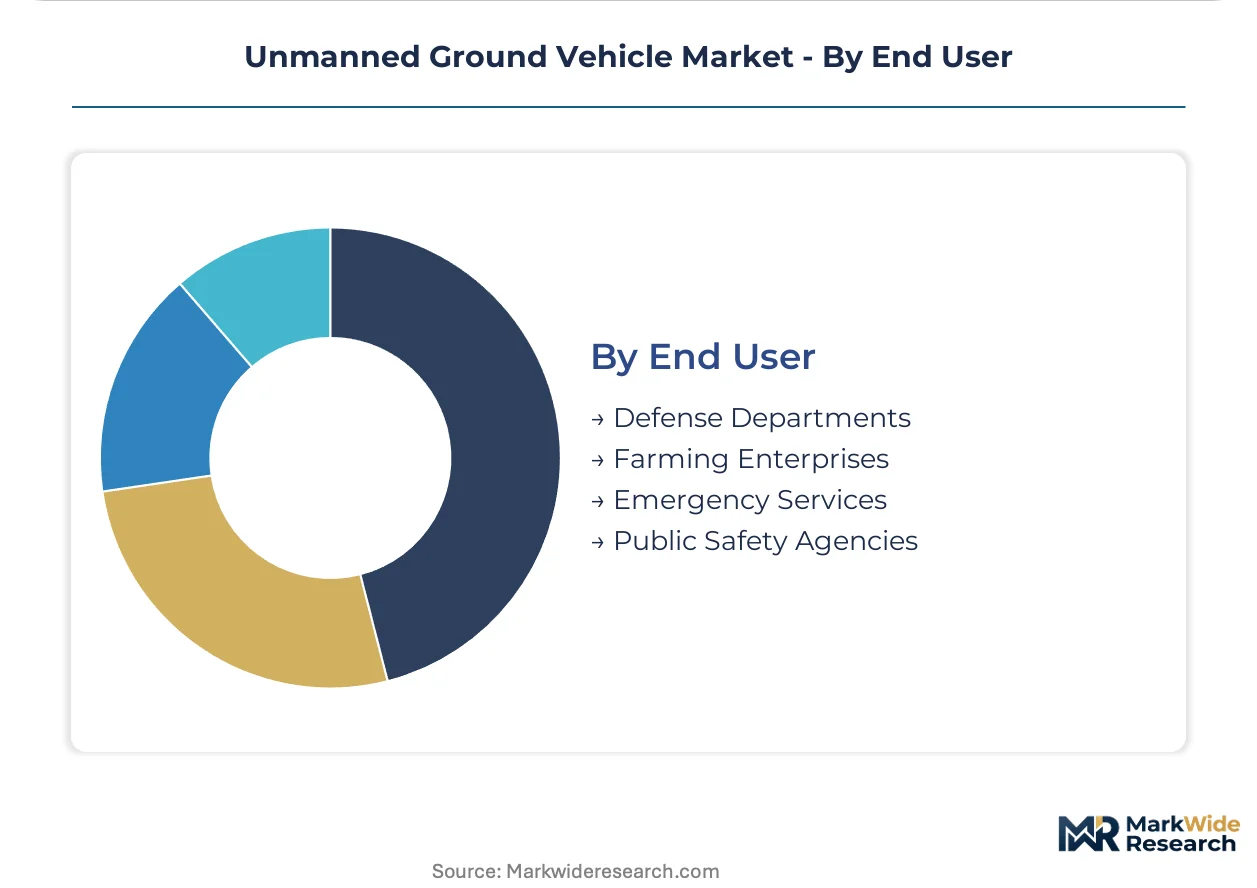
End User:
Customer type dictates UGV procurement strategies, ranging from large-scale government defense contracts to distributed commercial farming acquisitions.
- Defense Departments:Military organizations procure UGVs for reconnaissance, logistics, explosive ordnance disposal, and combat support, driven by modernization initiatives. The US Department of Defense is a significant customer for advanced UGV systems.
- Farming Enterprises:Agricultural businesses adopt UGVs for precision spraying, crop monitoring, and automated harvesting, addressing labor costs and improving resource management. Enterprises in Europe are increasingly integrating these solutions.
- Emergency Services:Fire departments, police, and disaster response teams deploy UGVs for hazardous environment assessment, search and rescue, and incident scene management. These services prioritize ruggedness and quick deployment.
- Public Safety Agencies:These entities use UGVs for surveillance, perimeter security, and crowd monitoring in urban settings and critical infrastructure protection. Law enforcement in various countries is exploring UGV integration.
Defense Departments represent the primary purchasing power, with Farming Enterprises expanding their UGV fleet significantly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense modernization programs globally stimulate demand for advanced Unmanned Ground Vehicles. Government initiatives, such as the US JADC2 framework, promote interoperability and autonomous capabilities across military platforms. These policies significantly influence procurement decisions and technological development in key markets.
United States
Military reconnaissance and logistics support drive significant UGV demand, alongside expanding agricultural monitoring applications. The US Department of Defense's JADC2 framework actively mandates interoperable UGV systems for future combat operations. Silicon Valley and Boston serve as crucial hubs for AI and robotics development, accelerating advanced UGV autonomy.
Germany
Industrial automation, defense sector upgrades, and specialized hazardous environment operations generate consistent demand for UGVs. The EU AI Act influences UGV development, focusing on stringent data security and liability standards for civilian use. Munich and Stuttgart host substantial automotive and robotics engineering firms, fostering cutting-edge UGV innovation.
China
Agricultural automation, last-mile logistics delivery, and domestic defense modernization programs fuel rapid UGV expansion. China's national AI development plan prioritizes autonomous systems, including UGVs, for both economic growth and strategic independence. Shenzhen's robust manufacturing ecosystem supports rapid prototyping and high-volume production of diverse commercial UGV platforms.
Japan
Construction site inspection, disaster response, and precision agricultural applications address persistent labor shortages and efficiency needs. METI promotes robotics innovation through targeted grants and regulatory sandboxes for new autonomous technologies. Tokyo and Nagoya remain key centers for advanced robotics research, driving critical sensor and navigation system advancements.
Australia
Mining operations, hazardous environment inspection, and agricultural efficiency improvements represent core UGV demand segments. The TGA sets crucial safety standards for industrial equipment, impacting UGV deployment strategies in heavy industries. Perth's specialized mining technology sector drives demand for highly ruggedized UGVs capable of performing complex tasks.
Unmanned Ground Vehicle Market Key Industry Players
Player mix skews toward large, established defense contractors alongside specialized robotics and sensor technology firms. The market structure exhibits a tiered consolidation, where a few major players secure significant government contracts while numerous smaller entities innovate in niche applications. Strategic partnerships between hardware manufacturers and software developers are common, facilitating advanced autonomy. Portfolio diversification into commercial sectors like agriculture represents a key competitive move for some defense-oriented companies.
Within the large defense contractor archetype, General Dynamics Corporation exemplifies extensive military vehicle production experience, consistently anchoring large-scale government contracts for UGV systems. Teledyne FLIR, a US-based Inc., represents specialized sensor technology providers, differentiating through advanced thermal imaging and critical payloads essential for diverse reconnaissance missions. QinetiQ Group plc, a UK-based plc, occupies a distinct position among modular platform developers, specializing in highly adaptable remote-controlled robotic solutions tailored for hazardous environment operations and specialized tasks. These entities collectively shape the market's technological trajectory and procurement dynamics, influencing both military and emerging commercial applications.
| Leading Market Players |
|---|
| Teledyne FLIR |
| QinetiQ Group plc |
| General Dynamics Corporation |
| L3Harris Technologies |
| Lockheed Martin |
| BAE Systems |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Rheinmetall AG |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized UGV components, often stretching 12-18 months, directly influence the market's pricing stability and dictate the upstream supply chain's inventory holding strategies. This dynamic favors manufacturers with robust forecasting capabilities and established supplier relationships.
Pricing Analysis
Certification level for operational safety and performance creates the primary price differentiation across Unmanned Ground Vehicles. Project-based and long-term contract pricing models dominate for military and hazardous environment applications. Advanced sensor payloads and AI-driven autonomy drive higher price points. Pricing softness impacts commercial segments due to high initial capital expenditure, making farming enterprises more price-sensitive than defense departments.
Supply Chain Analysis
Global semiconductor shortages, impacting microprocessors and advanced sensor availability, exert significant pressure on UGV manufacturing costs and delivery timelines. The supply chain for critical UGV components draws from China for manufacturing, the United States for defense-grade technology, and Germany for industrial automation parts. Advanced Lidar sensors and high-energy-density battery cells represent key dependencies. Single-source vulnerability for specialized AI chips poses a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Unmanned Ground Vehicle market is experiencing a buyer-power shift towards consolidated defense procurement entities like the US Department of Defense. This centralizes purchasing decisions for interoperable systems, influencing vendor roadmaps significantly.
For Market Incumbents: Secure long-term government contracts by aligning UGV development with interoperability standards like the US JADC2 framework. Diversify product portfolios into commercial sectors, such as agricultural automation, to mitigate reliance on defense spending cycles. The threat of specialized software providers creating modular solutions necessitates increased R&D investment in advanced AI algorithms. Cultivating strategic partnerships with sensor technology firms represents a critical lever.
For New Entrants and Emerging Players: A certification fast-track for commercial-grade UGVs in specific agricultural monitoring applications offers a strategic entry point. Target white-space opportunities in last-mile delivery services within urban areas and specialized inspection tasks in Australian mining sites. The agricultural monitoring segment remains the most penetrable due to labor shortages. Deploying a Robots-as-a-Service (RaaS) model provides a flexible go-to-market angle, reducing customer capital expenditure.
For Investors and Strategic Acquirers: Long-term, this sits as a technology adoption and platform play because autonomous capabilities are becoming indispensable across diverse industries. Identify acquisition targets among specialized software developers and advanced sensor manufacturers. These firms offer critical intellectual property for next-generation UGV autonomy. Widespread adoption of modular, open-architecture software by defense contractors indicates a significant inflection point for platform integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating diverse UGV platforms with JADC2 frameworks enhances military operational efficiency. |
| Software-Defined Autonomy Investment | Prioritizing advanced machine learning algorithms improves UGV decision-making in unstructured environments. |
| RaaS Model Expansion | Offering subscription-based UGV access lowers capital expenditure barriers for farming enterprises. |
| Sensor Payload Miniaturization | Developing smaller, more powerful Lidar and thermal sensors expands UGV utility in confined spaces. |
| Hazardous Environment Specialization | Designing ruggedized UGVs for nuclear sites and mining operations addresses niche industrial demand. |
Research Approach
A standing panel of defense procurement officers, agricultural enterprise managers, and robotics engineers provided ongoing calibration for market insights. The analysis combined primary interviews with these industry stakeholders and secondary validation from official sources. Secondary data included US Department of Defense reports, EU AI Act legislative documents, and company financial filings. Bottom-up market sizing was triangulated with top-down validation against established industry benchmarks.
Outputs were consistently checked against external benchmarks, including national defense budgets and agricultural technology adoption rates, to ensure model robustness across the analysis window. The analytical framework modeled segmentation by UGV type, application, technology, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical expansion and projected investment. Defense spending trends and agricultural automation investment served as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of a stable geopolitical landscape and predictable regulatory evolution; material deviation would warrant model refresh. Forecasts reflect these base assumptions regarding defense modernization and commercial automation. Unforeseen technological disruptions or significant regulatory shifts, like stricter EU AI Act enforcement, represent key risk factors, and outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Rotary-Wing Lidar Drone Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
Autonomous Aircraft Software Market