
 Bomb Disposal Robot Market | 2026-2036
Bomb Disposal Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Bomb Disposal Robot Market Insights
Defense leasing and performance-based service contracts is reconfiguring capital deployment across the competitive landscape. L3Harris Technologies leverages its communications integration expertise to bundle robot platforms with secure datalinks. QinetiQ anchors its position through sustained investment in autonomous navigation software for hazardous environments. Rheinmetall AG dominates European procurement channels with tracked platforms purpose-built for military counterterrorism applications.
Bomb disposal robots are remotely operated or semi-autonomous ground vehicles engineered with articulated manipulator arms, hardened electronic architectures, and real-time video relay systems rated for blast-proximity operations. These systems neutralize improvised explosive devices, chemical threats, and unexploded ordnance without exposing human technicians to detonation hazards. Tracked configurations command the premium segment due to superior obstacle traversal in urban rubble and off-road terrain. Artificial Intelligence and machine vision segments attract disproportionate R&D allocation as defense agencies mandate faster threat identification with reduced operator cognitive load. Remote control technology persists as the volume foundation across police departments with constrained budgets.
FAA guidelines on unmanned ground vehicle airlift compatibility, EU dual-use export controls under the Wassenaar Arrangement, and ISO 13482 safety standards for personal care robots collectively shape product certification roadmaps and cross-border sales eligibility. NHTSA collision-avoidance protocols for autonomous ground vehicles increasingly influence semi-autonomous platform design specifications for domestic law enforcement deployment. Stakeholders must weigh sovereign content requirements against modular open-architecture strategies when configuring supply chains for multinational defense tenders.
Market Dynamics
Machine vision and AI-based threat classification are redirecting vendor R&D budgets away from hardware-centric platforms toward software-defined capabilities that reduce operator cognitive load during high-stress explosive ordnance disposal operations.
Growth Catalysts
- Defense Modernization Programs:Military counterterrorism units across NATO member states are driving procurement volumes for tracked platforms with hardened electronic architectures.
- EU Dual-Use Export Controls:The Wassenaar Arrangement is accelerating domestic production capabilities in member states to circumvent technology transfer restrictions.
- Artificial Intelligence Integration:Autonomous navigation software for hazardous environments is attracting disproportionate R&D allocation as agencies mandate faster threat identification.
Market Restraints
- ISO 13482 Certification Complexity:Safety standards for personal care robots create cross-border sales eligibility friction for semi-autonomous ground vehicle manufacturers.
- Tracked Platform Cost Structure:Premium segment configurations require specialized steel alloys and blast-hardened electronics that concentrate input cost volatility.
- Remote Control Technology Saturation:Police departments with constrained budgets persist with volume-foundation platforms that limit average selling price expansion.
Strategic Opportunities
- South Korean Defense Spending:Explosive ordnance disposal capability prioritization creates white space for vendors with FAA airlift-compatible unmanned ground vehicle designs.
- NHTSA Protocol Convergence:Collision-avoidance standards for autonomous ground vehicles are opening domestic law enforcement deployment pathways previously blocked by safety certification gaps.
- Machine Vision-Manipulator Integration:Convergence of real-time video relay systems with articulated arm precision is enabling chemical threat neutralization applications beyond traditional IED disposal.
Industry Challenges
- Blast-Proximity Electronics Talent Gap:Hardened system design expertise remains concentrated among defense contractor alumni, constraining vendor scaling.
- Modular Open-Architecture Integration:Sovereign content requirements in multinational defense tenders conflict with supply chain flexibility objectives.
- Secure Datalink Certification Timelines:Communications integration expertise must navigate fragmented national security clearance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bomb Disposal Robot Market |
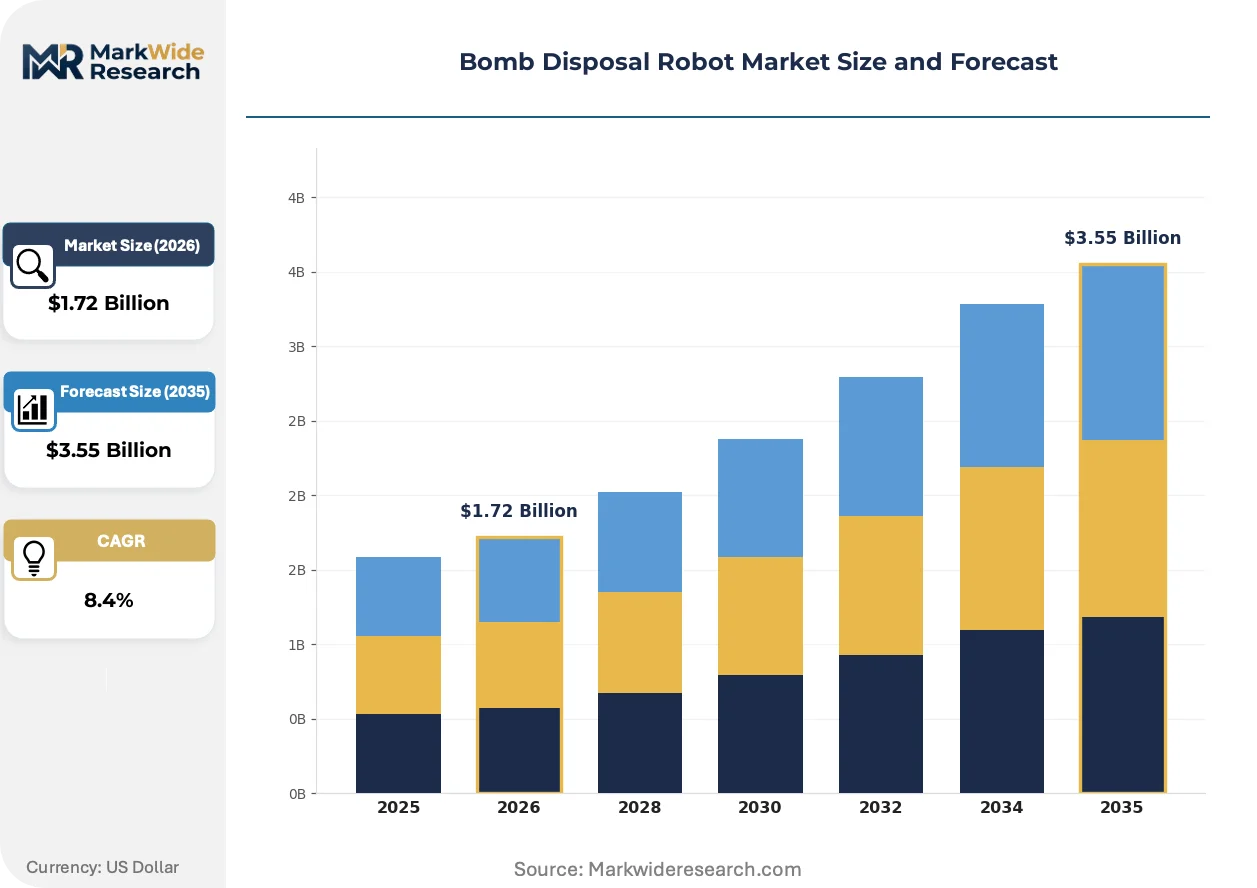
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.55 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracked, Wheeled, Hybrid, Stationary Manipulator Technology: Autonomous Navigation, Remote Control, Semi-Autonomous, Artificial Intelligence, Machine Vision Application: Military Counterterrorism, Law Enforcement, Hazardous Material Handling, Disaster Response, Surveillance End User: Defense Agencies, Police Departments, Private Security Firms, Emergency Responders, Research Institutions |
| Companies Covered | Northrop Grumman Corporation, L3Harris Technologies Inc., iRobot Corporation, QinetiQ, Lockheed Martin Corporation, Thales Group, BAE Systems, Rheinmetall AG, Peraton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bomb Disposal Robot Market Trends and Innovations
Defense leasing and performance-based service contracts are compressing capital deployment cycles while bundling robot platforms with integrated communications and maintenance capabilities.
Digital twin technology is virtualizing pre-mission simulation environments for explosive ordnance disposal teams. Military counterterrorism units in Germany and South Korea are adopting these systems at accelerated procurement cycles. This capability is virtualizing training costs while compressing operator certification timelines for hazardous environment deployment.
The EU AI Act is mandating risk classification for autonomous decision-making in defense applications. Vendors must now document algorithmic transparency for threat classification systems under emerging certification standards. Semi-autonomous platform developers in European procurement channels are responding by segregating AI-driven navigation from lethal action authorization protocols.
Buyer concentration among national defense ministries is consolidating tender specifications around integrated service-life contracts. Traditional equipment-only vendors face displacement by L3Harris and QinetiQ offerings that bundle platforms with secure datalinks and predictive maintenance. This pattern is most visible in United States and German military modernization programs where total-cost-of-ownership metrics dominate source selection.
Bomb Disposal Robot Market Segmentation
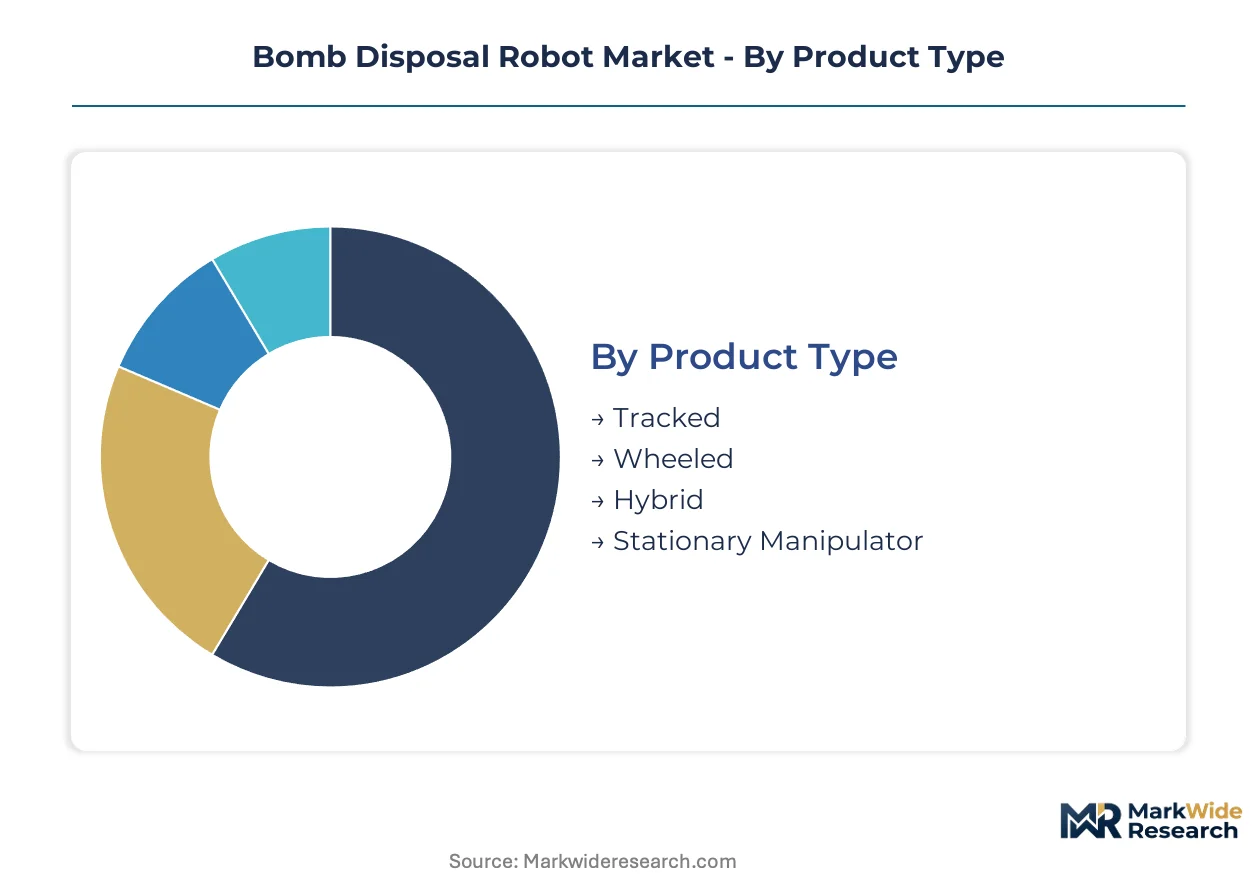
Segmentation in bomb disposal robotics reveals how mission profiles dictate platform specifications, with military counterterrorism units demanding blast-hardened tracked systems while police departments prioritize cost-effective wheeled alternatives for urban IED response.
Product Type:
Use-case spectrum spans battlefield ordnance disposal through fixed-site chemical threat neutralization, with mobility requirements and blast proximity tolerance determining chassis architecture selection.
- Tracked:Steel-reinforced continuous track systems distribute blast forces across wider ground contact surfaces, enabling traversal of urban rubble and off-road terrain. NATO military counterterrorism units in Germany and the United States concentrate procurement here, driven by requirements for hardened electronics survival at close detonation ranges.
- Wheeled:Configurations deploy rubber or composite tires on independent suspension for rapid urban deployment and lower acoustic signatures. Police departments in South Korea and municipal law enforcement across the United States favor these for budget-constrained IED response where blast proximity remains limited.
- Hybrid:Modular chassis accept both track and wheel attachments for mission-adaptive mobility. Defense agencies with varied terrain portfolios specify these for reduced fleet complexity.
- Stationary Manipulator:Fixed-base articulated arms handle chemical threat neutralization in controlled facility environments. Research institutions and hazardous material handling facilities deploy these where platform mobility is unnecessary.
The dominant share belongs to Tracked configurations, while Hybrid systems are closing the gap fastest as procurement officers seek fleet consolidation.
Technology:
Cost tier stratification separates premium autonomous navigation stacks from volume remote control foundations, with semi-autonomous platforms capturing mid-tier defense budgets.
- Autonomous Navigation:SLAM-based positioning with LIDAR obstacle mapping enables operator-reduced traversal of GPS-denied environments. South Korean defense modernization programs and German military counterterrorism units drive specification of these capabilities under emerging EU AI Act risk classification mandates.
- Remote Control:Tethered or radio-frequency manual operation persists as the volume foundation across police departments with constrained capital budgets. These systems limit cognitive load reduction but satisfy FAA airlift compatibility requirements with minimal certification complexity.
- Semi-Autonomous:Human-supervised waypoint navigation with operator override retains lethal action authorization while automating transit phases. This tier captures procurement officers balancing capability advancement with certification timeline pressure.
- Artificial Intelligence:Algorithmic threat classification from multi-sensor fusion accelerates identification of IED trigger mechanisms. Vendors redirect R&D budgets here as NATO agencies mandate faster response with reduced operator stress.
- Machine Vision:Real-time video analytics for object recognition and manipulator guidance integrate with articulated arm precision. Chemical threat neutralization applications beyond traditional explosive ordnance disposal are expanding demand for this segment.
Autonomous Navigation commands the premium tier, though Machine Vision is expanding most quickly as software-defined capabilities displace hardware-centric platform differentiation.
Application:
Customer maturity varies from established military protocols through emerging disaster response frameworks, with certification standards and procurement cycles determining vendor access.
- Military Counterterrorism:Blast-proximity operations in hostile territory demand hardened electronic architectures and secure datalinks. This segment anchors revenue concentration for tracked platform specialists serving NATO member states.
- Law Enforcement:Urban IED response and suspicious package handling operate under stricter rules of engagement with civilian proximity constraints. NHTSA collision-avoidance protocols increasingly shape semi-autonomous platform specifications for domestic deployment.
- Hazardous Material Handling:Chemical, biological, and radiological threat neutralization requires specialized manipulator end-effectors and sealed electronics enclosures. Research institutions and industrial facilities drive niche demand here.
- Disaster Response:Post-blast structural collapse and secondary device search utilize robotic platforms for human safety preservation. Emergency responder procurement remains fragmented across national and municipal funding streams.
- Surveillance:Persistent observation and reconnaissance missions leverage robotic mobility with reduced thermal and acoustic signatures. Private security firms and certain defense applications specify these for perimeter monitoring.
Military Counterterrorism retains the dominant procurement volume, while Hazardous Material Handling is gaining share fastest as chemical threat scenarios expand platform utility beyond explosive ordnance.
End User:
Procurement authority concentration shapes tender specifications, with defense ministries consolidating integrated service-life contracts and police departments fragmenting across municipal acquisition processes.
- Defense Agencies:National ministries with sovereign security clearance protocols specify platforms with secure datalinks and predictive maintenance bundles. Total-cost-of-ownership metrics dominate source selection in United States and German modernization programs.
- Police Departments:Municipal and national law enforcement with constrained budgets persist with remote control volume foundations. These buyers prioritize FAA airlift compatibility and rapid deployment logistics over autonomous capability advancement.
- Private Security Firms:Commercial entities protecting critical infrastructure operate under less stringent certification requirements but face insurance liability pressure for operator safety.
- Emergency Responders:Fire departments and specialized rescue units adopt platforms for disaster response scenarios with fragmented funding and training timeline constraints.
- Research Institutions:Universities and government laboratories acquire platforms for algorithm development and operator training virtualization through digital twin environments.
Defense Agencies command the dominant procurement value, though Research Institutions are climbing the fastest as digital twin adoption virtualizes training costs and compresses certification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in bomb disposal robotics favor technology-exporting nations with established defense industrial bases. The United States maintains a structural surplus in autonomous navigation systems and secure datalink technologies. Import-dependent markets in South Korea and Eastern Europe accelerate domestic production investments to circumvent technology transfer restrictions.
United States
Pentagon modernization programs drive procurement for tracked platforms with hardened electronics. FAA airlift compatibility guidelines shape unmanned ground vehicle certification requirements for rapid deployment logistics. Defense contractors cluster around Washington D.C.-Maryland-Virginia corridor, where secure facility clearances concentrate blast-hardened system design expertise.
Germany
Bundeswehr counterterrorism units specify autonomous navigation capabilities under emerging EU AI Act risk classification mandates. KBA vehicle safety protocols intersect with defense procurement standards for semi-autonomous platform deployment. Bavaria anchors European production through tracked platform specialists serving NATO tender specifications.
South Korea
Defense Agency for Technology and Quality explosive ordnance disposal capability prioritization creates procurement acceleration. MFDS medical device safety frameworks indirectly influence sealed electronics enclosure standards for hazardous material applications. Seoul Capital Area concentrates system integrators developing FAA-compatible airlift designs for export markets.
United Kingdom
Ministry of Defence performance-based service contracts compress capital deployment cycles toward integrated platform-datalink bundles. UK export control regulations under the Wassenaar Arrangement restrict technology transfer to non-NATO partners. QinetiQ and BAE Systems operations in Hampshire and Lancashire exemplify autonomous software development clustering.
Israel
Israel Defense Forces combat engineering corps demand blast-proximity electronics survival in hostile territory operations. National security clearance protocols fragment secure datalink certification timelines for multinational tenders. Tel Aviv metropolitan area concentrates machine vision algorithm developers serving dual-use defense-civilian applications.
Bomb Disposal Robot Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hardened electronics, manipulator arms, and navigation sensors. The vendor base stratifies across three tiers: full-spectrum defense primes bundling platforms with communications and maintenance; mid-tier autonomy software houses licensing navigation stacks; and specialized fabricators of blast-hardened chassis and articulated arms. Consolidation pressure intensifies as defense ministries consolidate tender specifications around integrated service-life contracts. Strategic moves center on M&A for autonomous navigation capabilities and partnerships for secure datalink certification acceleration.
Within the defense prime tier, Northrop Grumman Corporation and L3Harris Technologies Inc. exemplify platform-communications bundling strategies. QinetiQ occupies a distinct position as a UK-based autonomy software specialist with sustained investment in hazardous environment navigation. Rheinmetall AG anchors European tracked platform production through German manufacturing concentration. Lockheed Martin Corporation represents scale-driven system integration with cross-program electronics hardening expertise.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| L3Harris Technologies Inc. |
| iRobot Corporation |
| QinetiQ |
| Lockheed Martin Corporation |
| Thales Group |
| BAE Systems |
| Rheinmetall AG |
| Peraton |
| Others |
Pricing and Supply Chain Analysis
Steel alloy foundries in Germany and blast-hardened electronics fabricators in the United States concentrate upstream supply, anchoring margin capture with tracked platform specialists while wheeled configurations compete on volume economics.
Pricing Analysis
Defense agencies anchor a three-tier pricing structure across premium, standard, and economy levels, with tracked platforms commanding premium positioning due to hardened electronic architectures and NATO certification requirements. Price differentiation rests on blast-proximity tolerance ratings and secure datalink integration depth. Cost compression in the wheeled segment is intensifying because police departments with constrained budgets prioritize FAA airlift compatibility over autonomous capability advancement. Municipal law enforcement exhibits highest price sensitivity; military counterterrorism units demonstrate lowest sensitivity due to total-cost-of-ownership procurement metrics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for rare-earth magnet components and LIDAR sensor modules. Manufacturing concentrates in Germany for tracked chassis fabrication, South Korea for autonomous navigation software development, and the United States for secure communications integration. Raw material dependencies include specialized steel alloys for blast-hardened enclosures, high-temperature electronics substrates, and precision-machined manipulator arm components. Single-source vulnerability persists for SLAM-based positioning chipsets. Distribution runs through defense prime direct contracting channels and government procurement portals for law enforcement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors possessing hardened electronics design expertise and secure facility clearances, with talent scarcity in blast-proximity system architecture constraining competitive entry.
For Market Incumbents: Insulate platform-communications bundling advantages by deepening in-house production of autonomous navigation software stacks and accelerating secure datalink certification timelines. Emerging autonomy software houses threaten displacement of hardware-centric vendors. Certification investment in EU AI Act risk classification protocols represents the priority defensive lever. For New Entrants and Emerging Players: South Korean defense modernization programs present underpenetration opportunity for vendors with FAA-compatible airlift designs and machine vision-manipulator integration capabilities. Disaster response procurement fragmentation offers secondary white-space access. Research institution partnerships for digital twin training virtualization provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier autonomy software specialists holding hazardous environment navigation IP but lacking secure facility clearances for defense prime integration. Long-term viability favors vendors positioned for software-defined capability transitions rather than hardware volume plays. Algorithmic transparency documentation progress under emerging EU AI Act mandates serves as the critical inflection indicator for platform valuation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Software Acquisition | QinetiQ's sustained investment in hazardous environment SLAM-based positioning validates this capability as a differentiation anchor. |
| Secure Datalink Certification Acceleration | L3Harris leverages communications integration expertise to compress fragmented national security clearance timelines for NATO tenders. |
| Digital Twin Training Environment Development | German and South Korean military counterterrorism units adopt virtualized pre-mission simulation for compressed operator certification. |
| Machine Vision-Manipulator Integration | Chemical threat neutralization applications beyond traditional IED disposal expand platform utility into hazardous material handling. |
| Performance-Based Service Contract Bundling | UK Ministry of Defence procurement patterns demonstrate integrated platform-datalink-maintenance contracts displacing equipment-only vendors. |
Research Methodology
The analysis maps tracked platform specifications, autonomous navigation software stacks, and secure datalink integration tiers, each validated through explosive ordnance disposal unit commanders, defense procurement officers, and blast-hardened electronics design engineers. Primary interviews with NATO military counterterrorism specialists, municipal police department equipment managers, and hazardous material handling facility directors combine with secondary validation from FAA airlift compatibility guidelines, EU AI Act risk classification documentation, and Wassenaar Arrangement dual-use export control filings. Bottom-up segment sizing and top-down defense budget allocation triangulation anchor volume estimates.
Assumption sets held defense modernization program continuity and EU AI Act implementation trajectory fixed while varying machine vision adoption rates and police department budget allocation patterns across the projection horizon. Segmentation dimensions modeled include mobility architecture, technology tier, application mission profile, and end-user procurement authority concentration. CAGRs derive from segment-level growth rate reconciliation against aggregate defense spending trends. Industry-specific forecast inputs incorporate NATO tender specification evolution and NHTSA collision-avoidance protocol convergence timelines.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocation priorities or rare-earth magnet commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline compression and sovereign content requirement evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Drone Jamming System Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market