
 Unmanned Surface Vehicle (USV)S Market | 2026-2036
Unmanned Surface Vehicle (USV)S Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Surface Vehicle (USV)S Market Analysis
The gap between military-grade autonomy stacks and commercial-off-the-shelf maritime software is narrowing, forcing original equipment manufacturers to consolidate sensor fusion and edge computing architectures into unified hull designs. Kongsberg Gruppen leverages its Nordic naval heritage to dominate autonomous navigation subsystems for defense customers. Textron Systems anchors its position through manufacturing scale across multiple hull form factors. Saildrone competes in the environmental monitoring niche with persistent-ocean-survey platforms.
An unmanned surface vehicle is a self-propelled watercraft operating without embarked human operators, typically measuring 2-16 meters in length and integrating GPS navigation, sonar systems, and RF communication links for waypoint execution and remote command. The primary purpose spans mine countermeasures, hydrographic survey, maritime domain awareness, and persistent oceanographic data collection. Autonomous platforms lead the type segmentation due to reduced satellite bandwidth costs and improved collision-avoidance algorithms. Defense Operations commands the application dimension with sustained funding for anti-submarine warfare and port security missions. Military end users concentrate procurement through multi-year program-of-record contracts.
The U.S. Navy's Unmanned Campaign Framework and the International Maritime Organization's draft MASS Code are shaping hull certification standards and liability protocols for beyond-visual-line-of-sight operations. The U.S. Coast Guard's port access rules and the U.K. Maritime and Coastguard Agency's autonomous vessel trial permits are creating divergent compliance pathways that vendors must navigate simultaneously. Stakeholders must monitor which regulatory jurisdiction achieves protocol harmonization first, as this will determine the dominant export certification standard for international sales.
Market Dynamics
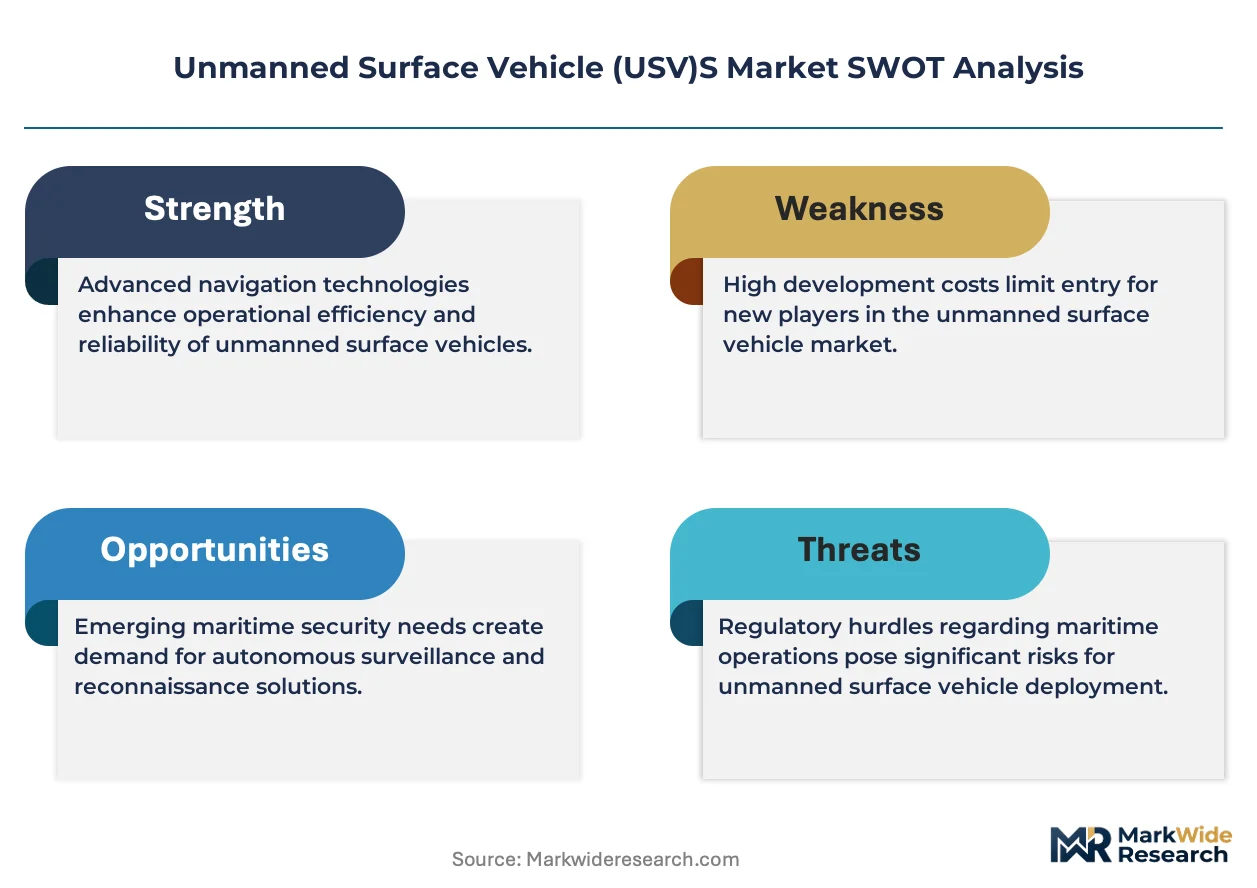
The collision-avoidance algorithm race is compressing development cycles across autonomous hull platforms, forcing subsystem vendors to integrate sensor fusion and edge computing into unified architectures or exit defense procurement channels entirely.
Growth Catalysts
- MASS Code Development:The International Maritime Organization's draft MASS Code is creating liability clarity for beyond-visual-line-of-sight operations, accelerating insurer willingness to underwrite autonomous vessel deployments in commercial channels.
- Naval Mine Countermeasures:Persistent demand for hull platforms capable of operating in contested littoral zones without risking crew safety is pulling autonomous systems into frontline defense procurement programs across multiple NATO member states.
- Edge Computing Maturation:Onboard processing architectures now enable real-time decision-making without continuous satellite uplink, reducing bandwidth costs and expanding operational envelopes for long-duration oceanographic missions.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cell production for maritime-grade energy storage clusters in East Asian manufacturing hubs, exposing hull integrators to input cost volatility and geopolitical supply disruption risks.
- Sensor Export Control Regimes:ITAR and dual-use technology classifications restrict transfer of military-grade sonar and radar components to non-allied end users, fragmenting addressable market geography.
- Autonomy Stack Certification Gaps:No harmonized international standard exists for validating artificial intelligence-driven navigation decisions, forcing redundant national certification processes that extend program timelines.
Strategic Opportunities
- Offshore Energy Inspection:Oil and gas platform operators in the North Sea are piloting persistent-hull monitoring to reduce helicopter crew transfer costs, creating a commercial beachhead outside defense contracting.
- Port Security Modernization:U.S. Coast Guard facility access rules are mandating enhanced underwater domain awareness, opening procurement pathways for autonomous surface and sub-surface platforms at commercial harbor installations.
- Synthetic Aperture Sonar Fusion:Convergence of high-resolution acoustic imaging with machine-learning target classification is enabling automated seabed survey workflows that displace crewed vessel operations.
Industry Challenges
- Maritime Autonomy Engineering Talent:The intersection of naval architecture, robotics, and ocean systems engineering produces a shallow labor pool, with defense contractors competing against commercial autonomous vehicle developers for the same specialized skill sets.
- Legacy Fleet Integration Complexity:Autonomous platforms must interoperate with existing command-and-control networks designed for crewed vessels, requiring middleware development that extends deployment timelines and inflates non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Surface Vehicle (USV)S Market |
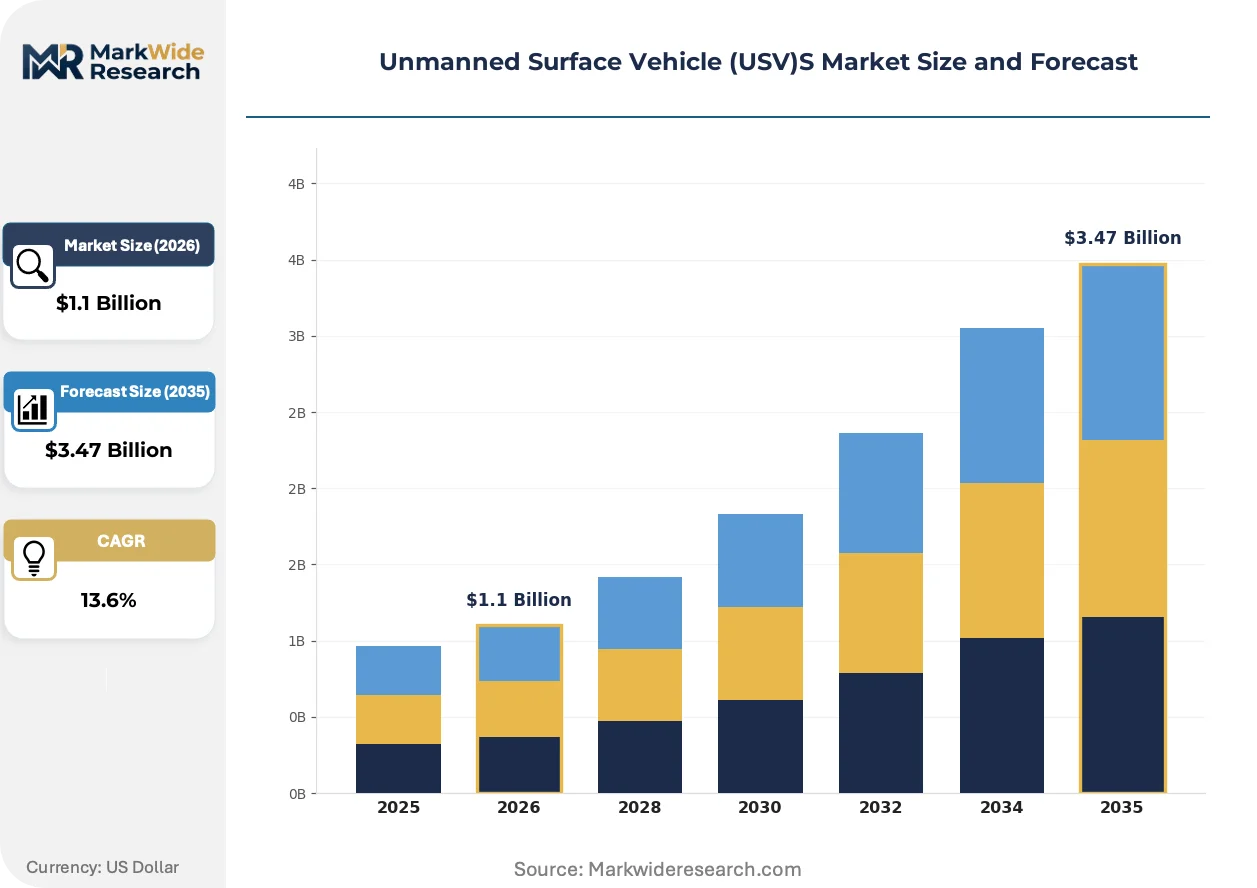
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Autonomous, Remotely Operated, Hybrid, Surface Drone Application: Marine Research, Surveillance, Environmental Monitoring, Defense Operations End User: Government, Research Institutions, Commercial, Military Technology: GPS Navigation, Sonar Systems, Communication Links, Navigation Sensors |
| Companies Covered | L3Harris Technologies, Kongsberg Gruppen, Textron Systems, Teledyne Technologies, Elbit Systems, ECA Group, Saildrone, Exail Technologies, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Surface Vehicle (USV)S Market Emerging Trajectories
Autonomous hull development is pivoting from remote-controlled platforms toward fully delegated decision-making architectures, compressing the boundary between military and commercial technology sourcing.
Sensor fusion middleware is hybridizing previously separate radar, lidar, and electro-optical processing streams into unified perception engines. Naval procurement offices are mandating these integrated stacks for new mine countermeasure programs. The technology is hybridizing vendor qualification requirements, as subsystem suppliers must now demonstrate cross-modal calibration capabilities to remain on approved source lists.
REACH chemical registration requirements in Europe are restricting certain antifouling coatings and battery electrolyte formulations used in autonomous hull construction. Manufacturers serving NATO defense customers are reformulating material specifications to maintain dual-use export eligibility. The regulatory pressure is most acute for battery-electric platforms targeting both military and environmental monitoring segments, where compliance documentation must satisfy divergent national regimes.
Defense buyers are consolidating vendor relationships around multi-year program-of-record contracts that bundle platform delivery with sustainment and software update services. Traditional spot-procurement of individual hull units is retreating to research and development phases. The contractual shift is most visible in U.S. Navy unmanned surface vehicle acquisitions, where prime contractors now capture lifecycle revenue streams previously distributed across maintenance networks.
Unmanned Surface Vehicle (USV)S Market Segmentation
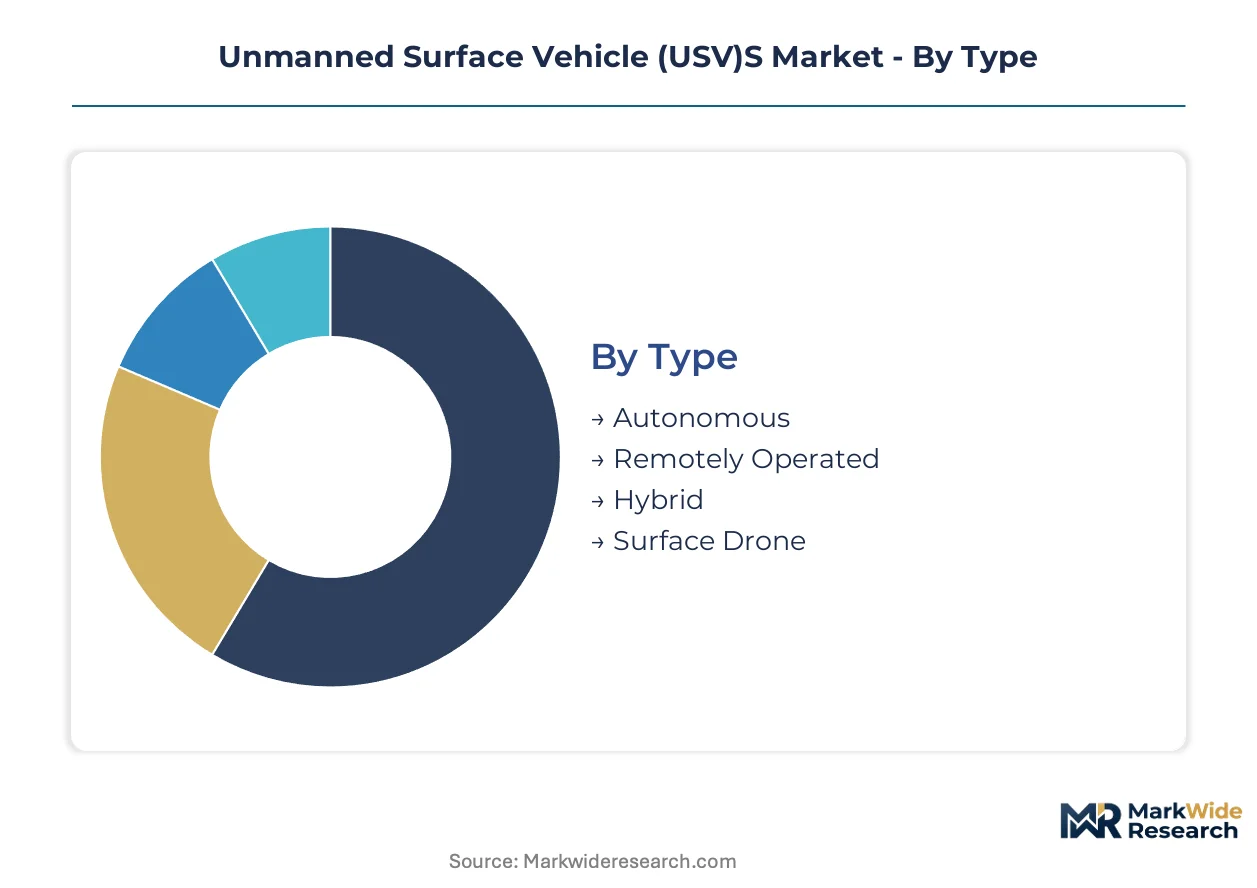
USV procurement cycles vary dramatically by autonomy level and end-use mission profile, creating divergent investment timelines across the technology stack. Defense programs lock in multi-year platform commitments while commercial environmental monitoring contracts refresh annually based on survey seasonality.
Type:
Autonomous platforms compress replacement cycles through continuous software updates, while remotely operated systems face hardware obsolescence pressures from satellite bandwidth cost inflation.
- Autonomous:Self-propelled hulls execute waypoint missions without continuous human oversight, integrating collision-avoidance algorithms and edge computing architectures. Norwegian naval programs and U.S. Navy mine countermeasure initiatives concentrate procurement here, driven by reduced satellite uplink dependency and crew risk elimination in contested littoral zones. Autonomous dominates installed base. Hybrid configurations are where expansion concentrates.
- Remotely Operated:Platforms maintain persistent RF or satellite tethering to shore-based operators for real-time command execution. Legacy port security installations and research institutions with limited autonomy expertise sustain demand, though bandwidth costs constrain operational envelopes for long-duration oceanographic missions.
- Hybrid:Systems switch between autonomous waypoint execution and remote override based on mission phase or threat environment. Oil and gas operators in the North Sea pilot these configurations for offshore platform inspection, balancing labor cost reduction with regulatory comfort for asset-proximity operations.
- Surface Drone:Compact hulls under 5 meters prioritize portability and rapid deployment over endurance or payload capacity. Academic research programs and coastal environmental monitoring contracts drive volume, with Kongsberg's Nordic cluster supplying perception subsystems to integrators targeting this tier.
Autonomous platforms dominate installed base. Hybrid configurations are where expansion concentrates.
Application:
Defense Operations command premium pricing through sovereign risk tolerance, while Environmental Monitoring competes on operational cost per nautical mile surveyed.
- Defense Operations:Mine countermeasures, anti-submarine warfare, and port security missions require hardened hulls with military-grade sensor suites. NATO procurement offices in the United States, United Kingdom, and Norway anchor demand through program-of-record contracts that bundle platform delivery with sustainment services.
- Environmental Monitoring:Persistent oceanographic data collection for climate research and fisheries management drives commercial adoption. Saildrone's California operations and Australian marine science institutions concentrate procurement here, with sensor payload modularity determining vendor selection.
- Surveillance:Maritime domain awareness missions span illegal fishing interdiction, smuggling detection, and exclusive economic zone patrol. Coast Guard organizations in the United States and Southeast Asian nations evaluate autonomous platforms against crewed cutter operating costs.
- Marine Research:Hydrographic survey and seabed mapping applications demand high-resolution sonar integration. University consortia and national oceanographic agencies issue shorter-cycle contracts, with synthetic aperture sonar fusion capabilities differentiating competitive bids.
Defense Operations commands the largest revenue pool. Environmental Monitoring is climbing the fastest as commercial beachheads mature.
End User:
Military procurement stretches development amortization across decade-long programs, while commercial users demand off-the-shelf availability with minimal customization.
- Military:Multi-year program-of-record contracts from U.S. Navy unmanned surface vehicle initiatives and U.K. Maritime and Coastguard Agency trials lock in prime contractor relationships. The contractual shift captures lifecycle revenue streams previously distributed across maintenance networks.
- Government:Non-defense agencies including environmental protection authorities and fisheries management bodies procure persistent monitoring platforms. Budget cycles align with fiscal year appropriations, creating procurement seasonality distinct from defense acquisition timelines.
- Research Institutions:University marine science programs and national oceanographic agencies prioritize sensor payload flexibility over hull endurance. Grant-funded acquisitions concentrate in the United States, Norway, and Australia, with equipment transferability between principal investigators influencing purchasing decisions.
- Commercial:Oil and gas operators, offshore wind developers, and port authorities evaluate autonomous platforms against helicopter crew transfer and crewed vessel charter costs. North Sea energy infrastructure inspection contracts represent the most visible commercial beachhead outside defense channels.
Military end users dominate committed backlog. Commercial adoption is gaining share fastest as energy sector pilot programs scale.
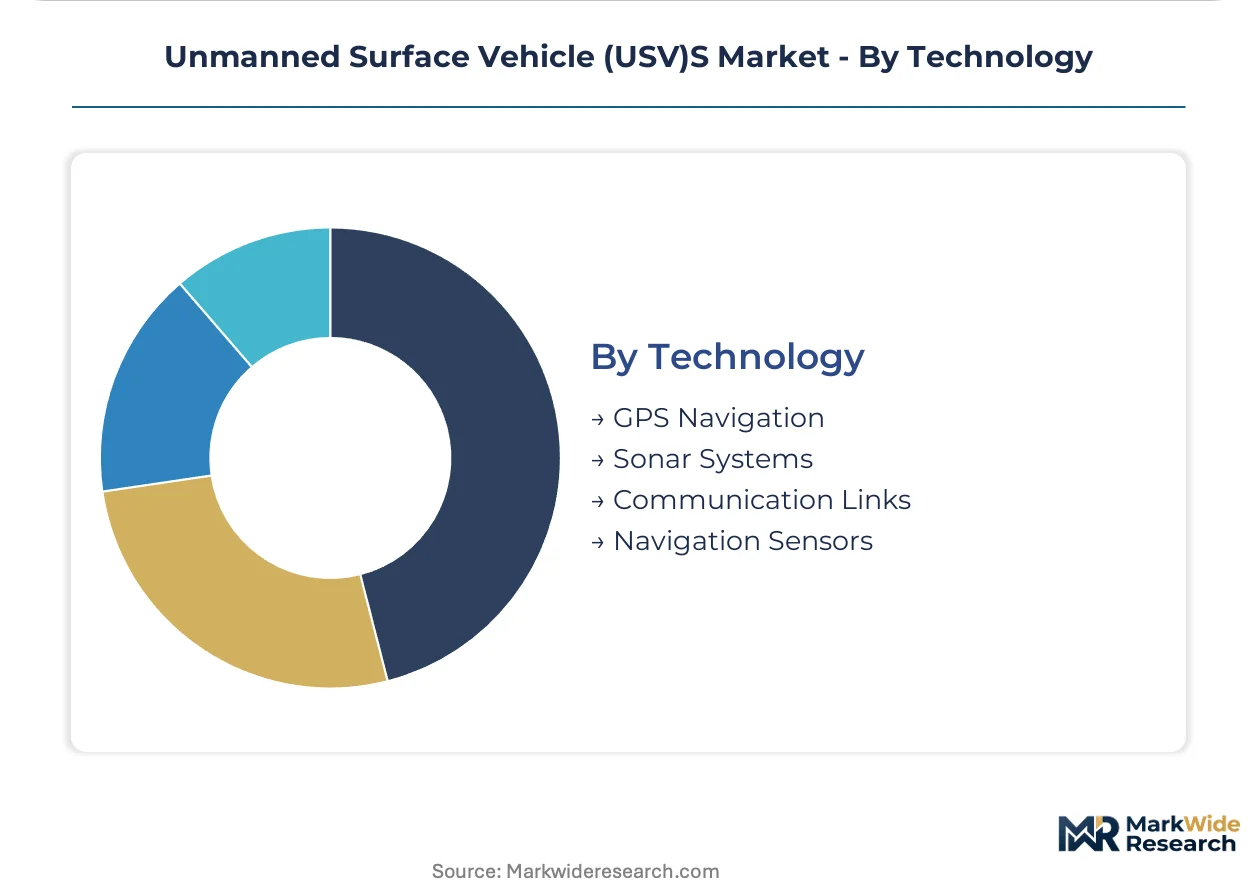
Technology:
Navigation sensor integration determines platform cost structure, with communication link architectures constraining operational geography based on satellite coverage.
- GPS Navigation:Satellite positioning systems enable waypoint execution and georeferenced data collection. Dual-frequency receiver integration has become standard for defense procurement, with jamming resilience now a mandatory specification for contested environment operations.
- Sonar Systems:Acoustic imaging for seabed mapping and obstacle detection spans multibeam bathymetry, side-scan, and synthetic aperture configurations. ITAR restrictions on military-grade components fragment supplier geography, with Norwegian and U.S. vendors dominating NATO-qualified sources.
- Communication Links:RF, satellite, and acoustic modem architectures determine command latency and operational range. Beyond-visual-line-of-sight deployments depend on Iridium or military satellite constellations, with bandwidth costs constraining real-time sensor data transmission for commercial applications.
- Navigation Sensors:Inertial measurement units, radar, lidar, and electro-optical systems feed sensor fusion engines for collision avoidance. Naval procurement offices now mandate integrated perception stacks rather than discrete subsystem procurement, compressing vendor qualification requirements.
Sonar Systems dominates platform bill-of-materials value. Navigation Sensors is where subsystem consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification requirements for autonomous hull platforms diverge sharply across procurement jurisdictions, forcing integrators to maintain parallel compliance documentation. The United States and Norway anchor defense procurement volumes, while commercial adoption clusters around North Sea energy infrastructure and Pacific fisheries monitoring programs.
United States
The U.S. Navy's Unmanned Campaign Framework drives program-of-record contracts for mine countermeasure and anti-submarine warfare platforms. Department of Defense autonomous vessel directives reshape contractor qualification standards annually. Textron Systems and L3Harris Technologies concentrate manufacturing operations across multiple hull form factors in southeastern defense corridors.
Norway
Kongsberg Gruppen leverages Nordic naval heritage to dominate autonomous navigation subsystem exports for NATO defense customers. The country's maritime technology cluster around Kongsberg R&D facilities concentrates sensor fusion expertise. Norwegian procurement offices prioritize reduced satellite bandwidth dependency in contested littoral specifications.
United Kingdom
The Maritime and Coastguard Agency's autonomous vessel trial permits create compliance pathways distinct from U.S. frameworks. U.K. defense procurement concentrates on hybrid autonomy configurations for port security modernization. Industrial activity clusters around Portsmouth naval infrastructure and Scottish marine research institutions.
France
ECA Group and Exail Technologies anchor domestic unmanned platform integration for mine warfare applications. French naval procurement emphasizes synthetic aperture sonar fusion for seabed survey automation. The Brittany maritime industrial base supplies acoustic imaging subsystems to Mediterranean and Atlantic defense programs.
Australia
The national oceanographic agency and university marine science programs drive environmental monitoring procurement for persistent oceanographic data collection. Australian fisheries management bodies evaluate autonomous platforms against crewed vessel operating costs for exclusive economic zone patrol. Sydney and Perth harbor technology clusters concentrate integration expertise for Asia-Pacific export markets.
Unmanned Surface Vehicle (USV)S Market Vendor Landscape
On the supply side, the industry is consolidating around multi-year program-of-record contracts that bundle platform delivery with lifecycle sustainment services. Tiered vendor qualification requirements separate prime contractors capable of integrated hull-sensor-software delivery from subsystem specialists. Defense heritage conglomerates and maritime technology pure-plays represent the dominant strategic archetypes. Competitive positioning depends on capturing defense procurement channel access through national security clearance infrastructure and achieving export certification under divergent NATO regulatory regimes.
Within the defense heritage tier, L3Harris Technologies and Kongsberg Gruppen exemplify contrasting geographic anchoring strategies for autonomous navigation subsystem dominance. Saildrone occupies a distinct position among California-based environmental monitoring specialists, competing on persistent-ocean-survey platform endurance rather than military specification compliance. Textron Systems represents the diversified conglomerate archetype, leveraging manufacturing scale across multiple hull form factors to capture U.S. Navy procurement volume. Thales Group and Elbit Systems sit within European and Israeli defense electronics traditions respectively, supplying sensor fusion middleware to prime contractors lacking in-house perception stack development.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Kongsberg Gruppen |
| Textron Systems |
| Teledyne Technologies |
| Elbit Systems |
| ECA Group |
| Saildrone |
| Exail Technologies |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cell manufacturing concentration in South Korean and Japanese production hubs directly determines margin capture downstream, with hull integrators facing input cost volatility that compresses platform pricing flexibility and forces tiered sourcing strategies.
Pricing Analysis
Military end users anchor platform pricing through multi-year program-of-record contracts that bundle hardware delivery with lifecycle sustainment services. Three-tier pricing structure across expeditionary-grade, standard-military, and research-configured hulls reflects certification burden and sensor payload integration complexity. Pricing pressure stems from commercial environmental monitoring contracts competing on operational cost per nautical mile, forcing defense contractors to demonstrate crewed-vessel cost displacement. Research institutions exhibit highest price sensitivity due to grant-funded acquisition cycles, while NATO defense procurement offices prioritize mission assurance over unit economics.
Supply Chain Analysis
Tariff exposure between United States and Chinese technology suppliers dominates supply chain risk assessment for navigation sensor and communication link components. Sonar system production concentrates in Norway, France, and the United States, with ITAR restrictions fragmenting qualified supplier geography for NATO defense programs. Hull fabrication draws from aluminum alloy suppliers in the United States and composite material specialists in Northern Europe. Single-source vulnerability in military-grade satellite communication modules creates procurement bottlenecks for beyond-visual-line-of-sight deployments. Distribution runs through prime contractor direct sales for defense channels and systems integrator partnerships for commercial offshore energy applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crewed vessel retrofits and leased autonomous services pose substitution threats that incumbent platform OEMs must navigate through demonstrated cost displacement and operational reliability.
For Market Incumbents: Harden program-of-record relationships by embedding software update subscriptions into multi-year contracts, capturing lifecycle revenue streams that leased-service competitors cannot replicate. Deepen backward integration into sensor fusion middleware development to reduce dependency on Thales Group and Elbit Systems for perception stack components. Prioritize NATO export certification harmonization to outpace U.K. Maritime and Coastguard Agency autonomous vessel trial frameworks that favor domestic integrators. For New Entrants and Emerging Players: Pursue commercial beachheads in North Sea offshore wind foundation inspection, where helicopter crew transfer cost displacement creates immediate value propositions without military specification compliance burdens. Target Australian fisheries management procurement cycles that evaluate autonomous platforms against crewed vessel operating costs for exclusive economic zone patrol. Position through sensor payload modularity rather than hull endurance, aligning with university marine science program grant funding constraints. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier hull integrators with established U.S. Navy or Royal Navy program access and in-house navigation sensor calibration capabilities. Long-term viability rests on capturing defense procurement channel positions before commercial environmental monitoring segments saturate. Monitor U.S. Coast Guard port security modernization funding authorizations as the critical inflection signal for commercial harbor installation demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Middleware Development | Reduces prime contractor dependency on Thales and Elbit perception subsystem supply. |
| NATO Export Certification Harmonization | Unlocks cross-border program-of-record contract eligibility for Norwegian and U.S. hull integrators. |
| Software Subscription Embedding | Captures recurring revenue streams from military sustainment budgets previously distributed across maintenance networks. |
| Offshore Energy Pilot Program Scaling | Validates persistent-hull monitoring value proposition against helicopter crew transfer costs in North Sea operations. |
| Synthetic Aperture Sonar Integration | Enables automated seabed survey workflows that displace crewed hydrographic vessel charter contracts. |
Methodological Framework
Operator-level perspectives from U.S. Navy program office directors, Kongsberg Gruppen autonomy engineers, Textron Systems manufacturing leads, and North Sea offshore energy operators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through U.S. Department of Defense unmanned vessel directive filings, International Maritime Organization MASS Code development documents, NATO procurement announcement databases, and SEC 10-K disclosures from listed defense conglomerates. Bottom-up platform delivery forecasts triangulated against top-down naval modernization budget appropriations across the analysis window.
Scenario-bracketing around autonomy stack certification timelines and lithium-ion supply disruption probabilities framed the analytical approach. Segmentation modeling spanned hull autonomy level, defense versus commercial end-use, sensor payload tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and program-of-record contract award trajectories. Forecast inputs incorporated satellite bandwidth cost inflation curves and synthetic aperture sonar target classification accuracy improvements.
Sensitivities concentrate around International Maritime Organization MASS Code ratification delays and U.S. Department of Defense autonomous vessel directive revisions that reshape contractor qualification standards. Forecasts reflect documented assumptions regarding NATO defense procurement continuity and commercial offshore energy pilot program conversion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Bomb Disposal Robot Market