
 Unattended Ground Sensors (UGS) Market | 2026-2036
Unattended Ground Sensors (UGS) Market Size, Share, and Industry Trends Forecast 2026-2036
Unattended Ground Sensors (UGS) Market Analytics
Border security applications is broadening as a revenue vertical for UGS manufacturers, complementing traditional military demand. Northrop Grumman Corporation leverages its signal processing heritage to dominate classified defense programs. L3Harris Technologies anchors its position through integrated communications-sensor architectures. Elbit Systems Ltd. specializes in ruggedized, miniaturized packages suited for extended field operations in contested environments.
Unattended Ground Sensors are self-contained, battery or solar-powered detection devices that incorporate seismic, acoustic, magnetic, or thermal transducers to identify personnel, vehicles, or wildlife movement across remote perimeters without human operator presence. These systems typically operate at power budgets below five watts, enabling months-long autonomous deployment through energy harvesting and duty-cycled wake-up circuits. Seismic sensors command the largest installed base due to their proven performance in discriminating foot traffic from environmental clutter, though acoustic sensors are gaining traction where multi-target classification matters. Wireless technology configurations are expanding fastest as mesh networking protocols reduce cabling costs and enable rapid emplacement, while wired systems retain preference in fixed infrastructure security where electromagnetic interference poses risks.
The U.S. Department of Defense mandates MIL-STD-810 environmental qualification and NSA Suite B encryption for fielded UGS, while the EU AI Act and GDPR impose constraints on automated target recognition algorithms deployed in European border zones. FCC spectrum allocations in the United States and CE marking requirements under the EU Radio Equipment Directive shape permissible transmission frequencies and power levels, directly limiting product architectures for cross-border vendors. Stakeholders must monitor evolving cryptographic standards and export control classifications, as these determine which sensor-fusion capabilities can be deployed in allied versus restricted foreign markets.
Market Dynamics
The U.S. Department of Defense's distributed battlefield awareness mandate is compressing procurement cycles for low-power, multi-modal detection systems, forcing manufacturers to accelerate sensor fusion development while maintaining MIL-STD-810 environmental qualification.
Growth Catalysts
- Networked Perimeter Programs:Southwestern U.S. border agencies are expanding seismic-acoustic sensor fusion deployments, creating sustained demand for ruggedized, extended-field packages.
- FCC Spectrum Allocations:Permissible transmission frequencies for unlicensed mesh networking are expanding, enabling rapid emplacement without cabling infrastructure.
- Energy Harvesting Advances:Duty-cycled wake-up circuits and solar-battery hybrids now sustain sub-five-watt operation for months, reducing logistics burden in remote theaters.
Market Restraints
- Export Control Classifications:NSA Suite B encryption and sensor-fusion capabilities face ITAR restrictions, blocking deployment in restricted foreign markets regardless of commercial demand.
- Electromagnetic Interference Vulnerability:Wireless mesh configurations face jamming risks in contested electromagnetic environments, preserving wired system preference for fixed critical infrastructure.
- Lithium Supply Concentration:Battery chemistry dependence on concentrated upstream processing creates input cost volatility for autonomous field systems.
Strategic Opportunities
- EU Border Automation:GDPR-compliant automated target recognition algorithms for European perimeter zones remain underdeveloped, creating first-mover space for privacy-preserving edge processing.
- Wildlife Corridor Monitoring:Conservation agencies in sub-Saharan Africa and Southeast Asia seek seismic-thermal fusion for anti-poaching applications outside traditional defense channels.
- Dual-Use Certification Pathways:CE marking under the EU Radio Equipment Directive offers streamlined market access for vendors achieving simultaneous defense and civilian qualification.
Industry Challenges
- Multi-Physics Simulation Talent:Seismic-acoustic-magnetic sensor fusion requires scarce expertise in coupled-field modeling and edge algorithm optimization.
- NSA Cryptographic Transition Timelines:Post-quantum encryption mandates compress recertification windows for fielded products, forcing premature obsolescence of current-generation hardware.
- Legacy System Integration:Proprietary command protocols from 1990s-era wired installations resist standardization, fragmenting procurement for hybrid network upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unattended Ground Sensors (UGS) Market |
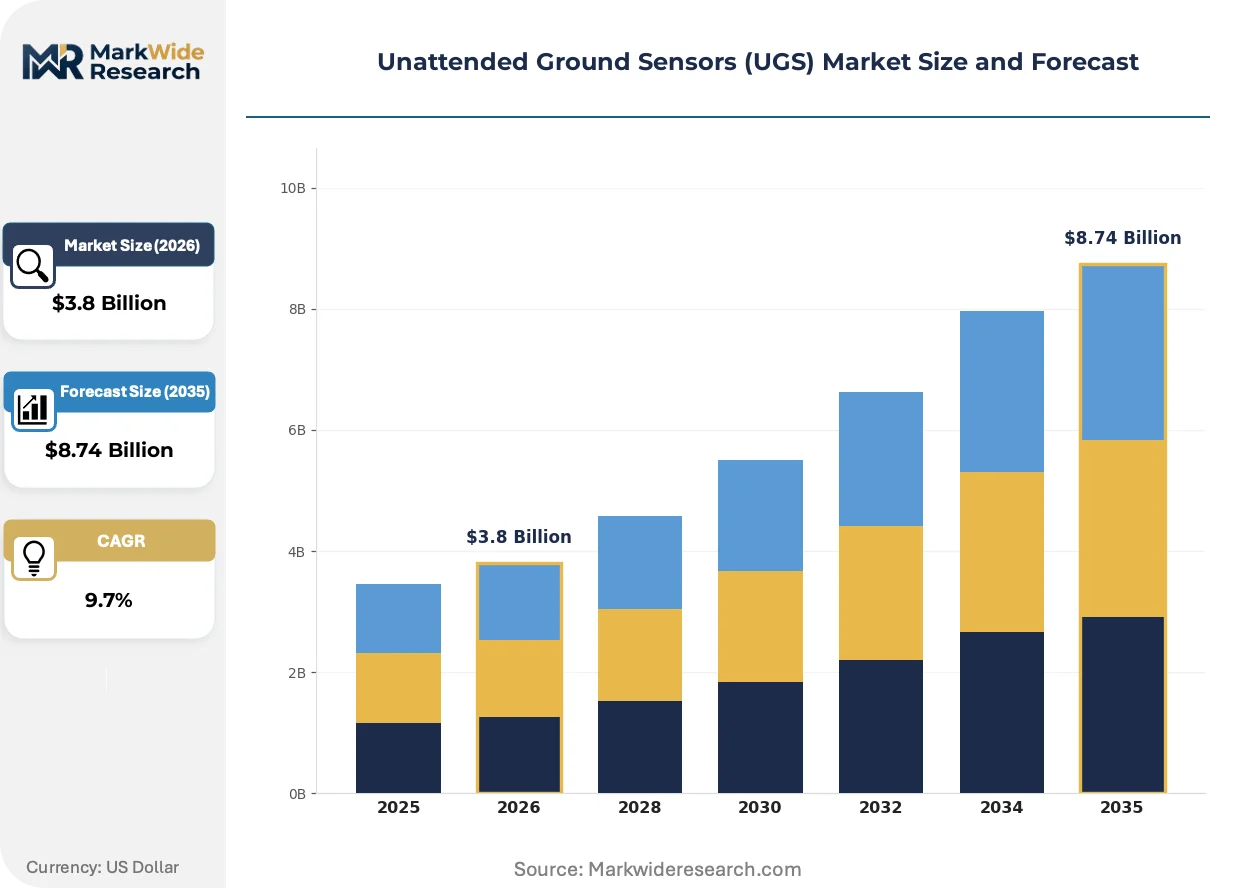
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seismic Sensors, Acoustic Sensors, Magnetic Sensors, Thermal Sensors Technology: Wireless, Wired, Solar-Powered, Battery-Operated Application: Military, Wildlife Monitoring, Infrastructure Security, Research End User: Defense Organizations, Environmental Agencies, Research Institutions, Private Security |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, L3Harris Technologies, Thales Group, Textron Systems, Raytheon Technologies Corporation, Elbit Systems Ltd., BAE Systems, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unattended Ground Sensors (UGS) Market Evolving Landscape
Active convergence between low-power edge computing and hardened environmental packaging is redefining acceptable performance thresholds for unattended deployment. Vendors now compete on wake-up latency and false-alarm discrimination rather than raw detection range.
Multi-modal sensor fusion is consolidating battlefield awareness architectures by collapsing separate seismic, acoustic, and thermal reporting chains into single-stream classification outputs. U.S. Army Rapid Capabilities and Critical Technologies Office procurement officers are prioritizing fused-source confidence scoring over single-modality sensitivity. This compression is eliminating standalone sensor vendors from classified program competitions.
The EU AI Act's risk classification framework for automated target recognition is forcing algorithm architecture redesigns for European border deployments. Systems must now maintain human-in-the-loop decision logging and bias audit trails, adding firmware complexity. French and German interior ministries are delaying full-network awards until compliance pathways clarify, creating procurement pauses distinct from North American timelines.
Defense procurement officers are unbundling sensor hardware from multi-year maintenance contracts, compressing vendor revenue recognition into front-loaded equipment sales. This shift pressures smaller manufacturers to establish regional service partnerships or sacrifice margin to prime integrators. The pattern is most visible in U.S. Customs and Border Protection networked array awards, where five-year sustainment obligations now route through separate logistics contracts.
Unattended Ground Sensors (UGS) Market Segmentation
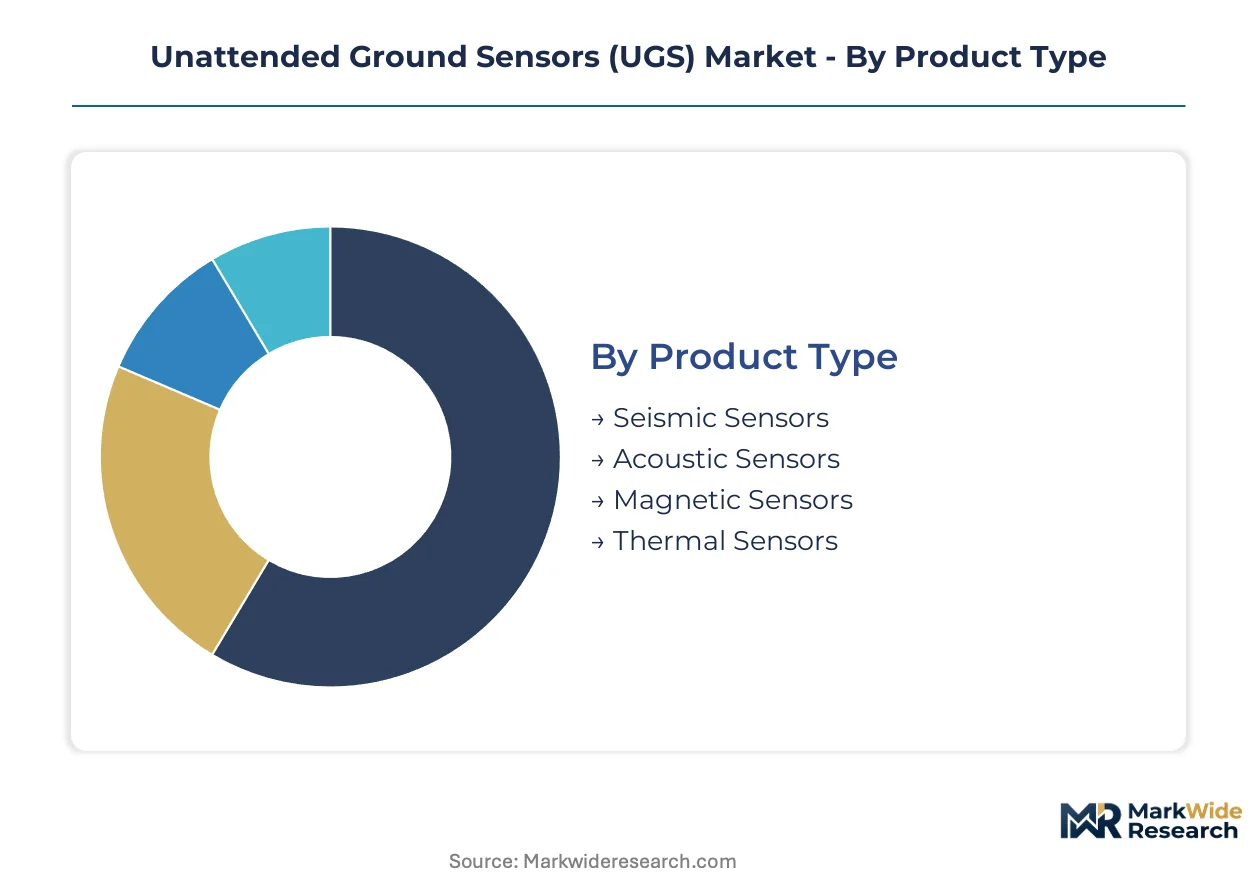
Procurement officers select UGS configurations based on power autonomy, detection modality, and network topology. Segment boundaries blur as multi-modal fusion packages displace single-sensor deployments across defense and civilian channels.
Product Type:
Detection modality determines environmental discrimination capability and false-alarm susceptibility.
- Seismic Sensors:Geophone arrays detect ground-borne vibrations from foot traffic and vehicle movement. U.S. Customs and Border Protection seismic-acoustic fusion networks in the southwestern United States sustain demand for ruggedized geophone packages with extended field endurance.
- Acoustic Sensors:Microphone clusters capture airborne signatures for multi-target classification. French and German interior ministries prioritize acoustic fusion where personnel-vehicle discrimination matters for GDPR-compliant border automation.
- Magnetic Sensors:Magnetometer nodes identify ferrous vehicle signatures with minimal power draw.
- Thermal Sensors:Infrared focal plane arrays detect heat signatures for wildlife corridor monitoring in sub-Saharan Africa.
Volume sits with Seismic Sensors; growth tilts toward Acoustic Sensors.
Technology:
Power and connectivity architecture shapes logistics burden and electromagnetic vulnerability.
- Wireless:Mesh radio protocols eliminate cabling infrastructure and enable rapid emplacement. FCC spectrum allocations for unlicensed bands in the United States accelerate procurement cycles for border surveillance arrays.
- Wired:Copper or fiber connections resist jamming in fixed critical infrastructure where electromagnetic interference poses unacceptable risks.
- Solar-Powered:Photovoltaic harvesting with duty-cycled wake circuits sustains sub-five-watt operation for months in remote theaters.
- Battery-Operated:Primary lithium cells deliver immediate deployment capability where solar insolation is unreliable.
Deployment flexibility favors Wireless; reliability requirements preserve Wired.
Application:
End-use context dictates environmental qualification levels and algorithm training data requirements.
- Military:MIL-STD-810 qualification and NSA Suite B encryption dominate procurement specifications. The U.S. Department of Defense distributed battlefield awareness mandate compresses delivery timelines for fused-source confidence scoring.
- Wildlife Monitoring:Conservation agencies in Southeast Asia seek seismic-thermal fusion for anti-poaching applications outside traditional defense channels.
- Infrastructure Security:Fixed perimeter protection for energy and transportation assets favors wired configurations with minimal maintenance windows.
- Research:Academic field studies drive demand for open-interface sensor nodes with configurable sampling protocols.
Revenue concentrates in Military; expansion accelerates in Wildlife Monitoring.
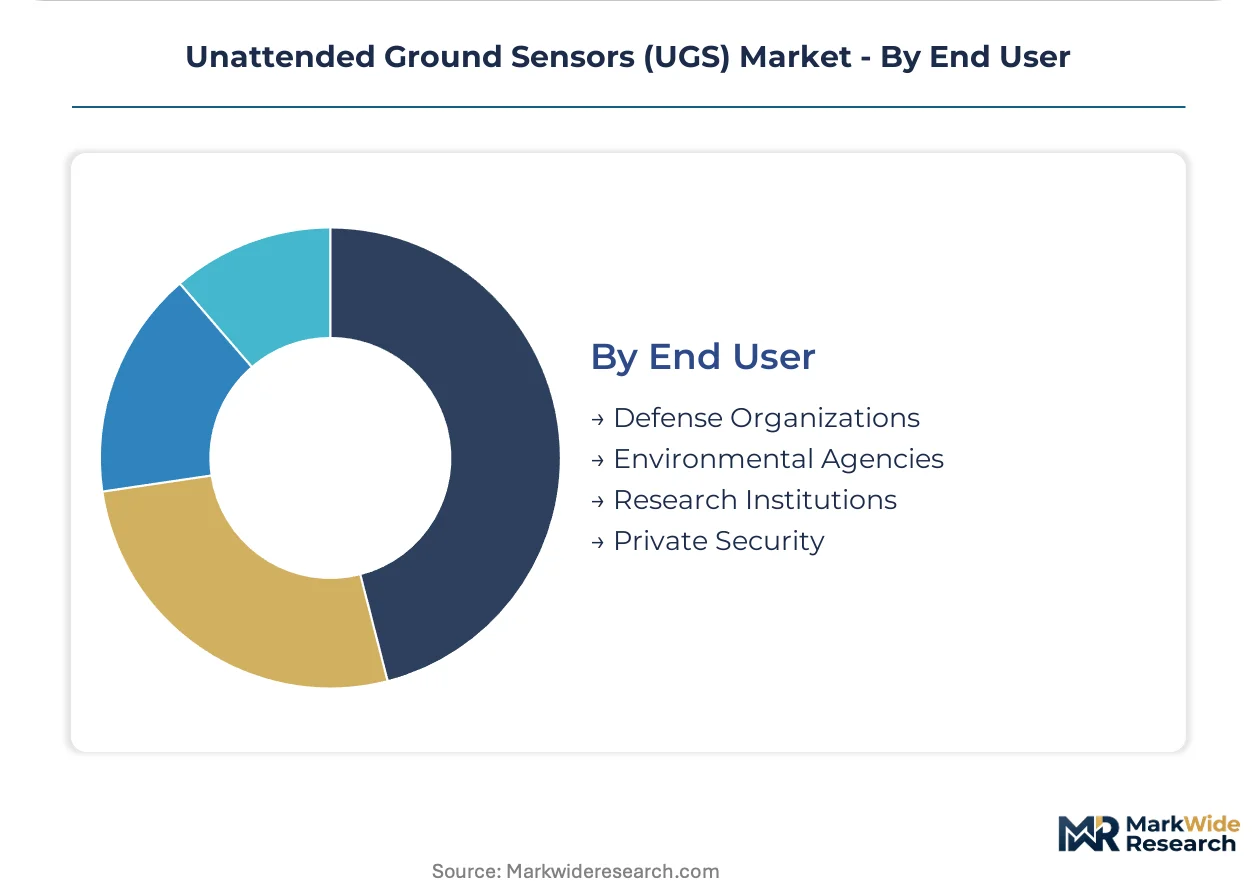
End User:
Budget authority and procurement regulations fragment demand across classified programs, civilian agencies, and commercial contracts.
- Defense Organizations:Classified program offices mandate integrated communications-sensor architectures with multi-year sustainment obligations now unbundled from hardware awards.
- Environmental Agencies:National park services and wildlife departments prioritize cost efficiency and non-proprietary data formats for ecosystem monitoring.
- Research Institutions:Universities require modular platforms supporting algorithm development and publication-grade datasets.
- Private Security:Mining and energy operators seek turnkey perimeter packages with minimal technical integration burden.
Contract value peaks with Defense Organizations; procurement velocity rises in Private Security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement corridors and border security special economic zones concentrate UGS manufacturing and deployment activity across four national markets. Each jurisdiction imposes distinct environmental qualification and encryption standards that reshape vendor compliance burdens.
United States
Southwestern border agencies drive seismic-acoustic sensor fusion procurement through integrated perimeter defense programs. FCC spectrum allocations for unlicensed mesh networking accelerate deployment timelines while NSA Suite B encryption mandates filter vendor eligibility. Arizona and Texas host the primary integration clusters where CBP networked array awards route through separate logistics contracts.
Germany
Federal interior ministry procurement prioritizes acoustic fusion systems for personnel-vehicle discrimination at Schengen perimeter points. CE marking under the EU Radio Equipment Directive shapes permissible transmission frequencies, while GDPR constraints delay full-network awards pending algorithm compliance clarity. Bavaria's defense electronics corridor anchors continental integration capacity for ruggedized field packages.
Israel
Contested environment requirements drive demand for miniaturized, extended-field sensor architectures. The national defense establishment mandates proprietary encryption overlays that exceed commercial NATO standards. Tel Aviv's defense technology cluster specializes in low-power edge processing for autonomous deployment scenarios.
Australia
Wildlife corridor monitoring applications expand addressable demand beyond traditional defense channels, with conservation agencies seeking seismic-thermal fusion for anti-poaching programs. The Australian Signals Directorate imposes cryptographic standards that align with Five Eyes interoperability requirements. Queensland and Western Australia host the primary field deployment zones for remote perimeter monitoring.
United Kingdom
Border Force procurement emphasizes rapid emplacement capability for coastal and port perimeter applications. Ministry of Defence specifications require MIL-STD-810 qualification for fielded systems alongside UK-specific encryption certifications. The South East England defense electronics cluster manages integration for NATO interoperability programs.
Unattended Ground Sensors (UGS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with classified defense programs consolidating around vertically integrated primes while civilian border applications sustain mid-tier system integrators. The vendor base organizes into three strategic archetypes: aerospace primes with signal processing heritage, communications-focused integrators, and ruggedization specialists serving extended-field requirements. Dominant competitive moves include unbundling hardware from multi-year sustainment contracts and establishing regional service partnerships to capture logistics revenue.
Among North American primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the aerospace heritage archetype, occupying positions where classified program access and MIL-STD qualification capabilities create procurement barriers. L3Harris Technologies represents the communications-sensor integration vector, sitting within the tier where integrated architectures anchor border surveillance awards. Elbit Systems Ltd. occupies the ruggedization specialist position, with its corporate structure reflecting extended-field operational focus.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Thales Group |
| Textron Systems |
| Raytheon Technologies Corporation |
| Elbit Systems Ltd. |
| BAE Systems |
| Leonardo S.p.A. |
| Others |
Value Network & Pricing Analysis
U.S. Department of Defense program offices concentrate procurement authority for seismic-acoustic fusion networks, compressing vendor margins through unbundled hardware-sustainment contracts that eliminate multi-year service premiums.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations for MIL-STD-810 qualified sensor packages, with border surveillance agencies paying substantial markups for rapid deployment capability against standard-cycle inventory positions. Three-tier pricing structure across ruggedized military-grade, commercial-off-the-shelf, and research-configured levels reflects certification burden and encryption compliance rather than raw sensor performance. Cost compression in commercial-off-the-shelf tiers intensifies because lithium cell supply volatility feeds into battery module pricing. Private security operators exhibit highest price sensitivity, while classified defense programs prioritize performance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from prime integrators require qualified suppliers for geophone transducers, lithium primary cells, and hardened edge processors, fragmenting procurement across domestic and allied-country vendors. Manufacturing concentrates in the United States, Israel, and Germany for final assembly, while rare-earth magnet inputs draw from concentrated upstream processing in China. Single-source vulnerability persists for NSA Suite B cryptographic modules, where domestic foundry capacity constrains qualified component availability. Distribution runs through defense prime integrators and specialized system houses serving civilian border agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where NSA Suite B encryption mandates and MIL-STD-810 qualification requirements erect barrier-to-entry moats that protect incumbent positions against unqualified challengers.
For Market Incumbents: Extend qualification advantages by deepening backward integration into lithium cell packaging and geophone transducer manufacturing, securing supply continuity against raw material volatility. Accelerate post-quantum cryptographic module development ahead of NSA transition timelines to capture recertification-driven replacement cycles. Channel control through regional service partnerships preserves logistics revenue as procurement officers unbundle sustainment obligations. For New Entrants and Emerging Players: Conservation agencies in sub-Saharan Africa represent the most penetrable buyer archetype, with wildlife corridor monitoring demand outpacing qualified vendor supply for seismic-thermal fusion packages. GDPR-compliant edge processing for European border automation offers second white-space entry, where algorithm audit-trail capabilities remain underdeveloped. Direct field engineering partnerships with national park services bypass prime integrator margin extraction. For Investors and Strategic Acquirers: The window for entry favors ruggedization specialists with existing MIL-STD qualification infrastructure rather than de novo hardware ventures facing certification timelines. Multi-modal sensor fusion algorithm developers with privacy-preserving architectures command premium positioning as EU AI Act enforcement clarifies. Watch for NSA post-quantum cryptographic mandate publication as inflection signal triggering hardware refresh investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Module Development | NSA Suite B transition timelines compress recertification windows, rewarding early hardware refresh positioning. |
| Regional Service Partnership Establishment | Unbundled sustainment contracts route through separate logistics awards, capturing recurring revenue streams. |
| GDPR-Compliant Edge Processing Architecture | EU AI Act risk classification frameworks force algorithm redesigns, creating first-mover advantage in European border zones. |
| Dual-Use Certification Pathway Investment | CE marking under EU Radio Equipment Directive streamlines civilian market access for defense-qualified platforms. |
| Lithium Cell Packaging Backward Integration | Upstream supply concentration creates input cost volatility that captive production mitigates for autonomous field systems. |
Research Methodology
Multi-period observation of CBP networked array procurement awards, FCC spectrum allocation proceedings, and EU AI Act implementation timelines anchored the trend analysis, supplemented by interviews with defense procurement officers, border surveillance program managers, seismic sensor engineering leads, and conservation technology specialists. Secondary validation drew from Department of Defense budget justification documents, EU Official Journal procurement notices, and customs records for lithium cell and geophone trade flows. Bottom-up unit economics for sensor fusion packages triangulated against top-down defense electronics market sizing.
Input-output matrices mapped detection modality adoption rates, power architecture preferences, and network topology selections across military, wildlife monitoring, infrastructure security, and research end-use segments over the projection horizon. CAGRs derived from logistic diffusion curves fitted to procurement cycle data and technology substitution patterns. Forecast inputs incorporated duty-cycled wake-up circuit efficiency trajectories, mesh networking protocol penetration rates, and encryption standard transition schedules.
Revisions become necessary when NSA cryptographic mandate timelines accelerate, EU AI Act enforcement thresholds shift, or lithium supply chain disruptions alter battery cost structures materially. Forecasts reflect assumptions regarding sustained defense procurement prioritization for distributed battlefield awareness and continued border security investment in southwestern United States perimeter programs. A model refresh is warranted upon material change in FCC spectrum allocation rules affecting unlicensed mesh networking deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
High Altitude Platform Market