
 Global Commercial Avionics Systems Market | 2026-2036
Global Commercial Avionics Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Avionics Systems Market Intelligence
The DO-178C software certification standard is reorganizing the competitive landscape for avionics suppliers, raising the barrier to entry. Collins Aerospace leverages its extensive portfolio in flight management systems to meet these stringent requirements. Honeywell International Inc. differentiates through its integrated cockpit solutions and advanced, certified navigation systems. Meanwhile, Thales Group competes on its strength in air traffic management and communication technologies across global commercial platforms.
Commercial avionics systems comprise the electronic systems, including communication, navigation, and monitoring equipment, used on aircraft to perform in-flight functions. These systems process real-time flight data, often through digital signal processing, to ensure operational safety and flight path efficiency. Flight management systems represent a mature, high-value product category, while satellite-based communication and navigation technologies are experiencing the fastest adoption. Demand from commercial airlines for systems that enhance flight safety and air traffic control remains the primary application driver.
Regulatory oversight from bodies like the US Federal Aviation Administration (FAA) and European aviation authorities establishes mandatory performance and safety standards. These strict regulations, often aligned with International Civil Aviation Organization (ICAO) guidelines, govern the certification and deployment of all new avionics hardware and software. Suppliers must therefore decide whether to invest heavily in next-generation, software-defined architectures or focus on the large market for retrofitting the existing global fleet.
Market Dynamics
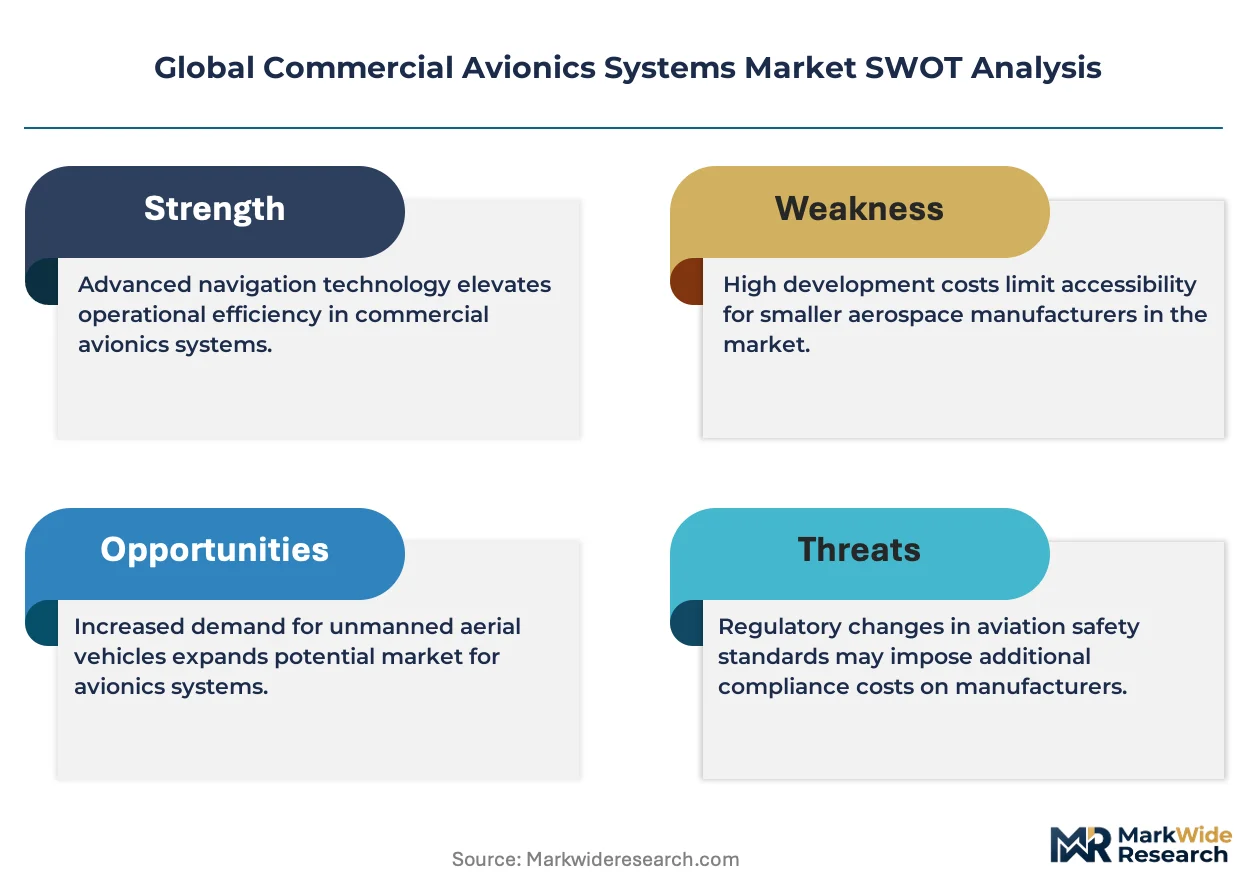
The central tension in the commercial avionics market is the bifurcation of demand. Next-generation aircraft programs require massive R&D for software-defined systems, while a vast global fleet of older aircraft necessitates a focus on cost-effective retrofits and upgrades.
Growth Catalysts
- Fleet Expansion:Modernization programs by commercial airlines in China and India create concentrated demand for complete cockpit-to-tail avionics suites on new narrow-body and wide-body aircraft.
- Air Traffic Modernization:Mandates for satellite-based navigation and communication systems, aligned with NextGen in the US and SESAR in Europe, compel fleet-wide upgrades for improved airspace efficiency.
- Enhanced Safety Systems:Demand for technologies like Enhanced Ground Proximity Warning Systems (EGPWS) and Traffic Collision Avoidance Systems (TCAS) remains strong for safety and insurance purposes.
Market Restraints
- Certification Costs:The extreme expense and long timelines associated with achieving DO-178C software certification for safety-critical systems create a high barrier to entry for new suppliers.
- Legacy System Integration:Integrating new digital avionics with the complex, often analog, wiring and systems of aging aircraft platforms presents significant technical and financial hurdles for operators.
- Specialized Components:A constrained supply chain for radiation-hardened semiconductors and other specialized electronic components creates vulnerability to shortages and price volatility for manufacturers.
Strategic Opportunities
- Data Analytics Services:Suppliers can develop new revenue streams by offering subscription-based services for flight data analysis, predictive maintenance, and fuel optimization derived from avionics data.
- Urban Air Mobility:The emerging market for electric vertical take-off and landing (eVTOL) aircraft requires a new class of lightweight, highly automated, and certifiable avionics systems.
- Cybersecurity Solutions:Growing connectivity of aircraft exposes them to cyber threats, creating an opportunity for specialized software and hardware solutions that secure avionics data links and networks.
Industry Challenges
- Software Engineering Talent:A persistent shortage of software engineers with verifiable experience in safety-critical standards like DO-178C slows down product development and certification timelines across the industry.
- System Interoperability:Ensuring seamless interoperability between avionics systems from different vendors on a single flight deck remains a significant integration challenge for both airframers and airlines.
- Obsolescence Management:The long service life of aircraft requires a proactive strategy for managing the obsolescence of electronic components and software within avionics systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Avionics Systems Market |
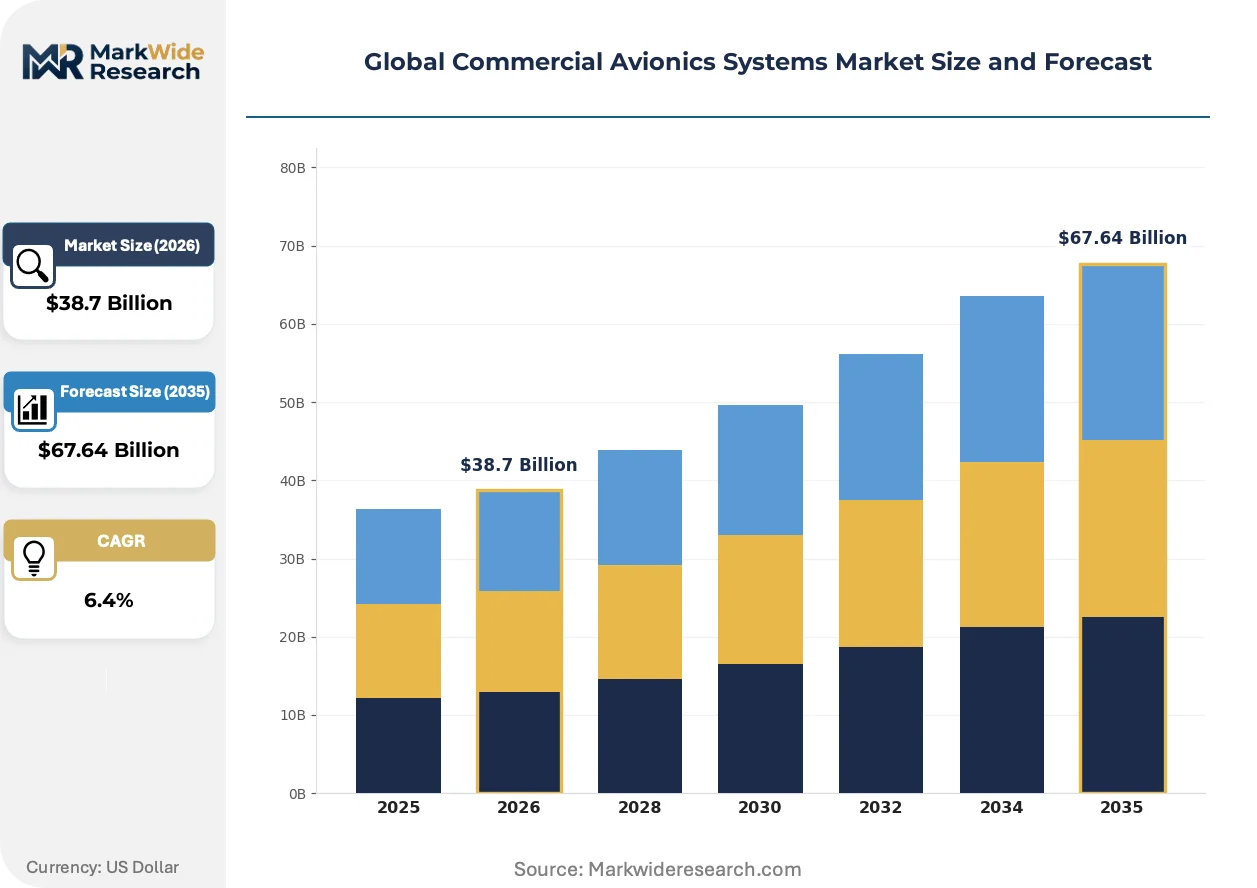
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Management Systems, Communication Systems, Navigation Systems, Monitoring Systems, Weather Radar Technology: Satellite-Based, Radar-Based, Fiber Optic, Wireless Data Link, Digital Signal Processing Application: Flight Safety, Air Traffic Control, Navigation Assistance, Weather Forecasting, Aircraft Maintenance End User: Commercial Airlines, Charter Operators, Cargo Carriers, Maintenance Providers, Training Institutions |
| Companies Covered | L3Harris Technologies, BAE Systems, Honeywell International Inc., Collins Aerospace, Safran Electronics & Defense, RTX Corporation, General Electric Aviation, Garmin Ltd., Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Avionics Systems Market Strategic Shifts & Innovations
The evolution of commercial avionics centers on the separation of software functions from dedicated hardware. This shift enables more flexible, upgradable, and cost-effective systems compared to the monolithic architectures of the past, driving new service models and capabilities.
Integrated Modular Avionics (IMA) provides a platform of shared computing resources for multiple avionics functions. Airframers specify IMA architectures for new aircraft like the Airbus A350 and Boeing 787 to reduce weight and complexity. This approach is decomposing the traditional model of single-function line-replaceable units, replacing it with software applications running on a common, certified hardware core.
Global mandates for Automatic Dependent Surveillance-Broadcast (ADS-B) Out, driven by ICAO and enforced by regulators like the FAA and EASA, are altering air traffic control. This shift forces a transition from ground-based radar to more precise satellite-based aircraft tracking. Older aircraft in both passenger and cargo fleets are most affected, creating a large, compliance-driven retrofit market to meet air traffic management requirements.
Airlines are increasingly purchasing avionics capabilities as a service rather than acquiring standalone hardware boxes. This model disrupts the traditional one-time sale by bundling hardware with ongoing software updates, data analytics, and performance guarantees. The shift is most visible among major carriers in Europe and North America using data to optimize fuel burn and maintenance schedules.
Global Commercial Avionics Systems Market Segmentation
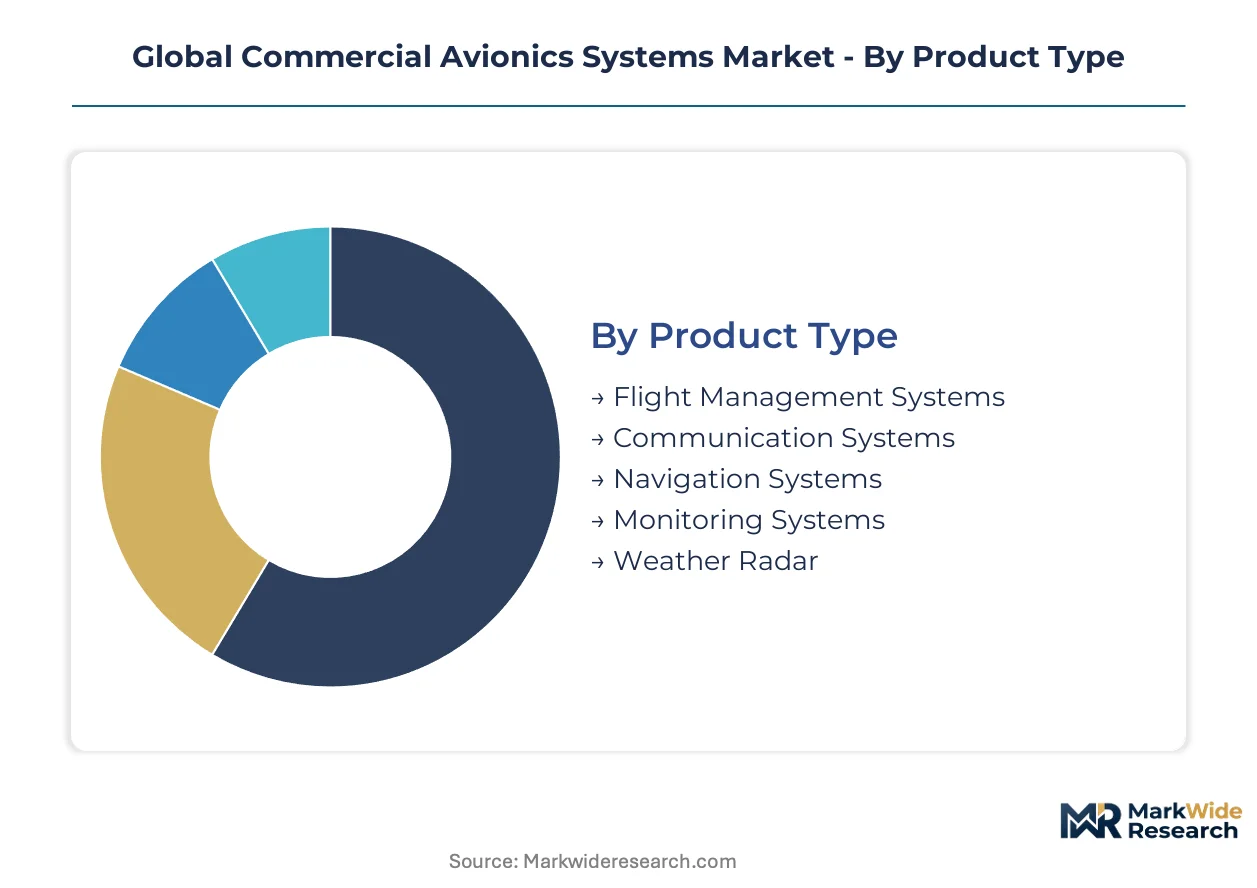
The global commercial avionics systems market segmentation provides a granular view of diverse product, technology, application, and end-user landscapes. Understanding these distinct segments allows suppliers to tailor offerings and address specific operational requirements across the aviation industry. This detailed breakdown highlights areas of concentrated demand and technological evolution.
Product Type:
The product type segmentation reveals where traditional hardware-centric systems face substitution pressure from software-defined architectures.
- Flight Management Systems:These integrated digital systems manage aircraft flight paths, optimize fuel consumption, and provide navigation guidance. Demand concentrates with major commercial airlines in China and India for fleet modernization.
- Communication Systems:These systems enable voice and data exchange between aircraft, air traffic control, and ground operations. Commercial airlines in Europe and North America prioritize advanced satellite-based communication for efficiency.
- Navigation Systems:These systems provide precise positional data using GPS, GLONASS, and inertial reference units for aircraft guidance.
- Monitoring Systems:These include engine health monitoring, air data, and environmental control systems, ensuring operational safety.
- Weather Radar:Airborne weather radar detects precipitation and turbulence, providing critical real-time information for flight safety.
Flight Management Systems anchors the volume base while Communication Systems gains share at the steepest rate.
Technology:
Technology segmentation highlights varying maturity levels and adoption rates of core avionics technologies across the global fleet.
- Satellite-Based:This technology leverages GNSS and satellite communication networks for precise positioning, navigation, and global connectivity. NextGen and SESAR mandates compel fleet-wide upgrades for airspace efficiency.
- Digital Signal Processing:This involves mathematical manipulation of digital signals to filter, compress, and analyze data for communication, navigation, and surveillance. It processes real-time flight data for operational safety.
- Radar-Based:Traditional radar technology provides aircraft detection, weather monitoring, and ground proximity warning capabilities.
- Fiber Optic:High-bandwidth, lightweight fiber optic cables transmit data within aircraft systems, reducing electromagnetic interference.
- Wireless Data Link:Wireless data links enable data exchange between aircraft and ground systems, supporting real-time operational updates.
The market is shifting decisively towards satellite-based and digital signal processing for next-generation aircraft platforms.
Application:
Application segmentation illustrates how regulatory mandates and operational imperatives drive demand for specific avionics functions.
- Flight Safety:This encompasses systems preventing accidents, including EGPWS and TCAS. Regulatory oversight from the US Federal Aviation Administration (FAA) and European aviation authorities establishes mandatory standards.
- Air Traffic Control:Avionics systems support air traffic management by providing precise aircraft location data and communication for ground controllers. ADS-B Out mandates alter control by shifting to satellite tracking.
- Navigation Assistance:These applications provide pilots with route guidance, positional accuracy, and terrain awareness for flight paths.
- Weather Forecasting:Airborne systems provide real-time weather data, allowing pilots to avoid hazardous conditions and optimize routes.
- Aircraft Maintenance:Avionics data supports predictive maintenance, fault diagnosis, and system health monitoring, reducing downtime.
Flight Safety and Air Traffic Control remain core value propositions, underpinning primary application drivers for avionics systems.
End User:
End-user segmentation highlights varying volume contributions and specific needs of different operator types within commercial aviation.
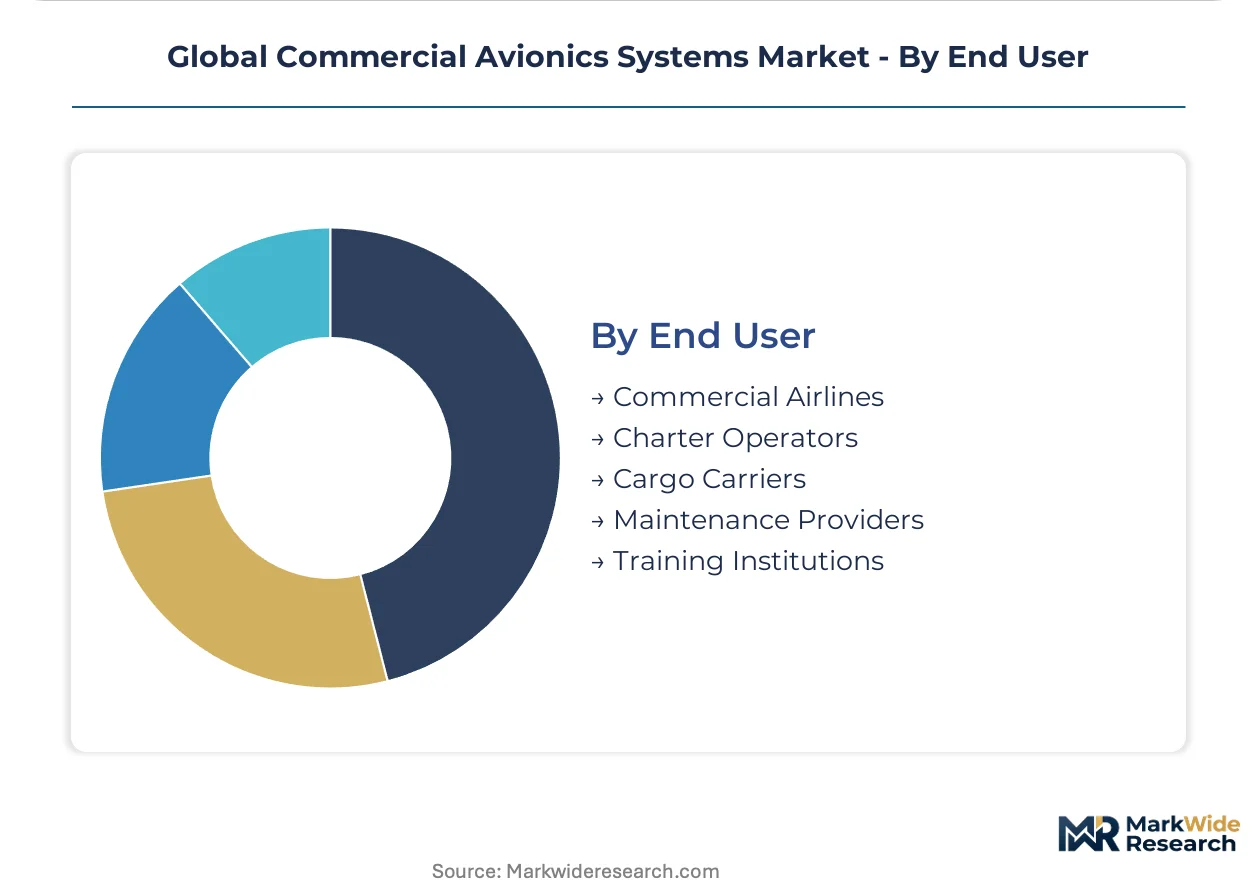
- Commercial Airlines:This segment includes major passenger carriers operating large fleets, demanding full cockpit-to-tail avionics suites. Fleet modernization programs by commercial airlines in China and India create concentrated demand.
- Cargo Carriers:These operators focus on air freight logistics, requiring robust avionics for long-haul operations and compliance. Expansion within cargo carriers significantly contributes to market growth.
- Charter Operators:Charter operators, often with business jet fleets, require flexible and cost-effective avionics solutions.
- Maintenance Providers:MRO organizations require specialized diagnostic and testing avionics for system upkeep and repairs.
- Training Institutions:Flight schools and simulation centers utilize avionics for pilot training, emphasizing realistic system replication.
Commercial Airlines drive the largest overall demand, while Cargo Carriers represent a rapidly expanding segment with specific operational requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial airlines in key global markets concentrate demand for advanced avionics systems. Fleet modernization programs and stringent safety mandates drive significant procurement across diverse geographies. This creates distinct regional investment patterns for both new aircraft and retrofit solutions.
United States
Demand for next-generation air traffic management systems drives avionics upgrades across the US fleet. The US Federal Aviation Administration (FAA) mandates ADS-B Out compliance for improved airspace efficiency. Major aerospace hubs in Seattle and Wichita focus on integrating advanced digital cockpits and certified systems.
China
Commercial airlines in China are expanding and modernizing their large fleets, creating substantial demand for full-suite avionics. Government initiatives support domestic aerospace manufacturing and technology adoption within the aviation sector. Chengdu and Shanghai are central to new aircraft production and avionics system integration efforts.
India
India's aviation sector exhibits strong demand for new aircraft and associated avionics suites, particularly for narrow-body expansion. The country's PLI scheme encourages local manufacturing and MRO capabilities for aerospace components. Bengaluru's aerospace cluster attracts investment in avionics software development and system integration projects.
Germany
European aviation authorities, like EASA, compel fleet-wide upgrades for improved airspace efficiency and safety standards. German carriers prioritize integrated modular avionics for newer aircraft models to reduce weight and complexity. Hamburg and Munich serve as critical centers for aerospace engineering and system certification processes.
France
French commercial airlines invest in satellite-based communication and navigation technologies for enhanced operational efficiency. European regulatory bodies enforce strict DO-178C software certification standards for all safety-critical systems. Toulouse, a major aerospace hub, leads in the development of advanced flight management systems and air traffic control solutions.
Global Commercial Avionics Systems Market Key Industry Players
Player mix skews toward large, integrated aerospace and defense contractors with extensive avionics portfolios. The market exhibits a tiered structure, with a few dominant players providing full-suite solutions alongside specialized component manufacturers and software-focused firms. Strategic archetypes include integrated cockpit solution providers, communication technology specialists, and those focused on retrofitting legacy fleets. Companies actively pursue portfolio diversification, strategic partnerships, and significant R&D investment to meet complex certification requirements.
Honeywell International Inc. exemplifies a leader in integrated cockpit solutions and advanced, certified navigation systems, demonstrating broad technological capability. Collins Aerospace, a major player, represents a firm leveraging an extensive portfolio in flight management systems to meet stringent DO-178C requirements for safety-critical software. Meanwhile, the Thales Group occupies a position as a specialist in air traffic management and communication technologies across global commercial platforms. These entities collectively anchor the market's high-value segment, focusing on comprehensive offerings and adherence to rigorous regulatory standards.
| Leading Market Players |
|---|
| L3Harris Technologies |
| BAE Systems |
| Honeywell International Inc. |
| Collins Aerospace |
| Safran Electronics & Defense |
| RTX Corporation |
| General Electric Aviation |
| Garmin Ltd. |
| Thales Group |
| Others |
Cost & Logistics Intelligence
Multi-year lead times for highly specialized avionics components contribute to a concentrated supply chain, granting significant pricing power to established manufacturers.
Pricing Analysis
Cost-plus contracts, often indexed to labor and material costs, dominate pricing for bespoke avionics systems and long-term service agreements. Price differentiation stems from the stringent DO-178C software certification level required for safety-critical systems and the level of customization for specific aircraft platforms. Pricing pressure stems from commercial airlines demanding cost-effective retrofit solutions for older fleets. Commercial airlines seeking complete cockpit-to-tail suites are generally less price-sensitive compared to smaller charter operators focused on cost-effective upgrades.
Supply Chain Analysis
Strategic stockpiling of critical, long-lead components rather than just-in-time delivery characterizes the avionics supply chain, given the high reliability requirements. Geographic supply concentrates in the United States, Germany, and China for various electronic components and sub-assemblies. The industry draws from radiation-hardened semiconductors and specialized electronic components. Single-source vulnerability for highly specialized parts represents a significant structural risk. Distribution runs through direct sales to airframers and dedicated MRO networks for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A shift in buyer power towards major commercial airlines, driven by fleet modernization programs and long-term procurement agreements, reshapes market dynamics.
For Market Incumbents:Consolidate core product lines by investing heavily in DO-178C certification for next-generation software-defined architectures. This strategy defends against emerging software-centric entrants and mitigates the threat of talent shortages in safety-critical engineering. Leverage extensive portfolios in flight management systems to offer integrated solutions, controlling a larger share of the avionics suite. Build capacity for advanced digital signal processing components in key manufacturing hubs.
For New Entrants and Emerging Players:Differentiate on accelerated certification pathways for lightweight avionics systems targeting the emerging Urban Air Mobility market. Target underpenetrated segments like regional cargo carriers requiring cost-effective ADS-B Out compliance solutions. A service-based go-to-market angle, bundling hardware with ongoing software updates and data analytics, can attract airlines seeking operational efficiency gains without large upfront capital expenditure.
For Investors and Strategic Acquirers:Carve-out targets emerge from large aerospace conglomerates divesting non-core avionics divisions or specialized software firms with expertise in AI-driven flight optimization. Long-term viability hinges on companies with verifiable DO-178C software engineering talent and a portfolio aligned with satellite-based navigation mandates. The signal to watch is the pace of regulatory harmonization for eVTOL avionics certification, indicating market readiness for new entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in DO-178C Software Certification | Ensures compliance with stringent safety standards for next-generation systems. |
| Develop Integrated Modular Avionics Platforms | Reduces aircraft weight and complexity, enhancing operational efficiency for airframers. |
| Expand Data Analytics Service Offerings | Creates new recurring revenue streams from flight data optimization and predictive maintenance. |
| Target Urban Air Mobility Avionics | Captures early market share in the rapidly growing eVTOL aircraft segment. |
| Secure Supply Chains for Specialized Components | Mitigates vulnerability to shortages and price volatility for critical electronic parts. |
Research Approach
Cross-validation between primary interviews with avionics engineers and secondary analysis of FAA certification databases anchors the qualitative findings. Industry stakeholders interviewed included airline procurement managers, air traffic control specialists, and aerospace R&D directors, alongside MRO service providers. Secondary data sources encompassed aerospace trade publications, ICAO reports, and company financial filings, triangulating insights from diverse perspectives to ensure robustness.
Sensitivity analysis informed the forecast framework, assessing impacts from varying aircraft delivery schedules and regulatory compliance timelines across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived from historical trends and projected market drivers, with key forecast inputs including global air traffic growth projections and fleet modernization program timelines.
The analysis sits within stated boundaries; outcomes outside significant shifts in global air traffic mandates or unforeseen technological disruptions would require recalibration. Forecasts reflect assumptions regarding regulatory stability and continued investment in aerospace infrastructure. Revision becomes warranted when major geopolitical events or profound supply chain disruptions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Aircraft EMI Shielding Market
Avionics
Military Aircraft Avionics Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Global Helicopter Avionics Market
Avionics
Display for Avionics Application Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Aerospace Avionics Market
Avionics
Global Avionics Market
Avionics
Europe Military Aircraft Communication Avionics Market