
 North America Unmanned Systems Market | 2026-2036
North America Unmanned Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Unmanned Systems Market Analytics
Aftermarket service revenue is fragmenting across the North America unmanned systems landscape as original equipment manufacturers and third-party providers compete for sustainment contracts. Lockheed Martin leverages its integrated defense electronics footprint to capture long-term platform support agreements. General Atomics anchors the military drone segment with proven medium-altitude endurance systems and associated ground control station networks.
North America unmanned systems encompass aerial, ground, and maritime platforms operating without onboard human pilots, typically employing GPS navigation, RF communication links, and sensor payloads exceeding 25 kilograms for defense-grade configurations. These systems serve military reconnaissance, infrastructure inspection, and precision agriculture through autonomous or remotely piloted flight profiles. Multirotor UAVs occupy the commercial entry tier where price sensitivity and ease of deployment dominate procurement criteria, while fixed-wing UAVs sustain higher-margin defense contracts demanding extended endurance and payload flexibility. Surveillance applications lead current deployment volumes across both military and homeland security end users.
FAA regulations governing commercial drone operations, alongside FCC spectrum allocations for command-and-control links, structure market access and platform certification requirements in the United States. NHTSA and Transport Canada parallel frameworks for ground-based unmanned vehicles impose safety and liability standards that shape product development timelines. Stakeholders must track evolving beyond-visual-line-of-sight rulemakings and cross-border certification reciprocity to anticipate where operational expansion becomes viable.
Market Dynamics
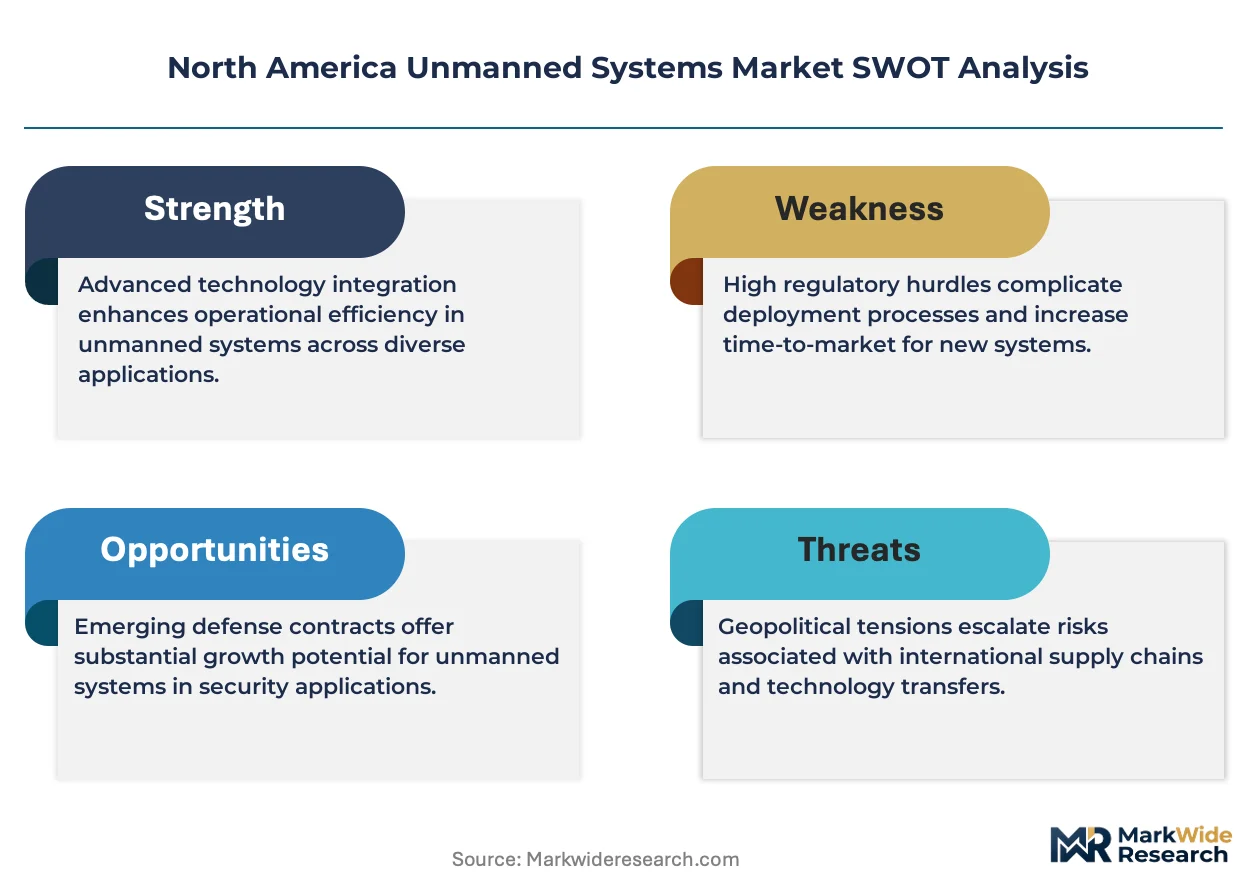
Beyond-visual-line-of-sight waiver approvals from the FAA are accelerating commercial access while defense procurement concentrates surveillance platform orders in southwestern U.S. test corridors.
Growth Catalysts
- FAA Part 107 Evolution:Expanded waiver categories for commercial drone operations unlock infrastructure inspection and precision agriculture deployments across U.S. airspace.
- Defense Cluster Concentration:Test ranges in New Mexico and Arizona support rapid prototyping cycles for military reconnaissance platforms.
- RF Spectrum Allocation:FCC command-and-control link designations secure dedicated bandwidth for unmanned system telemetry in congested electromagnetic environments.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in Asian manufacturing hubs, exposing North American assemblers to input cost volatility and logistics bottlenecks.
- Airworthiness Certification Friction:FAA type certification timelines for defense-grade platforms extend development cycles and compress contractor margins.
- Ground Vehicle Regulatory Fragmentation:NHTSA and Transport Canada maintain non-harmonized safety standards that fragment product development roadmaps for cross-border ground systems.
Strategic Opportunities
- Canadian Arctic Operations:Extended endurance platforms address surveillance gaps in northern territories where manned aviation faces weather and range constraints.
- AI-Enabled Autonomy Convergence:Machine vision algorithms paired with edge computing compress operator-to-vehicle ratios for commercial inspection fleets.
- State-Level Agricultural Incentives:California and Texas water management districts fund precision agriculture drone adoption for irrigation monitoring and crop stress detection.
Industry Challenges
- Embedded Software Talent Scarcity:Flight control firmware and sensor fusion engineering functions face acute hiring competition from autonomous vehicle and robotics sectors.
- Cross-Border Certification Reciprocity Delays:Divergent Transport Canada and FAA validation timelines force duplicate testing for platforms serving both markets.
- Legacy System Integration Complexity:Military ground control station networks require backward compatibility protocols that constrain hardware refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Unmanned Systems Market |
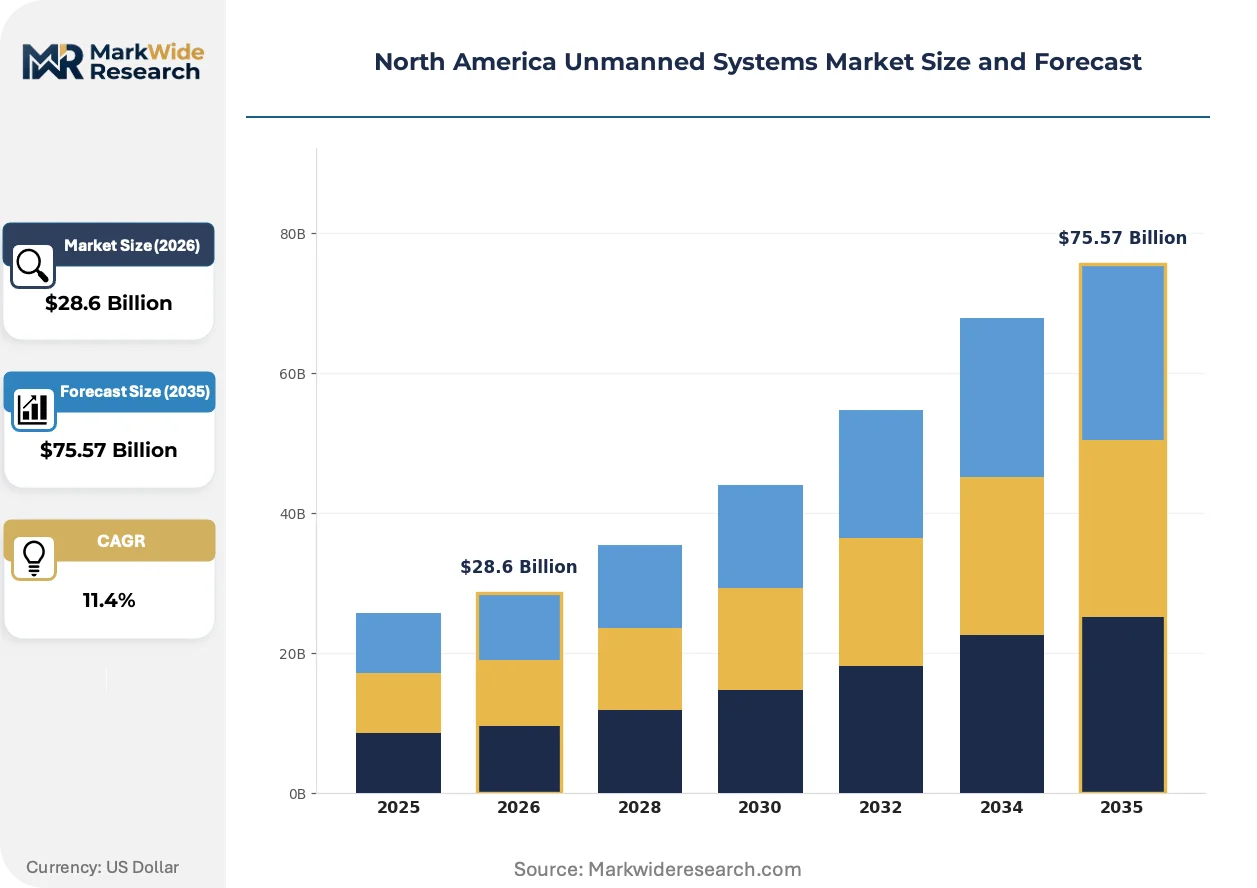
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing UAVs, Multirotor UAVs, Hybrid UAVs, VTOL UAVs End User: Military, Homeland Security, Agriculture, Entertainment Application: Surveillance, Delivery, Mapping, Inspection Technology: GPS, LiDAR, Computer Vision, RF Communication |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, General Atomics, L3Harris Technologies, Teledyne FLIR, Boeing, RTX Corporation, Textron Systems, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Unmanned Systems Market Evolving Landscape
Autonomous navigation architectures and regulatory sandbox expansions are compressing the gap between experimental platforms and certified commercial deployment across North American airspace and surface domains.
Edge-based sensor fusion is digitizing real-time decision-making for multirotor inspection fleets. Utility operators in Texas and California deploy these systems for transmission line monitoring at frequencies impossible with manned helicopters. The technology is digitizing maintenance scheduling by converting visual anomaly detection into automated work-order generation.
FAA Reauthorization Act provisions mandate integration of unmanned systems into the National Airspace System by specific statutory deadlines. The framework forces infrastructure investments in detect-and-avoid technologies and remote identification systems. Commercial operators in the southwestern United States accelerate BVLOS waiver applications to secure first-mover positioning in automated cargo corridors.
Buyers now unbundle platform acquisition from aftermarket sustainment, forcing OEMs to compete with third-party service providers on maintenance contract terms. Agricultural cooperatives in the Midwest and oilfield services firms in the Permian Basin lead this shift toward competitive tendering for spare parts and technical support. The pattern compresses OEM service margins while elevating specialized regional maintenance shops.
North America Unmanned Systems Market Segmentation
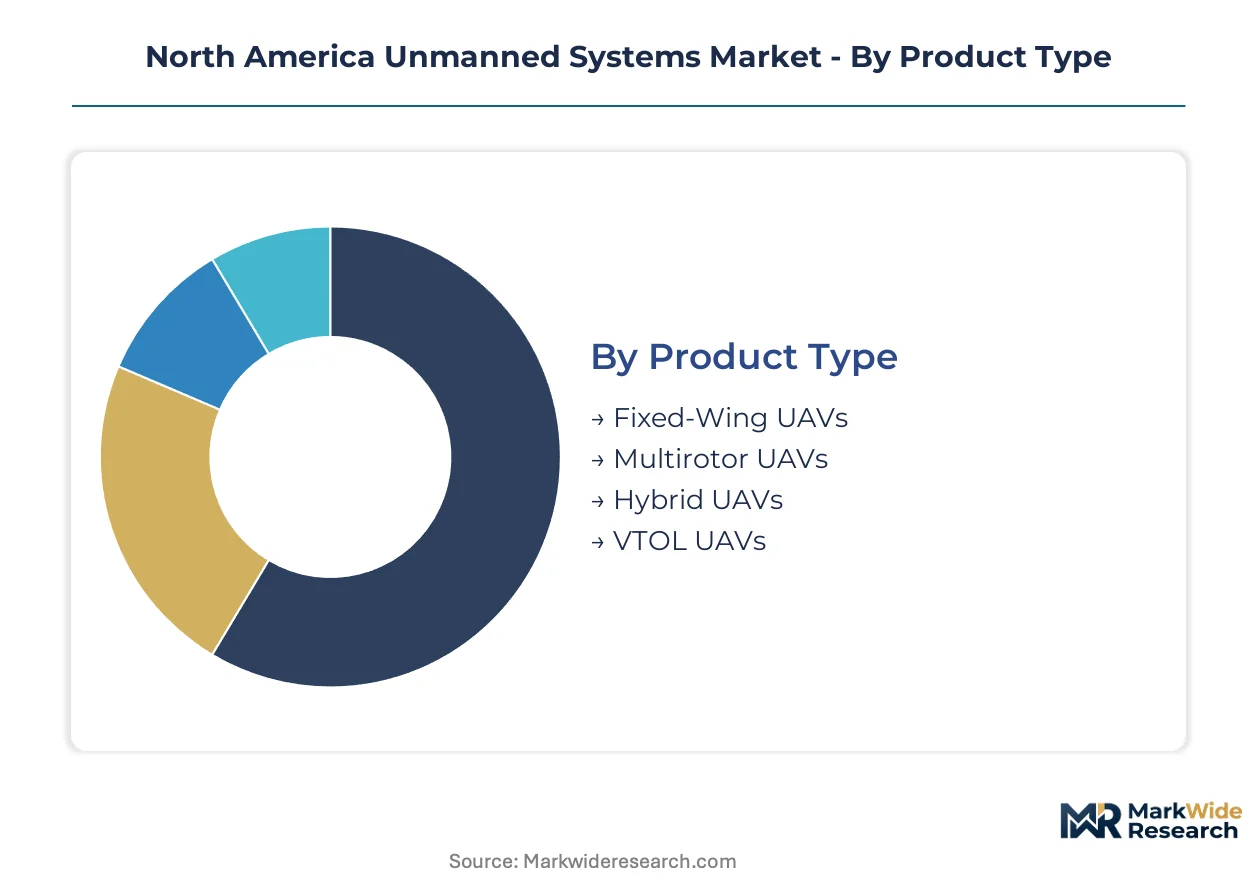
Platform configuration determines endurance, payload capacity, and regulatory pathway for unmanned systems across North American airspace. End-use concentration in defense and agriculture creates divergent performance requirements that shape procurement patterns and technology investment priorities.
Product Type:
Cost tier stratification separates defense-grade endurance platforms from commercial entry-level systems, with hybrid architectures commanding premium positioning for specialized missions.
- Fixed-Wing UAVs:Extended endurance airframes with wing-borne lift sustain missions exceeding 24 hours for military reconnaissance and maritime patrol. Demand concentrates in southwestern U.S. defense corridors where test ranges validate long-loiter surveillance configurations against electromagnetic threat environments.
- Multirotor UAVs:Vertical takeoff capability with distributed electric propulsion dominates commercial inspection and agricultural spraying below 400 feet AGL. Price sensitivity in the Midwest and California Central Valley drives procurement toward Chinese-manufactured airframes with localized software integration.
- Hybrid UAVs:Combined fixed-wing endurance with multirotor agility addresses utility inspection missions requiring runway-independent deployment.
- VTOL UAVs:Tilt-rotor and tail-sitter configurations optimize payload fraction for shipborne military operations and confined-area logistics.
Fixed-Wing UAVs hold installed capacity. VTOL UAVs is rotating up the share rankings.
End User:
Customer type determines certification burden, with defense procurement cycles extending 36-60 months against 6-12 month commercial deployment timelines.
- Military:Medium-altitude endurance platforms with encrypted C-band links and signals intelligence payloads anchor reconnaissance modernization programs. Pentagon procurement concentrates in New Mexico and Arizona test corridors where rapid prototyping accelerates fielding timelines for Indo-Pacific theater requirements.
- Homeland Security:Border patrol and port surveillance applications demand all-weather infrared sensors with automated object recognition for human and vehicle detection. CBP operations along the Rio Grande Valley and San Diego sectors drive volume for tethered and free-flying persistent stare systems.
- Agriculture:Multispectral crop monitoring and precision spraying reduce input costs for water-stressed operations in California and Texas.
- Entertainment:Light show coordination and cinematography applications prioritize flight safety redundancy and noise reduction for urban airspace.
Military commands procurement volume. Agriculture is expanding most quickly as state water management incentives accelerate adoption.
Application:
Application maturity separates established surveillance workflows from emerging automated cargo networks still awaiting beyond-visual-line-of-sight regulatory clarity.
- Surveillance:Real-time video streaming with gyro-stabilized gimbals dominates current deployment across military, law enforcement, and critical infrastructure protection. Texas utility operators and California agricultural districts sustain replacement demand as sensor resolution standards escalate.
- Delivery:Automated cargo corridors for medical supplies and retail fulfillment remain experimental pending FAA type certification for detect-and-avoid systems. Amazon Prime Air and Zipline operations in North Carolina and Texas test beds validate operational concepts before scaled deployment.
- Mapping:Photogrammetric and LiDAR survey missions support construction, mining, and environmental monitoring with centimeter-grade accuracy.
- Inspection:Confined-space and elevated asset examination reduces worker exposure in oilfield, wind turbine, and transmission tower environments.
Surveillance holds installed capacity. Delivery is rotating up the share rankings.
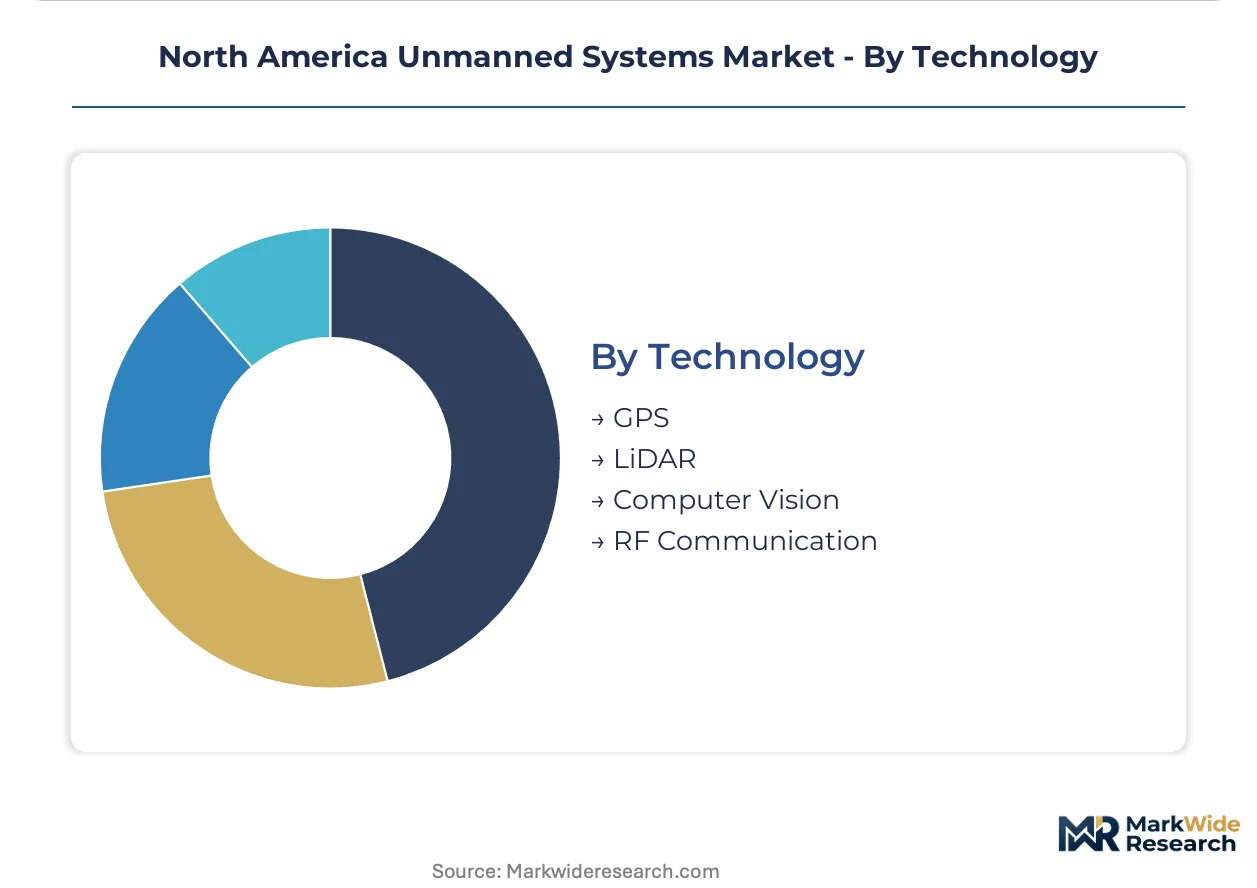
Technology:
Technology stack differentiation separates commodity navigation from mission-critical autonomy systems where embedded software talent scarcity constrains supplier expansion.
- GPS:Multi-constellation receivers with anti-jam capabilities provide position, navigation, and timing for defense platforms operating in contested electromagnetic environments. Military procurement mandates M-code GPS integration for resilience against spoofing and denial attacks.
- LiDAR:Solid-state laser ranging enables three-dimensional mapping and obstacle detection for autonomous navigation in GPS-denied conditions. Autonomous vehicle industry competition for 1550nm wavelength components constrains supply availability for aerial platforms.
- Computer Vision:Onboard machine learning inference accelerates target recognition and anomaly detection without ground station dependency.
- RF Communication:C-band and L-band command links with frequency-hopping spread spectrum resist interference in congested spectrum environments.
GPS holds installed capacity. Computer Vision is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial buyers in the Central Valley price-shop Chinese-manufactured multirotor frames, while Pentagon procurement officers prioritize endurance specifications over unit cost for reconnaissance platforms.
United States
Southwestern defense clusters in New Mexico and Arizona concentrate military drone prototyping, where Pentagon test ranges accelerate fielding cycles for Indo-Pacific theater requirements. FAA Part 107 waiver expansions unlock commercial BVLOS corridors for automated cargo trials in Texas and North Carolina. California agricultural districts drive multispectral sensor demand for water-stressed irrigation monitoring.
Canada
Arctic surveillance gaps in northern territories create demand for extended-endurance platforms where manned aviation faces weather constraints. Transport Canada maintains non-harmonized certification timelines with FAA counterparts, forcing duplicate validation for cross-border operators. Ontario and Quebec house emerging precision agriculture adopters leveraging provincial environmental incentives for crop monitoring deployment.
Mexico
Border security cooperation with U.S. agencies sustains demand for persistent stare systems along the Rio Grande corridor. Mexican energy infrastructure operators deploy inspection platforms for pipeline monitoring across remote terrain. Nuevo León and the Bajío Region concentrate manufacturing assembly for U.S.-bound commercial drone components.
North America Unmanned Systems Market Competitive Landscape
Integrated defense conglomerates and specialized unmanned platform developers split the market between long-cycle military contracts and agile commercial deployments. The vendor structure consolidates around prime contractors with established Pentagon relationships, while tier-two specialists capture niche agricultural and inspection segments. Two archetypes dominate: full-spectrum defense electronics houses with sustainment networks, and focused platform builders optimizing for specific mission profiles. Competitive moves center on aftermarket service unbundling and AI-enabled autonomy partnerships.
Within the integrated defense tier, Lockheed Martin and Northrop Grumman exemplify prime contractors leveraging electronics footprints for long-term platform support agreements. General Atomics occupies a distinct position as a focused platform specialist with proven medium-altitude endurance systems. These three entities represent the spectrum from diversified defense conglomerates to mission-specific developers competing for sustainment revenue as buyers unbundle acquisition from aftermarket service.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| General Atomics |
| L3Harris Technologies |
| Teledyne FLIR |
| Boeing |
| RTX Corporation |
| Textron Systems |
| AeroVironment |
| Others |
Value Network & Pricing Analysis
Lithium-ion cell production concentrates in South Korean and Chinese manufacturing hubs, tethering North American assemblers to input cost volatility while aftermarket service contracts capture margin pools downstream from hardware sales. Defense-grade platform vendors offset commodity exposure through long-term sustainment agreements, whereas commercial multirotor suppliers compete on upfront unit economics.
Pricing Analysis
Aftermarket parts and technical service contracts drive lifetime value capture as buyers unbundle platform acquisition from sustainment. Three-tier pricing structure across defense-grade endurance systems, commercial hybrid platforms, and entry-level multirotor frames reflects certification burden and payload flexibility. Cost compression in the commercial tier intensifies because agricultural cooperatives price-shop Chinese-manufactured airframes with localized software integration. Midwest farming operations exhibit highest price sensitivity; Pentagon procurement officers prioritize endurance specifications over unit cost.
Supply Chain Analysis
Electronics manufacturing services capacity for flight control modules and sensor fusion processors concentrates in Mexico, Taiwan, and Malaysia. Raw material dependencies span lithium-ion cathode chemistries, gallium nitride RF components, and precision-machined aluminum airframes. Single-source vulnerability in 1550nm LiDAR wavelength components constrains autonomous navigation platform availability. Distribution runs through defense prime contractor networks for military end users and direct-to-operator e-commerce channels for commercial agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are recovering from budget sequestration troughs, with Indo-Pacific theater modernization programs driving platform replacement demand across the analysis window.
For Market Incumbents: Build proprietary ground control station software ecosystems to lock in platform refresh cycles and aftermarket revenue. Deepen backward integration into encrypted C-band RF link production to secure supply against spectrum allocation disputes. Acquire specialized computer vision engineering teams to counter talent scarcity from autonomous vehicle sector competition.
For New Entrants and Emerging Players: Canadian Arctic surveillance gaps where manned aviation faces weather constraints represent the most penetrable entry point for extended-endurance platform developers. State-funded precision agriculture programs in water-stressed California and Texas districts offer volume traction without federal certification barriers. Partner with regional maintenance shops to bypass OEM service networks and capture unbundled sustainment contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward tier-two platform specialists with FAA Part 107 waiver operational experience and proven BVLOS flight hours. Long-term viability hinges on regulatory sandbox positioning ahead of National Airspace System integration deadlines. Monitor FAA detect-and-avoid rulemaking velocity as the critical inflection signal for automated cargo corridor scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Autonomy Partnership | Machine vision algorithms compress operator-to-vehicle ratios for commercial inspection fleets deploying across Texas utility corridors. |
| BVLOS Waiver Portfolio Expansion | First-mover positioning in automated cargo trials secures operational data advantages before FAA type certification standardization. |
| Regional Maintenance Network Acquisition | Capturing unbundled aftermarket service contracts elevates margin capture as agricultural cooperatives tender spare parts competitively. |
| Canadian Arctic Endurance Platform Development | Extended loiter capabilities address surveillance gaps in northern territories where Transport Canada regulations favor unmanned alternatives. |
| Defense Prime Contractor Sustainment Integration | Long-term platform support agreements with Pentagon procurement offices anchor revenue visibility through Indo-Pacific modernization cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with UAV program managers at defense primes, FAA certification specialists, agricultural cooperative procurement directors, and utility inspection fleet operators. Secondary validation drew from FAA waiver application databases, Pentagon budget justification documents, FCC spectrum allocation filings, and state-level agricultural incentive program disclosures. Bottom-up platform shipment estimates triangulated against top-down defense procurement budget allocations.
Calibration against historical defense modernization cycles and commercial BVLOS waiver approval velocities anchored projection trajectories across the analysis window. Segmentation dimensions modeled encompass platform configuration, end-user type, application maturity, and technology stack differentiation. CAGRs were derived from installed base replacement schedules and emerging use-case penetration curves, with specific inputs including lithium-ion battery cost decline trajectories and edge computing performance improvement rates.
Stress conditions across FAA rulemaking delays, lithium supply chain disruptions, and electromagnetic spectrum reallocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding National Airspace System integration timelines and defense budget authorization continuity. Quarterly review of BVLOS waiver approval rates and Pentagon program milestone announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Drone Jamming System Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Tethered Manned Submersible Market