
 Light Electric Aircraft Market | 2026-2036
Light Electric Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Light Electric Aircraft Market Outlook
The capital-intensity gap between certificated OEMs and prototype-stage developers is bifurcating competitive positions in the light electric aircraft sector. Joby Aviation leverages extensive flight-test infrastructure to sustain FAA certification momentum for its tiltrotor configuration. Lilium anchors its position through proprietary ducted-fan propulsion architecture and German manufacturing scale-up. Pipistrel d.o.o. dominates the ultralight segment with Slovenian production lines that supply training schools across Europe and Asia.
Light electric aircraft are fixed-wing, multirotor, or hybrid platforms propelled by battery-electric, fuel-cell, or solar-electric powertrains, typically operating below 19,000 feet with maximum takeoff weights under 19,000 pounds for regional transport, training, and surveillance missions. Fixed-wing configurations lead current deliveries to flight training schools, while hybrid-electric technology captures expanding margin pools in cargo transport applications where range requirements exceed pure-battery capabilities. Urban air mobility applications are concentrating demand for multirotor designs, though battery-electric technology remains constrained by energy density limitations that fuel-cell variants are positioned to address.
The FAA Part 23 rewrite and EASA SC-VTOL special condition framework are reshaping certification timelines and airworthiness standards for electric propulsion systems, with both regulators mandating novel battery thermal-runaway containment protocols. The EU Green Deal aviation decarbonization targets and the US Inflation Reduction Act clean-vehicle incentives are redirecting public procurement and airport infrastructure investment toward electrified fleets. Stakeholders must monitor harmonization gaps between FAA and EASA battery certification standards, as divergence in test protocols threatens to fragment market access for dual-certified platforms.
Market Dynamics
Certification pathway divergence between FAA Part 23 rewrite and EASA SC-VTOL special conditions is fragmenting development timelines and forcing dual-track engineering investments across the light electric aircraft sector.
Growth Catalysts
- EU Green Deal aviation decarbonization targets:The framework mandates fleet electrification milestones that redirect public procurement and airport infrastructure subsidies toward battery-electric and hydrogen-electric platforms.
- Solid-state battery chemistry maturation:Energy density improvements above 400 Wh/kg are unlocking extended-range missions for fixed-wing training aircraft and regional cargo feeders previously constrained by lithium-ion limitations.
- Flight training school electrification:European and Asian pilot academies are consolidating fleet orders around electric ultralight platforms to reduce hourly operating costs and meet municipal noise restrictions.
Market Restraints
- Battery cell supply concentration:Cathode material processing and cell manufacturing capacity clusters in China and South Korea, exposing OEMs to export control volatility and input cost spikes.
- Thermal-runaway containment engineering:FAA and EASA mandates for novel battery housing architectures add non-recurring engineering costs that disproportionately burden prototype-stage developers.
- Hybrid-electric range extension:Turbogenerator-assisted architectures retain competitive positioning for cargo operators requiring 300+ nautical mile missions, slowing pure-electric adoption in freight segments.
Strategic Opportunities
- US Inflation Reduction Act clean-vehicle incentives:Tax credits for domestic electric vehicle manufacturing extend to light aircraft propulsion systems, attracting greenfield assembly investment to Ohio and Washington state.
- Urban air mobility corridor development:German municipalities are designating vertiport networks in Munich and Hamburg that create captive demand for multirotor passenger platforms.
- Fuel-cell propulsion convergence:Integration of hydrogen storage with electric motors addresses energy density constraints in surveillance missions requiring 4+ hour endurance.
Industry Challenges
- Certification engineer scarcity:FAA and EASA qualified flight-test personnel shortages are extending validation timelines for novel electric propulsion architectures.
- Battery management system integration:Legacy airframe designs require structural modification to accommodate thermal monitoring and cell-balancing electronics, complicating retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Electric Aircraft Market |
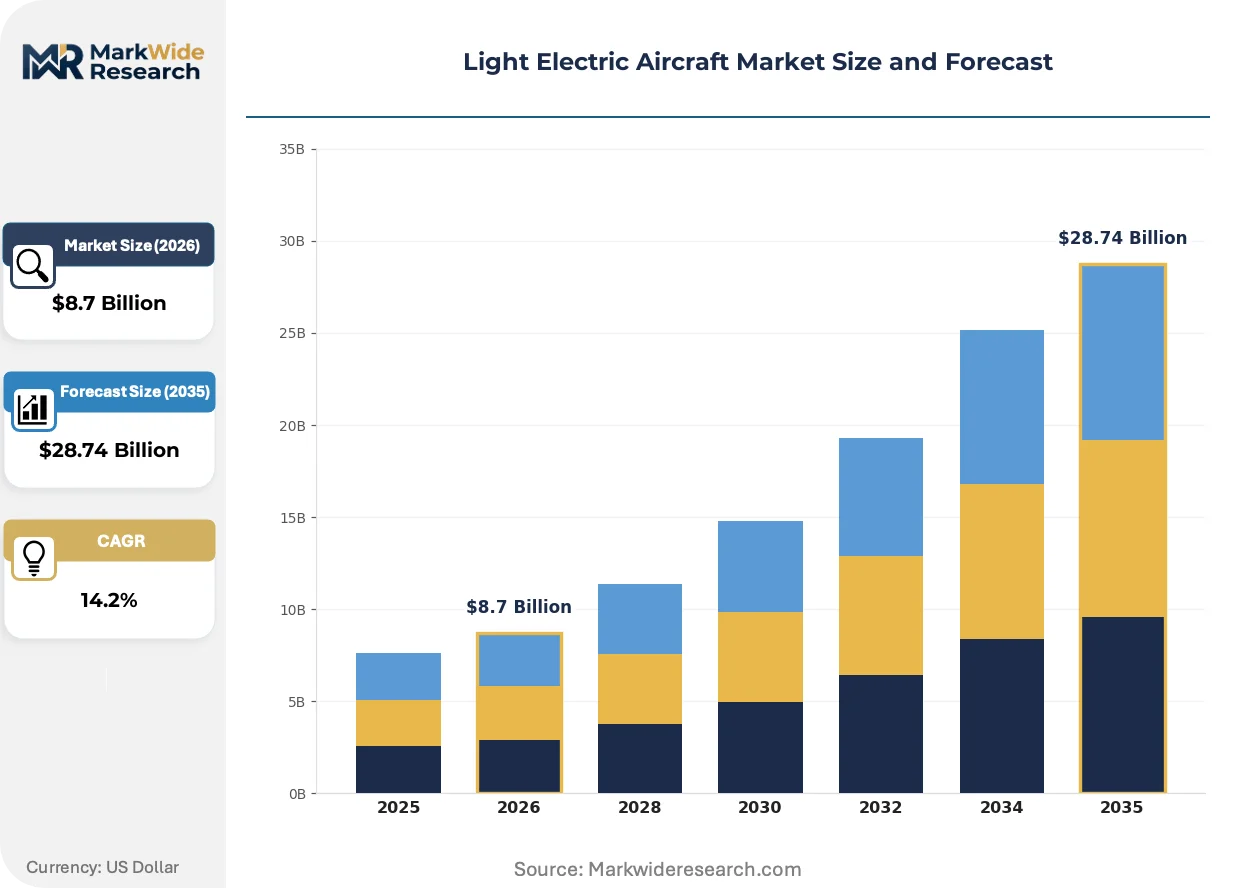
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multirotor, Hybrid, Ultralight End User: Private Aviation, Cargo Transport, Emergency Services, Training Schools Technology: Battery Electric, Fuel Cell, Hybrid Electric, Solar Powered Application: Aerial Surveying, Recreational Flying, Agricultural Monitoring, Urban Air Mobility |
| Companies Covered | Airbus SE, Joby Aviation, Lilium, Eviation, Pipistrel d.o.o., Ampaire Inc., Heart Aerospace, Bye Aerospace, AeroVironment, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Electric Aircraft Market Strategic Shifts
Power electronics packaging and thermal management architectures are compressing development cycles as OEMs race to lock in certification baselines before regulatory divergence widens.
Silicon carbide (SiC) power semiconductors are replacing silicon IGBTs in motor controllers, enabling higher switching frequencies that reduce inverter weight. Flight training schools and urban air mobility operators are specifying SiC-based systems for new fleet acquisitions. The technology is miniaturizing powertrain footprints, allowing distributed electric propulsion layouts that were previously volume-prohibitive.
EASA SC-VTOL special conditions for battery thermal-runaway containment are mandating redundant cell isolation and venting systems that exceed prior Part 23 requirements. OEMs serving European markets must redesign battery enclosures and demonstrate flame containment through extended fire tests. Tiltrotor and multirotor platforms face the steepest compliance costs due to battery placement proximity to passenger cabins.
Direct OEM-to-operator fleet leasing is displacing traditional aircraft ownership models in the training segment. Flight schools in Slovenia and the Czech Republic are contracting all-inclusive hourly rates that bundle maintenance, battery replacement, and insurance. This shift concentrates credit risk with manufacturers while accelerating fleet turnover cycles.
Light Electric Aircraft Market Segmentation
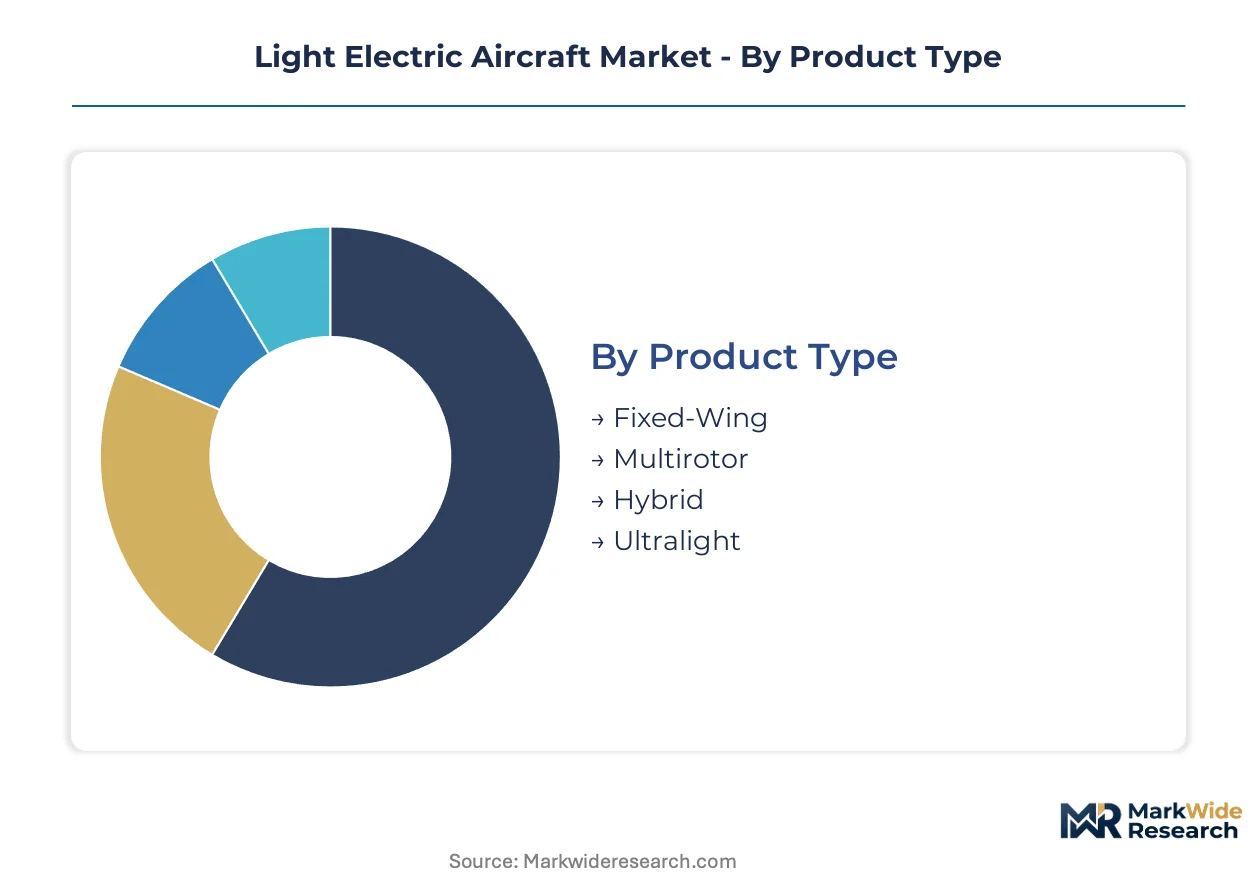
Segmentation in the light electric aircraft sector reveals how powertrain choices, airframe configurations, and mission profiles split manufacturing investment and certification resources. Understanding these divides exposes where capital is concentrating and which technology bets are reshaping competitive positions.
Product Type:
Margin pools concentrate in configurations that balance certification complexity against production scalability, with hybrid architectures capturing premium pricing for extended-range missions.
- Fixed-Wing:Conventional wing-and-tail designs dominate flight training school procurement due to lower hourly operating costs and established pilot transition pathways. European academies in Slovenia and the Czech Republic are consolidating fleet orders around electric fixed-wing platforms to meet municipal noise restrictions and reduce fuel expenditure.
- Multirotor:Vertical-lift configurations with distributed electric propulsion enable urban air mobility operations where runway access is constrained. German municipalities are designating vertiport networks in Munich and Hamburg that create captive demand for these platforms, though battery energy density limits payload-range economics.
- Hybrid:Turbogenerator-assisted architectures retain competitive positioning for cargo operators requiring extended missions beyond pure-battery capabilities. The technology captures expanding margin pools where range requirements exceed lithium-ion limitations.
- Ultralight:Sub-600 kg platforms serve recreational pilots and entry-level training with minimal certification burden. Pipistrel's Slovenian production lines supply these aircraft across Europe and Asia.
Fixed-wing holds installed capacity. Multirotor is rotating up the share rankings.
End User:
Volume concentration follows public procurement patterns, with training schools and cargo operators driving fleet-scale orders that amortize non-recurring engineering costs.
- Private Aviation:Owner-operated aircraft for recreational and personal transport missions. Demand clusters in regions with favorable small-airport density and charging infrastructure.
- Cargo Transport:Regional feeder operations and last-mile logistics represent the steepest expansion trajectory as e-commerce fulfillment networks electrify short-haul routes. Hybrid-electric technology addresses payload-range requirements that pure-battery systems cannot satisfy.
- Emergency Services:Medical evacuation and search-and-rescue missions require rapid response capability and all-weather reliability. Fuel-cell variants are gaining traction for endurance-critical operations.
- Training Schools:Pilot academies are consolidating fleet orders around electric platforms to reduce hourly operating costs. European and Asian schools are contracting all-inclusive hourly rates that bundle maintenance and battery replacement.
Training schools hold installed capacity. Cargo transport is climbing the fastest.
Technology:
Supply concentration in cathode material processing shapes competitive access, with solid-state chemistry development redirecting manufacturing investment toward longer-range applications.
- Battery Electric:Lithium-ion and emerging solid-state cells power the majority of delivered aircraft. Energy density improvements above 400 Wh/kg are unlocking extended-range missions for fixed-wing training aircraft previously constrained by cell limitations.
- Fuel Cell:Hydrogen-electric systems address energy density constraints in surveillance missions requiring extended endurance. Integration with electric motors is advancing for applications where battery weight penalties are prohibitive.
- Hybrid Electric:Turbogenerator-battery combinations serve cargo and regional transport segments. The architecture retains competitive positioning where mission profiles exceed pure-electric range.
- Solar Powered:Photovoltaic-integrated wings enable ultra-long-endurance surveillance and atmospheric research. Applications remain specialized due to power density limitations.
Battery electric holds installed capacity. Fuel cell is gaining share fastest.
Application:
Regulatory pathway divergence between FAA Part 23 and EASA SC-VTOL is fragmenting development timelines across mission types, forcing dual-track engineering investments.
- Aerial Surveying:Geospatial mapping and infrastructure inspection missions favor fixed-wing endurance or multirotor maneuverability depending on coverage requirements. Sensor payload integration drives airframe selection.
- Recreational Flying:Leisure and sport aviation represents established demand for ultralight and light-sport categories. Municipal noise restrictions are accelerating electric adoption in European markets.
- Agricultural Monitoring:Crop health assessment and precision spraying operations are expanding most quickly in regions with large-scale farming and regulatory acceptance of unmanned or reduced-crew operations.
- Urban Air Mobility:Passenger transport within and between metropolitan areas concentrates demand for multirotor designs. FAA and EASA certification frameworks are maturing, though battery thermal-runaway containment mandates add engineering burden.
Recreational flying holds installed capacity. Urban air mobility is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flight training schools in Slovenia and the Czech Republic demonstrate the highest price elasticity, consolidating fleet orders around ultralight electric platforms to minimize hourly operating costs. German urban air mobility operators show lower sensitivity, absorbing premium pricing for certified multirotor designs serving designated vertiport networks.
United States
FAA Part 23 rewrite timelines are accelerating certification investments for fixed-wing training aircraft and hybrid-electric cargo platforms. The Inflation Reduction Act clean-vehicle incentives redirect greenfield assembly investment toward Ohio and Washington state production clusters. Greater Los Angeles and Dallas-Fort Worth metropolitan areas are designating initial urban air mobility corridors that concentrate multirotor demand.
Germany
EASA SC-VTOL special conditions mandate redundant battery thermal-runaway containment systems that exceed prior airworthiness standards. The EU Green Deal aviation decarbonization targets redirect municipal infrastructure subsidies toward electrified vertiport development. Munich and Hamburg are establishing captive demand networks for multirotor passenger platforms through designated landing zone designations.
Slovenia
Flight training academies are contracting all-inclusive hourly rates that bundle maintenance, battery replacement, and insurance for electric ultralight fleets. National noise restriction policies accelerate adoption of battery-electric platforms at municipal airfields. Ajdovščina production clusters supply certified training aircraft across European and Asian pilot academies.
China
Cathode material processing concentration exposes OEMs to export control volatility and input cost spikes for lithium-ion cell supply. The country's dual carbon goals redirect state procurement toward electrified aviation demonstrators. Shenzhen and Chengdu manufacturing clusters are scaling solid-state battery pilot lines for aerospace applications.
United Kingdom
Post-Brexit regulatory divergence from EASA frameworks forces dual-track engineering investments for OEMs seeking continental market access. National decarbonization mandates for regional aviation accelerate hybrid-electric feeder aircraft development. Cranfield aerospace clusters concentrate flight-test infrastructure for novel electric propulsion validation.
Light Electric Aircraft Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the light electric aircraft sector, with certificated OEMs commanding capital access that prototype-stage developers cannot match. The integrated tier leverages extensive flight-test infrastructure and regulatory relationships to compress certification timelines. Specialist archetypes include propulsion-technology innovators, regional manufacturing-scale platforms, and training-segment volume suppliers. Competitive moves concentrate on strategic partnerships for battery supply security and geographic expansion into designated urban air mobility corridors.
Within the integrated tier, Airbus SE and Joby Aviation exemplify divergent strategic positions—European conglomerate diversification against pure-play certification momentum. Lilium occupies a position within the propulsion-technology specialist archetype through its German manufacturing base. Pipistrel d.o.o. anchors the training-segment volume tier with Slovenian production scale.
| Leading Market Players |
|---|
| Airbus SE |
| Joby Aviation |
| Lilium |
| Eviation |
| Pipistrel d.o.o. |
| Ampaire Inc. |
| Heart Aerospace |
| Bye Aerospace |
| AeroVironment, Inc. |
| Others |
Value Chain & Pricing Dynamics
Solid-state battery chemistry maturation is displacing conventional lithium-ion procurement patterns, simultaneously shifting cathode material sourcing toward Korean and Japanese pilot lines while compressing pricing premiums for extended-range aircraft configurations.
Pricing Analysis
After-sales battery replacement contracts and maintenance subscriptions drive lifetime value capture across the installed base. Three-tier pricing structure across premium certified platforms, standard training aircraft, and economy ultralight tiers reflects FAA and EASA certification grade differentiation. Cost compression in the economy tier intensifies because flight training schools in Slovenia and the Czech Republic consolidate fleet orders around bundled hourly rates. Cargo operators show lowest price sensitivity, absorbing premium positioning for hybrid-electric range extension.
Supply Chain Analysis
China and South Korea anchor cathode material processing and cell manufacturing capacity for lithium-ion supply. OEMs draw from nickel-cobalt-manganese cathode formulations and silicon-carbide power semiconductors as critical inputs. Single-source vulnerability concentrates in Chinese export control exposure for processed cathode materials. Distribution runs through direct OEM-to-operator fleet leasing arrangements that displace traditional distributor networks in the training segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification backlog cycles position this market for cyclical recovery as FAA and EASA qualified flight-test personnel shortages create pent-up validation demand.
For Market Incumbents: Fortify battery supply security through captive offtake agreements with Korean and Japanese solid-state pilot lines. Deepen upstream control over thermal management system manufacturing to defend margins against prototype-stage competitors facing EASA SC-VTOL containment cost burdens.
For New Entrants and Emerging Players: Urban air mobility corridor service gaps in German municipalities present white-space entry points where incumbent multirotor OEMs under-serve regional connectivity networks. Target cargo feeder operations in US Inflation Reduction Act incentive zones with turbogenerator-assisted hybrid platforms. Pursue direct fleet leasing contracts with European training academies as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed propulsion-technology specialists holding EASA certification momentum but constrained manufacturing scale. Long-term viability over the next decade hinges on solid-state battery integration timelines and regulatory harmonization progress. Monitor FAA-EASA battery thermal-runaway test protocol convergence as the critical inflection signal for dual-certified platform market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Timeline Acceleration | Locking FAA Part 23 baselines before EASA divergence widens compresses validation costs for tiltrotor developers. |
| Battery Supply Agreement | Korean solid-state pilot line offtakes secure cathode material access insulated from Chinese export volatility. |
| Vertiport Infrastructure Partnership | Munich and Hamburg municipal landing zone designations create captive demand corridors for multirotor operators. |
| Flight-Test Infrastructure Expansion | Cranfield and Ajdovščina validation centers reduce certification engineer scarcity bottlenecks for novel architectures. |
| Hybrid-Electric Platform Launch | Turbogenerator-assisted cargo configurations capture margin pools where pure-electric range falls short of mission requirements. |
Study Parameters
A standing panel of FAA certification engineers, EASA flight-test directors, battery procurement leads at OEMs, and urban air mobility fleet operators provided ongoing calibration across the study period. Primary interviews with Slovenian training academy contract managers and German vertiport infrastructure planners combined with secondary validation against FAA Part 23 rewrite documentation, EASA SC-VTOL special condition filings, EU Green Deal aviation decarbonization target releases, and US Inflation Reduction Act clean-vehicle incentive guidance. Bottom-up fleet order aggregation and top-down market sizing triangulated volume estimates.
Consistency checks validated outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, end user, technology, and application, with additional granularity on certification pathway and battery chemistry generation. CAGRs derived from installed base turnover rates and fleet replacement cycle analysis. Forecast inputs incorporated solid-state battery energy density improvement curves and regulatory harmonization probability assessments.
Underlying assumptions cover EASA-FAA certification timeline convergence and cathode material supply continuity, with deviation risk concentrated in export control escalation and qualified flight-test personnel availability. Recalibration cycles align with material shifts in battery chemistry maturation and special condition framework updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Regional Jet Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Electric Aircraft Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
North America Aviation Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
North America General Aviation Market