
 Asia-Pacific Airport Baggage Handling Systems Market | 2026-2036
Asia-Pacific Airport Baggage Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Airport Baggage Handling Systems Market Outlook
Low-cost carrier terminal expansion is decoupling from legacy full-service baggage infrastructure specifications, creating demand for modular, high-throughput systems optimized for narrow-body turnaround times. Siemens Logistics leverages its German-engineered sortation platforms to anchor major hub deployments across China and Southeast Asia. Daifuku competes through deep manufacturing scale in automated material handling, while Vanderlande Industries differentiates via integrated software-hardware suites for real-time baggage tracking.
Asia-Pacific airport baggage handling systems encompass the electromechanical and software infrastructure that conveys, sorts, and tracks checked luggage from check-in through aircraft loading, typically operating at belt speeds of 0.5–2.5 meters per second with RFID read rates exceeding 99.5 percent in modern installations. Conveyor systems remain the volume backbone across existing terminals, though sortation systems capture expanding share where hub airports require destination-coded vehicle processing above 4,000 bags per hour. Robotics and automated guided vehicles represent the fastest-growing technology layer, particularly for late-night narrow-body repositioning where labor availability constrains ground operations.
China's MIIT enforces GB standards for industrial equipment energy consumption, directly shaping motor and drive specifications for new conveyor installations, while Japan's METI promotes JIS-compliant IoT integration standards that influence technology procurement by Japanese airport operators. Australia's TGA-equivalent infrastructure safety frameworks and India's BIS electrical certification requirements add compliance layers for multinational vendors. Stakeholders must weigh modular capacity expansion against full-system replacement cycles as passenger recovery trajectories diverge across the region's aviation markets.
Market Dynamics
Electrification mandates across China and Japan are forcing terminal operators to replace legacy pneumatic and hydraulic conveyor drives with permanent magnet motor systems, compressing replacement cycles from fifteen years to eight.
Growth Catalysts
- China's Dual Carbon Goals:MIIT-enforced GB energy-efficiency standards for industrial motors accelerate conveyor modernization in Beijing Daxing and Chengdu Tianfu greenfield terminals.
- Narrow-body fleet expansion:Low-cost carriers across Indonesia, Vietnam, and the Philippines demand high-throughput sortation modules optimized for sub-30-minute turnaround windows.
- RFID mandate adoption:IATA Resolution 753 compliance drives real-time baggage tracking investments in Singapore Changi and Hong Kong International hub upgrades.
Market Restraints
- Copper and rare earth price volatility:Permanent magnet motor supply chains concentrate in Chinese processing facilities, exposing procurement costs to export quota fluctuations.
- Proprietary software lock-in:Integrated control systems from established vendors create switching costs that deter modular best-of-breed procurement strategies.
- Subsurface infrastructure constraints:Legacy terminals in Tokyo Narita and Sydney Kingsford Smith lack vertical clearance for modern tilt-tray sortation retrofits.
Strategic Opportunities
- Vietnam's Long Thanh International:Greenfield construction outside Ho Chi Minh City creates demand for fully automated early baggage storage and autonomous vehicle networks without legacy system integration burden.
- India's UDAN regional connectivity scheme:Tier-2 airport expansions in Lucknow, Jaipur, and Coimbatore favor scalable modular conveyor systems over capital-intensive destination-coded vehicle installations.
- Japan's METI IoT integration subsidies:JIS-compliant digital twin platforms for predictive maintenance attract public-private partnership funding for Kansai and Chubu Centrair modernization programs.
Industry Challenges
- Mechatronics technician scarcity:Belt alignment, encoder calibration, and servo drive troubleshooting skills lag demand across Southeast Asian maintenance labor pools.
- Multi-vendor system integration:Retrofitting RFID interrogators onto 1990s-era conveyor architectures requires custom middleware development that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Airport Baggage Handling Systems Market |
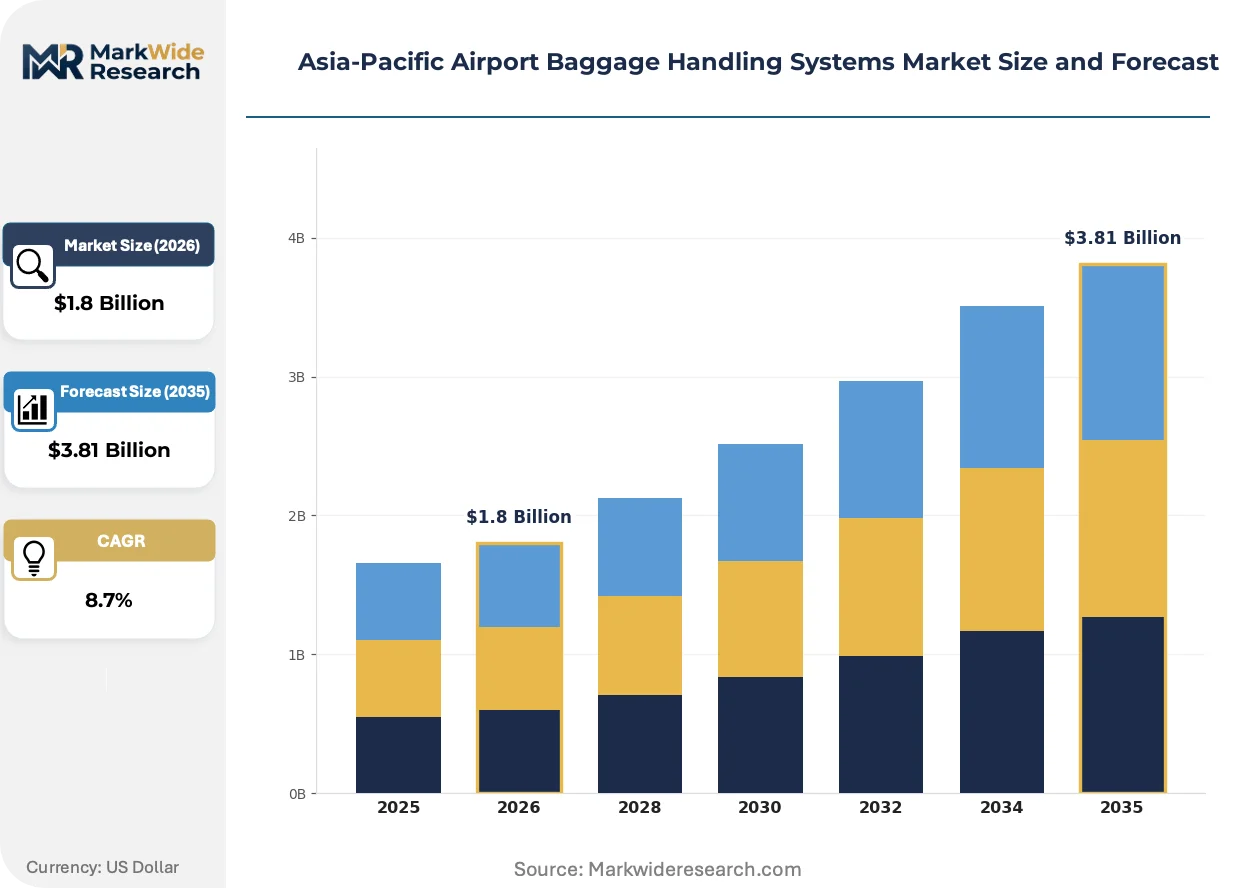
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Conveyor Systems, Sortation Systems, Robotics, Automated Guided Vehicles End User: Airports, Airlines, Ground Handling Companies, Logistics Providers Technology: RFID, Barcode, IoT, Traditional Tracking Capacity: High Capacity, Medium Capacity, Low Capacity, Modular Systems |
| Companies Covered | Siemens Logistics, CIMC TianDa, Vanderlande Industries, Leonardo, Unisys Corporation, Daifuku, SITA, Ansir Systems, BEUMER Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Airport Baggage Handling Systems Market Strategic Shifts
Automation architectures are converging around software-defined material handling, where control logic migrates from dedicated PLCs to edge-computing nodes. This shift compresses commissioning cycles and enables remote diagnostics across distributed terminal networks.
Autonomous guided vehicles with LiDAR navigation and fleet management software are automating late-night narrow-body repositioning at hubs including Seoul Incheon and Bangkok Suvarnabhumi. Ground handlers adopt these systems where labor availability constraints limit manual tug operations during 0200-0600 windows. The technology is automating baggage tractor pools and compressing ground support equipment headcount targets.
China's MIIT GB 30253-2013 motor efficiency standards and subsequent 2020 amendments now classify baggage conveyor drives as priority equipment for permanent magnet synchronous motor retrofits. Terminal operators in Shanghai Pudong and Guangzhou Baiyun face compliance audits that accelerate capital allocation toward magnet-based drive systems. Japanese airport operators observe these technical specifications as de facto benchmarks for their own energy reduction commitments under METI carbon neutrality roadmaps.
Airport procurement departments are unbundling long-term service contracts from initial system purchases, shifting toward performance-based maintenance agreements with uptime guarantees. This model disrupts traditional bundled vendor relationships and favors independent service providers with predictive analytics capabilities. The pattern is most visible in Australian terminal privatizations where infrastructure funds demand operational expenditure transparency.
Asia-Pacific Airport Baggage Handling Systems Market Segmentation
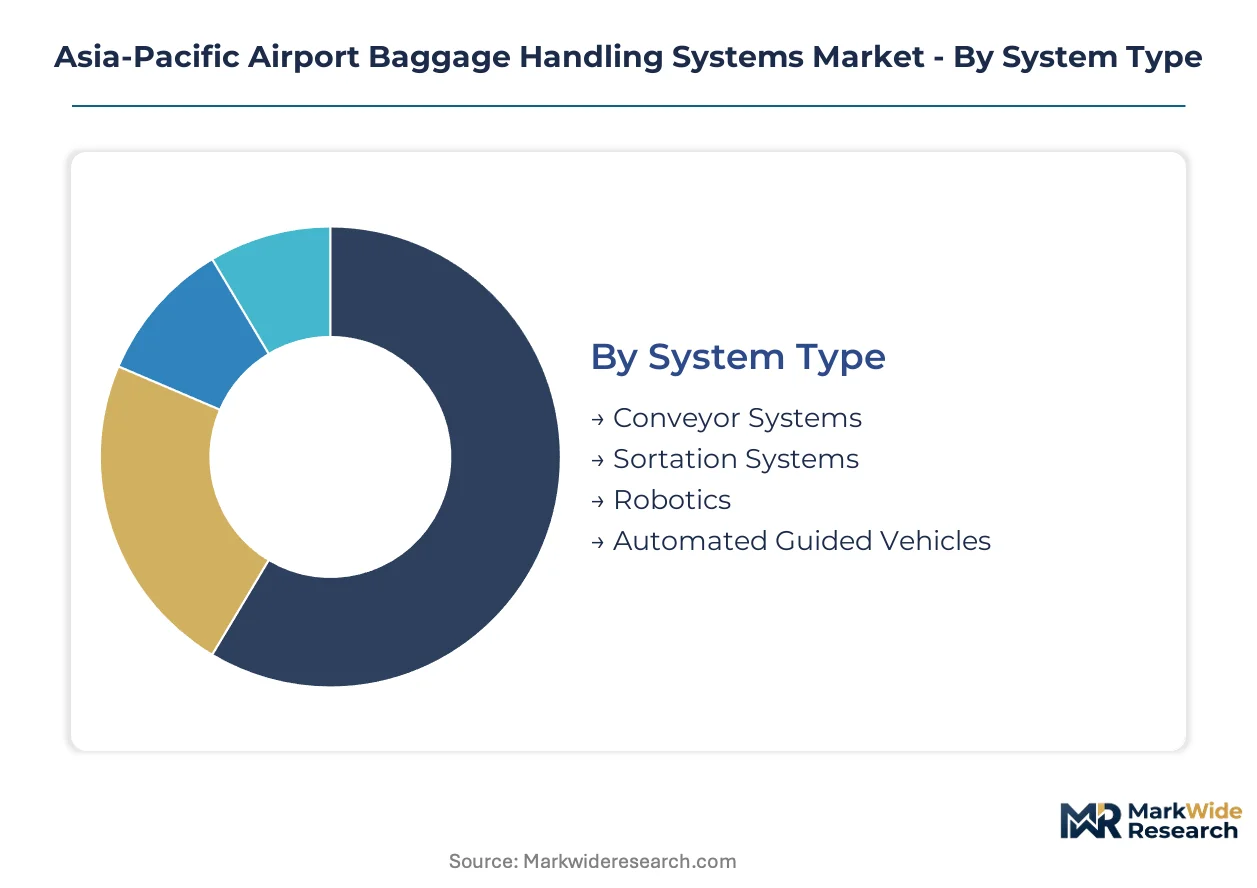
Segmentation across the Asia-Pacific Airport Baggage Handling Systems Market reveals distinct procurement patterns between greenfield terminals and legacy modernization projects. Equipment specifications diverge sharply based on passenger throughput targets, regulatory compliance timelines, and integration depth with existing terminal infrastructure.
System Type:
Standalone conveyor installations dominate brownfield retrofits where operators seek incremental capacity without full system replacement. Embedded sortation and robotics modules require deeper architectural integration, typically reserved for new-build terminals with unified control system design.
- Conveyor Systems:Belt-driven electromechanical infrastructure operating at 0.5–2.5 meters per second forms the volume backbone across existing terminals. Demand concentrates in India's UDAN-tier airport expansions where modular conveyor retrofits offer lower capital intensity than full sortation overhauls.
- Sortation Systems:Tilt-tray and cross-belt destination-coded vehicle platforms process above 4,000 bags per hour. China's Beijing Daxing and Chengdu Tianfu greenfield terminals deploy these as embedded centerpieces of unified baggage halls, driven by MIIT energy-efficiency mandates for permanent magnet motor integration.
- Robotics:Articulated arm systems for irregular item handling and containerization operate as standalone workcells alongside conventional conveyors.
- Automated Guided Vehicles:LiDAR-navigated baggage tractors automate late-night narrow-body repositioning at Seoul Incheon and Bangkok Suvarnabhumi where labor availability constrains 0200-0600 ground operations.
Conveyor systems lead volumes today; automated guided vehicles are gaining share fastest.
End User:
Procurement authority varies by airport governance model—direct terminal operator ownership versus outsourced ground handling contracts shapes system specification and vendor selection criteria.
- Airports:Terminal infrastructure owners specify backbone conveyor and sortation architecture in greenfield projects. Vietnam's Long Thanh International procurement favors unified system ownership without legacy integration burden.
- Airlines:Carrier-specific investments concentrate on check-in counter automation and priority baggage handling lanes. Low-cost carriers across Indonesia and the Philippines drive demand for sub-30-minute turnaround-optimized modules.
- Ground Handling Companies:Third-party operators procure autonomous vehicle fleets and late-stage make-up area equipment under performance-based service contracts.
- Logistics Providers:Integrated cargo-baggage hybrid handlers invest in tracking infrastructure for multimodal connectivity.
Airports control capital-intensive backbone investments; ground handling companies are expanding equipment ownership fastest.
Technology:
Tracking technology selection follows IATA compliance mandates and national regulator procurement preferences, with integration complexity rising from optical to radio-frequency architectures.
- RFID:IATA Resolution 753-compliant baggage tags with 99.5 percent read rates in modern installations. Singapore Changi and Hong Kong International hub upgrades prioritize RFID for real-time tracking compliance.
- Barcode:Legacy optical character recognition systems persist in cost-constrained tier-2 terminals. India's BIS certification requirements influence barcode scanner procurement specifications for regional connectivity scheme airports.
- IoT:Sensor networks and digital twin platforms for predictive maintenance attract Japan METI subsidy funding at Kansai and Chubu Centrair modernization programs.
- Traditional Tracking:Manual scan-and-log systems remain in aging infrastructure awaiting replacement cycle triggers.
Barcode systems retain installed base dominance; IoT platforms are climbing the fastest.
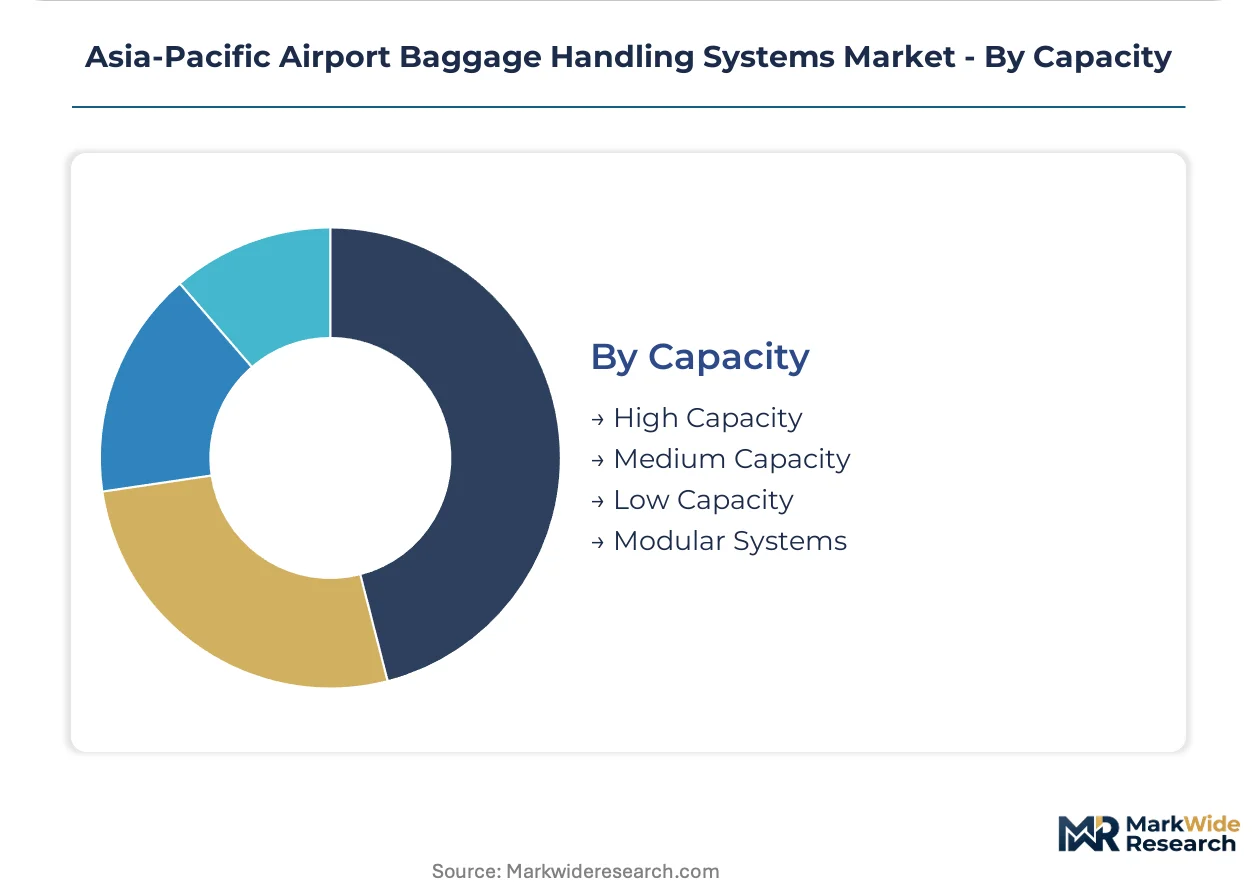
Capacity:
Throughput specification aligns with terminal scale and fleet mix, with modular architectures enabling phased expansion without full system redundancy.
- High Capacity:Systems processing above 6,000 bags per hour serve international hub terminals with wide-body dominant operations. China's dual carbon goals accelerate permanent magnet motor retrofits in Shanghai Pudong and Guangzhou Baiyun high-throughput halls.
- Medium Capacity:2,000–6,000 bags per hour configurations suit secondary hub and major domestic terminals. Australia's TGA-equivalent safety frameworks shape medium-capacity system certification requirements.
- Low Capacity:Sub-2,000 bags per hour installations address regional and general aviation terminals with limited peak demand.
- Modular Systems:Scalable conveyor and sortation units allow capacity expansion through standardized component addition rather than full replacement.
High capacity systems anchor hub terminal investments; modular systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal operators across Asia-Pacific migrate procurement toward jurisdictions with harmonized energy-efficiency standards, compressing vendor qualification cycles and reducing compliance arbitrage costs between national markets.
China
Greenfield terminals at Beijing Daxing and Chengdu Tianfu deploy unified baggage halls with embedded sortation cores. MIIT enforces GB 30253-2013 motor efficiency standards that classify conveyor drives as priority equipment for permanent magnet synchronous retrofits. Shanghai Pudong and Guangzhou Baiyun face compliance audits accelerating capital allocation toward magnet-based systems.
Japan
METI promotes JIS-compliant IoT integration standards influencing technology procurement by airport operators at Kansai and Chubu Centrair. Subsidy funding attracts public-private partnerships for digital twin platforms enabling predictive maintenance. Tokyo Narita's legacy subsurface constraints limit tilt-tray sortation retrofits despite modernization pressure.
India
Tier-2 expansions under the UDAN regional connectivity scheme favor scalable modular conveyor systems over capital-intensive destination-coded vehicle installations. BIS electrical certification requirements shape procurement specifications for airports in Lucknow, Jaipur, and Coimbatore. Ground handlers face mechatronics technician scarcity across maintenance labor pools.
Vietnam
Long Thanh International greenfield construction outside Ho Chi Minh City creates demand for fully automated early baggage storage without legacy system integration burden. Low-cost carrier terminal specifications decouple from full-service baggage infrastructure standards. Procurement favors autonomous vehicle networks optimized for narrow-body turnaround windows.
Australia
TGA-equivalent infrastructure safety frameworks shape medium-capacity system certification requirements for terminal privatizations. Infrastructure funds demand operational expenditure transparency, unbundling long-term service contracts from initial system purchases. Performance-based maintenance agreements with uptime guarantees disrupt traditional bundled vendor relationships.
Asia-Pacific Airport Baggage Handling Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated system architects dominating hub terminal greenfields while modular component suppliers capture brownfield retrofit volumes. Market structure concentrates around three strategic archetypes: German-engineered sortation platform providers, Japanese automated material handling scale manufacturers, and software-hardware integration specialists. Competitive positioning hardens through M&A consolidation of regional service networks and strategic partnerships securing permanent magnet motor supply chains.
Among Asia-Pacific active suppliers, Siemens Logistics anchors the German-engineered tier, Daifuku occupies the Japanese manufacturing scale position, and Vanderlande Industries exemplifies the integrated software-hardware suite archetype. These three represent distinct technical lineages competing for hub terminal deployments across China and Southeast Asia, each leveraging home-market regulatory alignment to accelerate qualification cycles in export markets.
| Leading Market Players |
|---|
| Siemens Logistics |
| CIMC TianDa |
| Vanderlande Industries |
| Leonardo |
| Unisys Corporation |
| Daifuku |
| SITA |
| Ansir Systems |
| BEUMER Group |
| Others |
Value Chain & Pricing Dynamics
Greenfield airport procurement programs across China and Vietnam concentrate buying power among state-owned terminal operators, compressing vendor margins through bundled tender specifications that demand permanent magnet motor compliance and IoT integration as baseline requirements rather than premium upgrades.
Pricing Analysis
Distributor margins in legacy terminal retrofits absorb 12-18 percentage points before equipment reaches brownfield operators, while direct-to-OEM contracts for greenfield hubs eliminate intermediary layers entirely. Project-based pricing dominates, with three-tier pricing structure across premium, standard, and economy levels differentiated by automation depth and software integration scope. Cost compression in conveyor drive retrofits is intensifying because MIIT compliance audits force accelerated replacement cycles. Tier-2 airport operators under India's UDAN scheme exhibit highest price sensitivity, whereas Chinese international hub terminals prioritize energy-efficiency specifications over unit cost.
Supply Chain Analysis
GB 30253-2013 motor efficiency certification and JIS IoT integration standards gate supplier qualification, extending vendor onboarding timelines by 8-14 months for non-compliant manufacturers. Permanent magnet motor production concentrates in China, Japan, and South Korea, with rare earth processing drawing from Chinese refining facilities. Neodymium, dysprosium, and copper windings constitute critical input dependencies. Single-source vulnerability in rare earth supply chains exposes procurement costs to export quota volatility. Distribution runs through regional system integrators with established maintenance networks across Southeast Asian aviation corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MIIT's GB 30253-2013 motor efficiency mandates and IATA Resolution 753 RFID compliance deadlines create synchronized replacement demand across China's hub terminal infrastructure.
For Market Incumbents: Anticipate margin compression in conveyor retrofits as Chinese state-owned operators unbundle long-term service contracts from initial system purchases. Siemens Logistics and Daifuku should deepen captive supply of permanent magnet synchronous motors through backward integration into rare earth magnet partnerships, insulating procurement costs from export quota volatility. Software-hardware integration specialists must defend against modular best-of-breed procurement strategies by embedding predictive maintenance platforms as subscription revenue anchors. For New Entrants and Emerging Players: Launch via independent service provider models targeting Australian terminal privatizations where infrastructure funds demand operational expenditure transparency and uptime-guaranteed performance contracts. Vietnam's Long Thanh International greenfield construction offers the most penetrable entry point, with autonomous vehicle networks for narrow-body repositioning representing an underserved specification layer. Pursue public-private partnership structures aligned with Japan's METI IoT integration subsidies to bypass capital-intensive system ownership barriers. For Investors and Strategic Acquirers: Airport infrastructure funds and sovereign wealth vehicles with aviation mandates are the most active acquirer in this space, consolidating regional service networks to capture recurring maintenance revenue streams. Target mid-scale automated material handling specialists with established BIS certification for India's UDAN-tier expansion pipeline. Watch for inflection in copper and rare earth price volatility as the signal triggering accelerated vendor consolidation or vertical integration moves.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Retrofit Programs | MIIT compliance audits at Shanghai Pudong and Guangzhou Baiyun accelerate capital allocation toward magnet-based drive systems. |
| IoT Integration Subsidy Capture | METI funding attracts public-private partnerships for digital twin platforms at Kansai and Chubu Centrair modernization programs. |
| Autonomous Vehicle Fleet Deployment | LiDAR-navigated baggage tractors automate late-night narrow-body repositioning at Seoul Incheon and Bangkok Suvarnabhumi. |
| Modular Conveyor System Expansion | India's UDAN-tier airports in Lucknow, Jaipur, and Coimbatore favor scalable units over destination-coded vehicle installations. |
| Performance-Based Maintenance Unbundling | Australian terminal privatizations disrupt traditional bundled vendor relationships through uptime-guaranteed service contracts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airport procurement directors, ground handling operations managers, mechatronics maintenance heads, and OEM system integration engineers with secondary validation through IATA baggage tracking compliance databases, MIIT equipment certification registries, METI subsidy program disclosures, and customs records for permanent magnet motor imports. Bottom-up installation tracking across 40+ terminal projects triangulated against top-down market sizing from aviation authority capital expenditure disclosures.
Historical reference periods anchored the forecast window to pre-pandemic throughput baselines and recovery trajectory divergence patterns across the region's aviation markets. Segmentation dimensions modeled include system type, end-user governance structure, tracking technology tier, and capacity throughput specification alongside greenfield versus brownfield procurement archetype. CAGRs were derived from equipment replacement cycle compression analysis and passenger throughput elasticity assumptions, with permanent magnet motor adoption curves and RFID mandate compliance timelines serving as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged copper and rare earth price volatility or accelerated electrification mandate expansion beyond current MIIT and METI frameworks. A model refresh is warranted upon material change in dual carbon policy enforcement intensity or IATA Resolution 753 compliance deadline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Advanced Airport Technologies Market