
 Military Robotics Market | 2026-2036
Military Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Military Robotics Market Outlook
Modular payload architectures is decoupling sensor packages from base platforms, letting buyers configure mission-specific variants without full system replacement. Lockheed Martin Corporation leverages this flexibility across its unmanned portfolio, sustaining upgrade revenue streams. BAE Systems anchors European supply through sovereign manufacturing lines in the United Kingdom. Elbit Systems Ltd. differentiates via vertical integration into tactical computing and electro-optics.
Military robotics encompasses autonomous and teleoperated machines engineered for combat support, reconnaissance, and force protection, typically integrating hardened communications, multi-spectral sensing, and decision-assistance algorithms operating in GPS-denied environments. Unmanned Aerial Vehicles dominate current procurement volumes due to mature supply chains and proven ISR utility, while Autonomous Underwater Vehicles represent the fastest-expanding category as naval powers prioritize seabed warfare and mine countermeasures. Artificial Intelligence and Sensor Fusion technologies concentrate margin pools where software-defined targeting and multi-source data integration create vendor lock-in.
The U.S. Department of Defense, the U.K. Ministry of Defence, and NATO standardization bodies collectively shape market access through autonomous systems ethics guidelines, interoperability mandates, and export control frameworks. These regulations restrict technology transfer to allied nations while accelerating domestic R&D investment in trusted AI and secure communications. Stakeholders must monitor evolving lethal autonomous weapons governance and position compliance capabilities ahead of anticipated procurement qualification shifts.
Market Dynamics
The U.S. Department of Defense's ethical AI guidelines and NATO interoperability mandates are compressing vendor qualification timelines while fragmenting procurement across sovereign supply chains. Defense ministries now demand hardened communications and trusted AI certifications as baseline market entry requirements.
Growth Catalysts
- Explosive Ordnance Disposal Modernization:NATO member states are fielding autonomous ground systems for route clearance and bomb disposal missions, replacing legacy teleoperated platforms with semi-autonomous alternatives.
- Seabed Warfare Prioritization:Naval powers are accelerating Autonomous Underwater Vehicle procurement for mine countermeasures and critical infrastructure protection, driven by contested underwater domain awareness requirements.
- Trusted AI Investment:The U.S. Department of Defense's Responsible AI Guidelines are channeling R&D funding toward explainable decision-assistance algorithms and secure edge computing architectures.
Market Restraints
- Rare Earth Magnet Concentration:Permanent magnet supply for precision actuators concentrates in Chinese processing facilities, exposing Western defense primes to export restriction vulnerability.
- ITAR Compliance Burden:U.S. International Traffic in Arms Regulations impose multi-year technology transfer approval timelines, limiting allied co-development and foreign market access.
- Swarm Coordination Limitations:Current tactical data links lack bandwidth and latency performance for large-scale autonomous vehicle coordination in contested electromagnetic environments.
Strategic Opportunities
- Australian Sovereign Industrial Capability:The AUKUS security pact is opening Australian defense manufacturing for unmanned maritime systems with guaranteed offtake from the Royal Australian Navy.
- Human-Machine Teaming Standards:NATO STANAG development for manned-unmanned teaming protocols creates first-mover advantage for platforms demonstrating certified interoperability.
- Swappable Payload Architectures:Modular sensor and effector integration is enabling single-platform multi-mission configurations, expanding addressable mission sets without fleet expansion.
Industry Challenges
- Autonomy Software Talent Scarcity:Defense contractors face acute competition with commercial autonomous vehicle developers for robotics perception and reinforcement learning specialists.
- Cross-Domain Certification Complexity:Airworthiness, seaworthiness, and ground vehicle safety standards require parallel qualification tracks, extending development cycles and inflating program costs.
- Legacy System Integration Friction:New autonomous platforms must interface with decades-old command-and-control networks using proprietary protocols, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Robotics Market |
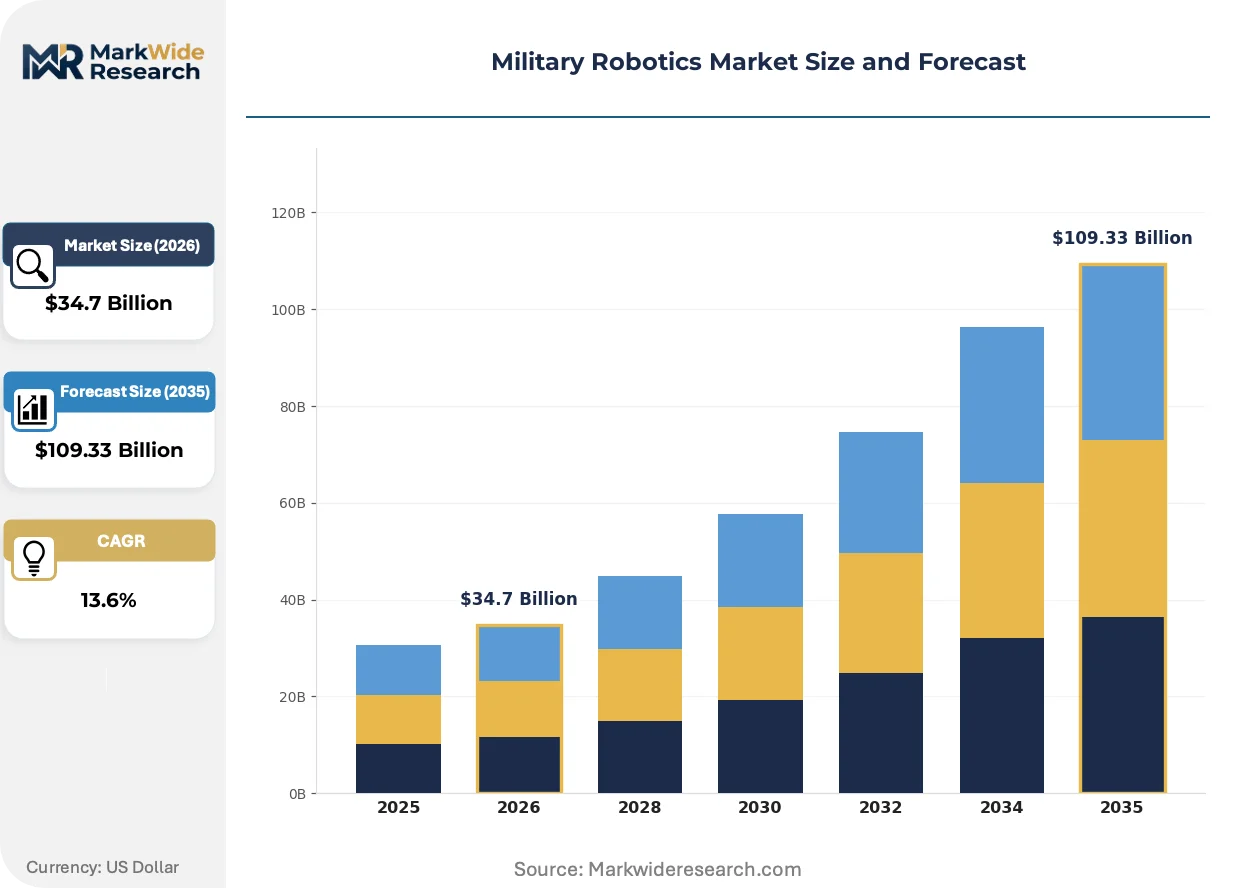
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $109.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Ground Vehicles, Unmanned Aerial Vehicles, Autonomous Underwater Vehicles, Tactical Robots Technology: Artificial Intelligence, Machine Learning, Computer Vision, Sensor Fusion Application: Surveillance, Reconnaissance, Explosive Ordnance Disposal, Logistics End User: Defense Agencies, Military Forces, Government Contractors, Research Institutions |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, BAE Systems, General Dynamics Corporation, Elbit Systems Ltd., AeroVironment, Inc., Thales Group, QinetiQ, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Robotics Market Strategic Shifts
Software-defined targeting and multi-source sensor fusion are displacing hardware-centric platform competition, concentrating margin capture in algorithm and data pipeline vendors. Defense procurement is pivoting toward capability-as-a-service models that emphasize persistent software upgrade revenue over single-platform sales.
Edge-deployed machine learning inference engines are integrating real-time target recognition and threat prioritization directly onto unmanned platforms, eliminating dependency on contested satellite uplinks. The U.S. Army's Robotic Combat Vehicle program is accelerating fielding of these capabilities, compressing the sensor-to-shooter timeline from minutes to seconds. This architecture is integrating third-party algorithm providers into prime contractor supply chains, fragmenting traditional platform-centric value capture.
The EU AI Act's high-risk system classification is imposing conformity assessment requirements on lethal autonomous weapons development, forcing European defense contractors into dual-track compliance investments. BAE Systems and Rheinmetall are establishing separate AI governance offices to manage documentation burdens. Naval autonomous systems face the most stringent scrutiny, with France's Direction Générale de l'Armement requiring explainability audits for underwater targeting algorithms.
Defense ministries are unbundling platform acquisition from sustainment and software update contracts, creating recurring revenue pools for vendors demonstrating continuous algorithm improvement. The U.K. Ministry of Defence's Maritime Autonomous Systems program pioneered this structure, separating hull procurement from autonomy software licensing. Israel Defense Forces procurement exhibits the most advanced adoption, with multi-year software subscription frameworks now standard for unmanned aerial system fleets.
Military Robotics Market Segmentation
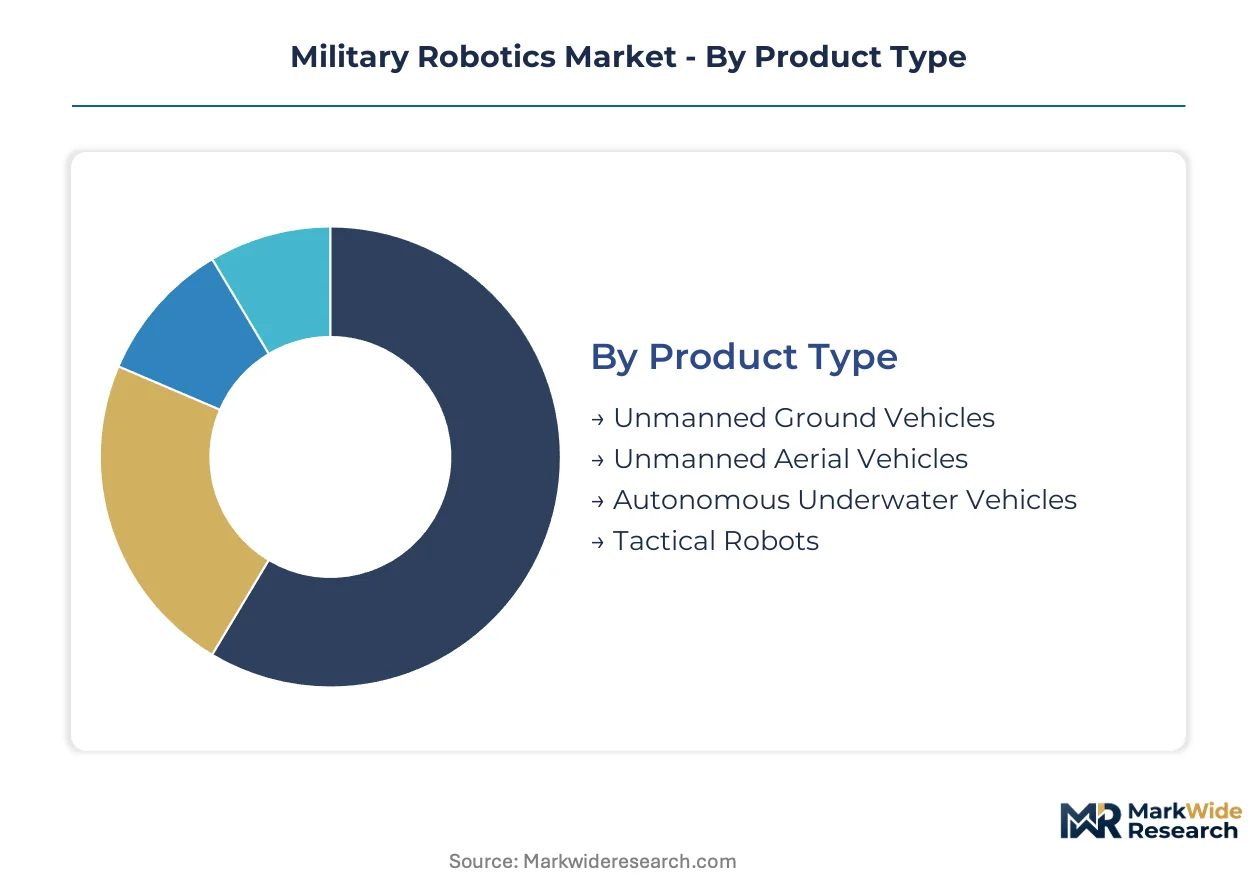
Military robotics procurement fragments across platform types, autonomy technologies, mission applications, and institutional buyers. Each segmentation dimension carries distinct qualification requirements, supply chain dependencies, and margin structures that reshape vendor positioning.
Product Type:
Platform manufacturing concentrates in defense primes with sovereign production lines, while subsystem suppliers fragment across specialized component tiers.
- Unmanned Aerial Vehicles:Fixed-wing and rotary-wing systems integrate hardened communications and multi-spectral payloads for ISR missions. The United States, Israel, and the United Kingdom sustain the highest procurement volumes, driven by contested airspace operations and counter-insurgency requirements.
- Autonomous Underwater Vehicles:Pressure-hulled platforms with acoustic navigation and seabed mapping sensors operate in GPS-denied environments. Naval powers in the Pacific and North Atlantic prioritize mine countermeasures and critical infrastructure protection, accelerating category expansion.
- Unmanned Ground Vehicles:Tracked and wheeled platforms with modular armor packages execute route clearance and logistics support.
- Tactical Robots:Man-portable systems with manipulator arms and disruptor mounts specialize in close-quarters explosive ordnance disposal.
Unmanned Aerial Vehicles absorb the bulk of installed capacity; Autonomous Underwater Vehicles are expanding most quickly.
Technology:
Software development talent scarcity concentrates capability in defense hubs with proximity to research institutions and classified computing facilities.
- Artificial Intelligence:Explainable decision-assistance algorithms enable autonomous target recognition and threat prioritization without human-in-the-loop latency. The U.S. Department of Defense's Responsible AI Guidelines channel R&D funding toward trusted edge computing architectures that satisfy procurement qualification.
- Sensor Fusion:Multi-source data integration combines electro-optical, radar, and signals intelligence into unified situational awareness displays. NATO standardization bodies mandate interoperability protocols, creating vendor lock-in for certified integration frameworks.
- Machine Learning:Reinforcement learning models optimize path planning and obstacle avoidance in dynamic terrain.
- Computer Vision:Real-time object detection and classification algorithms process thermal and visible-spectrum imagery.
Sensor Fusion commands premium pricing in platform integration contracts; Artificial Intelligence is climbing the fastest as explainability requirements reshape procurement specifications.
Application:
Mission profiles determine payload configurations, communications architectures, and operational tempo requirements that cascade through supply chain specifications.
- Explosive Ordnance Disposal:Semi-autonomous ground platforms with precision manipulators and disruptor mounts replace teleoperated legacy systems for route clearance. NATO member states field these capabilities for force protection in contested logistics corridors, with the United Kingdom and Germany expanding fleet modernization programs.
- Surveillance:Persistent aerial and maritime platforms with signals intelligence suites monitor border regions and exclusive economic zones. Israel Defense Forces procurement drives volume through multi-year software subscription frameworks that emphasize continuous algorithm improvement.
- Reconnaissance:Deep-penetration platforms with low-observable signatures and beyond-line-of-sight communications penetrate denied areas.
- Logistics:Autonomous convoy systems and warehouse robotics reduce personnel exposure in sustainment operations.
Surveillance dominates current fleet deployment; Explosive Ordnance Disposal is gaining share fastest as semi-autonomous capabilities mature.
End User:
Institutional procurement authority determines contract structures, security clearance requirements, and technology transfer restrictions that segment vendor access.
- Defense Agencies:National ministries and joint commands issue platform requirements through competitive tender processes with sovereign industrial participation mandates. The U.K. Ministry of Defence separates hull procurement from autonomy software licensing, creating recurring revenue pools for algorithm vendors.
- Military Forces:Service branches with operational deployment authority prioritize field reliability and maintenance interoperability over specification optimization. The U.S. Army's Robotic Combat Vehicle program compresses sensor-to-shooter timelines through edge-deployed inference engines.
- Government Contractors:Prime and subsystem suppliers execute development contracts with cost-plus and fixed-price structures.
- Research Institutions:National laboratories and university-affiliated centers prototype next-generation autonomy concepts.
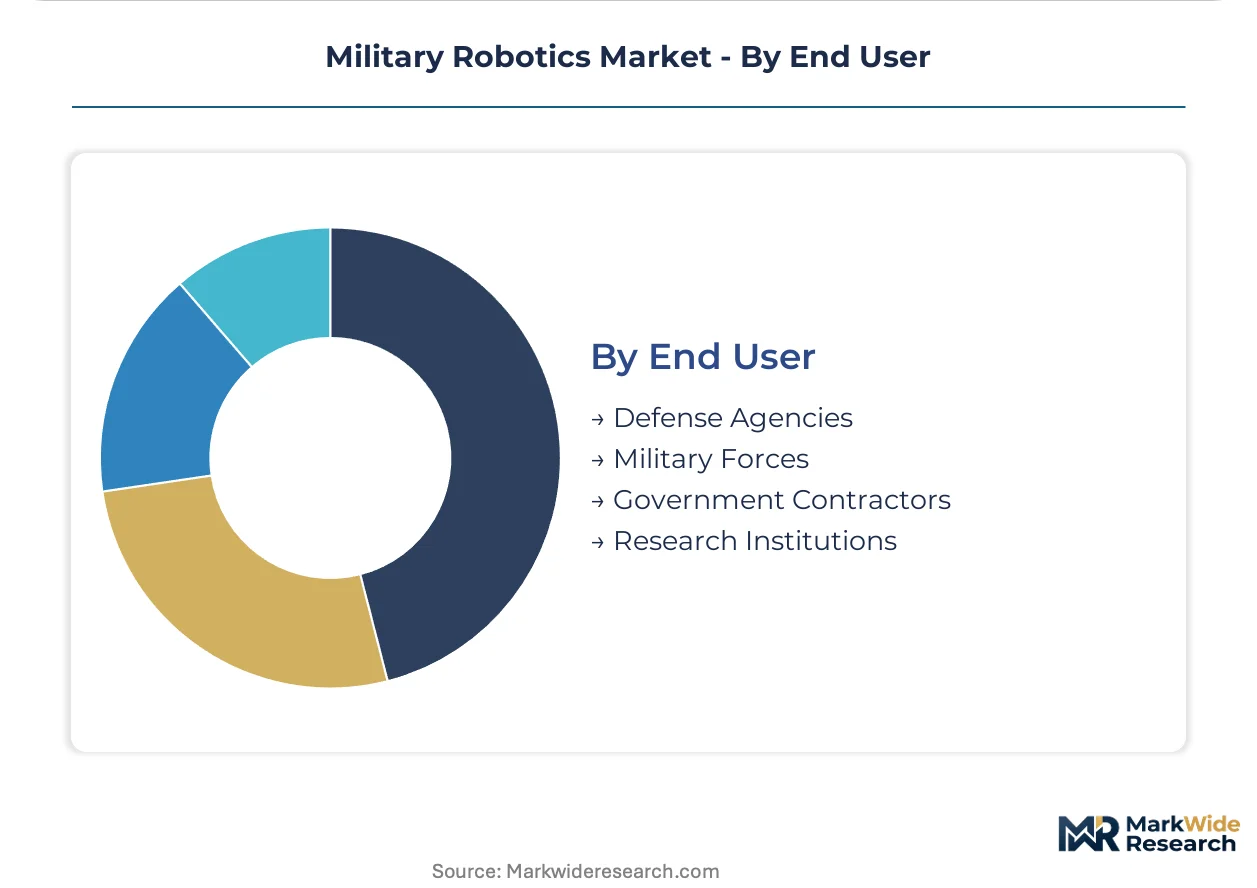
Defense Agencies control the majority of committed procurement budgets; Military Forces are expanding fastest as operational employment accelerates technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Defense Industrial Base Cybersecurity Zone and AUKUS-related special economic incentives are concentrating unmanned systems development in specific national clusters. Sovereign manufacturing mandates and export control frameworks now determine where primes establish production lines.
United States
The U.S. Department of Defense's Responsible AI Guidelines and Replicator initiative drive procurement volumes for autonomous platforms. ITAR compliance requirements channel foreign co-development through approved allied frameworks. Greater Boston and the National Capital Region host concentrated autonomy software development clusters serving prime contractors.
United Kingdom
The Ministry of Defence's Maritime Autonomous Systems program pioneered capability-as-a-service contracting structures. UK sovereign industrial capability mandates require domestic hull production for naval unmanned systems. Bristol and Portsmouth anchor submarine and surface drone manufacturing with dedicated test ranges.
Israel
Israel Defense Forces operational employment accelerates technology maturation through multi-year software subscription frameworks. The country's national defense regulator maintains strict technology transfer controls on autonomous targeting algorithms. Haifa and the Negev Desert host integrated development and live-fire test facilities.
Australia
The AUKUS security pact guarantees Royal Australian Navy offtake for sovereign unmanned maritime manufacturing. Australian sovereign industrial capability requirements open defense contracting to domestic platform assembly. Adelaide and Perth concentrate naval drone development with dedicated port infrastructure.
Germany
The Bundeswehr's explosive ordnance disposal modernization programs expand semi-autonomous ground vehicle procurement. KBA vehicle safety standards intersect with military airworthiness requirements for unmanned systems. Bavaria and Lower Saxony host prime contractor integration facilities with adjacent test ranges.
Military Robotics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across platform and subsystem tiers. Market structure concentrates in defense primes with sovereign production lines, while algorithm vendors fragment across specialized capability niches. Three archetypes dominate: vertically integrated platform primes, modular payload specialists, and autonomy software pure-plays. Competitive dynamics center on M&A for AI talent acquisition and strategic partnerships for sovereign manufacturing access.
Among U.S.-based diversified conglomerates, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify platform-centric positioning with integrated sovereign production. Elbit Systems Ltd. represents the vertically integrated specialist archetype with in-house electro-optics and tactical computing. BAE Systems anchors European supply through UK sovereign manufacturing lines, reflecting geographic diversification requirements.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| BAE Systems |
| General Dynamics Corporation |
| Elbit Systems Ltd. |
| AeroVironment, Inc. |
| Thales Group |
| QinetiQ |
| Boeing |
| Others |
Value Chain & Pricing Dynamics
Captive production of rare earth magnet processing in Chinese facilities anchors both component availability and cost structures for Western defense primes, concentrating pricing power with sovereign suppliers while forcing buyers into long-term offtake commitments or premium spot-market exposure.
Pricing Analysis
Short lead-time premiums for ITAR-cleared components command substantial markups over standard procurement cycles, while spot inventory of unclassified subsystems trades at discounts. Three-tier pricing structure across ITAR-restricted, NATO-cleared, and commercial-off-the-shelf levels reflects certification burden and technology transfer risk. Cost compression in unclassified sensor tiers is intensifying because commercial autonomous vehicle developers are absorbing defense-adjacent talent. Government contractors exhibit highest price sensitivity due to fixed-budget program structures, while defense agencies demonstrate lowest sensitivity where mission-critical specifications dominate.
Supply Chain Analysis
Defense-industrial qualification gates concentrate supplier access in facilities with existing security clearances and air-gapped manufacturing environments. Rare earth magnet processing concentrates in China, precision actuator manufacturing centers on Japan and Germany, and secure communications module assembly localizes in the United States and United Kingdom. Permanent magnet supply draws from Chinese processing facilities, gallium arsenide substrates from Taiwanese foundries, and precision optics from Israeli and German specialists. Single-source vulnerability in rare earth processing exposes Western primes to export restriction risk. Distribution runs through defense primes with sovereign manufacturing lines and approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. Department of Defense's Responsible AI Guidelines and ITAR frameworks erect substantial compliance moats, advantaging incumbents with established certification infrastructure and trusted facility networks while raising capital barriers for unqualified entrants.
For Market Incumbents: Anchor sovereign manufacturing capacity in AUKUS partner nations to secure offtake guarantees from the Royal Australian Navy and Royal Navy. Deepen backward integration into trusted AI development and secure edge computing to defend against autonomy software pure-plays fragmenting traditional platform value capture. ITAR compliance burden itself becomes a defensive asset when leveraged for exclusive allied co-development frameworks.
For New Entrants and Emerging Players: The gap between premium ITAR-cleared platforms and economy-tier commercial-off-the-shelf systems creates white-space for NATO-cleared mid-tier offerings. Target explosive ordnance disposal modernization programs in Germany and the United Kingdom, where semi-autonomous ground vehicle procurement is accelerating fastest. Pursue algorithm-as-a-service licensing to defense primes rather than full platform competition, exploiting the unbundling of hull procurement from autonomy software.
For Investors and Strategic Acquirers: Exit pathways concentrate in prime contractor acquisition of autonomy software specialists and sovereign manufacturing joint ventures. Long-term viability favors vendors with demonstrated compliance ahead of anticipated EU AI Act lethal autonomous weapons governance expansion. Target acquisition profile centers on explainable AI developers with existing NATO STANAG certification progress. Watch for lethal autonomous weapons governance shifts as the inflection indicator triggering consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Trusted AI Certification Investment | Positions vendors ahead of anticipated EU AI Act and U.S. DoD procurement qualification shifts. |
| Sovereign Manufacturing Joint Venture | Unlocks AUKUS offtake guarantees and satisfies UK Ministry of Defence domestic hull requirements. |
| Algorithm-as-a-Service Licensing | Captures recurring revenue from unbundled software contracts pioneered by Israeli Defense Forces procurement. |
| Modular Payload Architecture Development | Enables Lockheed Martin-style upgrade revenue streams across multi-mission platform configurations. |
| Rare Earth Magnet Supply Agreement | Mitigates Chinese export restriction exposure through Japanese or Australian alternative sourcing. |
Study Parameters
Multi-period observation of defense procurement announcements, program milestone disclosures, and regulatory guidance releases anchored the trend analysis, supplemented by interviews with program executives at prime contractors, autonomy software leads at defense startups, procurement officers at NATO standardization bodies, and supply chain managers at rare earth processing specialists. Secondary validation drew from U.S. Department of Defense budget justification documents, UK Ministry of Defence contract award notices, EU AI Act regulatory filings, and customs trade data on permanent magnet flows. Bottom-up platform deployment tallies and top-down defense R&D budget allocations were triangulated to constrain estimate ranges.
Segment-weighting applied differential growth assumptions across platform types, autonomy technology maturity tiers, and mission application criticality. The analytical framework modeled Unmanned Aerial Vehicles, Autonomous Underwater Vehicles, Unmanned Ground Vehicles, and Tactical Robots against Artificial Intelligence, Sensor Fusion, Machine Learning, and Computer Vision technology layers, further segmented by Explosive Ordnance Disposal, Surveillance, Reconnaissance, and Logistics applications. CAGRs were derived from fitted adoption curves reflecting program award velocity and operational deployment timelines. Forecast inputs incorporated U.S. Replicator initiative funding trajectories and AUKUS sovereign industrial capability mandates.
Inputs from defense ministry procurement databases and prime contractor segment disclosures were available through the study window; gaps in classified program budget detail and autonomous targeting algorithm performance specifications introduce uncertainty bands around penetration rate assumptions. Forecasts reflect modeling assumptions regarding ITAR compliance timeline stability and NATO interoperability mandate adoption velocity. A model refresh is warranted upon material change in lethal autonomous weapons governance frameworks or rare earth export restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Drone Jamming System Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
United States ROV Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market