
 Global Submarine Payload Market | 2026-2036
Global Submarine Payload Market Size, Share, and Industry Trends Forecast 2026-2036
Global Submarine Payload Market Foresight
Defense ministries with expeditionary undersea mandates are rotating procurement emphasis toward multi-mission payload suites. RTX Corporation leverages integrated sonar processing architectures to anchor contracts across NATO submarine programs. ThyssenKrupp Marine Systems sustains its position through captive design-to-build workflows for German and export hulls. Saab AB differentiates in compact payload integration for littoral diesel-electric platforms.
Submarine payload denotes the mission-specific equipment modules—sonar arrays, communication masts, inertial navigation units, torpedo tubes, and environmental sensor suites—hardened against pressure hull constraints and saltwater corrosion to enable undersea surveillance, strike, or data collection operations. Fiber optic tethered arrays now dominate acoustic detection segments due to lower self-noise profiles than legacy copper systems. Weapon Systems payloads command concentrated margin pools as hypersonic-capable delivery mechanisms require extensive hull interface redesigns. Surveillance applications absorb the largest volume share, though Scientific Research payloads are expanding fastest as oceanographic institutes deploy autonomous-underwater-vehicle mothership submarines.
The US Navy's Naval Sea Systems Command enforces shock qualification standards that filter non-compliant payload vendors from Virginia-class and Columbia-class programs. Australia's Defence Strategic Review and AUKUS technology-sharing protocols are restructuring supplier eligibility for nuclear-propulsion-compatible payloads. NATO's Undersea Research Centre coordinates interoperability benchmarks for multinational allied submarine squadrons. Stakeholders must monitor how export control harmonization between Washington, London, and Canberra reshapes vendor qualification timelines for third-country buyers.
Market Dynamics
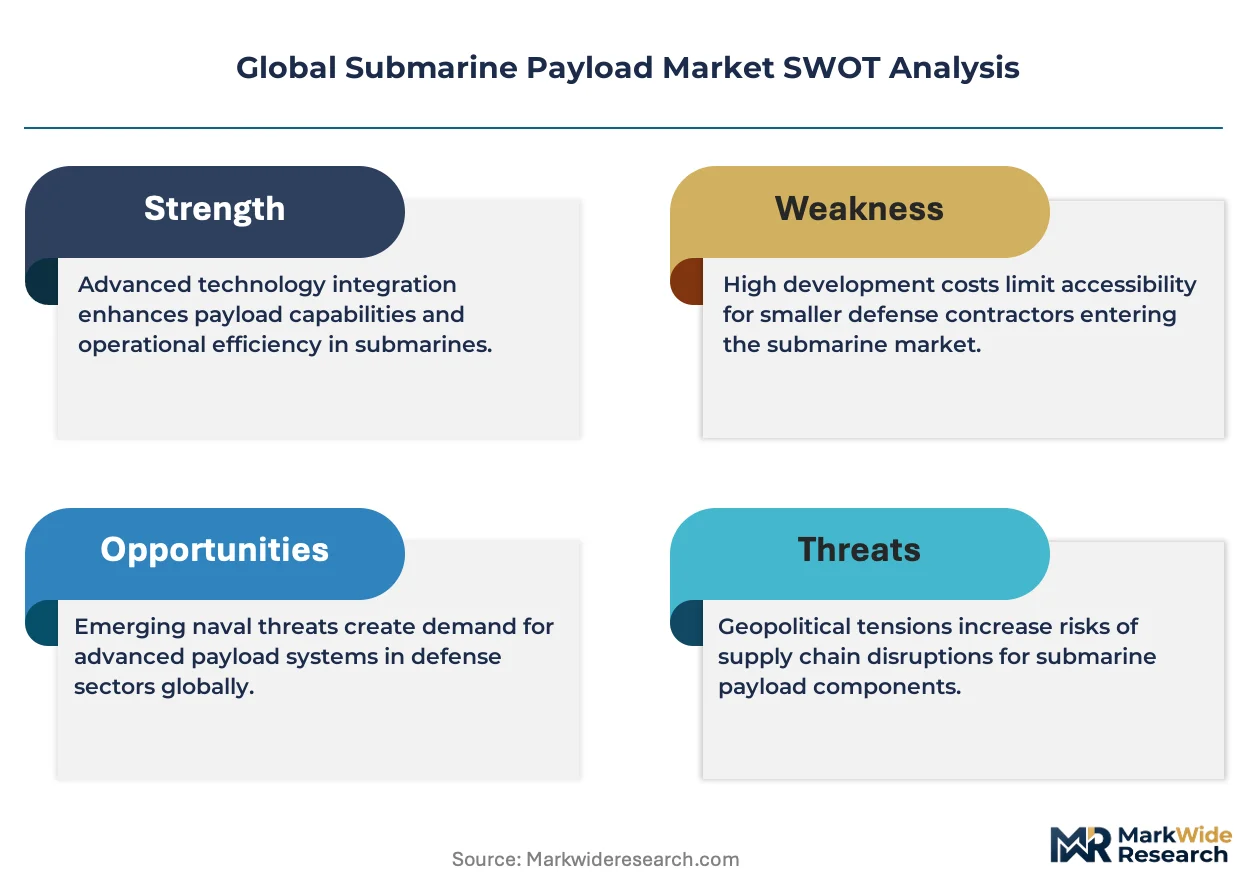
Pressure hull interface standardization is bifurcating supplier tiers as AUKUS-aligned programs demand nuclear-propulsion-compatible payload architectures incompatible with legacy diesel-electric specifications.
Growth Catalysts
- AUKUS technology-sharing protocols:Australia's Defence Strategic Review mandates nuclear-propulsion-compatible payload sourcing, creating captive demand corridors across US, UK, and Australian industrial bases.
- Fiber optic tethered arrays:Lower self-noise profiles than copper systems are accelerating acoustic detection payload replacements across NATO submarine programs.
- Hypersonic-capable delivery mechanisms:Weapon Systems payloads require extensive hull interface redesigns, concentrating R&D investment and margin capture among qualified integrators.
Market Restraints
- High-grade titanium alloy concentration:Pressure hull forging capacity clusters in Japanese and Russian supplier networks, exposing procurement timelines to geopolitical friction.
- US Naval Sea Systems Command shock qualification:Non-compliant payload vendors face automatic exclusion from Virginia-class and Columbia-class programs, compressing the addressable vendor pool.
- Autonomous underwater vehicle mothership substitution:Oceanographic institutes are deploying AUV swarms for data collection missions previously requiring manned submarine payloads.
Strategic Opportunities
- India's naval modernization:Indigenous submarine construction programs under Project-75I create demand for compact payload integration expertise transferable from littoral platform specialists.
- Quantum sensing convergence with photonic masts:Non-acoustic detection payloads are opening new mission profiles for intelligence-gathering operations.
- EU Green Deal defense procurement incentives:Sustainable manufacturing certifications are becoming selection criteria for NATO Undersea Research Centre-coordinated multinational programs.
Industry Challenges
- Systems engineering talent scarcity:Integrated sonar processing architecture expertise concentrates among retiring Cold War-era specialists, constraining design-to-build workflow expansion.
- Multi-decade certification timelines:Naval Sea Systems Command qualification protocols extend payload vendor onboarding across multiple program cycles, freezing market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Submarine Payload Market |
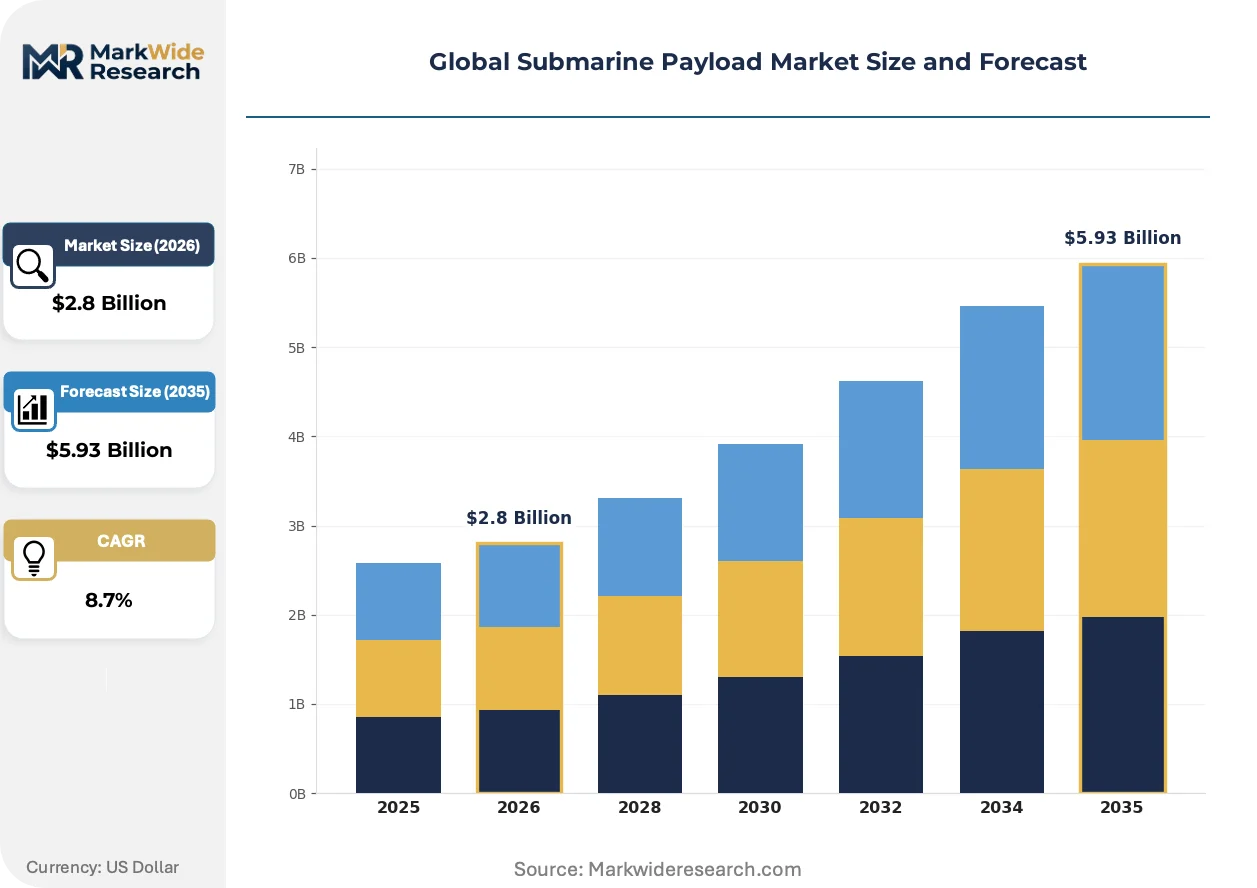
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payload Type: Sonar Systems, Communication Equipment, Navigation Systems, Environmental Sensors, Weapon Systems Technology: Fiber Optic, Acoustic, Electromagnetic, Satellite, Laser Guidance Application: Surveillance, Scientific Research, Underwater Exploration, Military Operations, Data Gathering End User: Naval Forces, Oceanographic Institutes, Energy Companies, Maritime Security Agencies |
| Companies Covered | RTX Corporation, Thales Group, BAE Systems, Saab AB, ThyssenKrupp Marine Systems, Lockheed Martin Corporation, General Dynamics Electric Boat, L3Harris Technologies, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Submarine Payload Market Shifts & Advancements
Acoustic detection architectures are fragmenting between fiber-optic wide-aperture arrays and quantum-enhanced magnetic anomaly detection, forcing payload integrators to support incompatible mission profiles within constrained hull volumes.
Photonic mast technology is bifurcating sensor suite configurations. Optical periscopes incorporating multispectral imaging and satellite communication relays are replacing traditional hull-penetrating masts. US Navy Columbia-class programs are mandating all-photonic solutions. This bifurcation is compressing demand for legacy mechanical mast suppliers while expanding contract pools for semiconductor-grade optical component manufacturers.
EU F-Gas Regulation restrictions on synthetic refrigerants are reshaping environmental sensor suite cooling systems. Payload thermal management architectures must now accommodate natural refrigerant alternatives with higher pressure ratings. Scientific Research payload segments face the steepest redesign costs as precision temperature control requirements conflict with available coolant specifications.
Consolidated fleet-level procurement is displacing boat-by-boat payload specifications. Royal Australian Navy and UK Royal Navy are negotiating multi-hull framework agreements with integrated through-life support commitments. This concentrates negotiation leverage with prime contractors and marginalizes component-level vendors lacking direct platform integration capabilities. Asia-Pacific theater programs exhibit the most aggressive consolidation pace.
Global Submarine Payload Market Segmentation
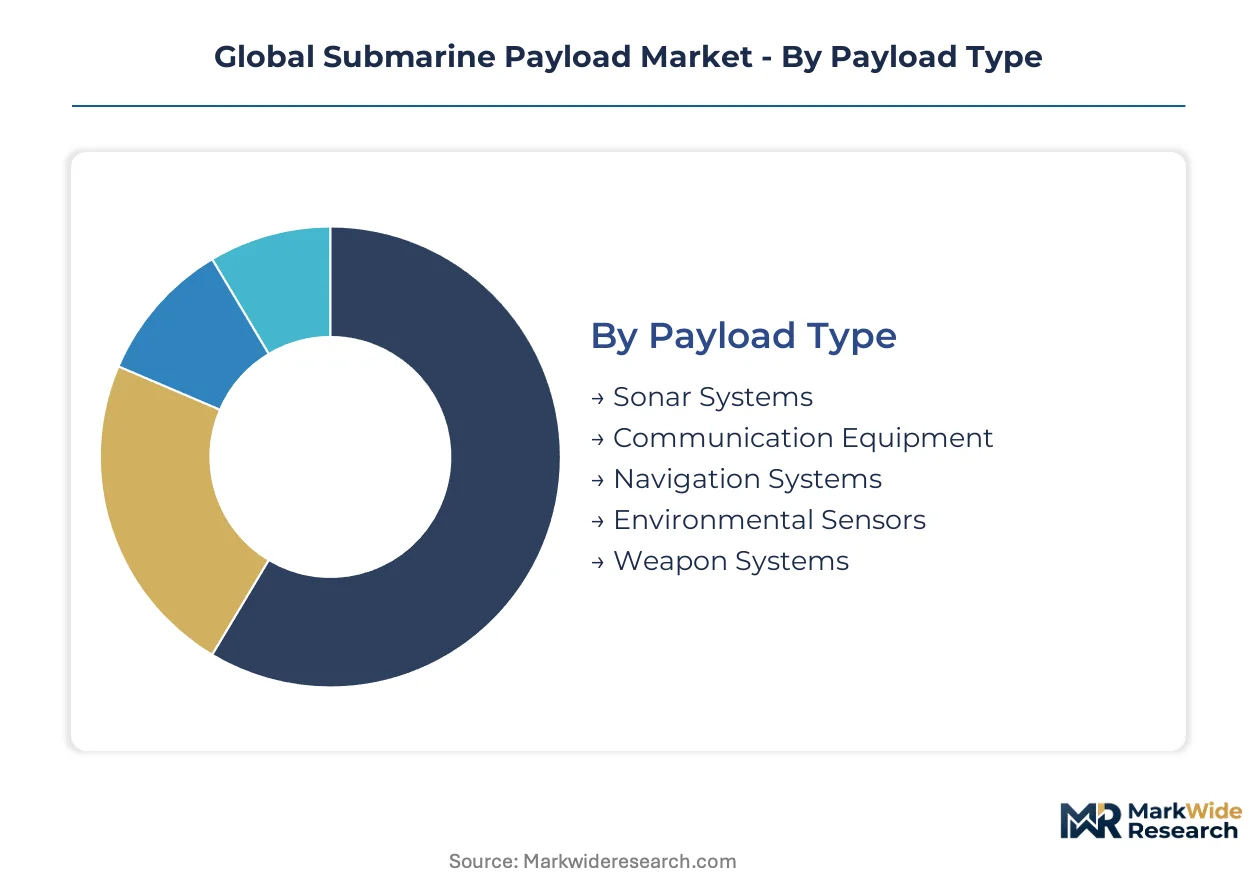
Submarine payload procurement splits sharply between sovereign naval programs with classified specifications and commercial export markets with modular standards. Segmentation reveals where technology leadership concentrates versus where price competition dominates.
Payload Type:
Domestic procurement in the US, UK, and Australia favors integrated multi-mission suites, while export markets to Southeast Asia and South America accept single-function payloads.
- Sonar Systems:Fiber-optic wide-aperture arrays with lower self-noise profiles than legacy copper systems. Australian AUKUS-aligned programs and US Navy Virginia-class procurements are concentrating demand for nuclear-propulsion-compatible acoustic detection architectures.
- Weapon Systems:Torpedo tubes and vertical launch systems requiring extensive hull interface redesigns for hypersonic-capable delivery mechanisms. Margin pools concentrate here due to shock qualification barriers that filter non-compliant vendors from NATO programs.
- Communication Equipment:Satellite relay masts and underwater acoustic modems.
- Navigation Systems:Inertial measurement units and gravimetric sensors.
- Environmental Sensors:Salinity, temperature, and pressure monitoring suites.
Weapon Systems holds the largest share; momentum sits with Sonar Systems.
Technology:
Cost tiers separate defense-grade hardened systems from research-grade commercial alternatives, with fiber optic commanding premium pricing against legacy acoustic implementations.
- Fiber Optic:Tethered arrays and photonic masts replacing hull-penetrating periscopes. US Navy Columbia-class mandates all-photonic solutions, compressing demand for mechanical mast suppliers while expanding contract pools for semiconductor-grade optical manufacturers.
- Acoustic:Traditional piezoelectric hydrophone arrays and passive sonar processing. Diesel-electric submarine operators in India and Southeast Asia sustain demand for copper-based legacy systems incompatible with nuclear-propulsion payload standards.
- Electromagnetic:Magnetic anomaly detection and non-acoustic sensing.
- Satellite:Communication relay and GPS-denied navigation aids.
- Laser Guidance:Precision targeting and underwater rangefinding.
Fiber Optic dominates value capture; Acoustic retains volume leadership in export corridors.
Application:
Volume concentrates in surveillance missions, though scientific research applications are climbing fastest as oceanographic institutes deploy autonomous-underwater-vehicle mothership submarines.
- Surveillance:Intelligence-gathering and undersea domain awareness missions absorbing the largest procurement volumes. Royal Australian Navy and UK Royal Navy framework agreements with through-life support commitments are consolidating fleet-level demand around prime contractors.
- Scientific Research:Oceanographic data collection and climate monitoring. EU F-Gas Regulation restrictions on synthetic refrigerants are reshaping environmental sensor cooling systems, forcing thermal management redesigns for precision temperature control requirements.
- Underwater Exploration:Seabed mapping and resource assessment.
- Military Operations:Strike missions and special forces insertion support.
- Data Gathering:Long-duration sensor network deployment.
Surveillance holds the largest share; Scientific Research is gaining share fastest.
End User:
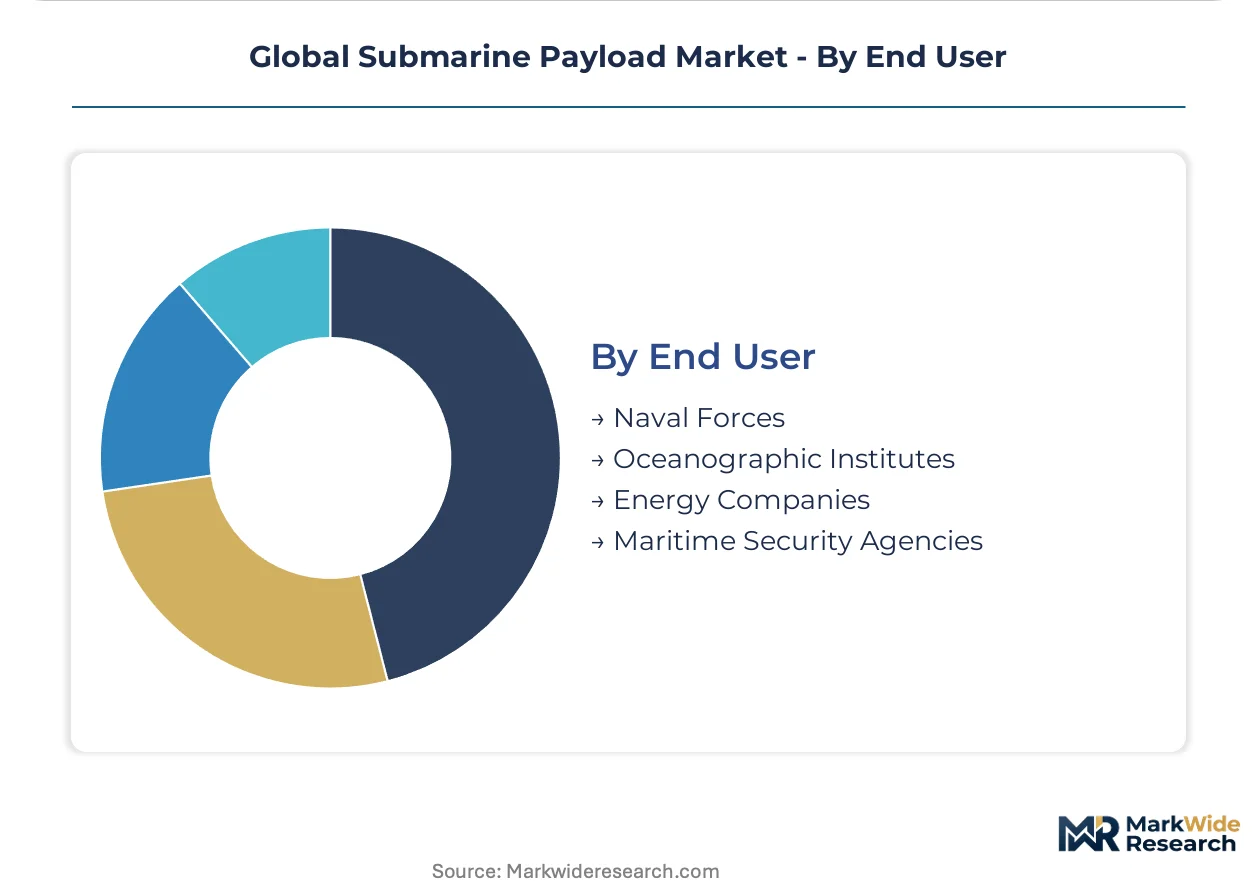
Customer type determines certification intensity, with naval forces imposing multi-decade qualification timelines that freeze market entry for non-compliant vendors.
- Naval Forces:US Naval Sea Systems Command shock qualification standards filter payload vendors from Virginia-class and Columbia-class programs. Australia's Defence Strategic Review and AUKUS technology-sharing protocols are restructuring supplier eligibility for nuclear-propulsion-compatible architectures.
- Oceanographic Institutes:Woods Hole Oceanographic Institution and Scripps Institution of Oceanography deploy AUV swarms for data collection missions previously requiring manned submarine payloads, creating substitution pressure on scientific payload segments.
- Energy Companies:Offshore infrastructure inspection and seabed survey.
- Maritime Security Agencies:Port protection and coastal surveillance.
Naval Forces holds the largest share; momentum sits with Maritime Security Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval procurement offices with expeditionary undersea mandates concentrate demand across five sovereign territories. Each jurisdiction imposes distinct certification regimes that filter supplier eligibility.
United States
Naval Sea Systems Command shock qualification standards govern Virginia-class and Columbia-class payload sourcing. The US Navy mandates all-photonic mast architectures, compressing demand for legacy mechanical suppliers. Connecticut-based Electric Boat and Virginia-class construction yards in Groton anchor nuclear-propulsion-compatible payload integration.
United Kingdom
UK Royal Navy Dreadnought-class programs drive demand for integrated multi-mission suites. Ministry of Defence procurement frameworks emphasize through-life support commitments spanning multi-hull agreements. Barrow-in-Furness shipbuilding clusters concentrate design-to-build workflows for nuclear submarine payloads.
Australia
Defence Strategic Review mandates redirect procurement toward AUKUS-aligned nuclear-propulsion-compatible architectures. Osborne Naval Shipyard in South Australia anchors domestic construction capacity for SSN-AUKUS hulls. TGA-equivalent defence certification protocols restructure supplier eligibility for technology-sharing corridors.
Germany
Bundeswehr naval procurement sustains demand for compact payload integration on diesel-electric platforms. ThyssenKrupp Marine Systems maintains captive design-to-build workflows for Type 212CD and export hulls. Kiel and Hamburg industrial clusters concentrate pressure hull forging and sonar array manufacturing.
India
Project-75I indigenous submarine construction creates demand for littoral-platform payload expertise. Ministry of Defence Production mandates local content thresholds for foreign original equipment manufacturers. Mumbai and Visakhapatnam naval dockyards concentrate hull integration capacity for Scorpene-class follow-on programs.
Global Submarine Payload Market Competitive Landscape
Player mix skews toward integrated platform prime contractors with captive payload design capabilities. Market structure concentrates around three to five sovereign-aligned industrial bases with multi-decade program relationships. Strategic archetypes include nuclear-propulsion specialists, littoral-platform compact integrators, and cross-domain electronics conglomerates. Dominant competitive moves involve framework agreements with through-life support commitments and technology licensing for AUKUS-aligned qualification.
Among US-based defence conglomerates, RTX Corporation, Lockheed Martin Corporation, and Northrop Grumman Corporation occupy positions anchoring integrated sonar processing and combat system architectures. RTX exemplifies the cross-domain electronics archetype with exposure across NATO submarine programs. Lockheed Martin represents the platform-systems integrator position with Columbia-class and Trident-related payload interfaces. Northrop Grumman sits within the mission-systems specialist tier with undersea warfare and electronic payload concentrations. European competitors including Thales Group, BAE Systems, and Saab AB represent geographically anchored alternatives with differentiated compact-platform expertise.
| Leading Market Players |
|---|
| RTX Corporation |
| Thales Group |
| BAE Systems |
| Saab AB |
| ThyssenKrupp Marine Systems |
| Lockheed Martin Corporation |
| General Dynamics Electric Boat |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| Others |
Supply & Pricing Matrix
US Naval Sea Systems Command shock qualification standards simultaneously gate supplier eligibility and stratify pricing tiers, compressing the addressable vendor pool while amplifying margin capture among certified integrators. This dual-filtering mechanism concentrates pricing power with primes possessing multi-decade program relationships.
Pricing Analysis
Next-generation fiber-optic wide-aperture arrays command substantial premiums against legacy copper-based acoustic systems, while emerging quantum-enhanced magnetic anomaly detection payloads occupy speculative pre-commercial pricing tiers. Three-tier pricing structure across nuclear-propulsion-compatible, diesel-electric-adaptable, and research-grade specifications separates mission-critical naval programs from export markets and scientific applications. Cost compression in copper-based legacy tiers is intensifying because Indian and Southeast Asian operators sustain demand for pre-fiber architectures. Maritime security agencies exhibit highest price sensitivity due to constrained procurement budgets, while AUKUS-aligned naval programs demonstrate lowest sensitivity given through-life support bundling.
Supply Chain Analysis
Japan and Russia anchor high-grade titanium alloy pressure hull forging capacity, while Germany and the United States concentrate precision sonar array manufacturing and integrated combat system integration. Supply chains draw from semiconductor-grade optical components, rare-earth magnetic materials for anomaly detection, and pressure-rated natural refrigerants reshaped by EU F-Gas Regulation restrictions. Single-source vulnerability clusters in Japanese titanium forging networks expose procurement timelines to geopolitical friction. Distribution runs through sovereign naval procurement offices with multi-hull framework agreements, marginalizing component-level vendors lacking direct platform integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global submarine payload markets occupy early-cycle expansion positioning as AUKUS technology-sharing protocols accelerate nuclear-propulsion-compatible payload adoption across allied industrial bases.
For Market Incumbents: Fortify qualification barriers by deepening captive design-to-build workflows for nuclear-propulsion architectures, insulating against emerging compact-platform specialists from littoral-market segments. Expand shock certification investment to preempt entry by non-compliant vendors seeking Virginia-class and Columbia-class access. Secure multi-hull framework agreements with Royal Australian Navy and UK Royal Navy before fleet-level procurement consolidation marginalizes component suppliers. For New Entrants and Emerging Players: Differentiate on quantum sensing convergence with photonic mast architectures, targeting scientific research payloads where EU F-Gas Regulation thermal management redesigns create entry openings absent entrenched incumbents. India's Project-75I indigenous submarine construction offers the most penetrable geography for compact payload integration expertise transferable from European littoral specialists. Pursue technology licensing arrangements with AUKUS-aligned primes to shortcut multi-decade Naval Sea Systems Command qualification timelines. For Investors and Strategic Acquirers: Australia's Defence Strategic Review and AUKUS technology-sharing protocol implementation reshapes the acquisition landscape by restructuring supplier eligibility criteria and redirecting capital toward nuclear-propulsion-compatible industrial corridors. Long-term viability centers on platforms with demonstrated through-life support execution across multi-hull commitments. Target acquisition archetypes: compact-platform payload integrators with transferable expertise to Indian and Southeast Asian diesel-electric programs. Monitor TGA-equivalent defence certification protocol harmonization between Washington, London, and Canberra as the critical signal for third-country vendor qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Hull Framework Agreements | Concentrates negotiation leverage with Royal Australian Navy and UK Royal Navy primes. |
| Shock Qualification Investment | Secures Naval Sea Systems Command access for Virginia-class and Columbia-class programs. |
| Photonic Mast Technology Licensing | Accelerates entry into US Navy Columbia-class all-photonic mandate compliance. |
| Quantum Sensing R&D Partnerships | Positions for non-acoustic detection payload openings in intelligence-gathering missions. |
| Natural Refrigerant Thermal Redesign | Addresses EU F-Gas Regulation constraints for scientific research payload segments. |
Research Methodology
Operator-level perspectives from submarine program managers, naval procurement officers, sonar systems engineers, and platform integration specialists anchored the qualitative base. Primary fieldwork combined structured interviews across US Naval Sea Systems Command, UK Ministry of Defence, Australian Defence Strategic Review implementation teams, and German Bundeswehr naval procurement with secondary validation from NATO Undersea Research Centre interoperability benchmarks, AUKUS technology-sharing protocol documentation, and EU F-Gas Regulation compliance filings. Bottom-up payload procurement tracking across Virginia-class, Columbia-class, Dreadnought-class, and SSN-AUKUS programs triangulated against top-down naval budget allocation analysis.
Sensitivity analysis tested forecast robustness across alternative AUKUS implementation timelines, titanium alloy supply disruption scenarios, and autonomous underwater vehicle substitution penetration rates. Segmentation dimensions modeled include payload type, technology generation, application mission profile, and end-user certification intensity. CAGRs derived from hull construction pipeline analysis, payload replacement cycle timing, and technology transition velocity across acoustic detection architectures. Industry-specific inputs incorporated photonic mast adoption curves, quantum sensing readiness levels, and shock qualification backlog durations.
Material uncertainties — sovereign budget reallocation, export control harmonization delays, and autonomous platform substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding AUKUS protocol adherence, NATO interoperability benchmark maintenance, and rare-earth magnetic material supply continuity. Recalibration cycles align with material shifts in Defence Strategic Review implementation milestones and Naval Sea Systems Command qualification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Subsea Navigation and Tracking Market