
 Automated Weapon System Market | 2026-2036
Automated Weapon System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Weapon System Market Analysis
Skilled autonomy engineers is collapsing across Western defense sectors, tightening delivery timelines for next-generation platforms. Rheinmetall AG anchors German ground-based automated turret production through captive metallurgy and in-house sensor integration. Israel Aerospace Industries dominates Middle Eastern UAV exports with combat-proven autonomous navigation stacks. Lockheed Martin sustains US naval systems leadership via classified manufacturing lines in Moorestown, New Jersey.
An automated weapon system integrates sensor fusion, AI-powered fire control, and autonomous navigation to detect, track, and engage targets with minimal human intervention, typically operating at engagement timelines below two seconds for close-in defense. These platforms serve military forces and security agencies requiring persistent area denial without continuous operator load. UAVs and missile systems capture the largest current procurement volumes, while ground-based systems represent the fastest-growing segment as European armies modernize armored formations. AI-powered control technology concentrates margin pools because algorithmic validation cycles lock in multi-year vendor relationships.
The US Department of Defense imposes autonomous systems ethics guidelines that restrict lethal decision-making without human oversight, while NATO standardization agreements shape cross-border interoperability requirements for member militaries. The EU AI Act classifies certain autonomous weapon applications as prohibited, forcing European defense contractors to segment product architectures by export destination. Stakeholders must monitor how rapidly evolving national interpretations of meaningful human control reshape addressable market boundaries and R&D allocation priorities.
Market Dynamics
The US Department of Defense's autonomous systems ethics guidelines are compressing vendor qualification timelines, forcing defense contractors to restructure algorithmic validation pipelines before contract eligibility.
Growth Catalysts
- DoD Ethics Mandates:The US Department of Defense's autonomous systems ethics guidelines require human oversight protocols, creating mandatory upgrade cycles for legacy platforms.
- AI-powered fire control:Algorithmic validation cycles lock in multi-year vendor relationships, concentrating margin pools with established suppliers.
- German armored modernization:European armies are prioritizing ground-based automated turrets for close-in defense below two-second engagement timelines.
Market Restraints
- EU AI Act prohibitions:The EU AI Act classifies certain autonomous weapon applications as prohibited, forcing product architecture segmentation by export destination.
- Engineer scarcity:Skilled autonomy engineers are collapsing across Western defense sectors, tightening delivery timelines for next-generation platforms.
- Input concentration:Captive metallurgy and in-house sensor integration requirements anchor production to vertically integrated suppliers with classified manufacturing capabilities.
Strategic Opportunities
- NATO interoperability:NATO standardization agreements for cross-border military systems create specification convergence across member procurement offices.
- Ground-based systems:European armies modernizing armored formations represent the fastest-growing segment for persistent area denial platforms.
- Combat-proven navigation:Autonomous navigation stacks validated in operational environments command premium positioning in Middle Eastern export markets.
Industry Challenges
- Algorithmic validation timelines:Multi-year certification cycles for AI-powered fire control systems delay revenue recognition and strain working capital.
- Meaningful human control interpretation:Rapidly evolving national definitions of operator oversight reshape addressable market boundaries mid-development.
- Legacy platform integration:Sensor fusion retrofits onto existing armored vehicles require custom mechanical interfaces and electromagnetic compatibility testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Weapon System Market |
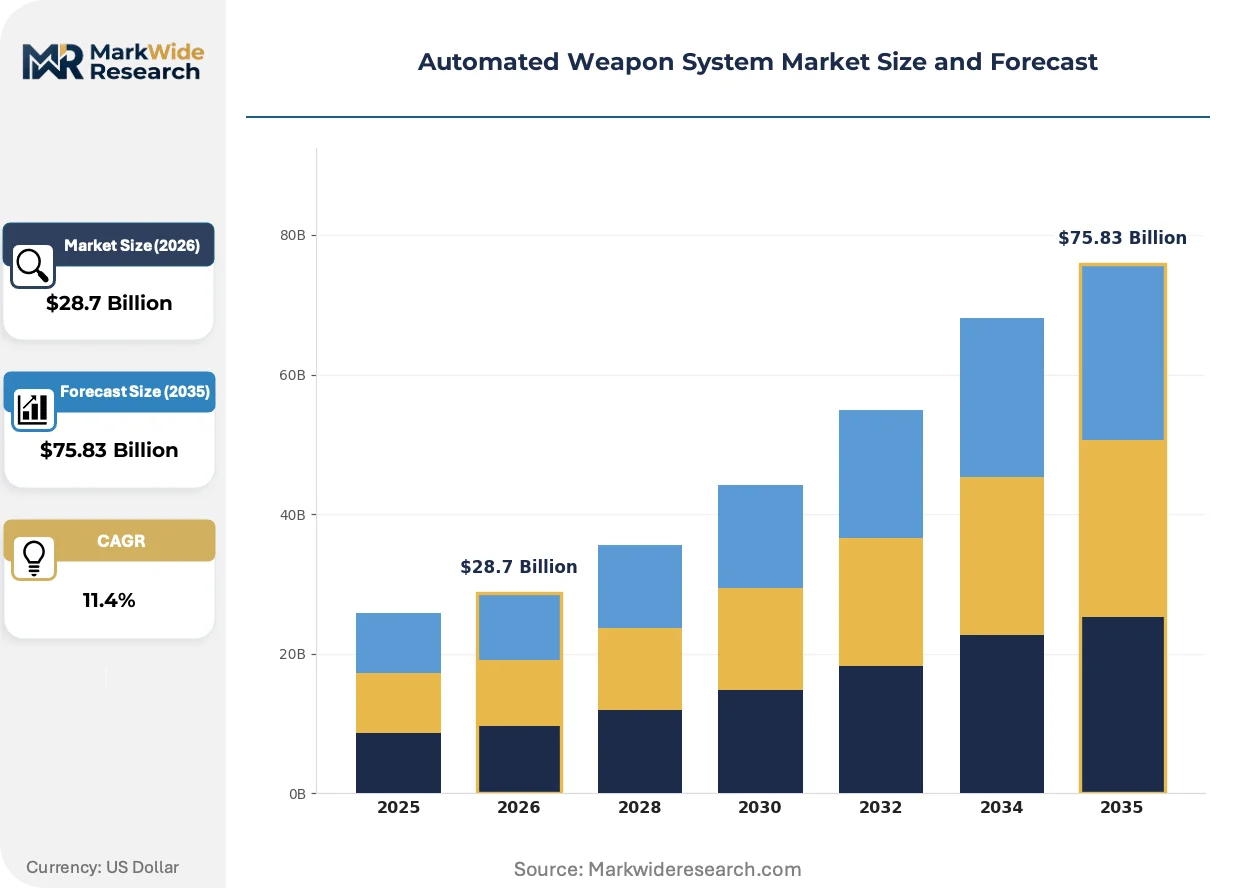
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Missile Systems, UAVs, Ground-Based Systems, Naval Systems Technology: AI-Powered Control, Remote Operated, Autonomous Navigation, Sensor Fusion End User: Military Forces, Defense Contractors, Security Agencies, Research Institutions Application: Surveillance, Target Acquisition, Combat Operations, Training Simulations |
| Companies Covered | Thales Group, Kongsberg Gruppen, Northrop Grumman, Rheinmetall AG, Israel Aerospace Industries, Lockheed Martin, General Dynamics Corporation, Leonardo, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Weapon System Market Emerging Trajectories
Algorithmic decision-making architectures are fragmenting procurement specifications across NATO member states, while sovereign capability mandates in lethal autonomy accelerate captive development programs.
Edge-computing inference engines are decomposing centralized command hierarchies in close-in defense systems. Naval destroyer programs are adopting distributed processing nodes for sub-second threat response. This topology shift is decomposing traditional fire-control supplier relationships into modular component competitions.
The EU AI Act's prohibited classification for certain autonomous applications is segmenting European defense product architectures. Contractors must maintain parallel development tracks for domestic and export variants. Ground-based turret manufacturers face the strictest compliance burden under these dual-track requirements.
Defense ministries are consolidating procurement authority into centralized autonomous systems offices. Traditional program managers are losing budget autonomy to specialized AI acquisition directors. This concentration is most visible in the United States and Germany, where new oversight bodies now control lethal platform approvals.
Automated Weapon System Market Segmentation
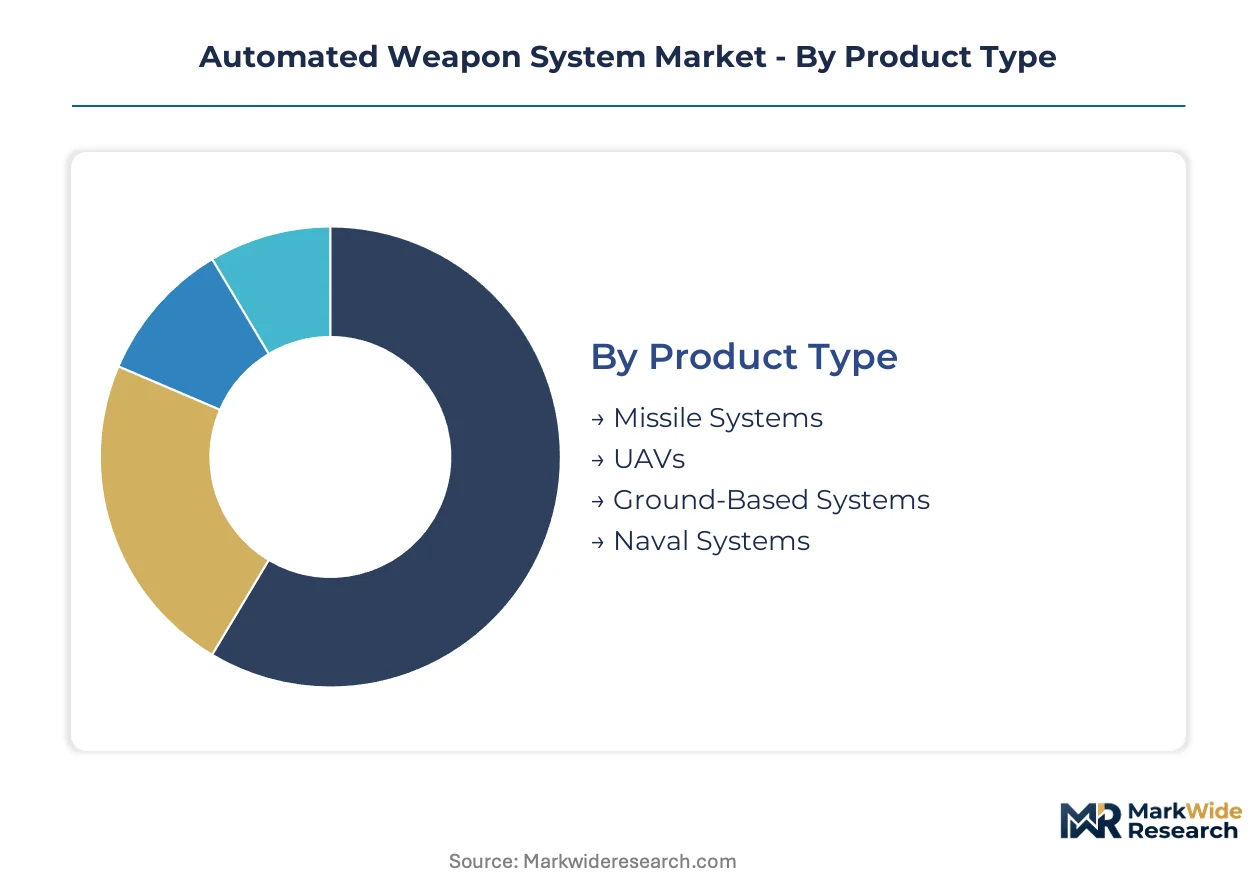
Automated weapon system procurement fragments across mission profiles and sovereign capability requirements. Procurement offices weight technology maturity against operational deployment timelines when allocating development budgets.
Product Type:
UAVs and ground-based systems dominate domestic Western defense budgets, while missile systems anchor export-led procurement in Middle Eastern markets.
- Missile Systems:Hypersonic interceptors and loitering munitions integrate AI-powered terminal guidance for sub-second engagement decisions. Demand concentrates in Israeli and Saudi defense modernization programs driven by regional air defense gaps.
- UAVs:Combat and reconnaissance drones deploy autonomous navigation stacks with satellite-denied operation capability. Procurement is accelerating in German and US force structures seeking persistent surveillance without pilot risk exposure.
- Ground-Based Systems:Automated turrets and active protection systems for armored vehicles.
- Naval Systems:Close-in weapon systems and autonomous surface vessels for maritime domain awareness.
Missile systems command the established base. The steepest expansion runs through ground-based systems.
Technology:
Cost tiers separate validated combat algorithms from developmental autonomy stacks, with sensor fusion commanding premium integration fees.
- AI-Powered Control:Algorithmic fire control systems execute target classification and engagement authorization under human-supervised protocols. Validation cycles lock in multi-year vendor relationships with classified manufacturing clearance.
- Sensor Fusion:Multi-spectral data integration from radar, electro-optical, and acoustic arrays enables all-weather target tracking. NATO standardization agreements are driving specification convergence across member procurement offices.
- Autonomous Navigation:GPS-denied positioning and obstacle avoidance for unmanned platforms.
- Remote Operated:Man-in-the-loop control architectures for contested electromagnetic environments.
Remote operated systems command the established base. The steepest expansion runs through AI-powered control.
End User:
Military forces drive volume procurement, while research institutions anchor pre-competitive development funding for next-generation autonomy.
- Military Forces:National defense ministries operate as sole-source procurers with classified operational requirements. US and German armed forces are consolidating procurement authority into specialized autonomous systems offices.
- Defense Contractors:Prime integrators and subsystem suppliers competing for algorithmic validation contracts.
- Security Agencies:Border patrol and critical infrastructure protection units with restricted lethal authority.
- Research Institutions:National laboratories and university-affiliated centers advancing foundational AI safety research.
Military forces command the established base. The steepest expansion runs through defense contractors.
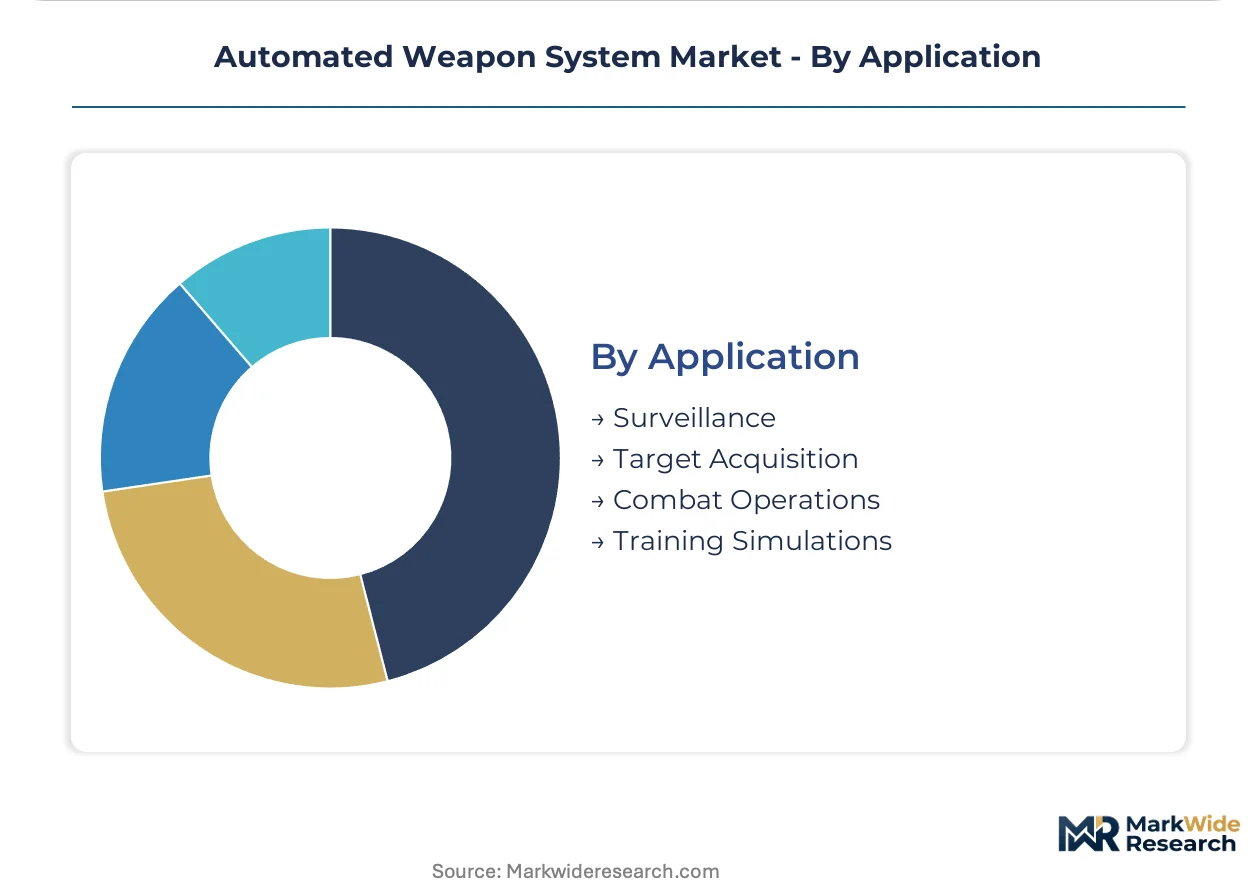
Application:
Volume concentrates in surveillance missions, while combat operations face the strictest meaningful human control compliance burdens.
- Surveillance:Persistent wide-area monitoring through multi-platform sensor networks with automated anomaly detection. Israeli and US border security programs are driving demand for reduced-operator-load systems.
- Combat Operations:Lethal engagement execution with human-supervised authorization protocols. EU AI Act prohibitions are forcing European contractors to maintain parallel domestic and export product architectures.
- Target Acquisition:Automated detection and tracking for manned-unmanned teaming.
- Training Simulations:Synthetic environments for operator proficiency and tactics development.
Surveillance commands the established base. The steepest expansion runs through combat operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Israeli and German manufacturing clusters while US procurement offices extract volume discounts through sole-source contracting authority. Defense ministries in Tel Aviv and Berlin command premiums for combat-validated autonomy stacks. Pentagon acquisition directors leverage multi-year algorithmic validation cycles to compress vendor margins.
United States
Naval destroyer programs and close-in weapon systems drive procurement volume through the Department of Defense's specialized autonomous systems offices. The DoD ethics guidelines mandate human oversight protocols, forcing contractors to restructure validation pipelines before contract eligibility. Classified manufacturing lines in Moorestown, New Jersey anchor naval systems integration for sub-second threat response.
Germany
Armored formation modernization accelerates demand for ground-based automated turrets with below-two-second engagement timelines. The EU AI Act forces product architecture segmentation between domestic and export variants, tightening compliance burdens. Captive metallurgy and in-house sensor integration in Düsseldorf and Unterlüß anchor Rheinmetall's vertically integrated production.
Israel
Combat-proven autonomous navigation stacks command premium positioning in Middle Eastern UAV export markets. Israeli defense procurement operates through centralized acquisition authorities with classified operational requirements. Israel Aerospace Industries in Lod anchors regional dominance through validated satellite-denied operation capability.
United Kingdom
BAE Systems sustains submarine-launched autonomous platforms and naval fire control through Scottish manufacturing clusters. NATO standardization agreements drive specification convergence with continental procurement offices. The Ministry of Defence's specialized AI acquisition directors now control lethal platform approvals, consolidating traditional program manager budgets.
South Korea
Border surveillance programs and persistent area denial systems accelerate procurement of reduced-operator-load platforms. The country's national defense regulator mandates algorithmic validation cycles that lock in multi-year vendor relationships. Seoul Capital Area manufacturing concentrates sensor fusion integration for all-weather target tracking arrays.
Automated Weapon System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the automated weapon system value chain. Algorithmic validation capabilities and classified manufacturing clearances concentrate margin pools with established suppliers, while modular component competitions erode traditional fire-control supplier relationships. Two strategic archetypes dominate: vertically integrated primes with captive metallurgy and sensor integration, and specialized autonomy stack developers with combat-validated navigation algorithms. Competitive dynamics center on multi-year certification cycles for AI-powered fire control and strategic partnerships for NATO interoperability compliance.
Within the vertically integrated prime tier, Rheinmetall AG and Lockheed Martin exemplify divergent geographic anchoring strategies. Rheinmetall occupies a position as the German ground-systems incumbent through in-house production capabilities. Lockheed Martin sits within the US naval systems segment via classified manufacturing infrastructure. Israel Aerospace Industries represents the combat-validation archetype, anchoring premium export positioning through operational deployment history. These three entities illustrate how sovereign capability mandates and ethics guideline compliance reshape competitive boundaries across NATO procurement offices.
| Leading Market Players |
|---|
| Thales Group |
| Kongsberg Gruppen |
| Northrop Grumman |
| Rheinmetall AG |
| Israel Aerospace Industries |
| Lockheed Martin |
| General Dynamics Corporation |
| Leonardo |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Multi-year algorithmic validation cycles stretching beyond thirty-six months concentrate pricing power with established suppliers holding classified manufacturing clearances, while compressing margins for challengers lacking combat-proven navigation stacks. This lead-time asymmetry shapes procurement negotiations across NATO defense ministries and Israeli export markets alike.
Pricing Analysis
Israeli and German manufacturing clusters command fifteen-to-twenty percent premiums over US sole-source contracts for combat-validated autonomy stacks. Three-tier pricing structure across premium combat-proven, standard NATO-interoperable, and economy remote-operated levels segments buyer budgets. Cost compression in standard-tier fire control systems intensifies as Pentagon acquisition directors leverage multi-year validation cycles. Research institutions exhibit highest price sensitivity; Israeli Defense Ministry procurement offices show lowest.
Supply Chain Analysis
Strait of Hormuz transit risk and electromagnetic component shortages anchor supply vulnerability for sensor fusion arrays deployed in Middle Eastern UAV exports. Production concentrates in Germany, Israel, and the United States for classified metallurgy and in-house sensor integration. Gallium nitride semiconductors, rare earth magnets, and precision optical substrates feed from constrained Asian refining capacity. Single-source vulnerability runs through Israeli electro-optical component suppliers. Distribution runs through defense ministry centralized autonomous systems offices with sole-source contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic validation bottlenecks and combat-proven certification scarcity create structural barriers that favor incumbents with classified manufacturing infrastructure while constraining new entrant pathways.
For Market Incumbents: Consolidate algorithmic validation capabilities through captive sensor fusion development and classified manufacturing line expansion in Moorestown or Unterlüß. Lockheed Martin's naval systems dominance demonstrates how in-house metallurgy anchors margin defense against modular component competitors. Prioritize NATO interoperability certification to capture specification convergence across member procurement offices. For New Entrants and Emerging Players: Post-contract algorithmic update services represent an underserved layer where primes under-invest in rapid validation cycle support. Target security agency border surveillance segments with reduced lethal authority requirements and lighter compliance burdens. Pursue research institution partnerships for pre-competitive development funding that sidesteps defense ministry sole-source barriers. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign capability consolidation play because defense ministries are centralizing procurement authority into specialized autonomous systems offices. Acquisition targets should exhibit combat-validated navigation algorithms with Middle Eastern export positioning. Watch for EU AI Act enforcement divergence as the inflection signal reshaping addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Validation Pipeline Restructuring | DoD ethics guidelines mandate human oversight protocol integration before contract eligibility. |
| Combat-Proven Navigation Stack Certification | Israeli operational deployment history commands premium export positioning in Middle Eastern markets. |
| Captive Metallurgy Capacity Expansion | Rheinmetall's Düsseldorf facilities anchor vertically integrated turret production against modular competitors. |
| NATO Interoperability Specification Convergence | Standardization agreements drive cross-border procurement alignment across member defense ministries. |
| Dual-Track Product Architecture Development | EU AI Act prohibitions force parallel domestic and export variant maintenance for European contractors. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, autonomous systems program managers, algorithm validation engineers, and prime contractor business development leads; and secondary validation against DoD ethics guideline filings, NATO standardization agreement texts, EU AI Act regulatory documents, and defense ministry budget appropriations. Bottom-up segment sizing triangulated against top-down market boundary assessments.
Across the analysis window, projections incorporate product type segmentation by mission profile, technology tier by validation maturity, end user concentration by procurement authority centralization, and application split by meaningful human control compliance burden. CAGRs derived from algorithmic adoption curve modeling and armored modernization program timelines. Combat-proven validation cycles and ethics guideline implementation pace served as key forecast inputs.
Underlying assumptions cover sustained NATO defense spending commitments and EU AI Act enforcement stability, with deviation risk concentrated in rapidly evolving national interpretations of meaningful human control. Practitioners should keep alternative scenarios live as Pentagon acquisition director authority consolidation and German armored formation modernization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Military Robotics Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Drone-In-A-Box Solutions Market