
 Integrated Range Market | 2026-2036
Integrated Range Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Range Market Insights
Residential kitchen renovation cycles is hardening demand for connected cooking platforms as homeowners prioritize appliance ecosystems over standalone purchases. Samsung Electronics leverages its SmartThings platform to anchor cross-device compatibility in premium kitchen suites. Bosch sustains manufacturing scale through its European appliance production network while competing on energy efficiency ratings. Whirlpool Corporation dominates North American retail channels through direct relationships with home improvement chains.
An integrated range denotes a kitchen appliance combining a cooktop surface with an oven cavity in a single cabinet enclosure, typically featuring convection heating elements, electronic touch controls, and optional Wi-Fi connectivity for remote preheating and temperature monitoring. The unit serves residential and light commercial food preparation environments where space optimization and unified aesthetic design drive purchase decisions. Smart Devices within the product type dimension leads current revenue contribution as voice-assistant compatibility becomes a baseline expectation. Energy Management within the use case dimension represents the fastest-growing application as utility rate structures incentivize demand-response-enabled appliances. The residential user segment occupies the dominant share of volume, though enterprise buyers in multi-unit housing development command superior margin pools through bulk specification contracts.
The US Department of Energy administers ENERGY STAR certification thresholds that dictate minimum efficiency standards for electric and gas cooking equipment sold in American markets. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant and insulation material choices in appliances distributed throughout European member states. China's GB standards and MIIT circular economy mandates impose recycling and material recovery obligations on domestic manufacturers. Stakeholders must monitor evolving interoperability standards as platform fragmentation threatens to segment addressable markets by ecosystem allegiance rather than product performance.
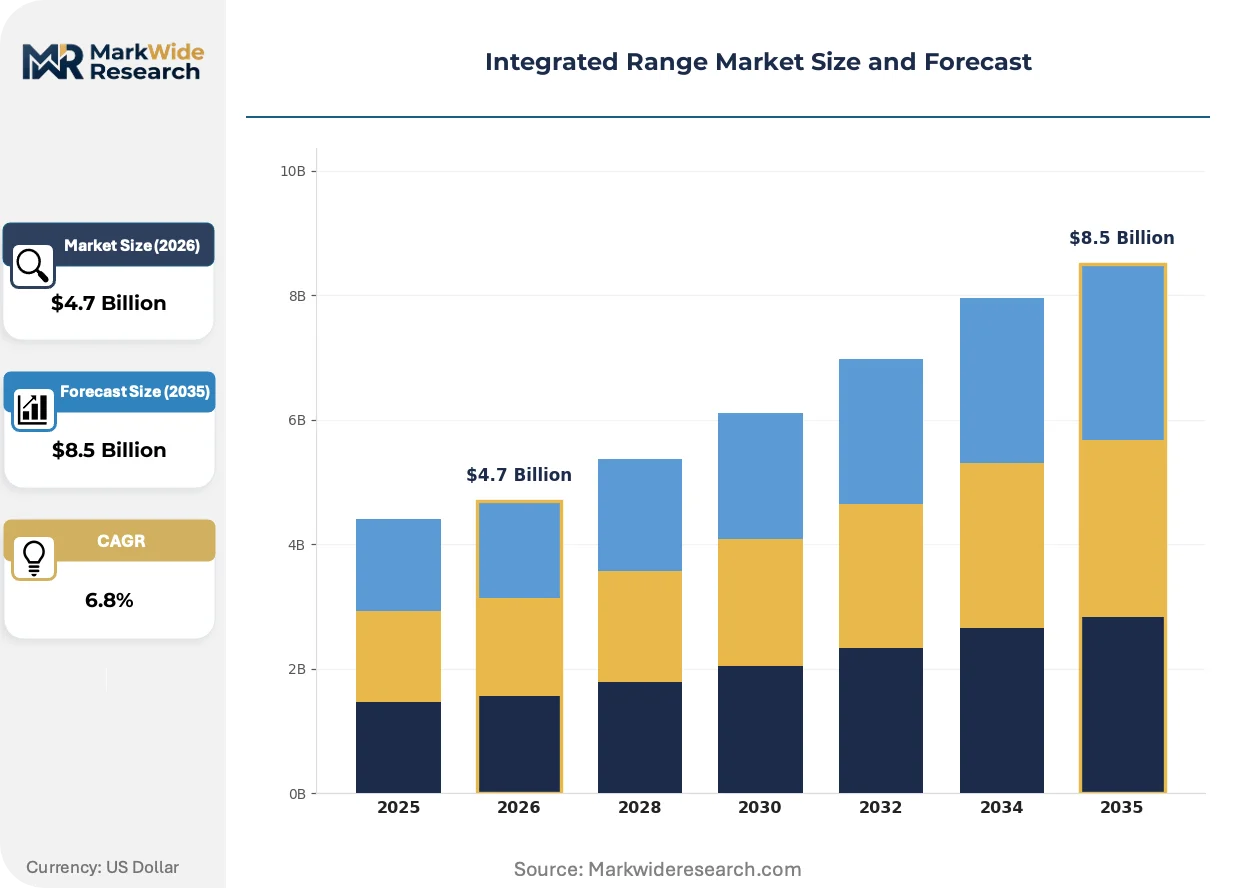
Market Dynamics
Platform fragmentation is splitting the integrated range market into competing smart home ecosystems, forcing manufacturers to commit R&D resources to proprietary connectivity stacks rather than core cooking performance.
Growth Catalysts
- ENERGY STAR Certification Thresholds:The US Department of Energy's tightening efficiency standards are pulling electric range development toward induction and advanced convection systems that reduce household energy consumption.
- Urban Household Formation:Metropolitan corridors in Germany, the United States, and China are generating concentrated demand for space-optimized kitchen appliances as apartment construction outpaces single-family housing starts.
- Voice-Assistant Integration:Smart speaker ecosystems are embedding remote preheating and temperature monitoring as baseline consumer expectations for premium appliance purchases.
Market Restraints
- Semiconductor Supply Concentration:Touch control panels and Wi-Fi modules depend on chip fabrication concentrated in East Asian foundries, exposing manufacturers to input volatility and allocation constraints.
- F-Gas Regulation Compliance Costs:The EU's constraints on refrigerant and insulation material choices are forcing European producers to reformulate product lines at elevated R&D expense.
- Gas-to-Electric Transition Friction:Existing residential gas infrastructure in North American housing stock slows displacement of gas ranges by electric alternatives despite efficiency advantages.
Strategic Opportunities
- China's Circular Economy Mandates:MIIT recycling and material recovery obligations are creating first-mover advantage for domestic manufacturers with closed-loop supply chain capabilities.
- Demand-Response Utility Programs:Time-of-use rate structures in California and Germany are opening revenue streams for ranges with grid-interactive load management.
- Multi-Unit Housing Specification:Bulk procurement by apartment developers in Shanghai and Dallas offers margin pools superior to retail channels through standardized platform integration.
Industry Challenges
- Interoperability Certification Timelines:Smart home protocol fragmentation requires manufacturers to pursue multiple compatibility certifications, extending product launch cycles.
- Legacy Kitchen Footprint Constraints:Existing cabinet dimensions and electrical service levels in renovated housing limit form factor innovation and power upgrades.
- Platform Exclusivity Pressure:Ecosystem allegiance requirements from major smart home providers are compressing addressable market scope for non-aligned product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Range Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Devices, Security Solutions, IoT Platforms, Analytics Tools Use Case: Home Automation, Security Monitoring, Energy Management, Environmental Monitoring End User: Residential Users, Enterprises, Government Agencies, Retailers Distribution Channel: Online Retail, Direct Sales, Distributors, System Integrators |
| Companies Covered | SIEMENS, Samsung Electronics, Whirlpool Corporation, Haier Group Corporation, Frigidaire, GE Appliances, LG Electronics, Midea Group, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Range Market Trends and Innovations
Connected cooking platforms are automating core kitchen tasks while regulatory pressure on energy consumption and material composition accelerates hardware redesign cycles across manufacturer portfolios.
Sensor-guided cooking algorithms are automating temperature adjustment and timing decisions based on food type recognition and internal probe feedback. Premium residential buyers in Germany and the United States are specifying these capabilities as standard in kitchen renovation projects. The technology is automating the traditional skill barrier that previously separated amateur from experienced home cooks, compressing the premium appliance justification from performance to convenience.
The EU Ecodesign Directive and F-Gas Regulation are constraining insulation foam chemistry and refrigerant choices in appliances distributed throughout European member states. Manufacturers serving this geography are reformulating product architectures to maintain thermal performance under tighter material constraints. Built-in oven segments face the steepest compliance cost escalation as cavity sealing requirements intensify.
Home improvement chains are consolidating appliance assortment decisions into centralized category management functions, reducing manufacturer access to regional buyer relationships. Multi-brand kitchen suite vendors are responding by developing direct-to-builder specification programs that bypass traditional retail gatekeepers. This channel reconfiguration is most visible in Texas and Florida metropolitan markets where new construction volume supports dedicated builder sales teams.
Integrated Range Market Segmentation
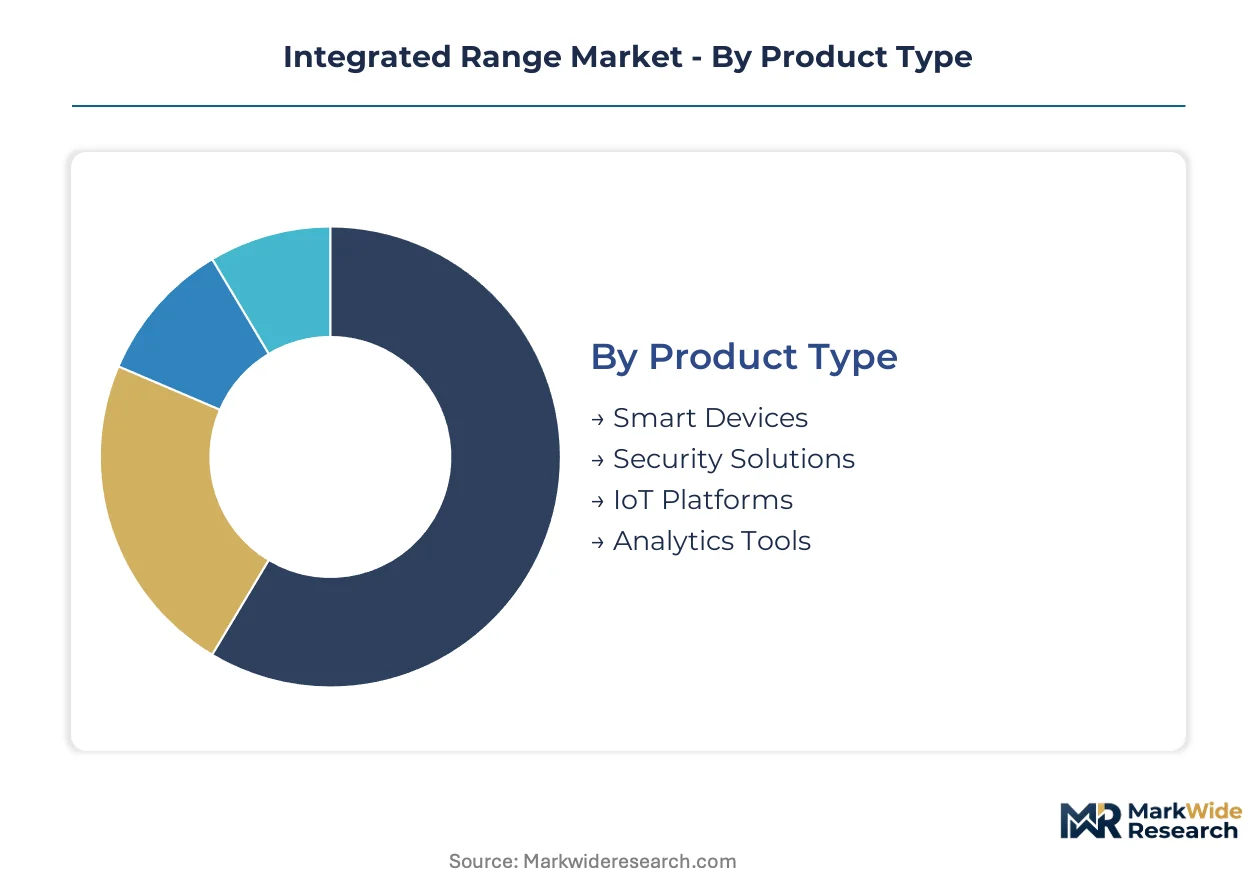
Segmentation in the integrated range market reveals how purchase decisions split between technology sophistication, installation context, and channel access. Manufacturers must align R&D investment with the specific performance thresholds and connectivity requirements that dominate each buyer category.
Product Type:
Premium buyers prioritize ecosystem integration over standalone cooking performance, directing specification toward platforms that unify kitchen control.
- Smart Devices:These units incorporate Wi-Fi modules, voice-assistant compatibility, and sensor-guided cooking algorithms that automate temperature adjustment. Demand concentrates in kitchen renovation projects across the United States and Germany where homeowners specify connected kitchen suites as standard. ENERGY STAR certification thresholds are pulling development toward induction and advanced convection systems in this segment.
- Security Solutions:Tamper-detection sensors, automatic shutoff mechanisms, and child-lock interfaces address liability concerns in multi-unit housing. Apartment developers in Shanghai and Dallas specify these capabilities through bulk procurement contracts that bypass traditional retail channels. China's MIIT circular economy mandates create compliance complexity for imported units in this category.
- IoT Platforms:Open API architectures enabling third-party recipe app integration and utility demand-response participation.
- Analytics Tools:Usage-pattern tracking and predictive maintenance alerts for commercial foodservice operators.
Smart Devices leads on scale; Security Solutions leads on momentum as liability-driven specification accelerates in multi-unit construction.
Use Case:
Utility rate structures and building codes are reshaping which functional capabilities command price premiums versus baseline expectations.
- Energy Management:Grid-interactive load management enables demand-response participation under time-of-use rate structures in California and Germany. These capabilities are climbing the fastest as utility programs open revenue streams for responsive appliances. The EU Ecodesign Directive constrains material choices while efficiency requirements intensify.
- Home Automation:Cross-device orchestration through platforms like SmartThings anchors premium kitchen suite purchases. Residential renovation cycles in metropolitan United States and German corridors harden demand for unified aesthetic control. Platform fragmentation forces manufacturers to pursue multiple compatibility certifications.
- Security Monitoring:Real-time fault detection and automatic emergency service notification for aging housing stock.
- Environmental Monitoring:Indoor air quality sensors and ventilation integration for tightly sealed modern construction.
Home Automation dominates current volume; Energy Management shows the steepest expansion trajectory as regulatory pressure on consumption intensifies.
End User:
Margin structure diverges sharply between price-sensitive individual purchasers and specification-driven institutional buyers.
- Residential Users:Individual homeowners purchasing through retail channels or kitchen renovation contractors. Demand concentrates in United States, German, and Chinese metropolitan corridors where urban household formation outpaces supply.
- Enterprises:Multi-unit housing developers and property management companies commanding superior margins through bulk specification contracts with standardized platform integration.
- Government Agencies:Public housing authorities and military facilities with mandated efficiency and interoperability requirements.
- Retailers:Commercial kitchen operators in hospitality and foodservice seeking durability and service-network reliability.
Residential Users anchor volume; Enterprises capture margin through procurement scale and specification lock-in.
Distribution Channel:
Channel power is consolidating into centralized category management functions that reduce manufacturer access to regional buyer relationships.
- Direct Sales:Manufacturer-to-builder specification programs bypassing retail gatekeepers in Texas and Florida metropolitan markets. These relationships offer margin pools superior to retail through multi-year platform commitments.
- Online Retail:E-commerce platforms capturing price-transparent comparison shopping for replacement purchases and entry-level segments.
- Distributors:Regional inventory and service networks supporting independent appliance dealers and renovation contractors.
- System Integrators:Smart home installation specialists bundling ranges with ecosystem configuration and ongoing support services.
Direct Sales leads on margin capture; Online Retail leads on volume accessibility as price transparency reshapes replacement purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan corridors in the United States, Germany, and China concentrate integrated range demand as urban household formation outpaces supply in dense housing markets. ENERGY STAR thresholds in North America and Ecodesign mandates in Europe reshape manufacturer priorities across these three dominant geographies.
United States
Kitchen renovation cycles in Dallas and Houston metro areas harden demand for connected cooking appliances as homeowners specify smart home ecosystems. The Department of Energy administers tightening ENERGY STAR certification thresholds that pull electric range development toward induction systems. California's time-of-use utility rate structures open revenue streams for grid-interactive load management capabilities.
Germany
Apartment construction in Berlin and Munich corridors generates concentrated demand for space-optimized kitchen appliances with unified aesthetic design. The EU Ecodesign Directive and F-Gas Regulation constrain insulation foam chemistry and refrigerant choices in products distributed throughout member states. Bosch sustains manufacturing scale through its European appliance production network while competing on energy efficiency ratings.
China
Urban household formation in Shanghai and Beijing metropolitan areas drives specification of platform-integrated units in multi-unit housing developments. MIIT circular economy mandates impose recycling and material recovery obligations on domestic manufacturers that create compliance complexity for imported units. Haier Group Corporation leverages closed-loop supply chain capabilities to capture first-mover advantage under these requirements.
South Korea
Premium residential buyers in Seoul Capital Area specify sensor-guided cooking algorithms as standard in kitchen renovation projects. The country's national efficiency standards align with global smart home interoperability protocols that redirect manufacturer R&D budgets toward connected platforms. LG Electronics anchors cross-device compatibility in premium kitchen suites through proprietary ecosystem integration.
Japan
Space-constrained urban housing in Tokyo and Osaka metro areas drives purchase decisions toward unified cooktop-oven enclosures with electronic touch controls. METI-administered efficiency programs and JIS standards shape product development timelines for manufacturers serving this market. Compact form factor innovation dominates R&D investment as legacy kitchen footprint constraints limit power upgrade flexibility.
Integrated Range Market Competitive Landscape
Platform exclusivity pressure dominates the current landscape as ecosystem allegiance requirements from major smart home providers compress addressable market scope for non-aligned product lines. The vendor base splits between diversified appliance conglomerates with multi-brand portfolios and specialized cooking equipment manufacturers with focused category depth. Three strategic archetypes occupy distinct positions: platform-anchored ecosystem players, efficiency-certified premium specialists, and scale-driven mass-market suppliers. Competitive intensity concentrates around M&A activity targeting smart home connectivity stacks and strategic partnerships securing semiconductor supply allocation.
Among diversified appliance conglomerates, Samsung Electronics and Whirlpool Corporation exemplify contrasting geographic anchoring strategies. Samsung leverages its SmartThings platform to unify kitchen control across device categories, while Whirlpool dominates North American retail channels through direct relationships with home improvement chains. Bosch occupies a position within the European efficiency-certified tier, sustaining manufacturing scale through regional production networks. These three players represent the dominant competitive archetypes shaping procurement patterns across their respective home markets.
| Leading Market Players |
|---|
| SIEMENS |
| Samsung Electronics |
| Whirlpool Corporation |
| Haier Group Corporation |
| Frigidaire |
| GE Appliances |
| LG Electronics |
| Midea Group |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
ENERGY STAR certification thresholds gate both qualified supply and premium-tier pricing access, as manufacturers must absorb compliance costs for induction systems and advanced convection elements to serve North American markets. This regulatory filter concentrates margin capture among certified producers while compressing pricing power for legacy gas-range portfolios facing displacement pressure.
Pricing Analysis
Retailer markup layers dominate the pricing structure, with home improvement chains extracting category management concessions that compress manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi-enabled smart devices from basic convection units and entry-level electric ranges. Cost compression in the standard tier is intensifying because semiconductor allocation constraints force component prioritization toward higher-margin connected SKUs. Individual homeowners purchasing through online retail channels exhibit the highest price sensitivity, while enterprise buyers in multi-unit housing development accept premium positioning for standardized platform integration.
Supply Chain Analysis
Freight cost volatility from East Asian fabrication centers to North American and European assembly plants is elevating landed cost uncertainty for touch control panels and Wi-Fi modules. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while induction coil production and oven cavity stamping draw from Mexico, Poland, and China. Single-source vulnerability in chip fabrication exposes manufacturers to allocation constraints during demand surges. Distribution runs through consolidated home improvement chain category managers and direct-to-builder specification programs that bypass traditional regional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on component cost-down curves for Wi-Fi modules and induction systems, alongside a structural shift toward premium-tier smart device specification in kitchen renovation cycles.
For Market Incumbents: Deploy closed-loop supply chain capabilities to capture first-mover advantage under China's MIIT circular economy mandates. Secure semiconductor allocation through multi-year foundry commitments to defend against chip fabrication concentration risk. Anchor ecosystem allegiance through platform-integrated kitchen suites that raise switching costs for renovation contractors and multi-unit developers. For New Entrants and Emerging Players: Enter via demand-response-enabled Energy Management use cases in California and Germany utility territories where time-of-use rate structures create immediate value propositions. Target multi-unit housing specification in Shanghai and Dallas corridors where bulk procurement bypasses retail gatekeeper consolidation. Lead with open API architectures that sidestep proprietary platform fragmentation. For Investors and Strategic Acquirers: Roll-up economics work for regional smart home integration specialists because platform exclusivity pressure is compressing addressable market scope for non-aligned product lines. Long-term viability favors targets with demonstrated builder-direct relationships and certified closed-loop supply chains. Watch utility demand-response program enrollment rates as the inflection signal for grid-interactive load management adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | SmartThings and proprietary ecosystems anchor premium kitchen suite purchases against standalone competitors. |
| Closed-Loop Supply Chain Investment | MIIT circular economy mandates in China reward domestic manufacturers with material recovery capabilities. |
| Direct-to-Builder Specification Programs | Texas and Florida metropolitan markets support dedicated sales teams bypassing retail category managers. |
| Demand-Response Capability Certification | California and Germany utility programs open revenue streams for grid-interactive load management features. |
| Induction Technology R&D Scale-Up | ENERGY STAR tightening pulls electric range development away from legacy resistance heating elements. |
Research Methodology
Bottom-up residential and enterprise procurement modeling reconciled against top-down manufacturer production tracking forms the analytical core of this study. Primary interviews with kitchen renovation contractors, multi-unit housing developers, appliance category buyers at home improvement chains, and smart home integration specialists combined with secondary validation from ENERGY STAR certification databases, EU Ecodesign Directive compliance filings, and MIIT circular economy disclosure records. This approach triangulates demand-side specification patterns against supply-side production allocation.
The input-output matrix maps unit shipments across product type, use case, end user, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis against urban household formation rates, renovation cycle timing, and regulatory compliance phase-in schedules. Induction technology penetration curves and Wi-Fi module cost trajectories inform the smart device segment trajectory.
The model holds under stable regulatory phase-in timelines and continued semiconductor allocation normalization; deviation in trade policy enforcement or foundry capacity expansion would shift volume and value outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Europe Unmanned Systems Market