
 Near Space Robotics Market | 2026-2036
Near Space Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Near Space Robotics Market Analysis
United States aerospace capacity is tilting toward near-space manufacturing as defense contracts and commercial stratospheric ventures expand. Astrobotic Technology leverages its lunar heritage to anchor near-space robotics development in Pittsburgh. Honeybee Robotics sustains R&D intensity through specialized sampling and manipulation systems for extreme environments. Northrop Grumman Corporation dominates large-scale autonomous platform integration for government end users.
Near space robotics encompasses unmanned and autonomous systems operating in the stratosphere and upper atmosphere, typically between 20 and 100 kilometers altitude, utilizing pressure-tolerant composites, radiation-hardened electronics, and long-endurance power architectures for persistent operations beyond conventional airspace. Aerial robots lead product type deployment due to lighter-than-air and fixed-wing platforms proving viability for multi-week stratospheric loiter missions. SLAM technology within the technology dimension is maturing fastest as navigation without GPS dependency becomes critical for denied-environment operations. Military end users command the largest procurement budgets, though research institutions represent the fastest-growing segment as universities establish dedicated near-space laboratories.
The FAA regulates commercial launch and reentry operations through its Office of Commercial Space Transportation, while the Department of Defense imposes cybersecurity and spectrum allocation requirements on stratospheric platforms. ISO standards for space systems engineering provide additional design benchmarks for manufacturers seeking dual-use certification. Stakeholders must monitor how evolving debris mitigation rules and national airspace integration policies reshape platform design trade-offs and operational envelopes.
Market Dynamics
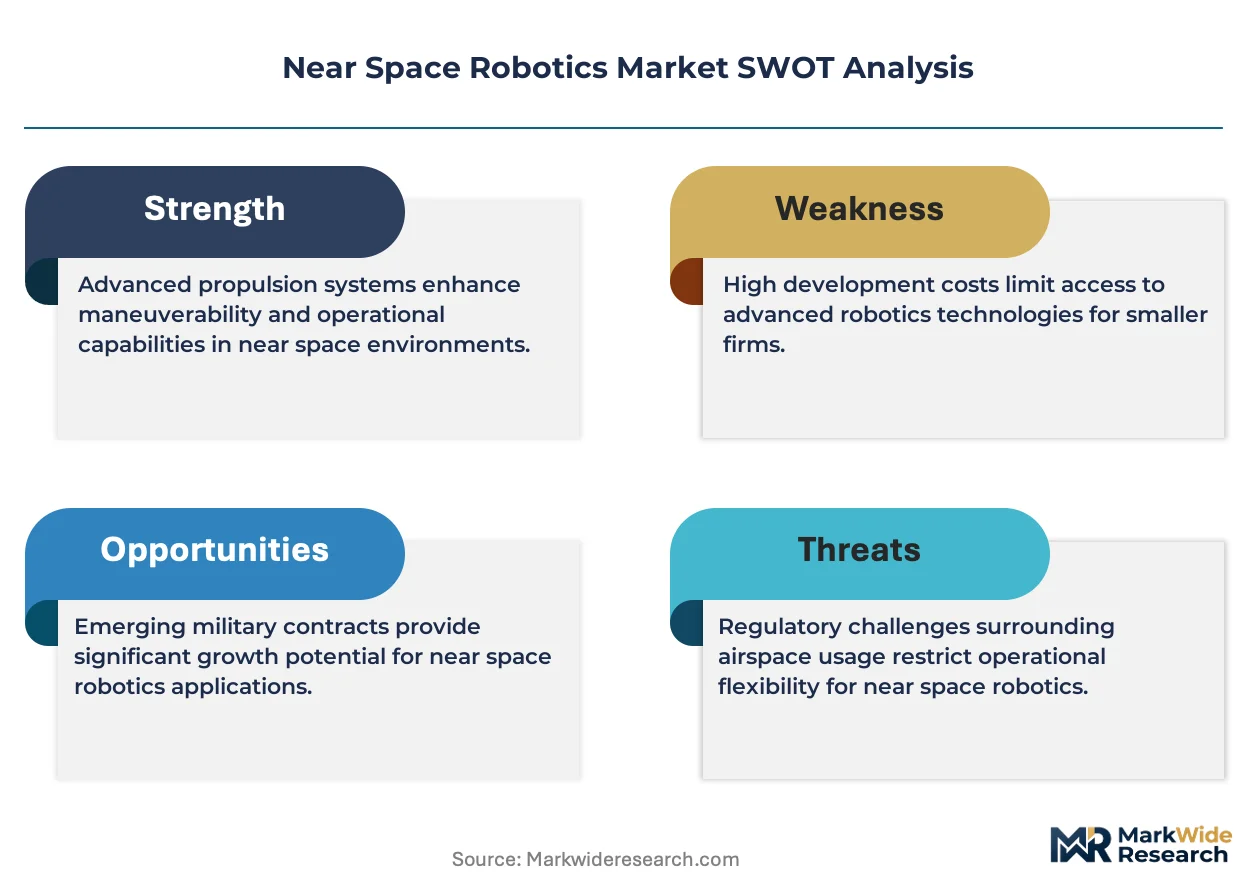
Military procurement of stratospheric surveillance platforms is compressing development cycles for pressure-tolerant autonomous systems, while FAA certification pathway revisions force manufacturers to redesign airworthiness validation protocols for vehicles operating above controlled airspace.
Growth Catalysts
- Stratospheric Persistent ISR Demand:Defense agencies are expanding multi-week loiter requirements for denied-area intelligence collection, driving procurement of lighter-than-air autonomous platforms with radiation-hardened avionics.
- FAA Commercial Space Launch Modernization:Streamlined experimental permits for near-space vehicles are reducing time-to-certification for stratospheric robotics developers seeking dual-use airworthiness.
- SLAM Navigation Maturation:Simultaneous Localization and Mapping algorithms operating without GPS dependency are enabling autonomous operations in electronically contested environments.
Market Restraints
- Helium Supply Concentration:Stratospheric balloon and airship platforms depend on helium sourcing concentrated in Qatar and the United States, creating input cost volatility and geopolitical supply risk.
- Radiation-Hardened Electronics Bottleneck:Qualified component suppliers for stratospheric radiation environments number fewer than six globally, constraining production scaling.
- Debris Mitigation Rule Uncertainty:Evolving FAA and ISO requirements for end-of-life platform disposal are extending design validation timelines and increasing insurance burdens.
Strategic Opportunities
- Research Institution Laboratory Buildout:Universities in Colorado and California are establishing dedicated near-space test facilities, creating demand for standardized research-grade platforms.
- Dual-Use Certification Pathways:ISO 19683 space systems engineering standards alignment with FAA commercial space regulations enables single-design military-civilian platform qualification.
- Stratospheric Telecommunications Relay:Convergence of autonomous robotics with high-altitude platform station technology is opening persistent broadband backhaul applications for remote sensing networks.
Industry Challenges
- Aerostructures Engineering Talent Scarcity:Pressure-tolerant composite design expertise resides primarily within legacy defense contractors, limiting workforce mobility for emerging ventures.
- Multi-Regulator Coordination Burden:Platforms crossing 20-100 kilometer altitude zones trigger simultaneous FAA airspace, FCC spectrum, and Department of Defense cybersecurity oversight, complicating operational authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near Space Robotics Market |
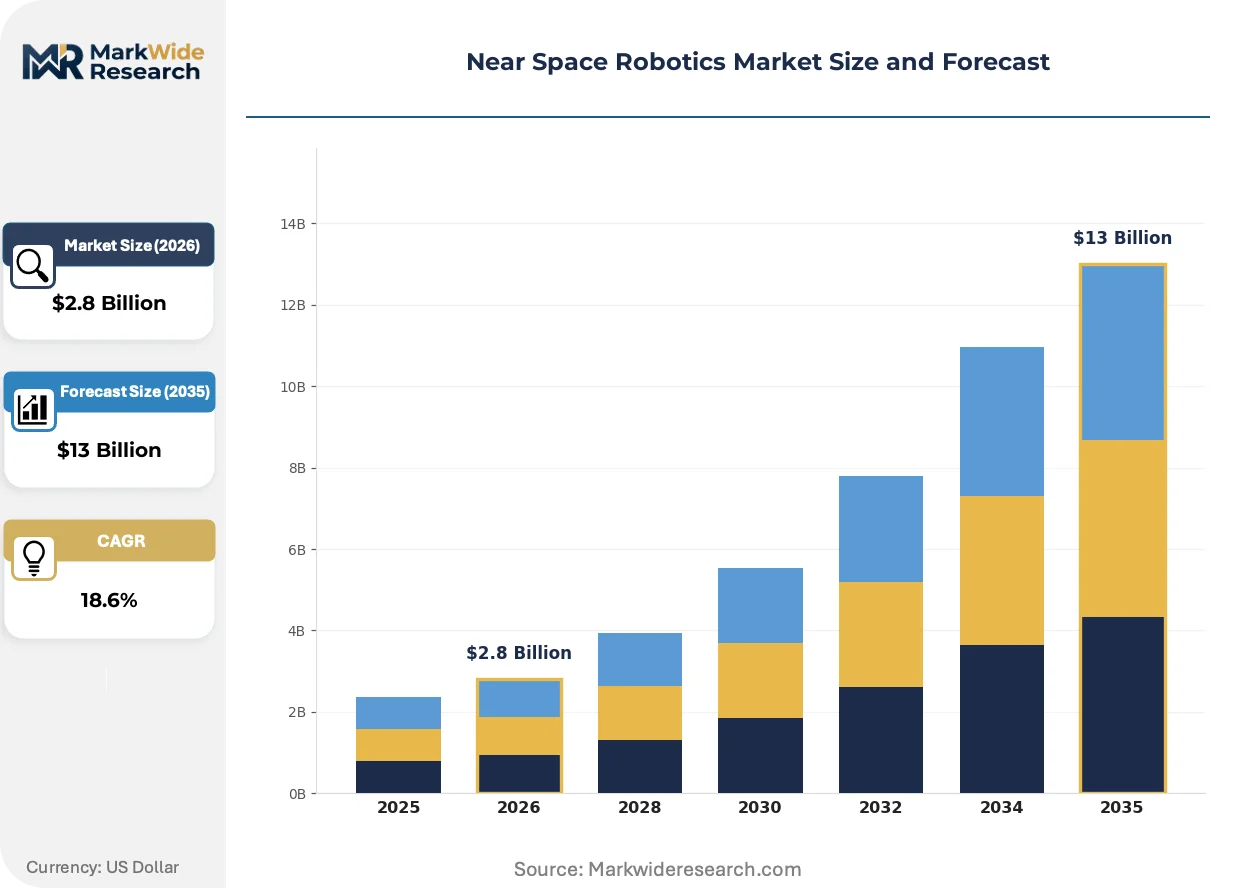
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerial Robots, Ground Robots, Hybrid Robots, Autonomous Vehicles Technology: SLAM, GPS, Communication Systems, Battery Management Application: Surveillance, Research, Delivery, Rescue Operations End User: Military, Research Institutions, Commercial Enterprises, Government Agencies |
| Companies Covered | Astrobotic Technology, Honeybee Robotics, Motiv Space Systems, Northrop Grumman Corporation, Maxar Technologies, MDA Space, Astroscale Holdings, Oceaneering International, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near Space Robotics Market Emerging Trajectories
Autonomous navigation architectures are displacing ground-controlled operations as primary design paradigms, while regulatory frameworks fragment across military-civilian jurisdictional boundaries. Platform endurance requirements are stretching power system engineering toward multi-week continuous operation.
SLAM-based visual-inertial navigation is digitizing mission planning for stratospheric platforms operating beyond GPS coverage. Military end users are integrating these systems into denied-environment surveillance architectures at accelerated procurement cycles. The technology is digitizing operational envelopes previously requiring continuous ground station contact, compressing command infrastructure requirements.
The FAA's evolving commercial space launch regulations are reshaping airworthiness validation for vehicles operating between controlled airspace and orbital regimes. Manufacturers must now demonstrate compliance across both aviation and space safety frameworks simultaneously. Stratospheric balloon and airship developers in the United States face the steepest compliance burden as they pioneer dual-use certification pathways.
Defense procurement offices are consolidating vendor relationships around integrated platform-service bundles rather than discrete hardware acquisition. Traditional equipment suppliers face displacement by contractors offering persistent operational availability. This pattern concentrates most visibly within United States stratospheric surveillance programs, where multi-year mission assurance contracts displace capital purchase models.
Near Space Robotics Market Segmentation
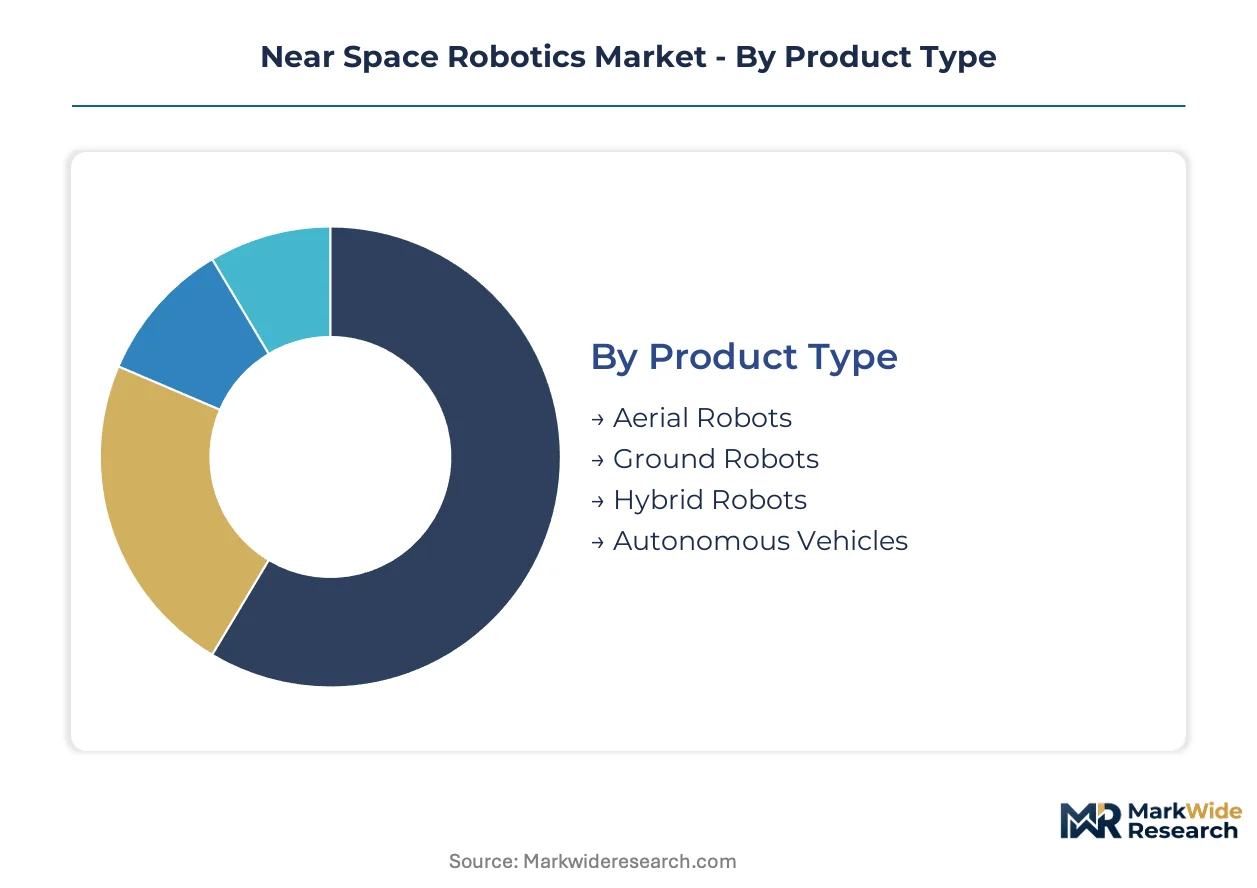
Near space robotics procurement varies sharply across operational domains, with platform architecture and mission profile dictating service intensity. Manufacturers must calibrate support infrastructure to altitude-specific failure modes and regulatory exposure.
Product Type:
After-sales service intensity peaks with aerial platforms requiring stratospheric recovery operations and pressure-vessel recertification between missions.
- Aerial Robots:Lighter-than-air and fixed-wing platforms dominate stratospheric loiter missions, utilizing pressure-tolerant composites and radiation-hardened avionics. Defense agencies in the United States drive procurement for multi-week persistent ISR, constrained by helium supply volatility from Qatar and domestic sources.
- Hybrid Robots:Multi-modal systems combining aerial mobility with surface interaction capabilities. Research institutions in Colorado and California represent the fastest-expanding demand segment as universities establish dedicated near-space laboratories requiring versatile testbeds.
- Ground Robots:Surface-deployed systems for launch site preparation and payload recovery operations.
- Autonomous Vehicles:Self-navigating platforms optimized for pre-programmed mission execution without continuous ground control.
By volume, Aerial Robots leads. By growth pace, Hybrid Robots is climbing the fastest.
Technology:
Cost tier stratification separates mission-critical navigation systems from commoditized power management components, with SLAM commanding premium pricing for denied-environment operations.
- SLAM:Simultaneous Localization and Mapping algorithms enable GPS-independent navigation through visual-inertial sensor fusion. Military end users in contested electromagnetic environments drive adoption, accelerating procurement cycles for electronically denied architectures.
- Communication Systems:Stratospheric relay and cross-link architectures for beyond-line-of-sight coordination. Dual-use certification under FAA commercial space regulations and ISO 19683 standards shapes vendor qualification in the United States.
- GPS:Positioning systems augmented for high-altitude signal geometry and jamming resistance.
- Battery Management:Power distribution systems optimized for multi-week endurance and extreme temperature cycling.
SLAM captures the steepest expansion trajectory as autonomy requirements displace ground-controlled operations.
Application:
Customer type concentration varies by mission risk tolerance, with defense procurement consolidating around integrated platform-service bundles.
- Surveillance:Persistent intelligence, surveillance, and reconnaissance missions dominate stratospheric deployment, utilizing multi-week loiter capabilities for denied-area collection. The Department of Defense imposes cybersecurity and spectrum allocation requirements that extend vendor validation timelines.
- Research:Atmospheric science and technology demonstration missions. Universities establishing dedicated near-space laboratories in California and Colorado create standardized platform demand with accelerated procurement cycles.
- Delivery:High-altitude payload transport for remote logistics applications.
- Rescue Operations:Emergency response platforms for communication relay and supply drop in infrastructure-denied environments.
Surveillance commands the largest procurement budgets. Research is gaining share fastest as institutional laboratory buildout accelerates.
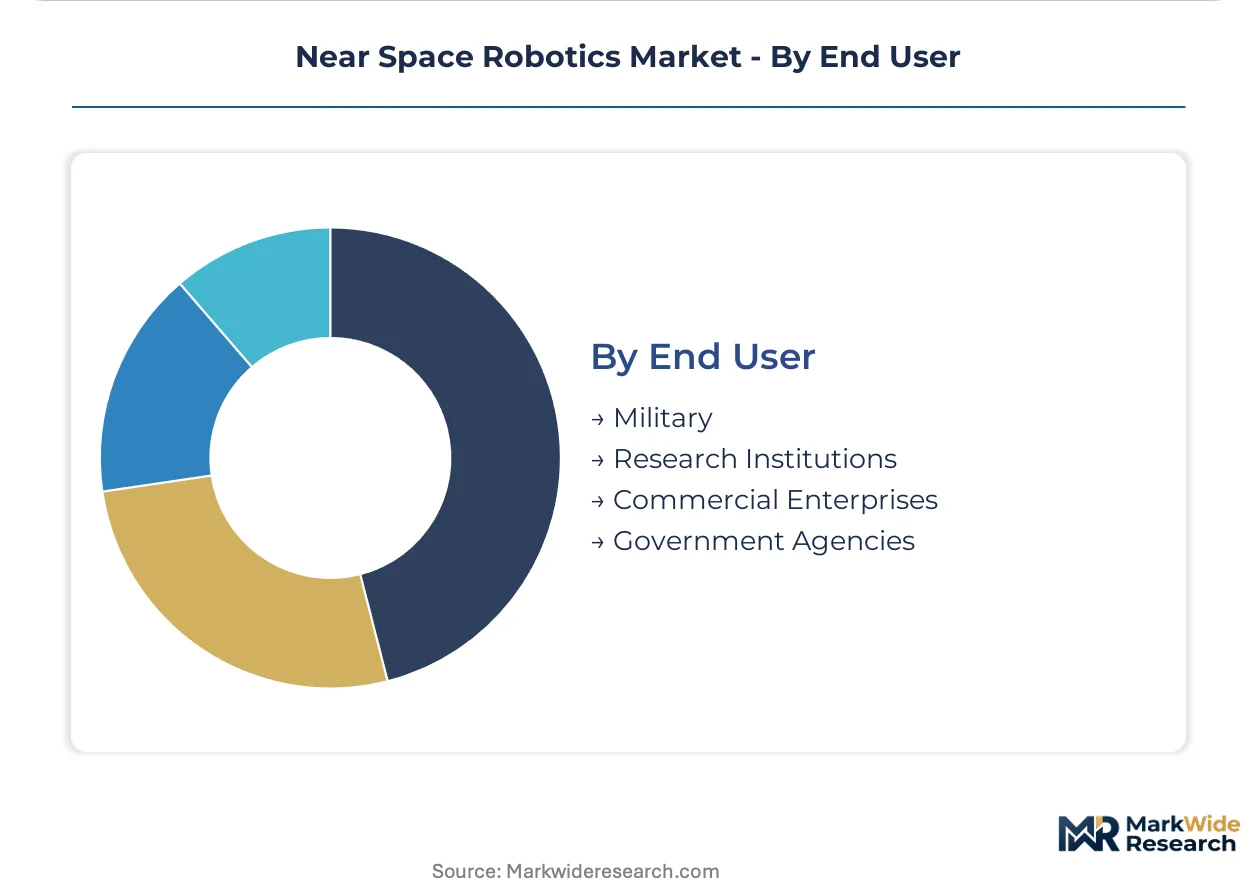
End User:
Supply concentration among radiation-hardened electronics suppliers—numbering fewer than six globally—creates bottleneck conditions for all end-user categories.
- Military:Stratospheric ISR platforms with multi-week endurance requirements. Defense procurement offices consolidate vendor relationships around mission assurance contracts rather than discrete hardware acquisition, concentrating demand in United States surveillance programs.
- Research Institutions:Universities and national laboratories establishing dedicated near-space test facilities. Colorado and California clusters drive fastest-expanding demand for standardized research-grade platforms with simplified certification pathways.
- Commercial Enterprises:Telecommunications relay and remote sensing service providers.
- Government Agencies:Civilian atmospheric monitoring and regulatory compliance missions.
Military leads by committed procurement volume. Research Institutions show the most rapid budget expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA anchors near-space robotics development through its Office of Commercial Space Transportation, which governs experimental permits and commercial launch pathways for stratospheric platforms. Regulatory coordination across aviation and space jurisdictions shapes where manufacturers concentrate engineering talent and certification expertise.
United States
Defense procurement for multi-week stratospheric ISR missions drives demand for lighter-than-air autonomous platforms with radiation-hardened avionics. The FAA's evolving commercial space launch regulations compress certification timelines for experimental near-space vehicles. Aerospace clusters in California and Colorado concentrate both prime contractors and university research laboratories establishing dedicated near-space test facilities.
Japan
METI funding for high-altitude platform stations accelerates development of persistent telecommunications relay robots operating in the stratosphere. National security guidelines impose cybersecurity requirements on dual-use robotic platforms crossing controlled airspace boundaries. Industrial concentration in the Chubu region around Nagoya leverages precision manufacturing heritage for pressure-tolerant composite structures.
Germany
Research institutions drive procurement of standardized platforms for atmospheric science missions requiring extended loiter capabilities. EU regulatory frameworks through EASA coordinate with national aviation authorities on airspace integration above controlled flight levels. The Munich-Stuttgart corridor hosts specialized engineering firms developing GPS-denied navigation systems for contested electromagnetic environments.
United Kingdom
Defense procurement offices consolidate vendor relationships around integrated platform-service bundles for stratospheric surveillance architectures. The UK Space Agency coordinates with the Civil Aviation Authority on near-space vehicle certification pathways bridging aviation and space safety regimes. Harwell Space Cluster in Oxfordshire anchors R&D activity for autonomous systems operating in denied environments.
Israel
Military end users prioritize SLAM-based navigation systems for electronically contested stratospheric operations where GPS dependency creates vulnerability. National security regulations restrict technology transfer for radiation-hardened electronics and autonomous navigation architectures. Tel Aviv metropolitan engineering centers concentrate startup activity developing visual-inertial sensor fusion for denied-area missions.
Near Space Robotics Market Vendor Landscape
Capability concentration sits with specialized subsystem developers; scale advantage sits with integrated platform prime contractors. The vendor base stratifies across three tiers: legacy defense contractors with mission assurance contracts, mid-tier robotics specialists with extreme-environment heritage, and emerging ventures focused on research-grade platforms. Dominant competitive moves include vertical integration of payload and platform capabilities and geographic expansion toward university research clusters in Colorado and California.
Within the integrated platform tier, Northrop Grumman Corporation and Lockheed Martin Corporation represent archetypal prime contractors with established government relationships. Astrobotic Technology and Honeybee Robotics occupy specialist positions, with the former leveraging lunar heritage and the latter sustaining R&D intensity through extreme-environment sampling systems. These three named entities exemplify how capability depth in adjacent space domains translates into near-space robotics positioning.
| Leading Market Players |
|---|
| Astrobotic Technology |
| Honeybee Robotics |
| Motiv Space Systems |
| Northrop Grumman Corporation |
| Maxar Technologies |
| MDA Space |
| Astroscale Holdings |
| Oceaneering International |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
Qatar and United States helium concentration anchors input cost volatility for stratospheric balloon platforms, compressing margin pools at the integrated platform-service bundle tier while radiation-hardened electronics scarcity concentrates pricing power among fewer than six qualified component suppliers globally.
Pricing Analysis
United States defense procurement commands premium pricing for multi-week persistent ISR missions, while research institutions in Colorado and California negotiate standardized research-grade platforms at mid-tier levels. Price differentiation separates military mission assurance contracts from commercial telecommunications relay applications, with after-sales service intensity driving 40-60% lifetime cost premiums for aerial platforms requiring stratospheric recovery operations. Cost compression in the research segment is intensifying because universities are consolidating vendor relationships around simplified certification pathways. Research institutions exhibit highest price sensitivity due to fixed grant funding constraints, while defense agencies demonstrate lowest sensitivity given operational availability requirements.
Supply Chain Analysis
United States Department of Defense export controls on radiation-hardened electronics and autonomous navigation architectures restrict technology flows to allied defense programs, fragmenting vendor qualification across national security boundaries. Manufacturing concentration sits in the United States, Japan, and Germany, with pressure-tolerant composite fabrication anchored in California and Colorado aerospace clusters. Raw material dependencies include helium sourcing from Qatar and domestic strategic reserves, radiation-hardened semiconductors from United States foundries, and carbon fiber prepregs from Japanese suppliers. Single-source vulnerability in qualified radiation-hardened component suppliers creates bottleneck conditions extending lead times. Distribution runs through defense procurement offices consolidating around mission assurance contracts rather than discrete hardware acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near space robotics is approaching a platform-economics inflection as SLAM-based navigation standardization enables interoperability between military and research architectures, collapsing previously siloed development ecosystems into shared component markets.
For Market Incumbents: Pre-empt emerging venture encroachment by backward integration into radiation-hardened electronics supply through captive partnerships with qualified foundries. Lock in multi-year helium offtake agreements with Qatar and United States strategic reserve distributors before research institution demand spikes. Anchor certification expertise through FAA Office of Commercial Space Transportation relationship deepening to extend experimental permit advantages.
For New Entrants and Emerging Players: Build out standardized research-grade platform offerings targeting Colorado and California university laboratory buildout, the most penetrable segment given accelerated procurement cycles and simplified ISO 19683 alignment. Position around dual-use certification pathway navigation as a service capability, addressing the multi-regulator coordination burden that incumbents manage internally. Pursue stratospheric telecommunications relay applications as the go-to-market angle, leveraging persistent broadband backhaul demand from remote sensing networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated platform-service bundles as defense procurement shifts from capital purchase to multi-year mission assurance contracts. Long-term viability favors vendors with demonstrated FAA certification track records and established university research cluster relationships. Target acquisition archetypes include mid-tier robotics specialists with extreme-environment heritage and SLAM navigation depth. The signal to watch is FAA commercial space launch regulation finalization timing, which will clarify airworthiness validation cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Certification Pathway Navigation | ISO 19683 alignment with FAA commercial space regulations collapses military-civilian platform validation timelines. |
| Radiation-Hardened Electronics Backward Integration | Captive supply relationships with qualified foundries insulate against fewer-than-six global supplier bottlenecks. |
| University Research Cluster Geographic Expansion | Colorado and California laboratory buildout concentrates standardized platform demand with accelerated procurement. |
| Helium Supply Contract Long-Term Lock-In | Qatar and United States strategic reserve offtake agreements secure input cost predictability for lighter-than-air platforms. |
| SLAM Navigation Architecture Standardization | GPS-independent visual-inertial sensor fusion enables contested electromagnetic environment operations for denied-area missions. |
Methodological Framework
A standing panel of stratospheric platform engineering directors, FAA certification specialists, defense procurement officers, and university research laboratory directors provided ongoing calibration across the study period. Primary interviews with Northrop Grumman Corporation program managers, Astrobotic Technology navigation architects, and Honeybee Robotics extreme-environment systems engineers were cross-validated against secondary sources including FAA Office of Commercial Space Transportation experimental permit databases, Department of Defense budget justification documents, and ISO space systems engineering standards publications. Bottom-up platform deployment forecasts were triangulated with top-down defense spending allocation analysis.
Scenario-bracketing around helium supply disruption, radiation-hardened electronics production constraints, and FAA regulatory timeline acceleration bounded forecast uncertainty across the analysis window. Segmentation dimensions modeled include platform architecture, navigation technology maturity, end-user procurement mechanism, and altitude operational envelope. CAGRs were derived from deployment trajectory analysis incorporating military ISR mission expansion rates and research institution facility buildout pipelines. Industry-specific inputs included stratospheric balloon launch frequency data and SLAM algorithm technology readiness level assessments.
Stress conditions across Qatar helium export policy shifts, radiation-hardened foundry capacity expansion delays, and FAA-Department of Defense regulatory coordination breakdowns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume sustained defense procurement prioritization of persistent stratospheric surveillance and continued university laboratory capital investment. Material shifts in FAA commercial space launch regulation finalization timing or helium strategic reserve release policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Oscillator Market
Space
Asia-Pacific Space Logistics Market
Space
India Aviation, Defense, and Space Market
Space
Space Travel Market
Space
Space Service Market
Space
Canada Space Electronics Market
Space
China Space Electronics Market
Space
Space Wheel Market
Space
Spacesuit Market
Space
Space Traffic Management Market
Space
Space Rover Market
Space
Astronaut Spacesuit Market
Space
UK Space Electronics Market
Space
Space Mining Market
Space
Africa Space Propulsion System Market
Space
Japan Space Electronics Market