
 Drone Surveillance Market | 2026-2036
Drone Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Surveillance Market Analysis
Aftermarket service revenue is tilting toward predictive maintenance contracts and flight-hour-based support agreements. BAE Systems Inc. anchors its position through deep defense channel relationships and sovereign security clearances. Aerodyne Group leverages a distributed pilot network across Southeast Asian markets to sustain inspection volume growth. Percepto competes with autonomous docking and recharging stations that reduce human-in-the-loop requirements for continuous perimeter monitoring.
Drone surveillance encompasses unmanned aerial systems deployed for persistent observation, data capture, and threat detection across commercial, civil, and defense domains, typically operating at altitudes below 400 feet with endurance ranging from 30 minutes to 12 hours depending on propulsion architecture. Fixed-wing platforms dominate long-range border and maritime patrol applications where loiter time exceeds four hours, while multirotor configurations lead in precision inspection tasks requiring stationary hovering and maneuverability in confined airspace. The military end-user segment occupies the deepest procurement budgets, though construction and agriculture are expanding faster as FAA Part 107 waiver clarity improves liability frameworks for commercial operators.
FAA regulations govern commercial flight authorization and airspace deconfliction in the United States, while EASA's drone-specific framework shapes certification requirements across European member states, and ISO 21384-3 establishes operational safety baselines that influence insurance underwriting and enterprise procurement criteria. Regulatory fragmentation between national aviation authorities creates compliance complexity for platform manufacturers seeking multi-jurisdiction deployment. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemakings and emerging counter-drone mandates that will reshape sensor payload requirements and operational protocols.
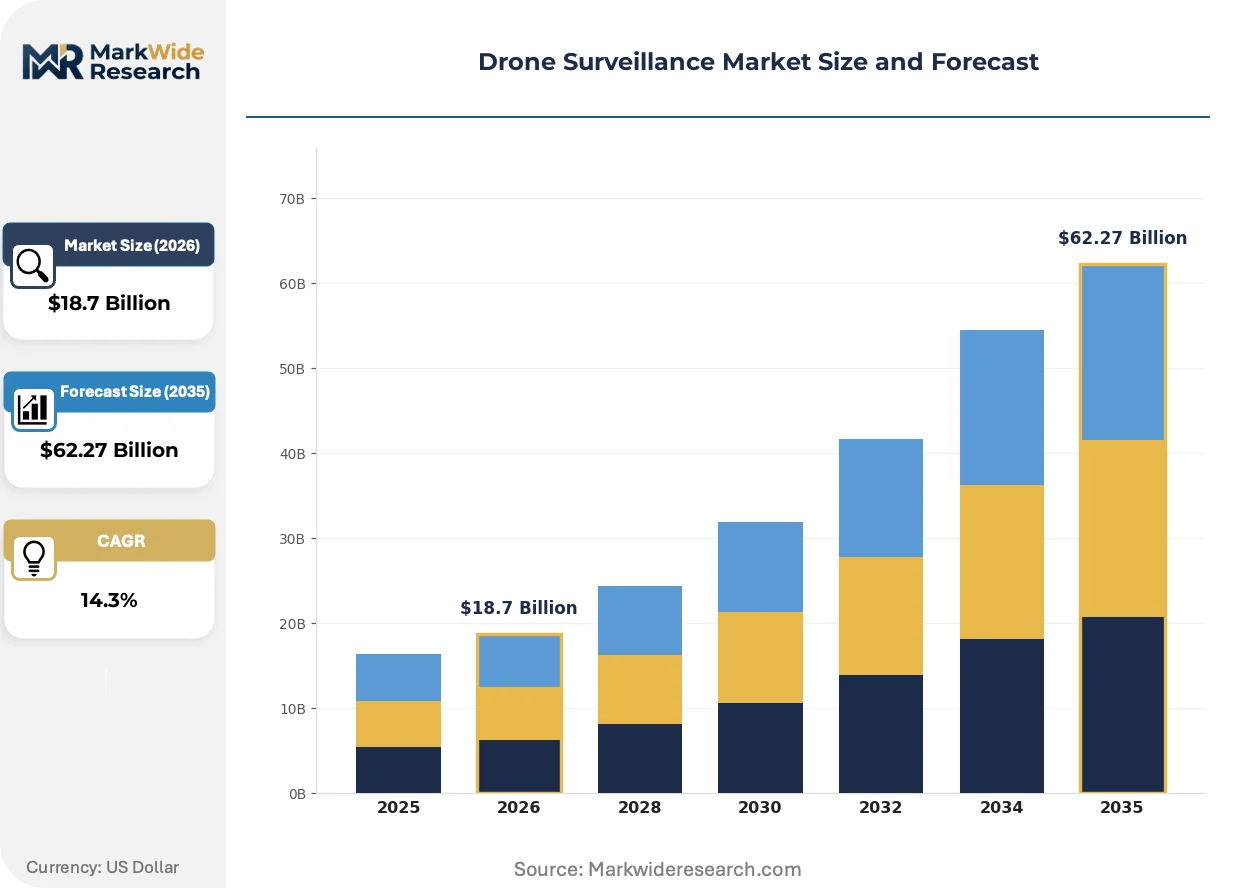
Market Dynamics
Beyond-visual-line-of-sight waiver expansions from the FAA are compressing operational timelines for commercial operators while NATO defense procurement is concentrating demand around fixed-wing platforms with multi-sensor payloads.
Growth Catalysts
- FAA Part 107 waiver expansion:Clarified liability frameworks for commercial operators are accelerating deployment in energy infrastructure inspection and construction monitoring across the United States.
- Infrared sensor miniaturization:Reduced payload weight enables longer endurance on electric platforms, extending mission profiles for border patrol and maritime surveillance applications.
- Germany:Bundeswehr reconnaissance program modernization is driving procurement of tactical UAS with sovereign data processing requirements.
Market Restraints
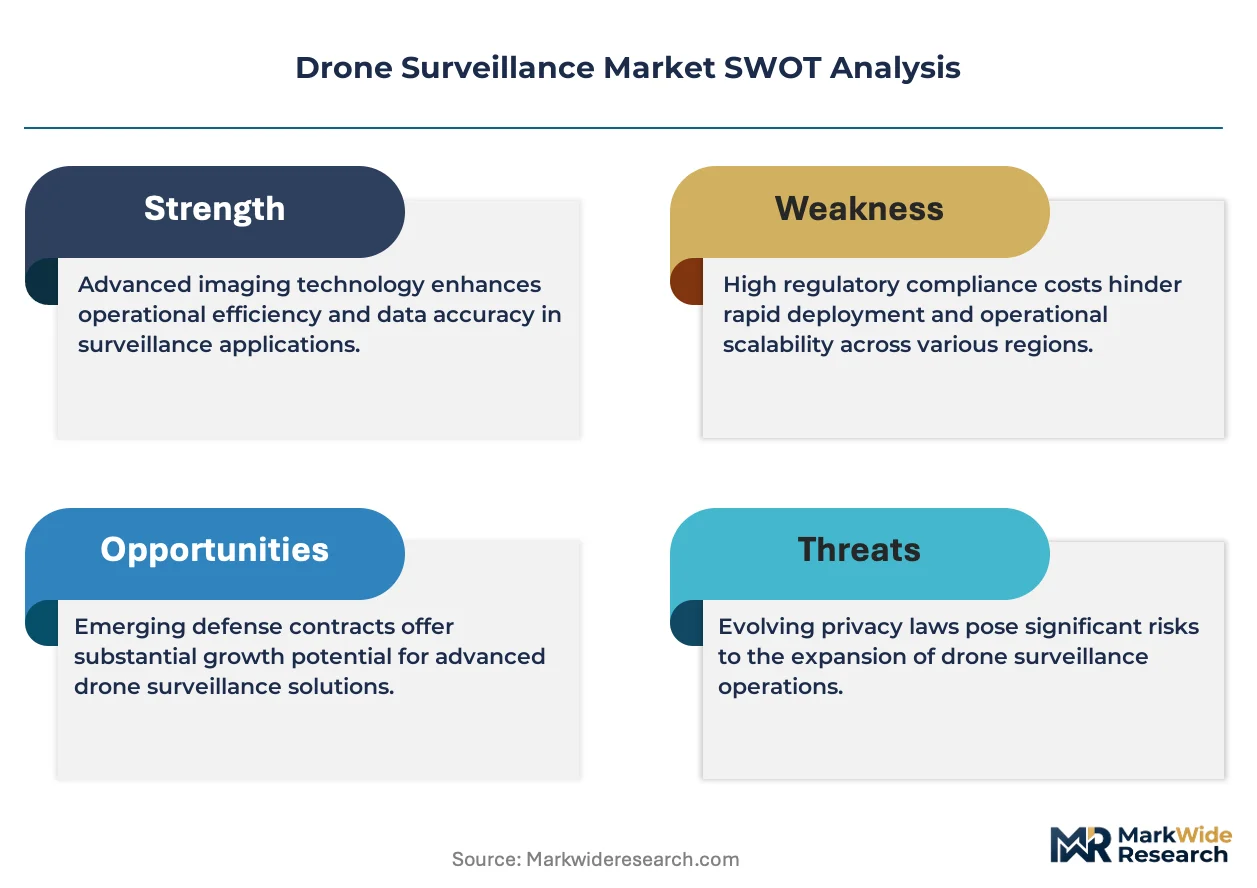
- Lithium-polymer battery supply concentration:Cell production clusters in East Asia create input cost volatility and geopolitical exposure for platform manufacturers.
- EASA type certification complexity:Fragmented national implementations of drone-specific frameworks delay multi-jurisdiction deployment timelines for commercial operators.
- Counter-drone system substitution:Ground-based radar and acoustic detection arrays compete for perimeter security budgets in critical infrastructure protection.
Strategic Opportunities
- India:PLI scheme incentives for drone manufacturing and DGFT import liberalization are opening domestic assembly and export channels.
- Autonomous docking infrastructure:Persistent perimeter monitoring without human-in-the-loop intervention addresses labor scarcity in remote facility security.
- ISO 21384-3 alignment:Standardized operational safety baselines reduce insurance underwriting friction and accelerate enterprise procurement decisions.
Industry Challenges
- Airspace deconfliction protocols:Integration with manned aviation traffic management systems requires capex-heavy ground control station upgrades and pilot retraining.
- Sensor payload interoperability:Proprietary data formats from infrared, electro-optical, and radar modules complicate multi-vendor fleet standardization for defense integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Surveillance Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $62.27 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed-Wing, Hybrid, Tactical End User: Government, Military, Agriculture, Construction Technology: Electro-Optical, Infrared, Radar, GPS Application: Monitoring, Reconnaissance, Inspection, Disaster Management |
| Companies Covered | BAE Systems Inc., Airobotics Ltd., Aerodyne Group, Cyberhawk Innovations Ltd., Terra Drone Corp., Sky-Futures Ltd., Percepto, Mistras Group, Avitas Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Surveillance Market Emerging Trajectories
Digital twin architectures are virtualizing mission planning and fleet coordination, compressing training cycles and enabling predictive failure modeling before physical deployment.
Synthetic aperture radar payloads are virtualizing all-weather surveillance capabilities previously requiring manned aerial platforms or satellite tasking. Energy utilities in the United States are adopting these systems for vegetation management along transmission corridors where cloud cover interrupts optical collection. The technology is virtualizing seasonal inspection windows into continuous monitoring regimes.
EASA's drone-specific framework is harmonizing type certification requirements across European member states while preserving national operational authority. Manufacturers are responding with modular platform designs that accommodate jurisdiction-specific radio frequency and data sovereignty modules. France and Germany are diverging in implementation timelines, creating transnational fleet deployment complexity.
Flight-hour-based service agreements are displacing capital purchase models for commercial inspection operators. Agricultural cooperatives in Australia and energy infrastructure managers in Canada are contracting predictive maintenance and pilot provision as bundled subscriptions. This reconfiguration shifts balance sheet treatment and reduces upfront technology adoption barriers for mid-scale enterprises.
Drone Surveillance Market Segmentation
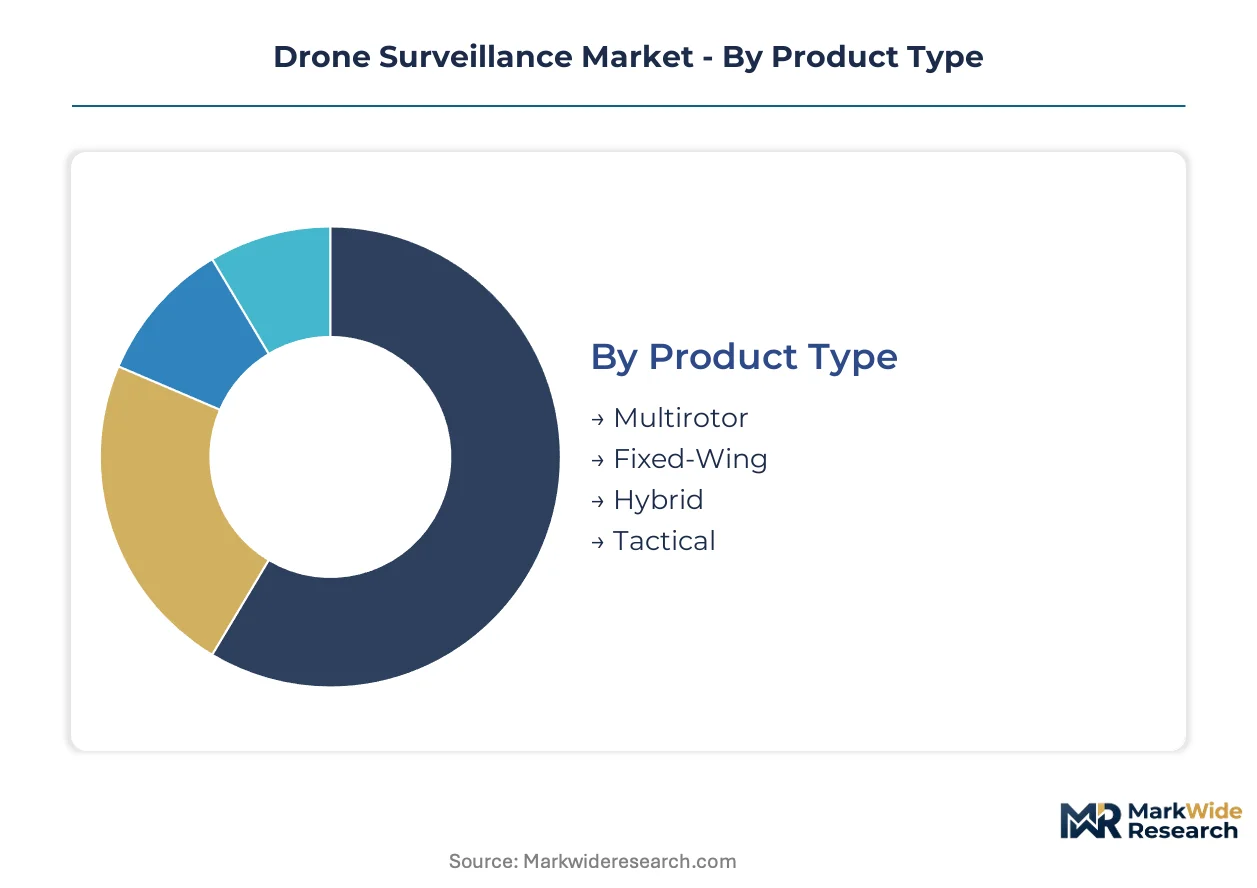
Drone surveillance procurement patterns diverge sharply across platform architectures, sensor payloads, and operational domains. Procurement officers and fleet managers navigate trade-offs between endurance, maneuverability, and regulatory compliance that reshape vendor selection criteria.
Product Type:
Platform architecture dictates mission duration, payload capacity, and airspace access permissions across defense and commercial deployments.
- Multirotor:Vertical takeoff and landing capability enables operation from confined launch zones without runway infrastructure. Energy utilities in Texas and California concentrate procurement here for substation inspection where precision hovering captures thermal anomalies on transformer equipment.
- Fixed-Wing:Aerodynamic efficiency extends endurance beyond four hours for maritime border patrol and pipeline corridor monitoring. NATO reconnaissance programs in Germany and Poland are standardizing procurement around these platforms with sovereign data processing modules.
- Hybrid:Combines multirotor agility with fixed-wing range through tilt-rotor or lift-plus-cruise configurations. Logistics operators in Australia deploy these for remote mining site surveillance where runway access is intermittent.
- Tactical:Man-portable systems with rapid deployment protocols for dismounted infantry units. Bundeswehr modernization programs specify these for forward reconnaissance teams operating in contested electromagnetic environments.
The dominant share belongs to Fixed-Wing, while Hybrid platforms are closing the gap fastest as battery energy density improvements extend electric range.
End User:
Budget cycles and procurement authority structures create distinct purchasing behaviors across institutional buyer categories.
- Government:Civilian agencies including border patrol, coast guard, and emergency management departments operate under appropriations-driven acquisition timelines. FAA Part 107 waiver clarity is accelerating deployment for infrastructure inspection mandates at the Department of Energy.
- Military:Defense procurement channels require sovereign security clearances and ITAR compliance that filter vendor pools. Multi-sensor payload integration with existing command systems drives specification requirements in NATO member states.
- Agriculture:Cooperative purchasing structures and seasonal cash flows shape adoption patterns. Australian cotton growers and Brazilian soybean operators contract flight-hour-based services rather than capital purchases.
- Construction:Project-based procurement aligns drone deployment with site development phases. Canadian infrastructure developers integrate aerial monitoring into progress reporting for institutional lenders.
Military buyers command the deepest procurement budgets, though Agriculture is expanding most quickly as liability frameworks mature for autonomous crop monitoring.
Technology:
Sensor payload selection determines environmental operating windows and data product utility for specific mission profiles.
- Electro-Optical:High-resolution visible spectrum imaging for documentation, mapping, and real-time video feeds. Construction progress monitoring in Dubai and Singapore relies on these payloads for millimeter-accurate photogrammetry.
- Infrared:Thermal detection capabilities for night operations and heat signature identification. German border patrol specifications require cooled infrared arrays for maritime smuggling interdiction.
- Radar:Synthetic aperture systems penetrate cloud cover and foliage for all-weather surveillance. US transmission utilities deploy these for vegetation management along Pacific Northwest corridors where persistent cloud layers interrupt optical collection.
- GPS:Precision navigation and georeferencing infrastructure enabling autonomous waypoint execution. EASA certification requirements mandate redundant GNSS receivers for beyond-visual-line-of-sight operations in French airspace.
Electro-Optical sensors retain the largest installed base, though Radar payloads are climbing the fastest as energy infrastructure operators demand continuous monitoring regimes.
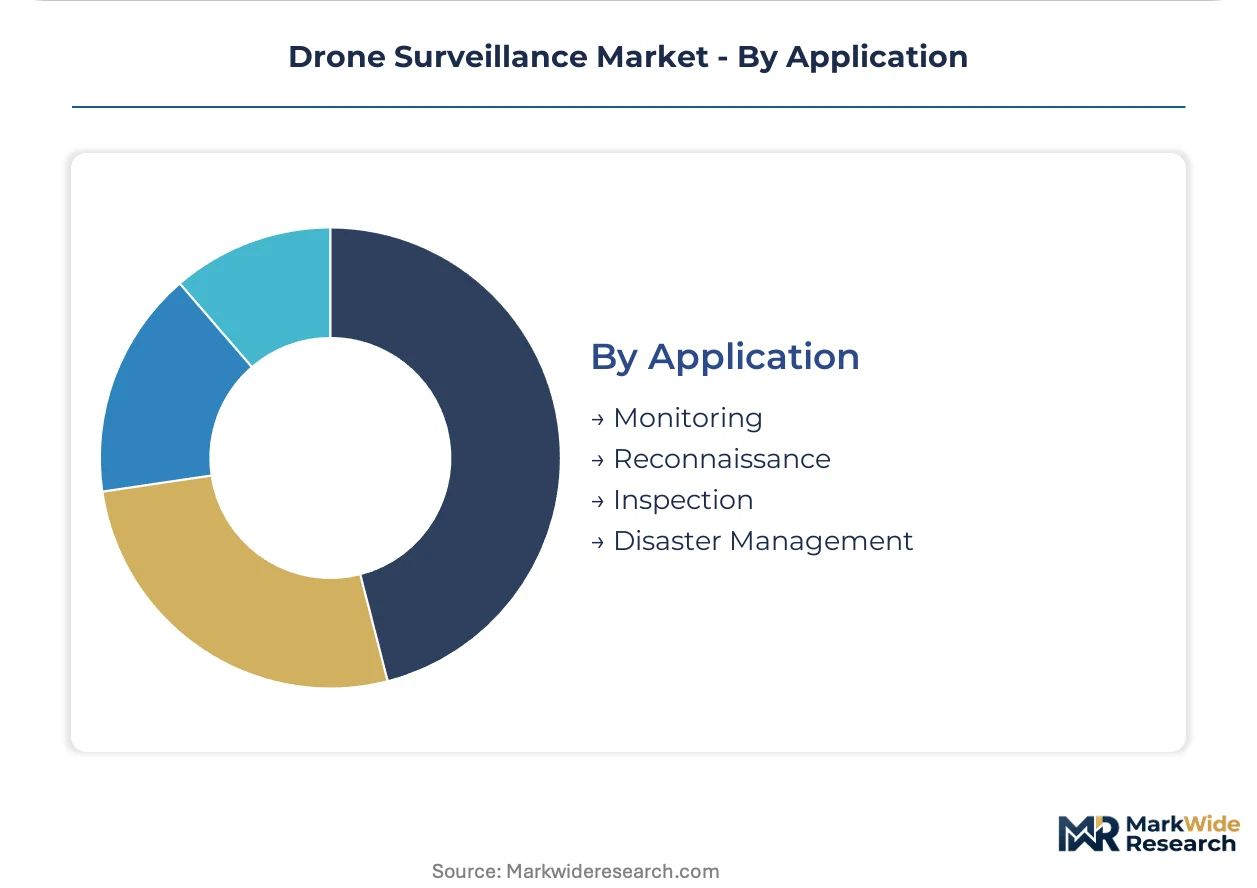
Application:
Mission type shapes platform specification, sensor configuration, and operator training requirements across deployment scenarios.
- Monitoring:Persistent observation of fixed facilities including prisons, power plants, and data centers. Autonomous docking stations in remote Alberta oil facilities eliminate human-in-the-loop requirements for perimeter security.
- Reconnaissance:Intelligence collection in contested or denied environments with low probability of detection requirements. Polish defense procurement specifies acoustic signature reduction for tactical reconnaissance platforms.
- Inspection:Structured data capture for asset condition assessment and predictive maintenance. Indian solar farm operators under PLI scheme incentives deploy thermal inspection for photovoltaic array fault detection.
- Disaster Management:Rapid deployment for search coordination and damage assessment following seismic or weather events. Japanese prefectural governments integrate drone surveillance into tsunami response protocols under METI coordination frameworks.
Inspection applications hold the dominant revenue position, while Disaster Management is gaining share fastest as climate-related emergency funding expands municipal procurement capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement channels. Defense buyers in NATO member states absorb premium pricing for sovereign data processing, while commercial operators in emerging markets prioritize flight-hour-based service models that minimize capital outlay.
United States
FAA Part 107 waiver expansions for beyond-visual-line-of-sight operations are compressing deployment timelines for energy infrastructure inspection. The Department of Energy mandates aerial monitoring for transmission corridor vegetation management. Texas and California utilities concentrate procurement of multirotor platforms equipped with thermal sensors for substation fault detection.
Germany
Bundeswehr reconnaissance program modernization drives tactical UAS procurement with electromagnetic signature reduction specifications. EASA drone-specific framework implementation delays commercial fleet standardization across German airspace. Bavaria hosts defense integrators developing sovereign data processing modules for NATO interoperability requirements.
India
PLI scheme incentives for drone manufacturing and DGFT import liberalization open domestic assembly and export channels for commercial surveillance operators. The Central Electricity Authority mandates thermal inspection protocols for solar photovoltaic installations. Karnataka and Gujarat host emerging assembly clusters serving agricultural cooperative demand for crop monitoring services.
Australia
Flight-hour-based service agreements dominate agricultural cooperative procurement for cotton and grain belt monitoring. The country's Civil Aviation Safety Authority clarifies liability frameworks for autonomous crop surveillance. Queensland and Western Australia mining operators contract persistent perimeter monitoring for remote facility security.
Japan
METI coordination frameworks integrate drone surveillance into prefectural tsunami response and disaster damage assessment protocols. Precision navigation requirements for beyond-visual-line-of-sight operations mandate redundant GNSS receiver configurations. Kanto region utilities deploy synthetic aperture radar for transmission corridor monitoring through persistent cloud cover.
Drone Surveillance Market Vendor Landscape
Capability concentration sits with defense contractors holding sovereign security clearances; scale advantage sits with distributed service networks aggregating pilot capacity across commercial inspection markets. The vendor base separates into three tiers: ITAR-compliant defense integrators, flight-hour-based commercial operators, and autonomous infrastructure specialists. Consolidation pressure runs through defense channel deepening and predictive maintenance contract aggregation.
Among defense-anchored integrators, BAE Systems Inc. exemplifies the sovereign clearance tier. Aerodyne Group occupies a position within distributed commercial service networks across Southeast Asian markets. Percepto sits within the autonomous infrastructure specialist archetype, representing persistent monitoring capabilities without human-in-the-loop requirements.
| Leading Market Players |
|---|
| BAE Systems Inc. |
| Airobotics Ltd. |
| Aerodyne Group |
| Cyberhawk Innovations Ltd. |
| Terra Drone Corp. |
| Sky-Futures Ltd. |
| Percepto |
| Mistras Group |
| Avitas Systems Inc. |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on lithium-polymer cells from East Asian production clusters compresses margin buffers across all pricing tiers while simultaneously forcing supply chain restructuring toward regional battery assembly partnerships. This dual pressure widens spreads between flight-hour-based service contracts and capital purchase models as operators seek to offload input cost volatility.
Pricing Analysis
Aftermarket service revenue anchored in predictive maintenance contracts and flight-hour-based support agreements drives lifetime value capture for platform vendors. Pricing stratifies across ITAR-compliant defense integrators, distributed commercial service networks, and autonomous infrastructure specialists based on sovereign security clearance depth and pilot network density. Cost compression in commercial multirotor segments intensifies as battery supply volatility feeds through to equipment leasing rates. Agricultural cooperatives in Australia exhibit highest price sensitivity, while NATO defense procurement channels absorb premium positioning for sovereign data processing modules.
Supply Chain Analysis
Extended payment terms from Tier 1 defense integrators cascade through component suppliers, compressing working capital cycles for infrared sensor and flight control module manufacturers. Cell production clusters in China, South Korea, and Japan anchor lithium-polymer supply, while German and Israeli specialists concentrate cooled infrared array fabrication. Single-source vulnerability in rare earth magnet sourcing for electric propulsion motors threatens platform delivery timelines. Distribution runs through defense procurement channels with sovereign clearance requirements, direct OEM sales to energy utilities, and distributed pilot networks aggregating inspection capacity across commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone surveillance platform economics are converging around autonomous docking infrastructure that virtualizes persistent monitoring into subscription-based perimeter security, with interoperability standards determining ecosystem capture.
For Market Incumbents: Harden defense channel relationships through deeper ITAR compliance investments and sovereign data processing certification expansion into Bundeswehr and Polish procurement programs. Counter emerging autonomous infrastructure specialists by acquiring predictive maintenance contract portfolios that aggregate flight-hour volume and lock in enterprise inspection mandates at Department of Energy facilities. For New Entrants and Emerging Players: Build out flight-hour-based service capacity targeting Australian agricultural cooperatives and Canadian energy infrastructure managers where liability framework clarity reduces adoption friction. Penetrate India's PLI scheme assembly clusters through domestic pilot network partnerships that satisfy Central Electricity Authority thermal inspection mandates for solar photovoltaic installations. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors autonomous infrastructure specialists with captive docking station deployment and ISO 21384-3 certification alignment. Long-term viability rests on persistent perimeter monitoring contracts that eliminate human-in-the-loop requirements. Watch FAA beyond-visual-line-of-sight rulemaking acceleration as the inflection signal for commercial operator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Docking Infrastructure Deployment | Eliminates pilot labor costs for continuous facility monitoring at remote Alberta oil sites. |
| Sovereign Data Processing Module Development | Unlocks Bundeswehr and NATO reconnaissance program procurement with electromagnetic signature compliance. |
| Flight-Hour-Based Service Network Expansion | Captures Australian cotton grower demand through bundled predictive maintenance subscriptions. |
| ISO 21384-3 Certification Alignment | Reduces insurance underwriting friction for enterprise procurement decisions across EASA jurisdictions. |
| PLI Scheme Domestic Assembly Partnership | Positions for Central Electricity Authority solar inspection mandates in Karnataka and Gujarat clusters. |
Methodological Framework
The analysis maps fixed-wing, multirotor, hybrid, and tactical platform architectures, each validated through defense procurement officers, commercial fleet managers, energy utility inspection coordinators, and agricultural cooperative purchasing leads. Primary fieldwork combined structured interviews with platform OEMs, sensor payload integrators, and distributed service network operators against secondary validation from FAA Part 107 waiver databases, EASA type certification registries, Bundeswehr modernization program disclosures, and PLI scheme incentive filings. Bottom-up fleet deployment estimates triangulated against top-down defense appropriations tracking and commercial operator flight-hour aggregation.
Assumptions held fixed include FAA beyond-visual-line-of-sight waiver expansion trajectory, EASA framework harmonization timelines, and lithium-polymer cell supply concentration patterns, while varying platform energy density improvement rates and sovereign data processing mandate adoption across NATO member states. The analytical framework modeled segmentation across platform architecture, sensor payload technology, end-user procurement channel, and application mission type throughout the projection horizon. CAGRs derived from deployment volume trajectory analysis weighted by procurement budget depth in defense versus commercial channels, with specific inputs from infrared sensor miniaturization curves and autonomous docking station penetration assumptions.
Practitioners should monitor FAA rulemaking acceleration, EASA national implementation divergence, and counter-drone mandate emergence for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
North America Passive Radar Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Military Radar Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market