
 EMEA Dismounted Soldier Systems Market | 2026-2036
EMEA Dismounted Soldier Systems Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Dismounted Soldier Systems Market Foresight
The shift from single-source national programs toward multi-source NATO framework contracts is restructuring how European ministries acquire dismounted soldier equipment. Rheinmetall AG leverages its German manufacturing base to anchor large-volume orders across Central Europe. Thales Group competes through sensor-integration capabilities that span communication and tactical-wearable subsystems. Saab AB specializes in lightweight load-carriage systems that meet Nordic mobility requirements.
Dismounted soldier systems comprise integrated personal combat equipment combining ballistic protection, networked communications, power management, and sensor fusion into a single wearable architecture. These systems typically integrate Level III+ or Level IV body armor plates with 24-hour battery-powered tactical radios and helmet-mounted displays to sustain continuous situational awareness during extended ground operations. Weapon systems and communication equipment represent the most mature segments with established procurement channels, while tactical wearables and sensor integration command expanding budget allocations as digitization priorities intensify. Networked systems attract the fastest-growing investment because they enable real-time data sharing between individual soldiers and command nodes.
EU Green Deal procurement criteria and the F-Gas Regulation constrain material choices for power systems and thermal management components across member state tenders. REACH compliance requirements shape chemical safety standards for ballistic fabrics and coatings used in body armor production. EMA and national defense procurement agencies coordinate medical-equipment interoperability standards for embedded casualty-care modules. Stakeholders must monitor how the EU Defense Industrial Strategy alters cross-border joint procurement mechanisms and whether non-EU suppliers face adjusted market access conditions.
Market Dynamics
The EU Defense Industrial Strategy is consolidating national procurement into cross-border framework agreements, compressing vendor margins while accelerating standardization of soldier system architectures across member states.
Growth Catalysts
- EU Green Deal procurement criteria:Defense ministries now mandate REACH-compliant ballistic fabrics and low-GWP thermal management, opening certified supplier slots for sustainable material providers.
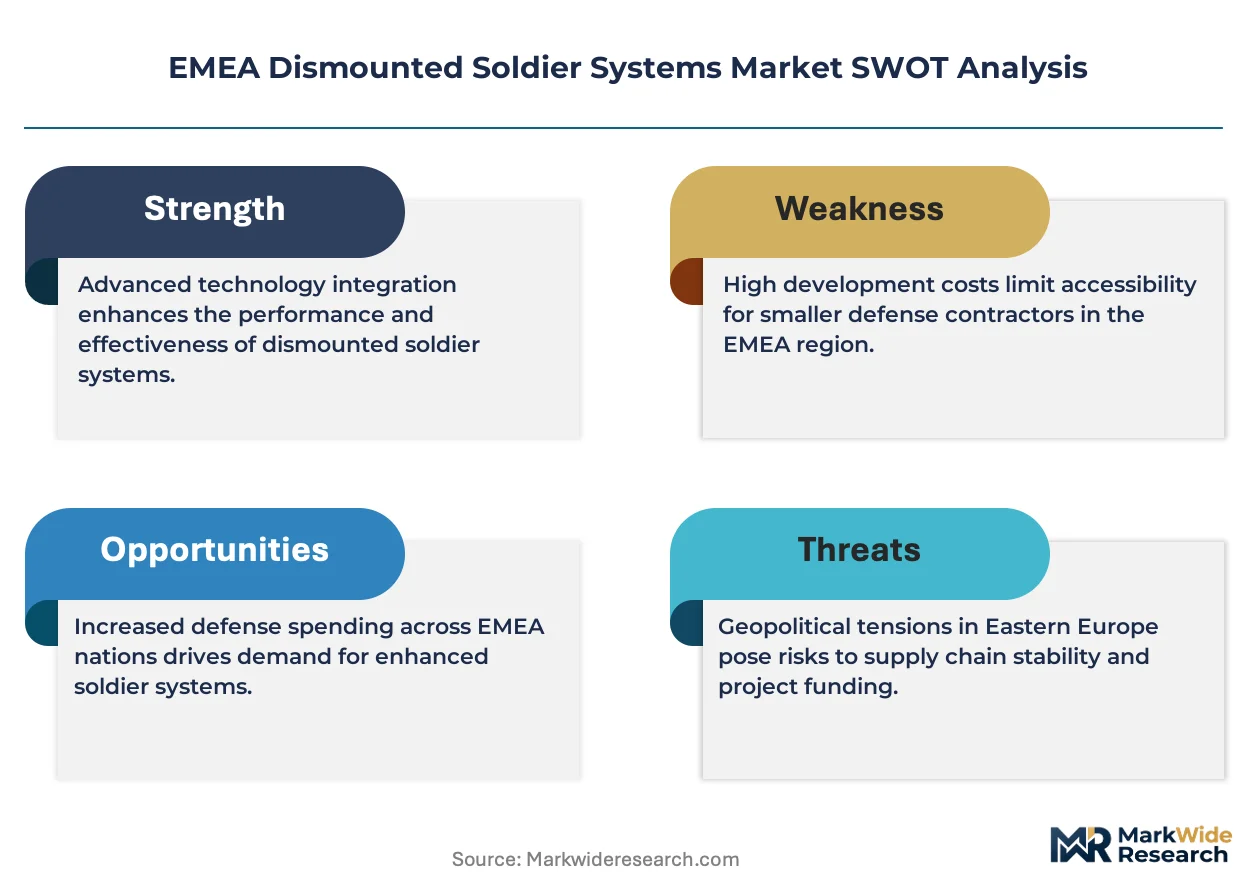
- Special operations forces modernization:Tier-one units across Germany, France, and the United Kingdom are replacing legacy kit with integrated load-carriage and power-distribution platforms.
- NATO framework contracting:Allied procurement offices pool dismounted soldier equipment volumes, creating multi-year demand visibility for subsystem integrators.
Market Restraints
- Ballistic ceramic supply concentration:Sintered alumina and silicon carbide plate production clusters in Eastern European foundries, exposing buyers to single-source disruption risk.
- F-Gas Regulation compliance costs:REACH and EU thermal management rules restrict refrigerant and phase-change material choices, extending qualification timelines for power system vendors.
- Legacy radio interoperability:Proprietary waveforms in existing tactical communication networks block seamless integration with next-generation soldier-worn terminals.
Strategic Opportunities
- Nordic mobility requirements:Saab AB's lightweight carriage designs for Swedish and Norwegian arctic units demonstrate exportable architectures for Baltic procurement programs.
- Embedded casualty-care modules:EMA-coordinated medical equipment standards create openings for trauma monitoring and automated tourniquet subsystems in French and German tenders.
- AI-enabled sensor fusion:Convergence of helmet-mounted displays with biometric monitoring is compressing situational awareness latency for platoon-level command nodes.
Industry Challenges
- Systems integration engineering talent:Shortages of power electronics and RF engineers delay platform qualification for networked soldier architectures.
- Multi-national certification timelines:Divergent national defense procurement agency test protocols force redundant validation cycles for cross-border framework bids.
- Legacy battery form factor lock-in:Existing vest-integrated power compartments constrain adoption of higher-density solid-state cell designs without platform redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Dismounted Soldier Systems Market |
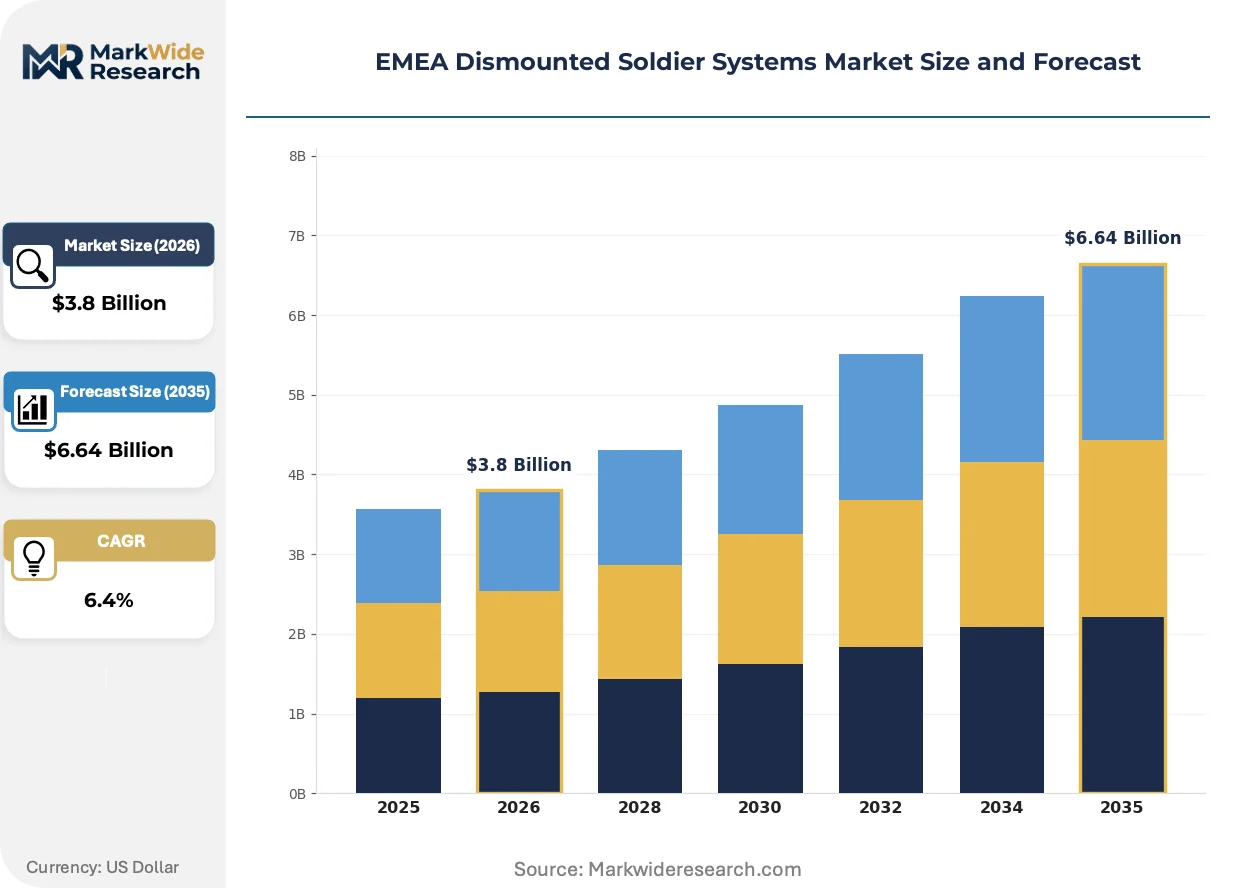
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Armor, Load Carriage, Communication Equipment, Weapon Systems Technology: Networked Systems, Sensor Integration, Mobility Solutions, Tactical Wearables End User: Infantry Forces, Special Operations, Military Agencies, Defense Contractors Application: Combat Operations, Training Exercises, Humanitarian Missions, Surveillance |
| Companies Covered | Elbit Systems Ltd., Lockheed Martin Corporation, Rheinmetall AG, Saab AB, Leonardo S.p.A., BAE Systems plc, L3Harris Technologies, General Dynamics European Land Systems, Thales Group, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Dismounted Soldier Systems Market Shifts & Advancements
Digital integration is compressing the boundary between personal protection and networked warfare, with power management and data fusion now treated as coequal design priorities rather than add-on capabilities.
Helmet-mounted display systems are modularizing soldier-worn computing architectures across European special operations units. German Bundeswehr procurement offices now specify open-interface headborne electronics that separate display, processing, and power into swappable subsystems. This architecture is modularizing vendor selection, allowing end-users to mix Thales optics with Rheinmetall power management without platform lock-in.
REACH compliance requirements are reshaping material specifications for ballistic protection and coatings production. The European Chemicals Agency's updated substance restrictions now govern flame-retardant treatments and adhesive formulations in body armor laminates. French and Belgian defense procurement agencies have accelerated supplier audits to verify SVHC-free supply chains ahead of 2027 tender deadlines.
Joint procurement through NATO support and procurement agencies is consolidating buyer power while fragmenting vendor access. National ministries are pooling dismounted soldier system volumes into multi-year framework contracts that displace single-source national programs. This concentration is most visible in Central European orders, where Polish and Czech defense offices now coordinate specification alignment to qualify for pooled financing mechanisms.
EMEA Dismounted Soldier Systems Market Segmentation
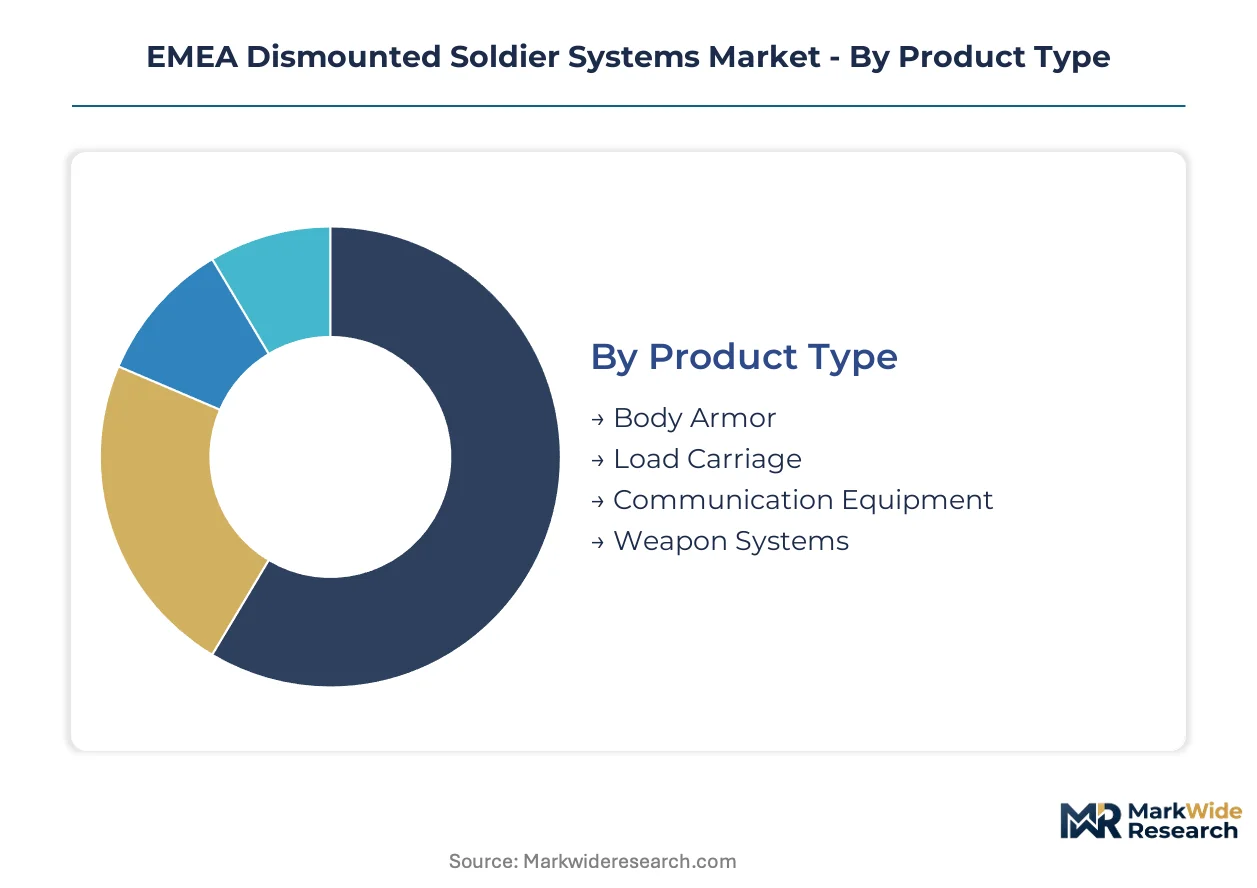
Dismounted soldier systems require heterogeneous capital allocation across protection, connectivity, and lethality subsystems. Procurement offices weight lifecycle cost against mission-critical performance when segmenting budget authority. Vendor specialization patterns follow these capital-intensity gradients.
Product Type:
Capital requirements peak in ceramic-composite armor manufacturing due to sintering infrastructure and ballistic testing facilities. Load carriage and communication equipment demand lower fixed-asset thresholds but higher software development intensity.
- Body Armor:Level III+ and Level IV ceramic plates combine sintered alumina or silicon carbide with aramid backing to defeat rifle threats. German and French procurement offices concentrate orders for multi-curve designs that balance coverage against mobility degradation.
- Communication Equipment:Software-defined radios with embedded encryption modules require semiconductor fabrication partnerships and waveform certification cycles. NATO framework contracts pool demand for interoperable soldier-worn terminals across Central European member states.
- Load Carriage:Modular vest platforms distribute equipment weight across the torso and hips.
- Weapon Systems:Individual small arms and sighting modules integrate with soldier-worn power and data architectures.
Most installed capacity flows through Body Armor. Expansion is steepest in Communication Equipment.
Technology:
Application specificity separates battlefield-proven segments from emerging integration layers. Mature technologies compete on cost-per-unit; nascent categories compete on architectural control.
- Networked Systems:Mesh radio networks and soldier-worn computing nodes enable real-time data exchange between dismounted personnel and command elements. British Army modernization programs prioritize these architectures for platoon-level situational awareness.
- Sensor Integration:Helmet-mounted displays, biometric monitors, and environmental sensors fuse multiple data streams into actionable intelligence. Nordic special operations units drive specification requirements for lightweight, low-power implementations.
- Mobility Solutions:Exoskeleton assistive devices and load-redistribution mechanisms address musculoskeletal injury rates.
- Tactical Wearables:Smart textiles with embedded power distribution and physiological monitoring capabilities.
Revenue concentration sits with Networked Systems. Sensor Integration gains share fastest as digitization timelines accelerate.
End User:
Procurement authority fragmentation creates distinct customer segments with divergent technical specifications and contract vehicles. Budget scale and operational tempo separate institutional buyers.
- Special Operations:Tier-one units in the United Kingdom, France, and Germany procure integrated kits through classified acquisition channels with shortened qualification timelines. These forces prioritize modularity and rapid technology refresh over standardization.
- Infantry Forces:Conventional ground combat units across EMEA member states purchase through national defense procurement agencies with multi-year framework agreements. Volume concentration in Polish and Czech orders shapes regional supplier selection.
- Military Agencies:Research and development organizations evaluate emerging technologies for future standardization.
- Defense Contractors:System integrators and subsystem vendors serve as indirect procurement channels for government clients.
Special Operations commands the highest per-soldier expenditure. Infantry Forces aggregate the largest absolute procurement volumes.
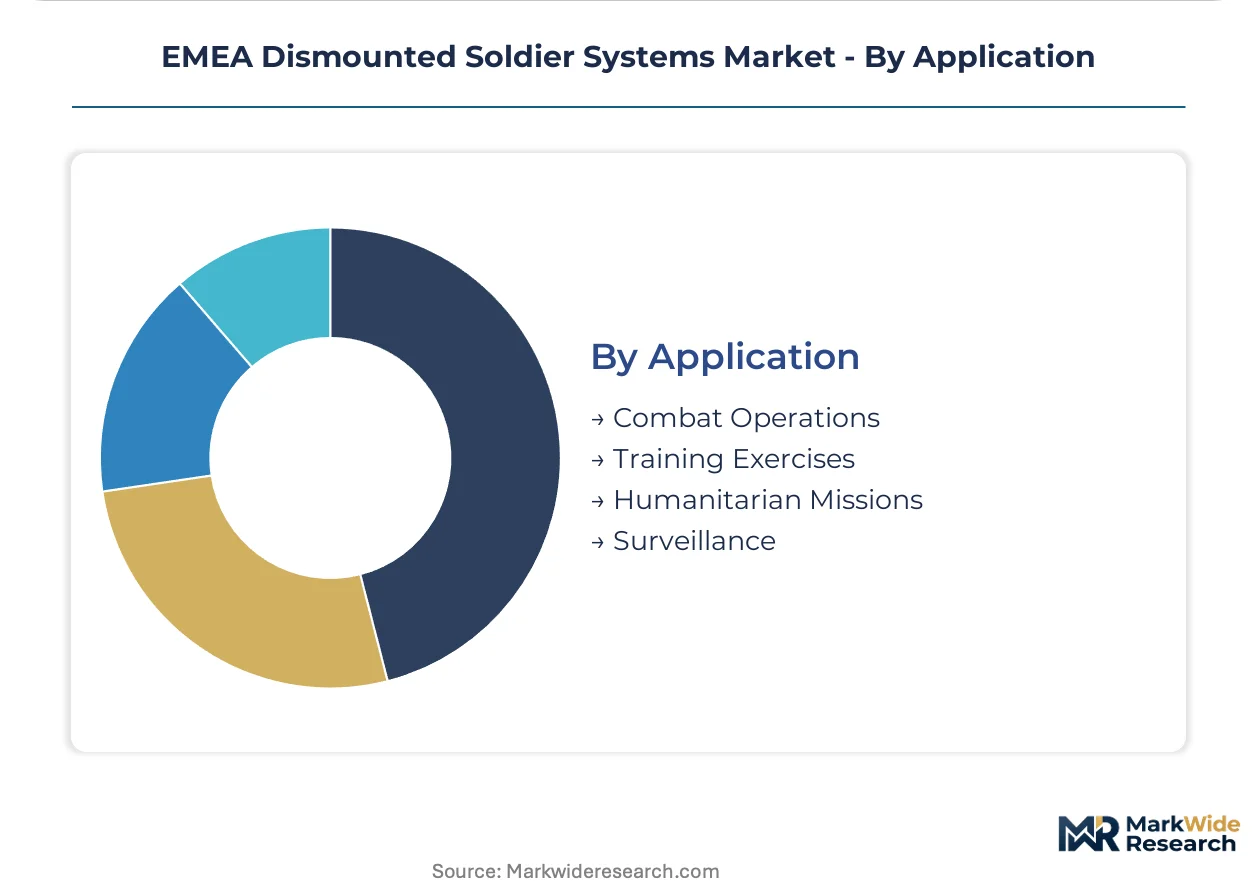
Application:
Mission profile determines equipment configuration and replacement frequency. Combat employment drives the most demanding performance specifications and shortest upgrade cycles.
- Combat Operations:Full-system deployment under hostile conditions requires maximum protection levels, continuous power supply, and jam-resistant communications. French and German deployments to external operations theaters sustain demand for expeditionary-configured soldier systems.
- Training Exercises:Repeated use in simulated combat environments prioritizes durability and cost-effective repairability over cutting-edge performance. Baltic state training programs emphasize interoperability validation for NATO collective defense scenarios.
- Humanitarian Missions:Reduced threat profiles permit lighter protection configurations with enhanced mobility.
- Surveillance:Extended stationary observation demands power-efficient sensor and communication packages.
Combat Operations absorbs the majority of fielded systems. Training Exercises represents the largest addressable expansion opportunity as readiness investments intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Düsseldorf-Cologne corridor anchors EMEA defense manufacturing, hosting Rheinmetall's headquarters and dense supplier networks for ballistic ceramics and power electronics. National procurement fragmentation persists despite EU Defense Industrial Strategy harmonization efforts.
Germany
Bundeswehr special operations modernization drives integrated soldier kit procurement through shortened acquisition channels. The Federal Office of Bundeswehr Equipment prioritizes REACH-compliant ballistic fabrics under EU Green Deal procurement criteria. Bavarian foundries in Nuremberg supply sintered silicon carbide plates for multi-curve body armor designs.
United Kingdom
British Army platoon-level digitization programs prioritize networked soldier-worn computing nodes for situational awareness. Ministry of Defence framework contracts now mandate open-interface headborne electronics specifications. Greater London defense procurement offices coordinate with NATO support agencies for pooled equipment volumes.
France
French external operations sustain demand for expeditionary-configured soldier systems with continuous power supply requirements. The Direction Générale de l'Armement enforces EMA-coordinated medical equipment interoperability standards for embedded casualty-care modules. Toulouse-area integrators specialize in sensor-fusion subsystems for helmet-mounted displays.
Poland
Polish defense offices accelerate procurement through NATO framework contracting mechanisms alongside Czech coordination for specification alignment. National tenders increasingly reference F-Gas Regulation compliance for thermal management components. Warsaw procurement clusters concentrate load-carriage system integration for Central European collective defense scenarios.
Sweden
Swedish and Norwegian arctic units drive lightweight carriage specifications that emphasize Nordic mobility requirements over protection-heavy configurations. Saab AB's Linköping engineering base exports modular vest architectures to Baltic procurement programs. Swedish defense procurement agencies audit SVHC-free supply chains ahead of 2027 REACH tender deadlines.
EMEA Dismounted Soldier Systems Market Competitive Landscape
Global majors compete with regional champions across subsystem integration, with European primes holding advantage in NATO-certified communication equipment while Israeli and American firms penetrate sensor fusion niches. Market structure tilts toward consolidated platform integrators controlling multi-year framework contracts, yet fragmentation persists in specialized ballistic materials and power electronics. Three archetypes dominate: full-system integrators bundling protection-communication-power architectures; subsystem specialists delivering certified radio or display modules; and materials suppliers commanding sintered ceramic plate production. Competitive dynamics center on strategic partnerships for waveform interoperability and capacity expansion in Eastern European foundry capacity.
Among full-system integrators, Rheinmetall AG anchors large-volume Central European orders through its German manufacturing base, while Thales Group exemplifies sensor-integration specialists spanning communication and tactical-wearable subsystems. Saab AB occupies a distinctive position serving Nordic mobility requirements with lightweight load-carriage architectures exportable to Baltic programs. These three represent the competitive archetypes reshaping vendor selection as modular open-interface specifications displace platform lock-in.
| Leading Market Players |
|---|
| Elbit Systems Ltd. |
| Lockheed Martin Corporation |
| Rheinmetall AG |
| Saab AB |
| Leonardo S.p.A. |
| BAE Systems plc |
| L3Harris Technologies |
| General Dynamics European Land Systems |
| Thales Group |
| Others |
Supply & Pricing Matrix
Modular open-interface specifications for helmet-mounted electronics are compressing platform lock-in premiums while fragmenting vendor pricing power across subsystem tiers. This architectural shift simultaneously lowers switching costs for defense procurement offices and concentrates margin capture among certified materials suppliers facing REACH compliance deadlines.
Pricing Analysis
Input-cost pass-through from sintered alumina and silicon carbide plate manufacturing runs through multi-year NATO framework contracts with limited renegotiation windows. Three-tier pricing structure across expeditionary-grade, standard-issue, and training-configured equipment levels reflects certification grade and volume scale differentiation. Pricing pressure stems from EU Green Deal procurement criteria mandating SVHC-free ballistic fabrics, which extends supplier qualification timelines. Infantry Forces exhibit highest price sensitivity due to aggregate volume procurement authority, while Special Operations commands tolerate premium positioning for rapid technology refresh cycles.
Supply Chain Analysis
Reverse-logistics flows for body armor refurbishment and radio terminal remanufacturing create secondary material recovery channels that compete with virgin ceramic plate production. Sintered silicon carbide manufacturing concentrates in Germany, Poland, and Czechia, while aramid fiber backing production draws from Belgian and French textile clusters. Raw material dependencies span high-purity alumina feedstock, rare-earth elements for RF components, and lithium-ion cells for power management. Single-source vulnerability in Eastern European foundry capacity represents the dominant structural risk. Distribution runs through national defense procurement agencies coordinating via NATO support mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMEA Dismounted Soldier Systems Market reads as a late-cycle quality story where procurement offices prioritize REACH-compliant, modular architectures over lowest-bidder selection. Tier-one unit demand for integrated load-carriage and power-distribution platforms is shifting specifications toward premium-certified subsystems.
For Market Incumbents: Extend certification coverage across EMA-coordinated medical equipment interoperability standards to anchor embedded casualty-care module procurement. Deepen backward integration into sintered ceramic plate production through Bavarian and Polish foundry partnerships. Lock in multi-year NATO framework contract positions before open-interface specifications fragment platform control. For New Entrants and Emerging Players: Capture Nordic mobility requirement specifications for lightweight load-carriage systems exportable to Baltic procurement programs. Penetrate the sensor integration segment where helmet-mounted display convergence with biometric monitoring remains under-supplied. Lead with AI-enabled situational awareness latency reduction as the primary go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among subsystem specialists with certified radio waveform portfolios and SVHC-free supply chain audit completion. Five-to-ten-year viability hinges on EU Defense Industrial Strategy harmonization sustaining cross-border framework contract volumes. Monitor Polish-Czech specification alignment coordination as the critical inflection signal for Central European demand consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | EMA and ECHA substance restrictions now govern body armor laminate formulations across French and Belgian tenders. |
| NATO Framework Contract Positioning | Pooled procurement mechanisms in Central Europe compress vendor margins while accelerating multi-year demand visibility. |
| Open-Interface Architecture Development | German Bundeswehr specifications for swappable headborne electronics subsystems displace platform lock-in premiums. |
| Eastern European Foundry Expansion | Sintered silicon carbide capacity additions in Poland and Czechia reduce single-source disruption exposure for ceramic plate supply. |
| Embedded Casualty-Care Module Integration | French Direction Générale de l'Armement tenders now require trauma monitoring and automated tourniquet interoperability standards. |
Research Methodology
Direct dialogue with defense procurement officers, subsystem integration engineers, ballistic materials specialists, and NATO support agency coordinators grounded qualitative findings in operational procurement constraints. Secondary validation drew from EU Defense Industrial Strategy policy documents, ECHA substance restriction updates, national tender specifications, and customs trade data for ceramic plate and radio terminal categories. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis across the analysis window.
Segment-level projections across product type, technology, end user, and application dimensions fed into analytical framework outputs spanning the projection horizon. CAGRs derived from procurement timeline modeling incorporating qualification cycle durations, framework contract renewal patterns, and technology refresh cadences specific to soldier-worn power management and networked communication equipment.
Defense budget reallocation shocks, REACH substance restriction amendments, and NATO collective defense posture revisions are the dominant revision risks to modeled assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Drone Jamming System Market
Unmanned Systems
Military Robots Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market