
 Military Unmanned Ground Vehicle Market | 2026-2036
Military Unmanned Ground Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Military Unmanned Ground Vehicle Market Foresight
Software-defined autonomy packages are recalibrating what militaries procure, shifting capital expenditure from hardware-centric platforms to updatable mission systems. Rheinmetall AG leverages its sensor fusion architecture to anchor European NATO requirements for manned-unmanned teaming. Milrem Robotics competes through modular payload interfaces that allow rapid reconfiguration between logistics and combat support roles. QinetiQ Group sustains long-term service contracts covering predictive maintenance and over-the-air capability upgrades for British Army platforms.
Military unmanned ground vehicles are self-propelled robotic systems operating on land without onboard human operators, typically weighing between 200 kilograms and 12 metric tons and integrating LiDAR, thermal imaging, and mesh-network communications for beyond-line-of-sight command. Their primary purpose spans explosive ordnance disposal, perimeter surveillance, and resupply convoys in denied electromagnetic environments. Armed vehicle types command the largest committed procurement budgets, while autonomous operation modes represent the fastest-growing capability tier as militaries seek to reduce operator cognitive load in contested networks. Combat support applications concentrate the deepest margin pools due to recurring integration contracts with legacy command systems.
The U.S. Department of Defense, the European Defence Agency, and the UK Ministry of Defence shape demand through autonomous systems roadmaps that mandate open architecture standards and cybersecurity certification for networked ground robots. These frameworks restrict market access for platforms failing interoperability protocols or electromagnetic resilience testing. Stakeholders must monitor how export control revisions affecting sensor and AI components reshape supplier eligibility across allied procurement programs.
Market Dynamics
Defense procurement offices are compressing validation cycles for autonomous ground systems as contested logistics scenarios expose vulnerabilities in manned convoy operations. The shift from demonstration programs to multi-year production contracts is restructuring supplier relationships around software update velocity rather than hardware durability metrics.
Growth Catalysts
- Contested Electromagnetic Environment Protocols:NATO expeditionary exercises in the Baltic states and Pacific theater are mandating mesh-network resilience standards that only autonomous platforms with distributed command architectures can satisfy.
- Autonomous Systems Roadmaps:The U.S. Department of Defense's Replicator initiative and similar frameworks in Australia and Germany are converting pilot programs into operational procurement streams with defined unit cost targets.
- Explosive Ordnance Disposal Backlogs:Demining commitments in Eastern Europe and the Caucasus are outstripping trained human operator availability, forcing procurement of semi-autonomous detection platforms with remote supervisory control.
Market Restraints
- High-Grade Sensor Cost Volatility:Solid-state LiDAR and cooled thermal imagers face supply concentration in East Asian component foundries, exposing program budgets to tariff and export control fluctuations.
- Cybersecurity Certification Friction:The UK Ministry of Defence's NITES and similar national frameworks impose multi-year validation timelines that delay platform deployment even after technical readiness.
- Human Operator Substitution Thresholds:Armed reconnaissance missions retain human-in-the-loop requirements under most national rules of engagement, capping addressable demand for fully autonomous combat variants.
Strategic Opportunities
- Autonomous Logistics in Arctic Conditions:Norway and Finland are testing unmanned ground vehicles for resupply across denied GPS environments, creating demand for inertial navigation and terrain-relative positioning packages.
- AI-Enabled Predictive Maintenance:Convergence of edge computing and vibration analysis sensors allows platform-as-a-service contracts that bundle hardware with guaranteed availability rather than capital purchase.
- Interoperability Standards Gap:The absence of unified NATO datalink protocols for ground robots creates openings for middleware vendors who can bridge national command systems during coalition operations.
Industry Challenges
- Autonomy Software Talent Scarcity:Military clearance requirements and compensation gaps relative to commercial autonomous vehicle developers constrain recruitment of perception and path-planning engineers.
- Legacy System Integration Complexity:Battle management systems fielded in the 2000s lack open APIs, forcing costly adapter development for each national customer.
- Electromagnetic Resilience Testing Bottlenecks:Only three accredited facilities in the United States and Germany can validate platforms against high-power jamming scenarios, creating program schedule risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Unmanned Ground Vehicle Market |
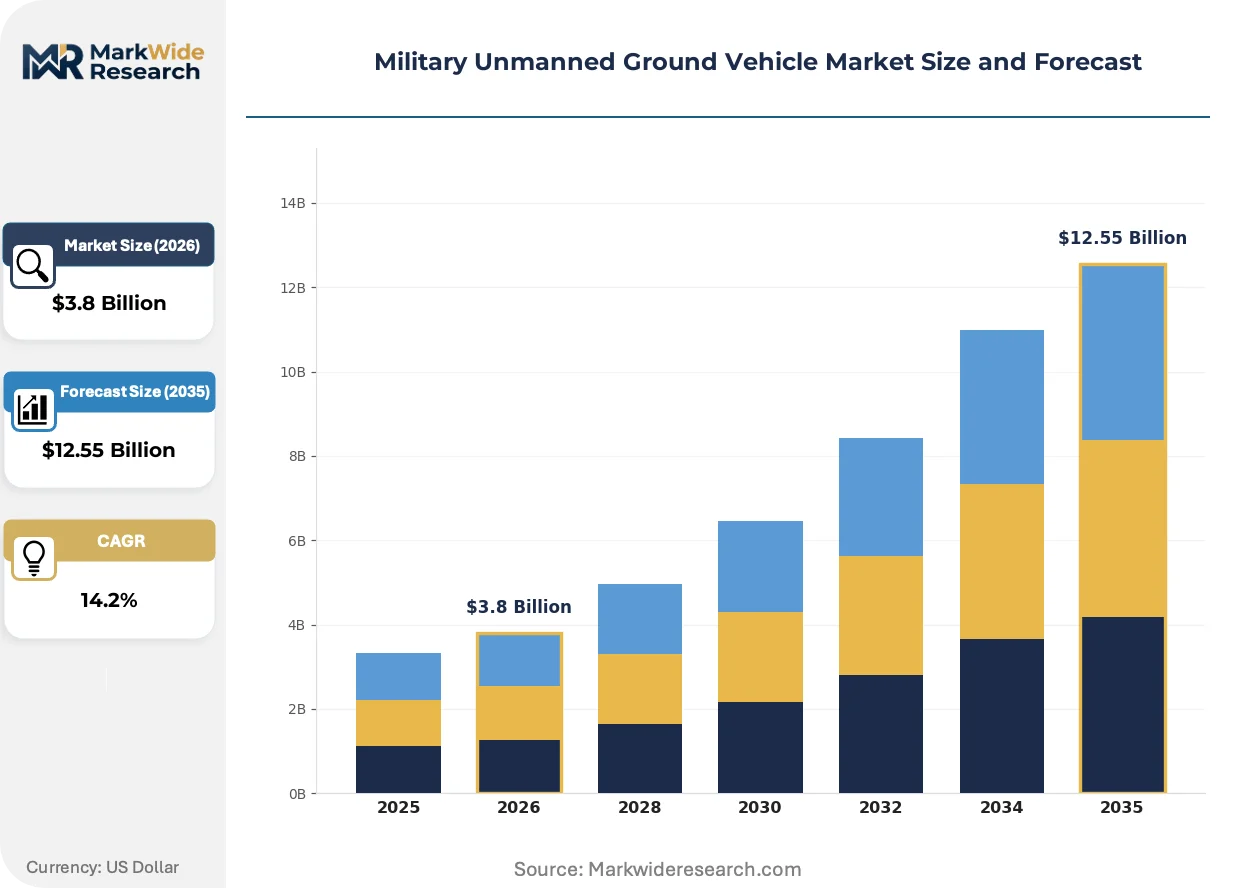
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
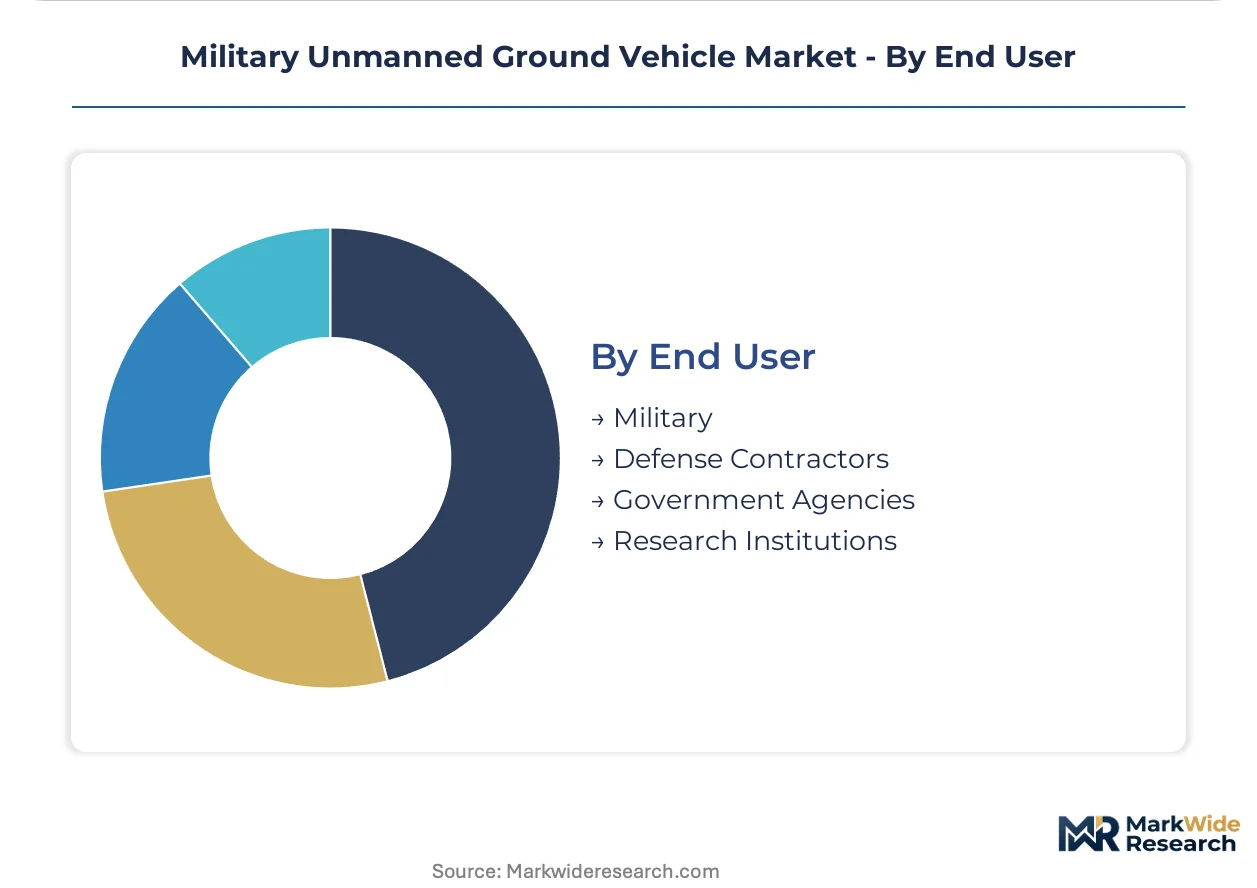
| Segmentation | Vehicle Type: Reconnaissance, Logistics, Surveillance, Armed Operation Mode: Remote Controlled, Autonomous, Semi-Autonomous, Teleoperated Application: Combat Support, Search & Rescue, Border Security, Explosive Disposal End User: Military, Defense Contractors, Government Agencies, Research Institutions |
| Companies Covered | Rheinmetall AG, QinetiQ Group, Oshkosh Defense, Textron Systems, China North Industries Group Corporation, Milrem Robotics, ASELSAN, BAE Systems, Roboteam Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Unmanned Ground Vehicle Market Shifts & Advancements
Software-defined mission architectures are displacing fixed-function hardware platforms across military robotics, enabling capability upgrades through over-the-air updates rather than physical retrofit. This shift is compressing procurement cycles and expanding the addressable supplier base beyond traditional defense primes.
Sensor fusion middleware is modularizing around containerized perception stacks that separate hardware drivers from mission logic. Defense ministries in Germany and Australia are mandating this separation in tender specifications, allowing component swaps without re-certifying entire platforms. The architecture is compressing integration timelines for new payload types from years to months.
The EU AI Act's risk classification framework for autonomous weapons systems is forcing European suppliers to document algorithmic decision boundaries and human override protocols. Manufacturers serving NATO export markets must now maintain dual compliance tracks: national military certification and EU conformity assessment. Armed reconnaissance platforms face the steepest documentation burdens, shifting development resources toward logistics variants.
Buyers are unbundling platform purchase from through-life support, demanding availability-based contracts with penalties for mission aborts. The British Army's MORPHEUS program and similar Australian initiatives specify performance metrics rather than technical specifications, transferring operational risk to contractors. This model concentrates margin in predictive analytics and spare parts pre-positioning rather than initial hardware sale.
Military Unmanned Ground Vehicle Market Segmentation

Military unmanned ground vehicle procurement decisions cascade through multiple specification layers, from mission profile to command architecture. Understanding how these dimensions intersect reveals where defense budgets concentrate and where technology roadmaps diverge.
Vehicle Type:
Platform weight classes and payload hardpoints determine which missions command sustained funding versus experimental allocations.
- Reconnaissance:Lightweight platforms under 500 kilograms dominate this segment, integrating mast-mounted electro-optical turrets for standoff target identification. Demand concentrates in Pacific theater exercises where reduced electromagnetic signatures prove decisive against counter-reconnaissance systems.
- Logistics:Mid-weight carriers between 1 and 4 metric tons move ammunition, medical supplies, and forward-positioned fuel across contested supply lines. Germany and Australia are expanding multi-year contracts for autonomous convoy systems that reduce manned vehicle exposure.
- Surveillance:Stationary-perimeter variants with extended-duration power systems monitor critical infrastructure and forward operating bases.
- Armed:Weaponized platforms face restricted procurement pipelines due to human-in-the-loop requirements under most rules of engagement.
Logistics leads on scale; reconnaissance leads on momentum.
Operation Mode:
Command autonomy levels separate platforms that reduce operator cognitive load from those that merely extend physical reach.
- Autonomous:Platforms with onboard path-planning and obstacle negotiation algorithms operate without continuous datalink connectivity. NATO expeditionary exercises in the Baltic states mandate these capabilities for denied electromagnetic environments.
- Semi-Autonomous:Systems combining supervised waypoint navigation with human authorization for critical decisions balance risk reduction with rules-of-engagement compliance.
- Remote Controlled:Line-of-sight radio links constrain these platforms to perimeter security and training applications.
- Teleoperated:Beyond-line-of-sight satellite links enable explosive ordnance disposal in Eastern Europe where demining commitments outstrip trained operator availability.
Semi-autonomous systems dominate committed procurement volumes; fully autonomous modes are climbing the fastest.
Application:
Mission criticality determines whether platforms receive dedicated operational funding or remain confined to research and development budgets.
- Combat Support:Ammunition resupply, casualty evacuation, and forward arming and refueling point operations attract the deepest recurring integration contracts with legacy command systems.
- Explosive Disposal:Semi-autonomous detection platforms with remote supervisory control address backlogs in Eastern Europe and the Caucasus where human operator availability cannot match clearance commitments.
- Border Security:Persistent perimeter monitoring applications concentrate in Middle Eastern and North African procurement programs.
- Search & Rescue:Disaster response configurations remain experimental, dependent on civil-military coordination frameworks.
Combat support commands the largest committed budgets; explosive disposal shows the steepest expansion trajectory.
End User:
Procurement authority and operational risk tolerance separate segments with multi-year production contracts from demonstration program dependencies.
- Military:Defense ministries in the United States, Germany, and Australia drive interoperability requirements through joint expeditionary exercises, mandating open architecture standards.
- Defense Contractors:Prime integrators purchase subsystems for platform-as-a-service contracts that bundle hardware with guaranteed availability metrics.
- Government Agencies:Border control and internal security organizations procure surveillance variants under separate civil procurement frameworks.
- Research Institutions:Experimental autonomy validation programs depend on defense ministry research funding rather than operational procurement streams.
Military end users anchor procurement scale; defense contractors are gaining share fastest through availability-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices migrate platform development toward jurisdictions with streamlined cybersecurity certification timelines, exploiting gaps between the UK Ministry of Defence's NITES framework and faster validation pathways elsewhere.
United States
The Department of Defense's Replicator initiative accelerates operational validation for autonomous logistics platforms, compressing multi-year demonstration cycles into defined procurement streams. The Pentagon mandates open architecture standards and electromagnetic resilience testing through accredited facilities in Maryland and California. Textron Systems and Oshkosh Defense anchor production clusters in Wisconsin and Michigan, supplying NATO interoperability requirements.
Germany
Rheinmetall AG leverages sensor fusion architectures to capture European NATO manned-unmanned teaming contracts, driven by Bundeswehr demands for contested supply line resupply. The country's national defense procurement office enforces EU AI Act risk classification documentation alongside military certification. Industrial concentration in Bavaria and North Rhine-Westphalia supports rapid payload reconfiguration for logistics-to-combat support transitions.
Australia
Joint expeditionary exercises with the United States and Japan drive interoperability requirements for autonomous ground systems in denied electromagnetic environments. The Department of Defence's autonomous systems roadmap mandates mesh-network resilience standards validated through Queensland-based testing ranges. Milrem Robotics and local integrators position platforms for Arctic-relevant terrain-relative navigation development.
United Kingdom
QinetiQ Group sustains predictive maintenance and over-the-air upgrade contracts for British Army platforms under availability-based performance metrics. The UK Ministry of Defence's NITES cybersecurity framework imposes multi-year validation timelines that delay deployment despite technical readiness. BAE Systems concentrates development in Hampshire and Lancashire, bridging legacy command system integration with containerized perception stacks.
Turkey
ASELSAN develops indigenous autonomous ground platforms for border security and explosive ordnance disposal missions across Eastern European and Caucasus demining commitments. The country's defense procurement agency prioritizes domestic sensor fusion capabilities to reduce dependence on East Asian LiDAR component supply chains. Production clusters in Ankara and Istanbul focus on semi-autonomous supervisory control architectures compliant with NATO expeditionary exercise requirements.
Military Unmanned Ground Vehicle Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense primes commanding armed platform procurement while modular payload integrators capture logistics retrofit opportunities. The vendor base concentrates around three strategic archetypes: sensor fusion architects anchoring European NATO requirements, modular interface specialists enabling rapid mission reconfiguration, and availability-based service contractors bundling hardware with predictive maintenance guarantees. Competitive positioning hardens through multi-year production contracts and through-life support unbundling, with M&A activity targeting middleware vendors bridging national command system interoperability gaps.
Within the sensor fusion architect tier, Rheinmetall AG and BAE Systems exemplify European defense prime positioning, anchoring NATO manned-unmanned teaming requirements through sustained integration contracts with legacy battle management systems. Milrem Robotics occupies a modular specialist position, representing the payload-agnostic archetype that defense ministries in Germany and Australia increasingly specify for rapid logistics-to-combat support transitions. QinetiQ Group sits within the availability-based service tier, bundling British Army platform hardware with predictive analytics and over-the-air capability upgrades rather than capital purchase models.
| Leading Market Players |
|---|
| Rheinmetall AG |
| QinetiQ Group |
| Oshkosh Defense |
| Textron Systems |
| China North Industries Group Corporation |
| Milrem Robotics |
| ASELSAN |
| BAE Systems |
| Roboteam Ltd |
| Others |
Supply & Pricing Matrix
Software-defined mission architectures are compressing hardware refresh cycles while concentrating value capture in firmware and autonomy stack vendors, simultaneously flattening capital expenditure curves and shifting procurement power toward integrators with rapid reconfiguration capabilities. Defense ministries in Germany and Australia now unbundle platform purchase from through-life support, transferring cost risk to contractors who must price predictive maintenance and over-the-air upgrades into availability-based contracts rather than discrete hardware sales.
Pricing Analysis
Direct-to-defense-procurement discounts dominate volume transactions, with integrators offering 15-25 point reductions for multi-year production commitments that guarantee minimum fleet availability. Price differentiation separates NATO-certified platforms with electromagnetic resilience validation from commercial-derivative systems lacking military-grade hardening. Cost compression in semi-autonomous tiers intensifies as modular payload interfaces commoditize base chassis production. Government research institutions exhibit highest price sensitivity due to grant-funded acquisition constraints; prime defense contractors demonstrate lowest sensitivity where operational risk transfer justifies premium positioning.
Supply Chain Analysis
Dual-sourcing requirements for solid-state LiDAR and cooled thermal imagers mandate qualification of East Asian and Israeli component suppliers alongside domestic European alternatives, though concentration in Taiwanese and South Korean foundries persists. Raw material dependencies center on rare-earth magnets for drive motors, gallium nitride substrates for RF components, and high-grade aluminum alloys for armor plating. Single-source vulnerability in precision optical coating capacity creates schedule risk for electro-optical turret integration. Distribution runs through prime integrator assembly facilities in Wisconsin, Bavaria, and Queensland rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for autonomous weapons systems compounds procurement complexity, mandating algorithmic decision documentation that extends validation timelines and deepens compliance investment requirements for armed platform variants.
For Market Incumbents: Lock in multi-year availability contracts with British and Australian defense ministries before middleware standardization commoditizes integration services. Vertical integration into predictive analytics software and spare parts pre-positioning defends margin pools against modular payload specialists. Threat substitution from commercial autonomous vehicle talent migration demands accelerated perception engineering recruitment with security clearance sponsorship. For New Entrants and Emerging Players: Defense contractor tier-two suppliers represent the most penetrable channel partner type for middleware vendors bridging national command system interoperability gaps. White-space targets concentrate in Arctic logistics variants for Norway and Finland, and in demining platform retrofits for Eastern European commitments. Go-to-market positioning should emphasize containerized perception stacks that satisfy German and Australian tender specifications for hardware-software separation. For Investors and Strategic Acquirers: Valuations sit cheapest among availability-based service contractors with embedded British Army or Australian Defence Force relationships, where recurring revenue visibility extends across the analysis window. Acquisition target archetype: middleware vendors with NATO datalink protocol translation capabilities and existing electromagnetic resilience certification. Signal to watch: UK Ministry of Defence NITES framework revision timelines that could compress validation bottlenecks and unlock deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Open Architecture Certification Investment | EU AI Act documentation and NATO interoperability standards gate market access for platform integrators. |
| Platform-as-a-Service Contract Conversion | British Army MORPHEUS and Australian availability-based models transfer operational risk to contractors. |
| Middleware Vendor Acquisition | National command system bridging capabilities command premium positioning in coalition exercise procurement. |
| Arctic Navigation Package Development | Norwegian and Finnish GPS-denied logistics trials create demand for inertial and terrain-relative positioning. |
| Predictive Maintenance Analytics Buildout | Edge computing convergence with vibration sensors enables guaranteed availability pricing models. |
Research Methodology
Direct dialogue with defense procurement officers, autonomy software engineers, electromagnetic resilience test facility directors, and prime integrator program managers grounded qualitative assessment, cross-referenced against NATO expeditionary exercise after-action reports, U.S. Department of Defense Replicator initiative documentation, EU AI Act regulatory filings, and national defense budget appropriations committee records. Bottom-up platform deployment tallies triangulated against top-down defense ministry autonomous systems roadmap commitments.
Bottom-up modeling segmented procurement volumes by vehicle weight class, command autonomy level, mission application, and end-user procurement authority, with value estimates derived from disclosed contract ceilings and comparable multi-year production agreements. Top-down validation assessed aggregate defense robotics budget allocations across the projection horizon, reconciling through CAGR derivation that weighted operational procurement acceleration against demonstration program conversion timelines. Forecast inputs incorporated electromagnetic resilience testing facility capacity constraints and cybersecurity certification queue lengths.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control revisions affecting East Asian sensor components and to NATO datalink protocol standardization decisions. Deviation in UK NITES or EU AI Act implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Indonesia Defense Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Japan Defense Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Destroyers Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Russia Defense Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Iran Defense Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market