
 Global Remote Firing System Market | 2026-2036
Global Remote Firing System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Firing System Market Intelligence
The capital-intensity divergence between integrated blasting suppliers and specialized electronics firms is redrawing competitive boundaries in remote firing systems. Orica Limited leverages its vertically integrated explosives-to-detonator supply chain to bundle firing hardware with consumables contracts across Australian iron ore operations. Dyno Nobel sustains technology leadership through proprietary wireless mesh protocols that reduce misfire rates in deep underground environments. Solar Industries India Limited anchors its position in emerging markets with cost-optimized programmable controllers tailored for quarry operators in South Asia and Africa.
A remote firing system comprises electronic initiation hardware, signal transmission infrastructure, and blast sequencing software designed to detonate explosive charges from a protected distance, typically operating across frequencies from 400 MHz to 2.4 GHz depending on terrain and regulatory band allocation. Its primary commercial purpose centers on eliminating human proximity to blast faces during detonation while enabling precise millisecond-delay timing for optimized rock fragmentation. Wired remote firing retains dominance in underground mining operations where electromagnetic interference risks render wireless protocols unreliable, though wireless remote firing is capturing share in open-pit environments where mobility and rapid redeployment justify premium hardware costs. Hybrid systems that switch between wired backup and wireless primary modes are emerging as the fastest-growing configuration, particularly among defense agencies conducting adaptive training exercises across variable terrain.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives enforces strict storage and transport protocols for electronic detonators, while Australia's Work Health and Safety Regulations mandate dual-redundancy firing circuits for all surface coal operations above specified blast volumes. The EU's Machinery Directive and CE marking requirements for programmable controllers create compliance barriers for non-European suppliers seeking access to European quarry and demolition markets. Stakeholders must monitor evolving frequency allocation decisions by national telecommunications regulators, as spectrum congestion from 5G rollout threatens to constrain wireless firing bandwidth in densely developed mining regions.
Market Dynamics
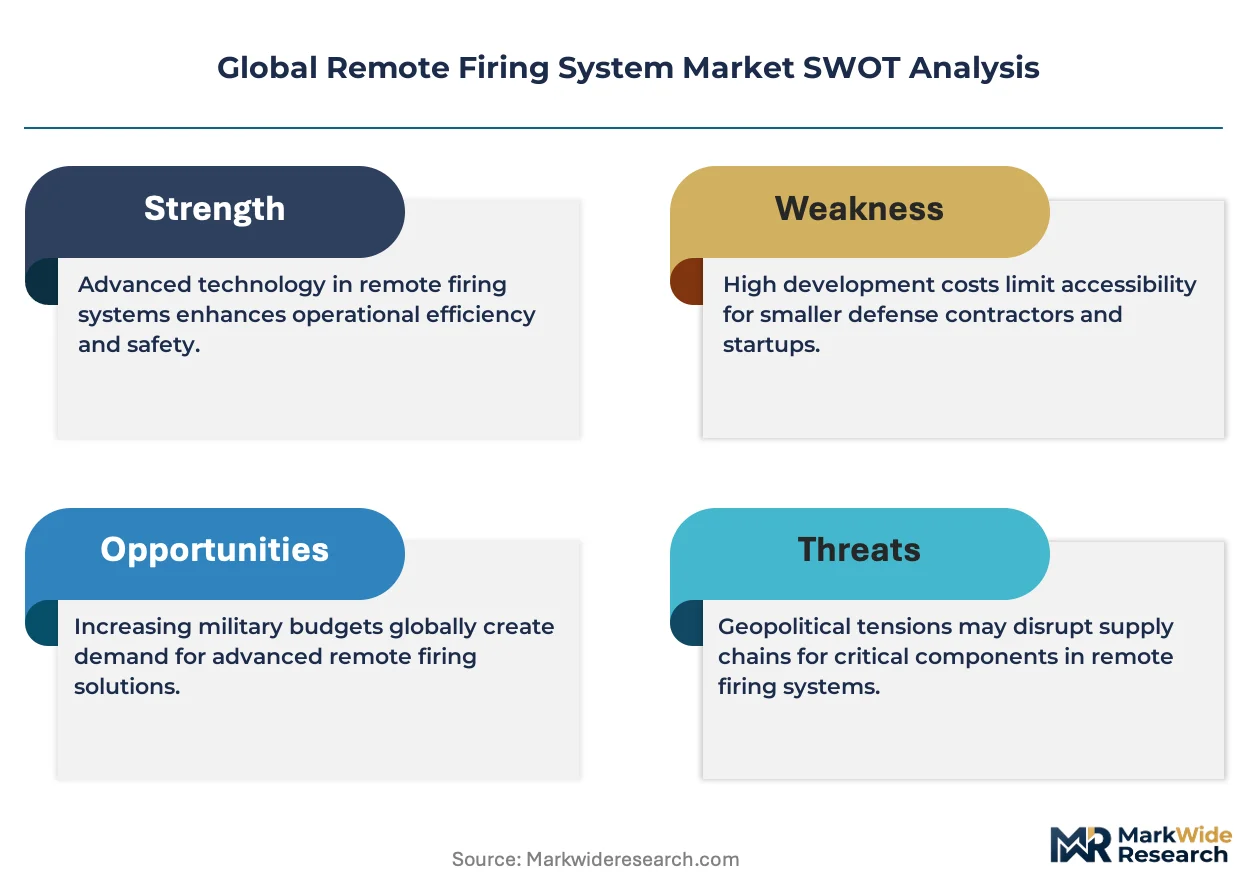
Wireless mesh protocols are fragmenting established supplier relationships as mining operators in Australia and Chile demand interoperable hardware that decouples detonator procurement from proprietary firing controllers.
Growth Catalysts
- EU F-Gas Regulation:REACH framework restrictions on fluorinated greenhouse gases are accelerating replacement of pneumatic firing systems with solid-state electronic controllers in European quarry operations.
- Underground electromagnetic resilience:Mining contractors in South Africa's platinum belt are deploying redundant wired backup circuits where wireless signal propagation fails at depth.
- Copper belt sequencing demand:Chilean surface operations require microsecond-precision delay timing for wall control blasting, pulling advanced programmable detonators into high-volume contracts.
Market Restraints
- Rare earth magnet supply:Neodymium price volatility from Chinese export quotas is compressing margins on servo-actuated firing mechanisms.
- Spectrum congestion:Australia's 5G rollout in the 3.5 GHz band is crowding legacy 2.4 GHz wireless firing channels, forcing hardware redesigns.
- Dual-certification burden:CE marking under the EU Machinery Directive plus ATEX explosion protection compliance adds 14-18 month approval timelines for non-European suppliers.
Strategic Opportunities
- Indian quarry formalization:BIS certification mandates for commercial explosives are creating first-mover advantage for programmable controller suppliers in Rajasthan and Karnataka stone markets.
- Defense adaptive training:Hybrid wired-wireless systems are capturing defense procurement contracts for variable-terrain explosive ordnance disposal simulation.
- ISO 18747-2 convergence:International standardization of electronic detonator performance testing is reducing regional customization costs for multi-continental suppliers.
Industry Challenges
- Blast engineering talent scarcity:Specialized firmware programming skills for detonation sequencing algorithms command 40% wage premiums above general embedded systems roles.
- Legacy analog integration:Underground coal operators in Poland and Ukraine face 18-24 month migration timelines from pyrotechnic cap systems to electronic initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Firing System Market |
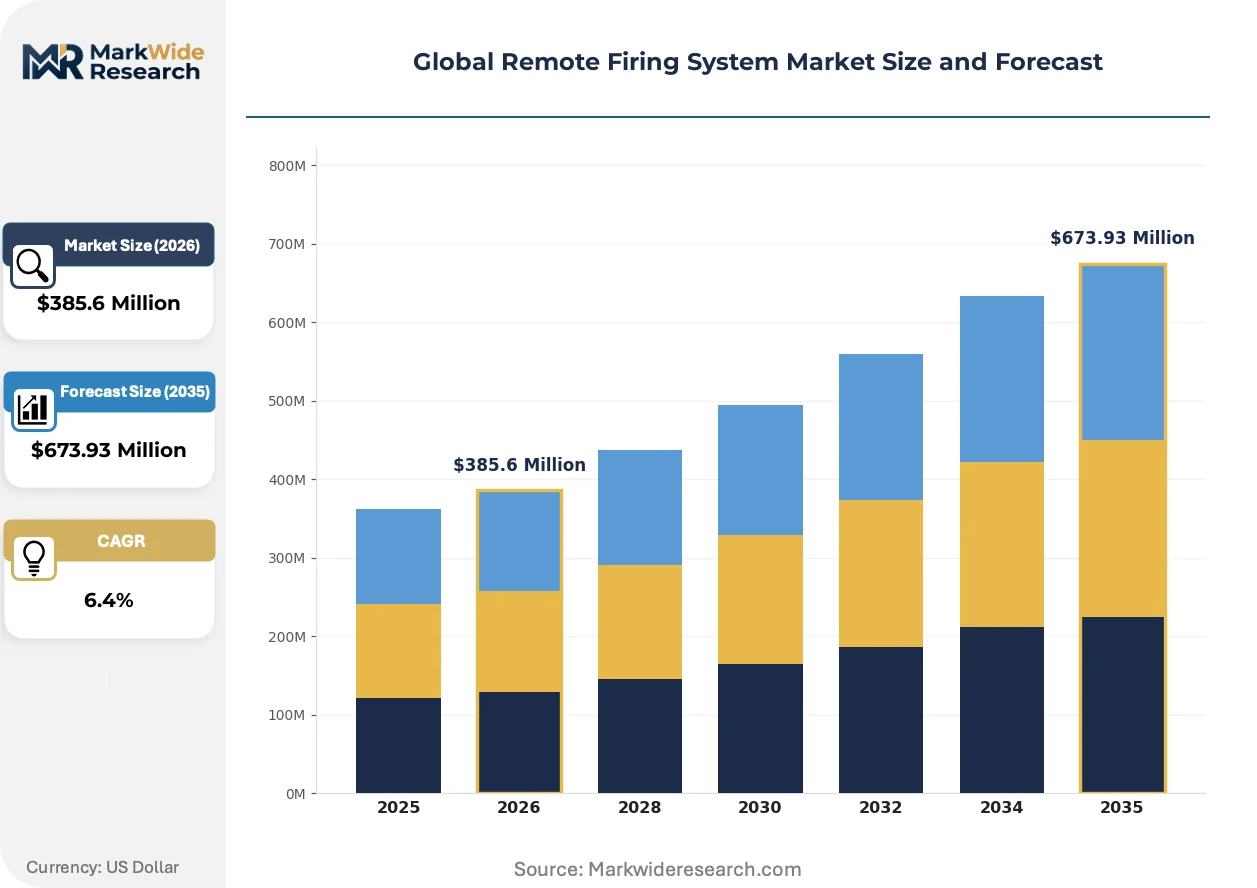
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Remote Firing, Wireless Remote Firing, Hybrid Systems, Programmable Controllers Application: Mining Operations, Demolition Projects, Military Training, Controlled Blasting End User: Mining Contractors, Construction Firms, Defense Agencies, Quarry Operators Deployment Mode: Surface Deployment, Underground Setup, Mobile Platforms, Fixed Installations |
| Companies Covered | Orica Limited, Dyno Nobel, Solar Industries India Limited, Austin Powder Company, Enaex, MAXAM, BAE Systems, Lockheed Martin, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Firing System Market Strategic Shifts & Innovations
Precision timing hardware is converging with telemetry analytics, reshaping how blast contractors optimize fragmentation and validate regulatory compliance in real time.
Mesh-networked detonator architectures are fragmenting procurement patterns across Australian iron ore operations. BHP and Rio Tinto contractors are trialing multi-vendor interoperability protocols that separate detonator supply from controller hardware. This decoupling is compressing long-term consumables contracts and enabling spot purchasing of electronic initiation components.
REACH authorization requirements for lead-based primary explosives are forcing reformulation of traditional detonator compositions across German and French quarry markets. ECHA's sunset date enforcement is accelerating adoption of diazodinitrophenol-based alternatives. Non-compliant inventory is being pushed into Eastern European and North African markets with weaker chemical substance enforcement.
Blast contractors are unbundling after-sales service from hardware procurement, particularly in Chile's copper belt. Codelco subcontractors now contract sequencing optimization separately from detonator supply, using third-party blast analytics platforms. This disintermediation is most visible in Antofagasta Region operations where equipment utilization rates drive purchasing decisions.
Global Remote Firing System Market Segmentation
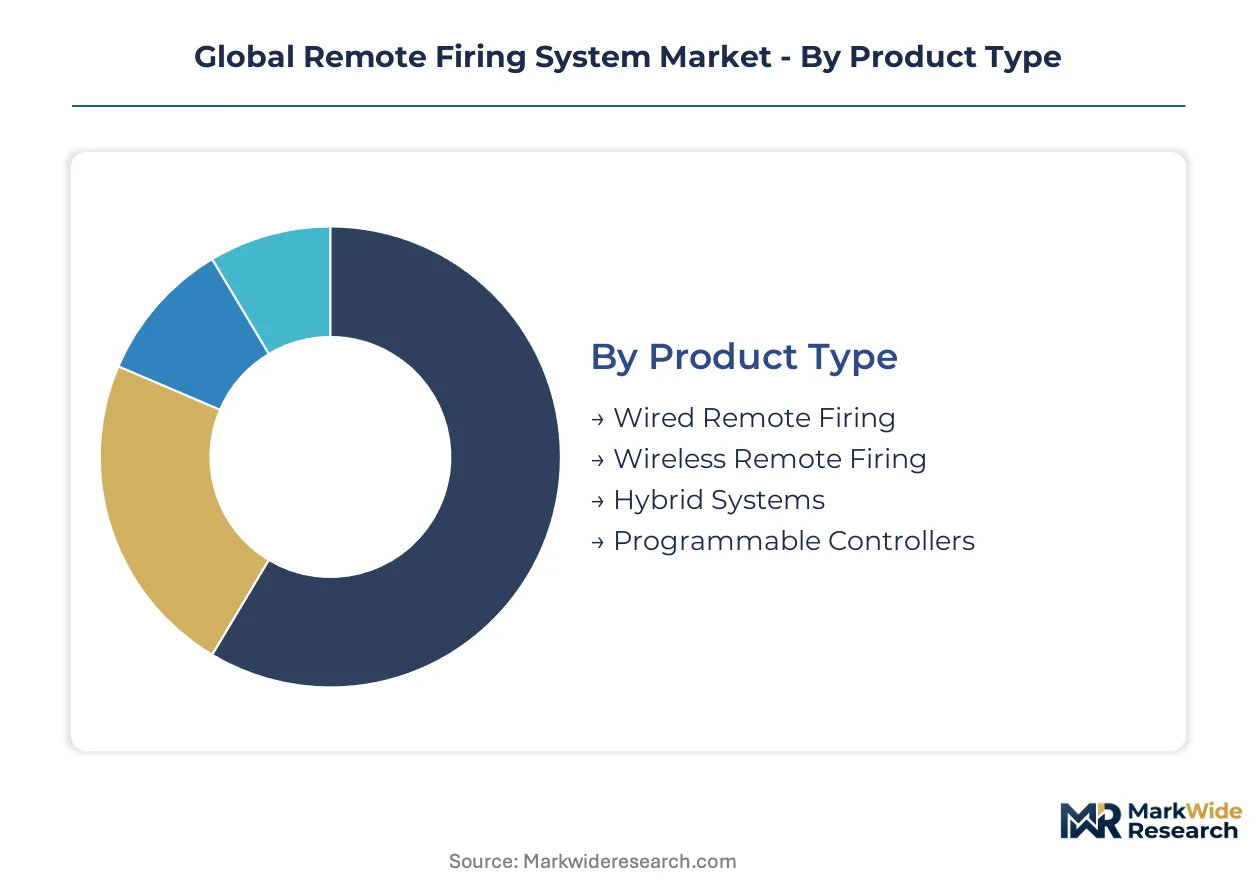
Remote firing system procurement splits sharply between consumables-heavy mining contracts and discrete hardware sales to defense and demolition sectors. Channel economics favor bundled detonator-controller packages in Australian iron ore and Chilean copper operations, while standalone programmable controllers dominate European quarry modernization.
Product Type:
Channel mix varies dramatically by connectivity architecture, with wireless hardware commanding premium distributor margins and wired systems flowing through integrated blasting suppliers.
- Wireless Remote Firing:Mesh-protocol hardware operating across 400 MHz to 2.4 GHz bands eliminates trailing cables in open-pit environments. Australian Pilbara contractors are standardizing on interoperable wireless architectures that decouple detonator procurement from proprietary controllers, compressing long-term consumables contracts.
- Hybrid Systems:Dual-mode units switch between wireless primary and wired backup circuits based on terrain conditions. Defense agencies across variable-terrain training ranges are driving fastest adoption, where adaptive ordnance disposal simulation requires electromagnetic resilience.
- Wired Remote Firing:Copper-cable initiation retains dominance in deep underground operations where signal propagation fails. South Africa's platinum belt deploys redundant wired backup circuits as standard configuration.
- Programmable Controllers:Solid-state sequencing units with microsecond-precision timing replace pneumatic firing systems under EU F-Gas Regulation pressure.
Wired remote firing dominates installed base. Hybrid systems are where expansion concentrates.
Application:
Cost tier stratification separates capital-intensive mining deployments from price-sensitive quarry and demolition segments.
- Mining Operations:Large-scale surface and underground extraction requires millisecond-precision delay timing for optimized rock fragmentation. Chile's copper belt pulls advanced programmable detonators into high-volume contracts as wall control blasting complexity intensifies.
- Demolition Projects:Urban controlled implosion demands fail-safe redundancy and real-time telemetry validation. European metropolitan markets under Machinery Directive compliance drive premium controller specifications.
- Military Training:Adaptive explosive ordnance disposal simulation across variable terrain favors hybrid wired-wireless procurement. Defense contracting channels bypass traditional mining distributor networks.
- Controlled Blasting:Precision rock excavation for infrastructure projects requires calibrated fragmentation analysis. Indian highway expansion programs are formalizing contractor certification standards.
Mining operations command highest hardware attach rates. Military training represents the steepest expansion trajectory.
End User:
Customer type determines service bundling intensity, with mining contractors accepting comprehensive blast optimization packages and quarry operators favoring unbundled component sourcing.
- Mining Contractors:Tier-one operators across Australia's Pilbara corridor bundle firing hardware with long-term explosives supply agreements. BHP and Rio Tinto subcontractors trial multi-vendor interoperability protocols that fragment established supplier relationships.
- Defense Agencies:Military procurement channels prioritize electromagnetic spectrum resilience and rapid terrain redeployment capability. Hybrid system specifications dominate adaptive training exercise contracts.
- Construction Firms:Urban demolition specialists under OSHA and ATF jurisdiction require dual-redundancy firing circuits for metropolitan blast permits.
- Quarry Operators:Rajasthan and Karnataka stone markets under BIS certification mandates are creating first-mover advantage for programmable controller suppliers in formalizing segments.
Mining contractors concentrate revenue volume. Quarry operators are gaining share fastest as formalization spreads.
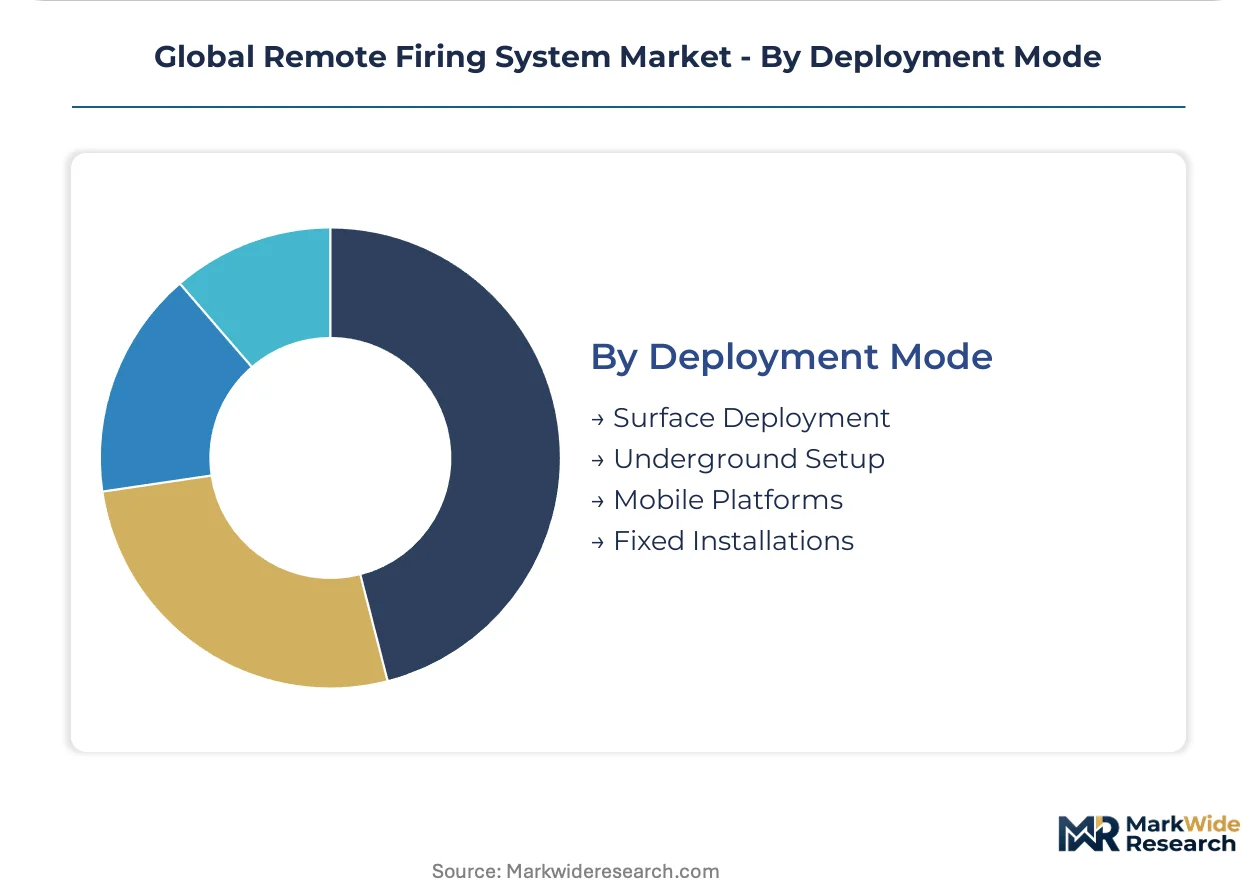
Deployment Mode:
Volume distribution tracks terrain topology, with surface deployment generating unit scale and underground setup commanding specification premiums.
- Surface Deployment:Open-pit operations across Chile's Antofagasta Region and Australia's Pilbara enable wireless mesh network coverage without signal attenuation constraints. Rapid bench-to-bench redeployment justifies premium hardware costs.
- Underground Setup:Deep mining environments in South Africa's platinum belt and Poland's coal seams require shielded cable infrastructure and redundant circuit architectures. Electromagnetic interference risks preclude wireless protocol reliance.
- Mobile Platforms:Vehicle-mounted firing units support adaptive defense training and remote quarry development. Battery-powered programmable controllers enable off-grid operation.
- Fixed Installations:Permanent firing infrastructure serves continuous extraction operations with dedicated power and telemetry backhaul.
Surface deployment anchors unit shipments. Underground setup captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with emerging market quarry operators demanding cost-optimized hardware while Australian and Chilean mining contractors prioritize precision timing capabilities regardless of premium positioning.
Australia
Pilbara iron ore contractors drive wireless mesh adoption for bench-to-bench redeployment flexibility. Work Health and Safety Regulations mandate dual-redundancy firing circuits for surface coal operations above specified blast volumes. Perth-based blasting service providers are fragmenting long-term consumables contracts through multi-vendor interoperability trials.
Chile
Antofagasta Region copper operations pull advanced programmable detonators into high-volume contracts for wall control blasting complexity. National mining safety codes align with international electronic initiation standards. Santiago-headquartered contractors now unbundle sequencing optimization from detonator supply using third-party analytics platforms.
United States
Defense agencies prioritize hybrid wired-wireless systems for adaptive ordnance disposal simulation across variable terrain. The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces strict storage and transport protocols for electronic detonators. Southwestern training ranges are capturing fastest hybrid system adoption for electromagnetic resilience requirements.
Germany
REACH authorization deadlines for lead-based primary explosives force diazodinitrophenol-based detonator reformulation across quarry markets. EU Machinery Directive and CE marking requirements create compliance barriers for non-European programmable controller suppliers. Ruhr Valley demolition specialists drive premium controller specifications for urban controlled implosion projects.
India
Rajasthan and Karnataka stone markets under BIS certification mandates create first-mover advantage for programmable controller suppliers in formalizing segments. Central Electricity Authority regulations govern explosive storage near power infrastructure. Jaipur-based quarry operators are migrating from pyrotechnic cap systems to electronic initiation under modernization programs.
Global Remote Firing System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with explosives-to-detonator supply chain control separating the top tier from component-focused competitors. The middle layer contains wireless protocol specialists and programmable controller manufacturers competing on timing precision and interoperability. Two strategic archetypes dominate: vertically integrated blasting suppliers bundling hardware with consumables contracts, and electronics-focused firms selling standalone controllers into price-sensitive quarry markets. Competitive moves center on multi-vendor interoperability partnerships and geographic expansion into formalizing emerging markets.
Within the integrated explosives tier, Orica Limited and Dyno Nobel exemplify contrasting geographic anchors—Australian and North American respectively—while occupying positions as full-service blasting solution providers. Solar Industries India Limited represents the emerging market specialist archetype, with its corporate structure suggesting cost-optimized positioning for South Asian and African quarry formalization. These three entities collectively illustrate how supply chain depth, wireless protocol ownership, and regional cost engineering define competitive differentiation in remote firing systems.
| Leading Market Players |
|---|
| Orica Limited |
| Dyno Nobel |
| Solar Industries India Limited |
| Austin Powder Company |
| Enaex |
| MAXAM |
| BAE Systems |
| Lockheed Martin |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
CE marking under the EU Machinery Directive gates both programmable controller qualification and price differentiation simultaneously, forcing non-European suppliers into 14-18 month approval timelines that compress their pricing power against certified incumbents while enabling premium positioning for compliant architectures.
Pricing Analysis
After-sales service contracts and sequencing optimization subscriptions now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade hybrid systems from quarry-focused programmable controllers and basic wired firing units. Cost compression in the economy tier is intensifying because Indian and African quarry operators demand stripped-down controllers under BIS certification mandates. Mining contractors across Australia's Pilbara corridor show least price sensitivity, prioritizing microsecond-precision timing and multi-vendor interoperability over unit cost.
Supply Chain Analysis
China and Australia anchor rare earth magnet supply for servo-actuated firing mechanisms, while Germany and Japan feed precision electronic components into controller manufacturing. Neodymium price volatility from Chinese export quotas rests on downstream margin stability, with neodymium, copper cable, and solid-state semiconductors forming critical input dependencies. Single-source vulnerability in rare earth processing creates exposure for manufacturers dependent on Chinese magnet supply. Distribution runs through integrated blasting suppliers in mining corridors and specialized electronics distributors in quarry markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized firmware programming skills for detonation sequencing algorithms command 40% wage premiums above general embedded systems roles, constraining expansion for firms lacking captive blast engineering talent.
For Market Incumbents: Compound wireless protocol ownership into multi-vendor interoperability partnerships that fragment competitor consumables contracts. Lock in long-term explosives supply agreements with Australian iron ore and Chilean copper contractors before spot purchasing of electronic initiation components spreads. Backward integration into rare earth magnet sourcing mitigates Chinese export quota exposure. For New Entrants and Emerging Players: Anchor in Indian quarry formalization under BIS certification mandates, where Rajasthan and Karnataka stone markets lack established programmable controller suppliers. Target defense adaptive training procurement channels that bypass traditional mining distributor networks and prioritize hybrid wired-wireless specifications. Lead with cost-optimized architectures priced below integrated blasting supplier bundles. For Investors and Strategic Acquirers: REACH authorization deadlines for lead-based primary explosives reshape the acquisition landscape by accelerating diazodinitrophenol-based detonator reformulation capabilities. Five-to-ten year viability favors targets with solid-state electronic controller expertise and European regulatory compliance infrastructure. Monitor ECHA sunset date enforcement as inflection indicator for compliant inventory valuation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor Interoperability Partnership | BHP and Rio Tinto contractors trial protocols that decouple detonator procurement from proprietary controllers. |
| Backward Integration into Rare Earth Sourcing | Neodymium supply from Chinese processors is being secured through offtake agreements by servo-actuated mechanism manufacturers. |
| Defense Hybrid System Certification | Southwestern US training ranges drive fastest adoption for electromagnetic resilience in adaptive ordnance disposal simulation. |
| Indian BIS Certification First-Mover Program | Jaipur-based quarry operators migrating from pyrotechnic caps create captive demand for compliant programmable controllers. |
| Blast Analytics Platform Integration | Codelco subcontractors in Antofagasta Region unbundle sequencing optimization from detonator supply using third-party telemetry validation. |
Research Approach
Two parallel data streams informed the analysis: primary engagement with blast engineering directors, mining contractor procurement leads, defense agency ordnance specialists, and quarry operator safety managers; and secondary validation against customs trade records, SEC filings from integrated explosives suppliers, ECHA authorization databases, and national mining safety regulator disclosures. Bottom-up unit economics triangulated against top-down market sizing across connectivity architecture, application vertical, and end-user category.
Across the analysis window, volume and value outputs reflect modeling across wireless, hybrid, wired, and programmable controller product types; mining, demolition, military training, and controlled blasting applications; and surface deployment, underground setup, mobile platform, and fixed installation modes. CAGRs derive from segment-level growth rate blending with input cost trajectory assumptions. Frequency allocation decisions by national telecommunications regulators and rare earth export quota patterns inform wireless firing bandwidth and hardware margin projections.
Decision-makers should treat outputs as directional under assumptions of stable EU F-Gas Regulation enforcement and continued Australian Work Health and Safety Regulations dual-redundancy mandates; material deviation in REACH authorization timelines or Chinese rare earth export policy would warrant model refresh. Recalibration cycles align with material shifts in spectrum congestion from 5G rollout and blast engineering talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Autonomous Drone Market