
 Low-Noise Drone Propulsion Systems Market | 2026-2036
Low-Noise Drone Propulsion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Noise Drone Propulsion Systems Market Insights
Buyer concentration is shifting as urban delivery operators consolidate fleet procurement while environmental agencies and infrastructure firms fragment into specialized niche contracts. DJI leverages its integrated platform architecture to control channel access across consumer and commercial tiers. Rolls-Royce anchors high-thrust electric propulsion development for heavy-lift cargo drones. T-Motor competes aggressively on brushless motor specialization for cinematography and inspection segments.
Low-noise drone propulsion systems integrate electric motors, precision-machined propellers, and electronic speed controllers with acoustic dampening materials to achieve sound signatures below 65 dB at operational altitude, serving applications where auditory stealth preserves mission integrity or community acceptance. Brushless DC motors dominate unit shipments due to mature manufacturing economics, yet acoustic metamaterials claim expanding margin pools as military and urban delivery operators mandate verifiable noise reduction. Active noise control technology leads R&D intensity, though aerodynamic design refinements sustain broader adoption across price-sensitive agricultural monitoring deployments.
The FAA's Part 107 framework and emerging municipal noise ordinances in Germany and France shape certification pathways and flight corridor access. EASA's drone-specific type certification requirements under the EU AI Act and U-space regulations compound compliance complexity for cross-border operators. Stakeholders must monitor regulatory divergence between FAA performance-based standards and EASA's prescriptive acoustic thresholds when configuring product portfolios for multi-jurisdiction deployment.
Market Dynamics
Urban air mobility corridors in Germany and France now mandate sub-60 dB acoustic thresholds, forcing propulsion manufacturers to reconfigure motor-ESC-propeller integration around noise certification rather than power-to-weight optimization alone.
Growth Catalysts
- FAA Part 107 Night Waiver:Extended operational hours for commercial drone fleets in the United States expand addressable flight windows for delivery and inspection operators, directly stimulating demand for certified low-noise systems that satisfy community noise ordinances.
- Acoustic Metamaterials:Engineered lattice structures integrated into motor housings and propeller roots achieve broadband noise reduction without thrust penalty, enabling compliance in noise-sensitive urban cores where conventional dampening fails.
- Last-Mile Delivery Consolidation:Urban logistics operators in Frankfurt, Munich, and Paris are standardizing fleet procurement around acoustic-compliant propulsion units to secure municipal operating permits and residential route access.
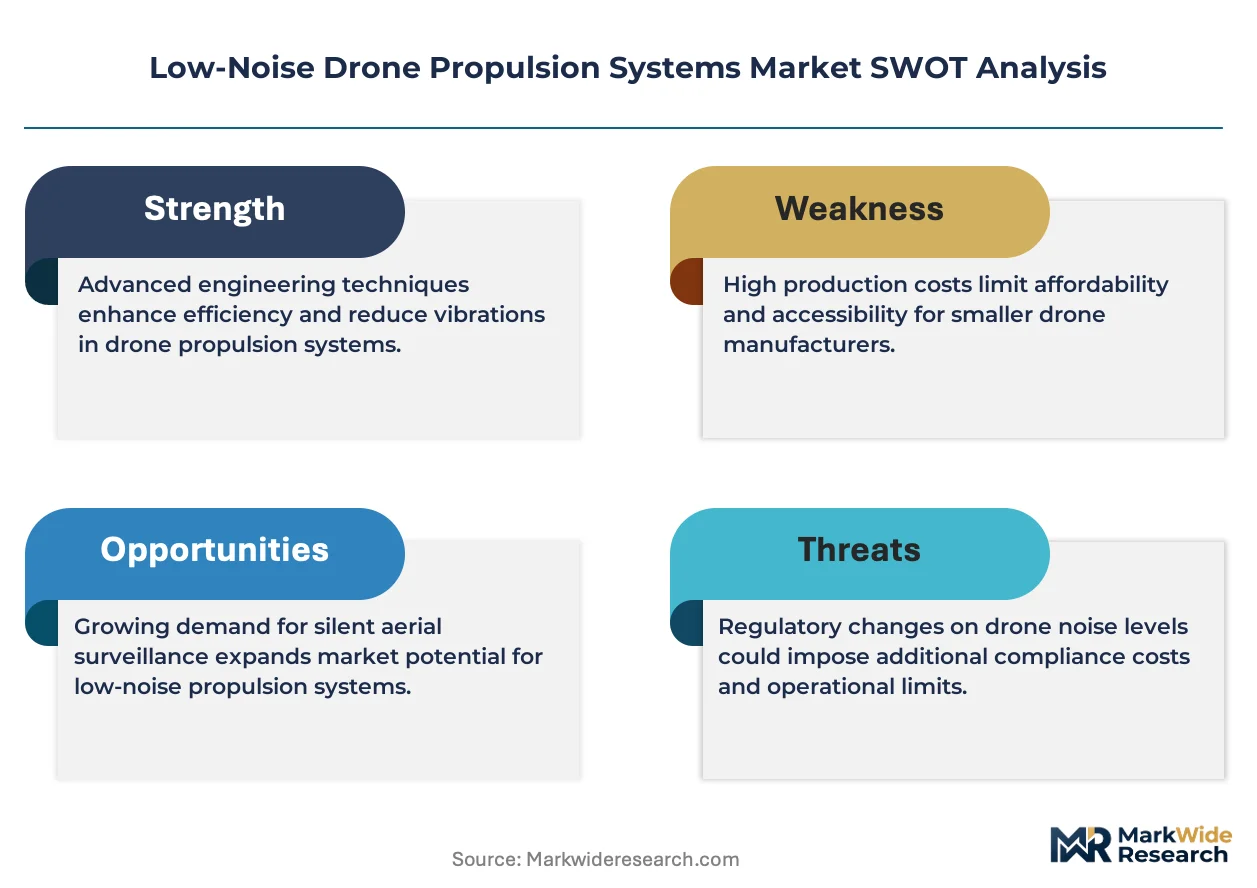
Market Restraints
- Neodymium Price Volatility:Rare-earth magnet supply concentrated in Chinese processing facilities exposes brushless motor manufacturers to input cost swings that compress margins on mid-tier propulsion units.
- EASA Prescriptive Thresholds:The EU AI Act's drone-specific type certification requirements impose acoustic testing protocols that diverge from FAA performance-based standards, fragmenting product development roadmaps and raising compliance overhead for cross-border operators.
- Acoustic Trade-Off Physics:Tip speed reductions necessary for noise suppression directly constrain thrust density, limiting payload capacity for heavy-lift cargo applications below commercially viable thresholds.
Strategic Opportunities
- Active Noise Control Convergence:Real-time adaptive cancellation algorithms paired with sensor-integrated ESCs enable dynamic frequency suppression, opening military surveillance and wildlife monitoring segments where absolute silence preserves mission integrity.
- U-Space Corridor Expansion:European unmanned traffic management infrastructure deployment creates regulated low-altitude highways where acoustic compliance becomes a de facto entry ticket for commercial operators.
- Agricultural Monitoring Underpenetration:Precision farming deployments in France and Spain currently prioritize cost over acoustic performance, presenting a volume channel for simplified low-noise systems that meet basic regulatory floors without premium feature sets.
Industry Challenges
- Aeroacoustic Engineering Talent Scarcity:The intersection of computational fluid dynamics, structural vibration analysis, and real-time control systems demands specialists whose training pipelines remain underdeveloped relative to market need.
- Certification Timeline Compression:EASA's evolving type certification requirements under concurrent regulatory frameworks force manufacturers to maintain parallel validation tracks, stretching R&D budgets and delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Noise Drone Propulsion Systems Market |
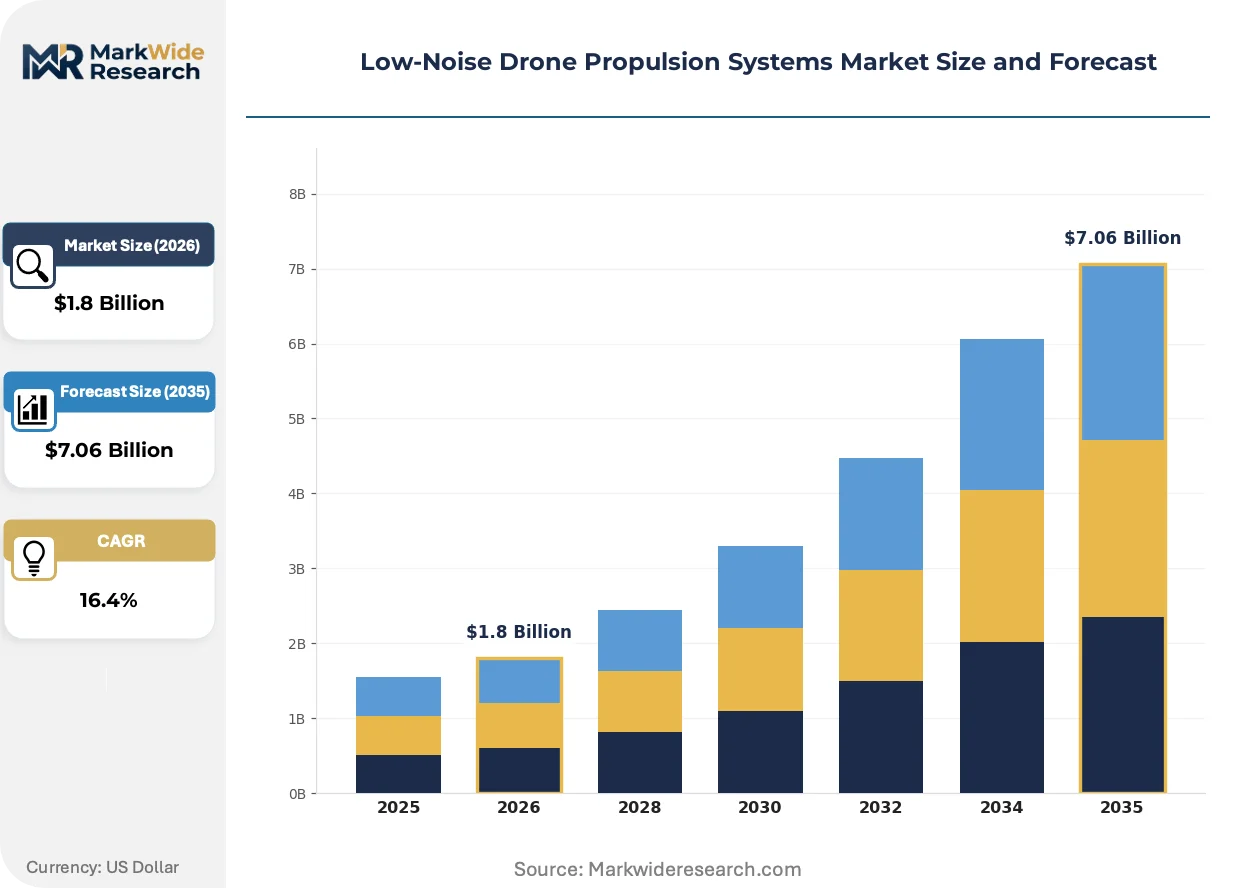
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motors, Brushless DC Motors, Propellers, Gearboxes, Electronic Speed Controllers Technology: Acoustic Metamaterials, Vibration Dampening, Aerodynamic Design, Active Noise Control, Sound Absorption Panels Application: Surveillance, Agricultural Monitoring, Infrastructure Inspection, Urban Delivery, Wildlife Observation End User: Military Units, Agricultural Enterprises, Civil Aviation Operators, Infrastructure Firms, Environmental Agencies |
| Companies Covered | DJI, Honeywell International, Rolls-Royce, Safran, RTX, General Electric, Ballard Power Systems, Hirth Engines, T-Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Noise Drone Propulsion Systems Market Trends and Innovations
Propulsion architecture is fragmenting into interchangeable subsystems as acoustic compliance becomes a modular design constraint rather than an integrated optimization target, enabling faster reconfiguration across mission profiles.
Active noise control hardware is modularizing around swappable ESC-motor-propeller stacks that embed microphonic feedback loops and adaptive filtering chipsets. Military operators in Germany and France are piloting these configurations for rapid field reconfiguration between high-thrust cargo and low-signature surveillance modes. The technology is modularizing supplier relationships, allowing end-users to mix acoustic-grade subsystems from specialized vendors without platform-level integration penalties.
EASA's U-space regulations and the EU AI Act's drone certification requirements are converging on verifiable acoustic performance metrics that override manufacturer self-declaration. Operators seeking cross-border corridor access in Germany, France, and the Netherlands must now submit third-party acoustic test data to national aviation authorities. Heavy-lift cargo segments face the steepest compliance ramps, as their higher power draws generate noise signatures that exceed municipal thresholds without active suppression.
Buyer concentration among urban delivery fleet operators is consolidating procurement decisions into centralized technical specifications that bundle acoustic certification with maintenance and data analytics. Small cinematography and inspection operators in Spain and Italy are responding through cooperative purchasing alliances that aggregate volume to access tier-one supplier pricing. This behavioral shift is most visible in German urban air mobility corridors, where municipal permit requirements force acoustic compliance upstream into fleet acquisition criteria rather than aftermarket retrofit.
Low-Noise Drone Propulsion Systems Market Segmentation
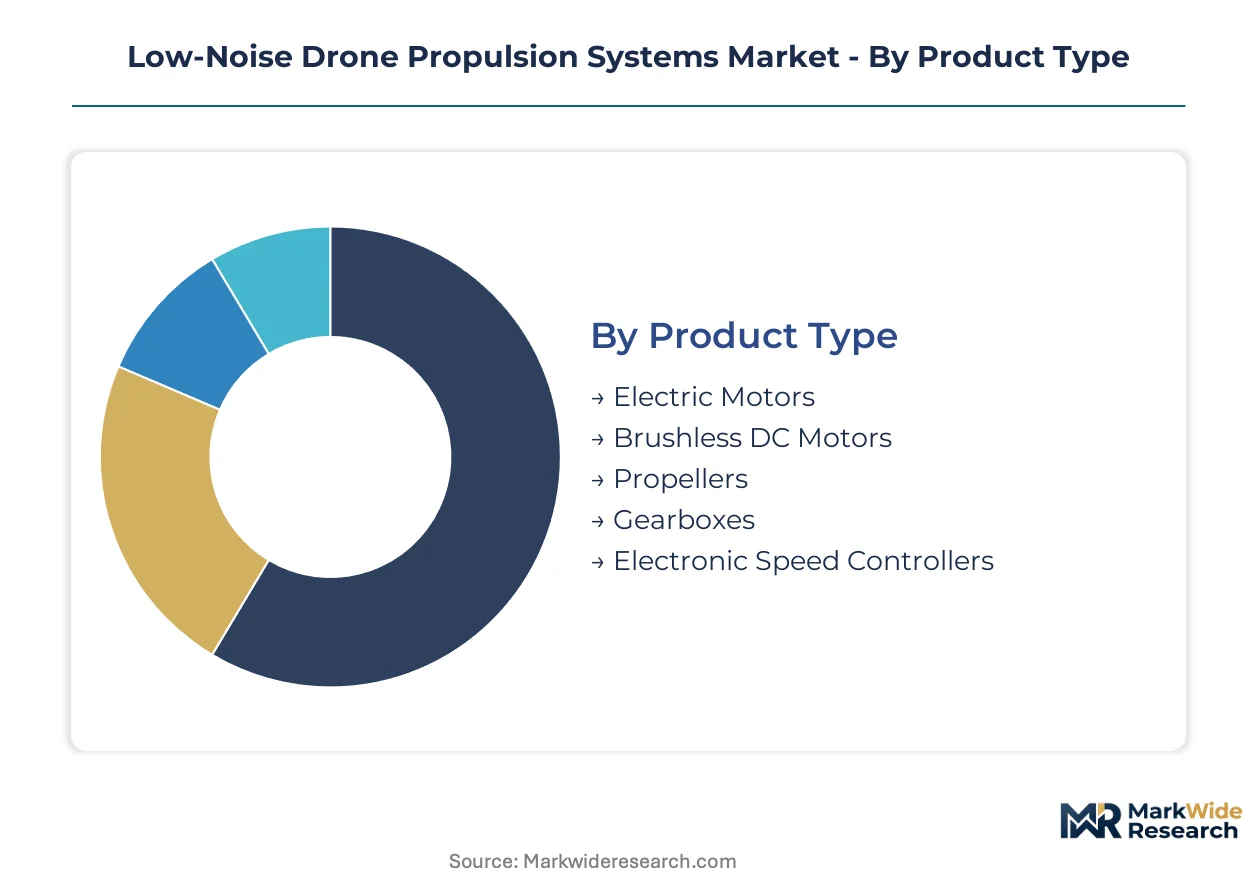
Acoustic compliance mandates fragment procurement patterns across the low-noise drone propulsion market. Buyers now configure subsystems differently for standalone retrofit versus integrated OEM deployment.
Product Type:
Standalone motor and propeller replacements dominate aftermarket channels, while integrated powertrain modules ship primarily through airframe OEM partnerships.
- Electric Motors:Core power generation units rated for continuous operation at reduced tip speeds to suppress broadband noise signatures. German urban air mobility corridors specify these for municipal delivery permits in Frankfurt and Munich.
- Brushless DC Motors:Permanent-magnet synchronous designs with slotless stators eliminate cogging torque and associated acoustic harmonics. Volume concentrates in agricultural monitoring fleets across France and Spain where cost sensitivity limits adoption of active noise alternatives.
- Propellers:Precision-machined composite blades with serrated trailing edges disrupt laminar vortex shedding.
- Gearboxes:Planetary reduction stages enable motor operation at optimal efficiency RPM independent of propeller loading.
- Electronic Speed Controllers:Field-oriented control algorithms with sinusoidal commutation minimize electrical switching noise.
Volume placements concentrate in Brushless DC Motors; the faster expansion belongs to integrated Electronic Speed Controllers with embedded acoustic feedback loops.
Technology:
Cost stratification separates passive material solutions from active electronic suppression systems, with hybrid architectures emerging for premium military and urban delivery contracts.
- Acoustic Metamaterials:Engineered lattice structures integrated into motor housings achieve targeted frequency absorption without mass penalty. EASA's prescriptive acoustic thresholds under U-space regulations drive certification demand in France and the Netherlands.
- Vibration Dampening:Elastomeric isolation mounts and constrained-layer damping sheets attenuate structure-borne noise transmission. Agricultural operators in Spain select these for basic regulatory compliance at minimum cost.
- Aerodynamic Design:Tip shape optimization and blade pitch distribution reduce turbulent wake generation.
- Active Noise Control:Real-time adaptive algorithms paired with microphonic sensors enable dynamic frequency cancellation. Military surveillance units in Germany pilot these for mission-critical acoustic stealth.
- Sound Absorption Panels:Porous composite liners applied to internal cavities dissipate resonant standing waves.
Cost-tier positioning favors Vibration Dampening for volume; steepest expansion trajectory resides in Active Noise Control for defense and premium urban delivery segments.
Application:
Mission duration and altitude requirements determine whether passive or active acoustic architectures achieve operational noise budgets.
- Surveillance:Extended loiter operations at low altitude demand sub-55 dB signatures to avoid ground detection. Military procurement in France specifies active noise control for border monitoring missions.
- Agricultural Monitoring:Broad-area crop surveys prioritize flight endurance over acoustic performance. French and Spanish farming cooperatives drive unit volume through standardized fleet specifications.
- Infrastructure Inspection:Close-proximity bridge and power line surveys require moderate noise suppression for worker safety compliance.
- Urban Delivery:Repeated low-altitude overflight of residential zones mandates sub-60 dB certification. Municipal permit requirements in German cities force acoustic compliance into fleet acquisition criteria.
- Wildlife Observation:Minimal disturbance protocols for sensitive species research demand absolute acoustic stealth.
Procurement volume clusters in Agricultural Monitoring; Wildlife Observation gains share fastest as conservation budgets expand acoustic performance requirements.
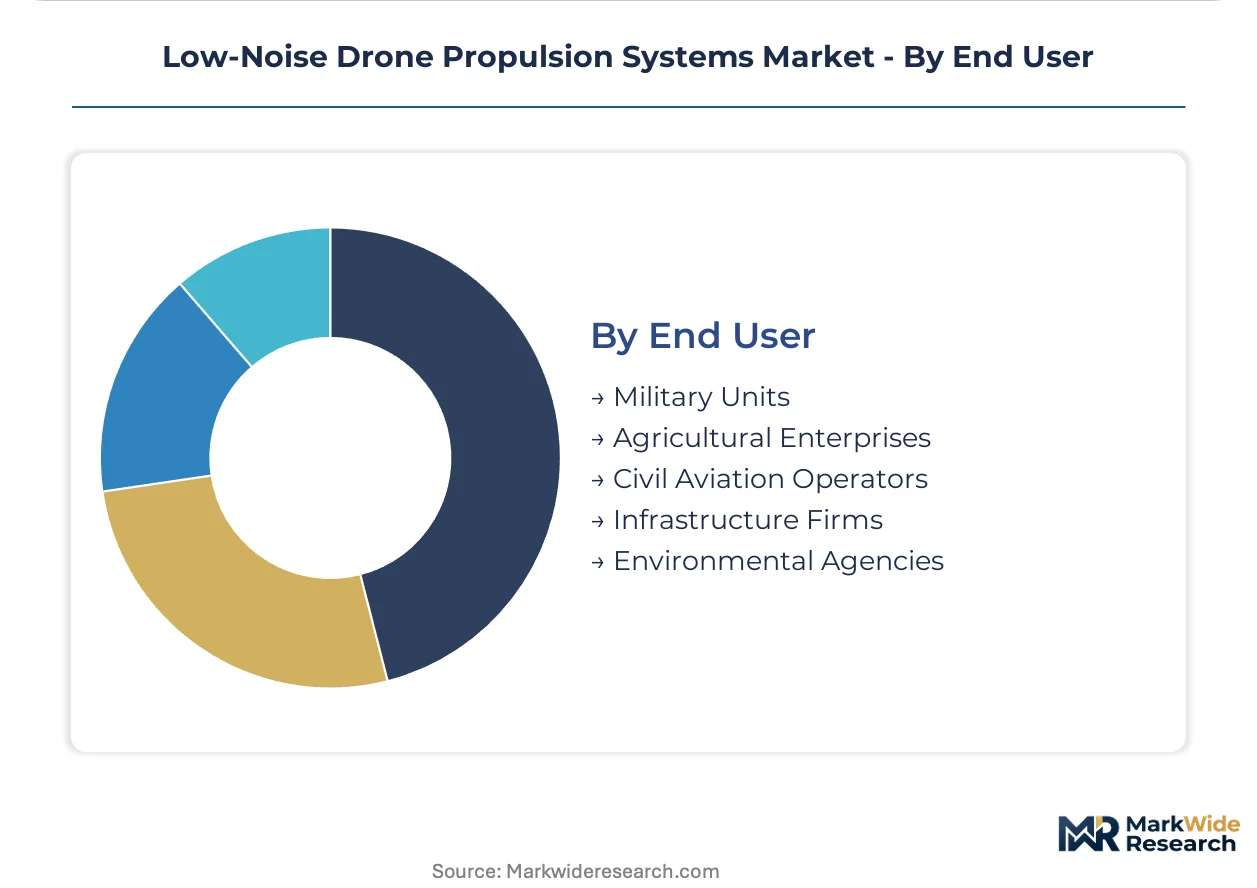
End User:
Buyer sophistication spans from centralized military technical specifications to fragmented agricultural cooperative purchasing.
- Military Units:Classified mission profiles drive investment in adaptive active noise suppression with rapid field reconfiguration capability. German and French defense procurement offices mandate verifiable acoustic test data under EASA convergence frameworks.
- Agricultural Enterprises:Cost-driven fleet standardization limits specification complexity to passive dampening solutions. Cooperative purchasing alliances in Spain aggregate volume to access tier-one supplier pricing.
- Civil Aviation Operators:Commercial drone service providers balance certification overhead against route access permissions.
- Infrastructure Firms:Utility and transportation operators integrate acoustic compliance into safety management systems.
- Environmental Agencies:Regulatory enforcement and research missions require demonstrable noise reduction for public legitimacy.
Contract concentration sits with Agricultural Enterprises; Environmental Agencies expand procurement most quickly as noise ordinance enforcement tightens across European municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban delivery operators in Germany, France, and the United States concentrate procurement volumes, while municipal noise ordinances in European cities and FAA certification pathways in North America reshape competitive access.
United States
FAA Part 107 night operation waivers extend commercial flight windows for delivery and inspection fleets, directly stimulating certified low-noise system procurement. The FAA's performance-based standards emphasize operational outcomes over prescriptive acoustic thresholds. Dallas-Fort Worth and Phoenix anchor emerging urban air mobility corridors where operators negotiate municipal permits.
Germany
KBA enforcement of municipal noise ordinances in Frankfurt and Munich mandates sub-60 dB propulsion certification for urban delivery permits. EASA's U-space regulations compound compliance requirements for cross-border corridor access. Bavaria's urban air mobility infrastructure prioritizes acoustic compliance in fleet procurement specifications.
France
ANSM coordination with EASA implements drone-specific type certification under the EU AI Act, requiring third-party acoustic test data for commercial operators. Military surveillance units pilot active noise control configurations for border monitoring missions. The Paris metropolitan region enforces residential overflight restrictions that filter propulsion supplier selection.
China
MIIT standards for civilian unmanned aircraft establish noise emission baselines that manufacturers must self-certify before commercial deployment. Dual carbon goals accelerate electric propulsion substitution for combustion alternatives. Shenzhen and Guangzhou manufacturing clusters integrate acoustic dampening into export-oriented production lines.
United Kingdom
Civil Aviation Authority integration with EASA post-Brexit creates parallel certification tracks that fragment product validation timelines. London's congestion pricing zones expand to include low-emission airspace corridors with acoustic performance gates. The Southeast England logistics hub concentrates cooperative purchasing alliances among small commercial operators.
Low-Noise Drone Propulsion Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue active noise control specialization and modular subsystem architectures. Market structure consolidates around integrated platform providers with OEM channel access, while mid-tier specialists fragment across aftermarket retrofit segments. Three archetypes dominate: aerospace conglomerates with defense-civilian dual-use capabilities, precision motor fabricators with brushless specialization, and acoustic engineering boutiques with metamaterial IP. Competitive moves center on strategic partnerships with urban air mobility infrastructure developers and technology licensing agreements for noise suppression algorithms.
Among aerospace-heritage conglomerates, Rolls-Royce and Safran occupy positions exemplifying high-thrust electric propulsion development for heavy-lift applications. T-Motor represents the precision motor fabrication archetype, anchoring brushless specialization for cinematography and inspection market segments. These three entities illustrate the tier divergence between integrated system providers and component specialists.
| Leading Market Players |
|---|
| DJI |
| Honeywell International |
| Rolls-Royce |
| Safran |
| RTX |
| General Electric |
| Ballard Power Systems |
| Hirth Engines |
| T-Motor |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement consolidation among German and French urban delivery operators now mandates sub-60 dB acoustic certification as a non-negotiable specification, forcing suppliers to absorb metamaterial and active noise control costs into base unit pricing while competing for long-term maintenance contracts.
Pricing Analysis
Volume placements concentrate in mid-tier brushless DC motors where margin compression runs deepest; premium-tier active noise control systems retain pricing power through military and municipal delivery contracts. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified integrated modules from basic vibration-dampened replacements and uncertified agricultural units. Pricing pressure stems from neodymium magnet cost volatility concentrated in Chinese processing facilities. Agricultural cooperatives in Spain exhibit highest price sensitivity; defense procurement offices in Germany and France demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in precision aeroacoustic engineering concentrate manufacturing capabilities in Germany, China, and the United States. Brushless motor production draws from rare-earth magnet supply chains anchored in Chinese processing, precision-machined propeller composites from Japanese carbon fiber suppliers, and adaptive filtering chipsets from Taiwanese semiconductor foundries. Single-source vulnerability in neodymium oxide refining creates structural exposure to export restriction scenarios. Distribution runs through OEM airframe partnerships for integrated powertrain modules and specialized aftermarket distributors for standalone retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA's U-space regulations and the EU AI Act's drone-specific type certification requirements erect a cost-of-compliance barrier that favors incumbents with established validation track records and parallel certification capacity across multiple jurisdictions.
For Market Incumbents: Anticipate margin erosion in standard-tier brushless motor segments as Chinese manufacturers expand export capacity. Defensive consolidation should prioritize backward integration into rare-earth magnet sourcing and captive acoustic testing laboratory capacity. Certification investment in EASA-FAA dual-track validation preserves corridor access for cross-border operators. For New Entrants and Emerging Players: Active noise control algorithm specialization offers a technology-first wedge against integrated platform incumbents. White-space targets include agricultural monitoring fleets in France and Spain seeking basic regulatory compliance at minimum cost, and wildlife observation segments where conservation budget expansion outpaces supplier coverage. Go-to-market positioning through cooperative purchasing alliances aggregates fragmented demand. For Investors and Strategic Acquirers: The window for entry favors acoustic engineering boutiques with metamaterial IP and modular subsystem architectures. Long-term viability hinges on regulatory divergence between performance-based and prescriptive acoustic standards persisting through the decade. Watch EASA's evolving type certification timeline compression as the inflection signal for R&D budget stress among mid-tier specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Testing Laboratory Acquisition | Captive certification capacity accelerates EASA validation timelines for German manufacturers. |
| Metamaterial IP Licensing Agreement | Engineered lattice structures from defense suppliers transfer to commercial motor housings. |
| Urban Air Mobility Infrastructure Partnership | Municipal corridor access in Frankfurt and Munich locks in fleet procurement specifications. |
| Rare-Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors hedge neodymium price volatility exposure. |
| Active Noise Control Platform Integration | Real-time adaptive algorithms embedded in ESC firmware differentiate surveillance offerings. |
Research Methodology
Regulatory filings from EASA and the FAA, trade customs data for brushless motor and rare-earth magnet flows, and SEC disclosures from listed aerospace conglomerates formed the secondary backbone. Primary interviews with propulsion system engineering directors, urban air mobility fleet procurement managers, and acoustic testing laboratory certification leads combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis of electric motor shipments, propeller unit volumes, and electronic speed controller placements established baseline growth patterns across the projection horizon. Segmentation modeling captured product type, technology tier, application mission profile, and end-user sophistication dimensions. CAGRs derived from regression analysis against regulatory milestone timing and fleet procurement cycle data, with cross-validation against OEM airframe delivery schedules and municipal permit issuance rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EASA-FAA regulatory convergence or sustained neodymium supply disruption. Forecasts reflect assumptions documented in the analysis framework. A small set of named triggers—EASA type certification timeline compression, Chinese rare-earth export policy shifts, and German municipal noise ordinance enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Autonomous Technology Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Drone-In-A-Box Solutions Market