
 Lidar Drone Market | 2026-2036
Lidar Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Lidar Drone Market Intelligence
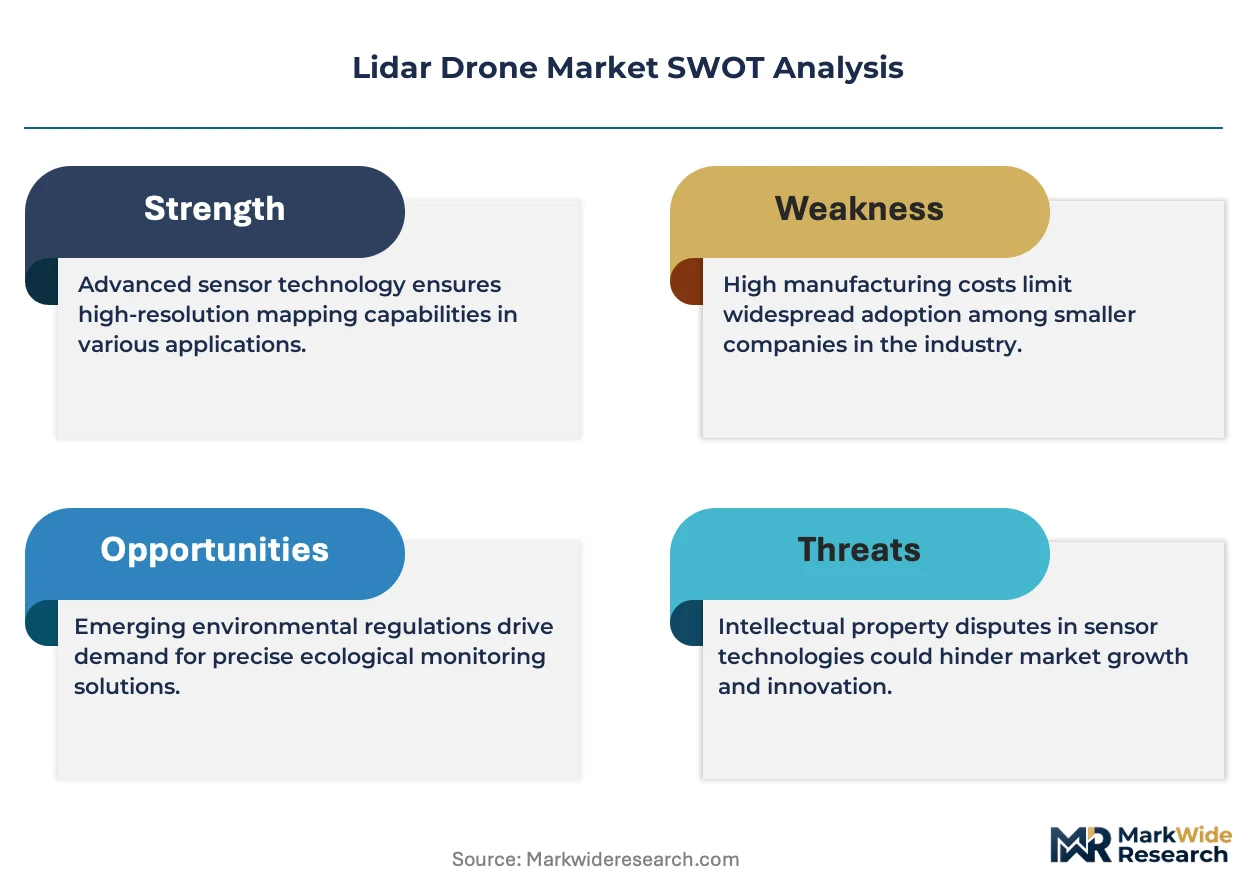
The unbundling of software from hardware payloads is shifting procurement patterns, allowing users to select best-of-breed system components. This modular approach contrasts with previously dominant all-in-one packages. RIEGL Laser Measurement Systems GmbH specializes in high-accuracy sensors for demanding scientific and surveying applications. Meanwhile, SZ DJI Technology Co., Ltd. positions its offerings as fully integrated, accessible solutions for broad commercial use.
A lidar drone integrates an unmanned aerial vehicle with a Light Detection and Ranging sensor. The sensor emits rapid laser pulses, often exceeding 500,000 points per second, to measure distances and create a precise three-dimensional point cloud. This data enables the generation of highly accurate digital terrain and surface models. While the LiDAR sensor is the core component, the GNSS receiver is critical for georeferencing the collected data accurately.
Market access is shaped by national aviation authorities, including the FAA in the United States, EASA in Europe, and the Civil Aviation Administration of China. These bodies set the rules for drone weight classes, operator certification, and flight permissions for sensitive areas. Regulations governing beyond-visual-line-of-sight operations are a particularly critical factor for large-scale surveying projects. Future growth depends on the continued harmonization of these international airspace frameworks.
Market Dynamics
The central structural force shaping the lidar drone market is the unbundling of software from hardware payloads. This modularization allows end-users to mix and match best-in-class components, directly challenging the dominance of previously integrated, all-in-one system packages.
Growth Catalysts
- Sensor Miniaturization:The development of compact, lightweight solid-state LiDAR sensors enables integration onto smaller drone platforms, opening up applications in precision agriculture and indoor mapping where larger systems were previously impractical.
- Infrastructure Investment:Demand for high-accuracy surveying in large-scale construction and civil engineering projects, particularly for progress monitoring and as-built verification, provides a primary catalyst in markets like the United States and Germany.
- Airspace Rule Harmonization:Regulatory progress by bodies like the FAA and EASA toward clear frameworks for beyond-visual-line-of-sight (BVLOS) flights is expanding the viable operational range for large-area mapping and corridor surveys.
Market Restraints
- High Initial Capital Outlay:The combined cost of survey-grade LiDAR sensors, high-precision GNSS/INS positioning systems, and the drone itself presents a substantial investment barrier for small to medium-sized enterprises and independent surveyors.
- Restrictive Flight Regulations:Stringent and often inconsistent national regulations governing drone operations, especially concerning flights over populated areas and in controlled airspace, limit deployment for many commercial applications.
- Data Processing Bottlenecks:The immense size of point cloud datasets requires specialized software, powerful computing hardware, and skilled technicians for processing, creating a significant post-acquisition workflow challenge for many organizations.
Strategic Opportunities
- Environmental and Carbon Monitoring:New applications in forestry management for biomass estimation, carbon stock accounting, and wildfire risk assessment are creating demand, particularly in regions with strong climate policies like Canada and Northern Europe.
- Multi-Sensor Payload Integration:Combining LiDAR with other imaging systems, such as hyperspectral or thermal cameras, on a single platform creates opportunities for advanced data products in precision agriculture, utility inspection, and geology.
- Emerging Market Infrastructure:Greenfield infrastructure development in regions like Southeast Asia and Latin America provides a significant opportunity where lidar drones can bypass the challenges of difficult terrain for terrestrial surveying.
Industry Challenges
- Skilled Personnel Deficit:A shortage of professionals who possess the dual expertise of certified drone piloting and the advanced skills needed for LiDAR data processing and analysis constrains the ability of service providers to scale operations.
- Data Interoperability Issues:The lack of universal standards for point cloud data formats and metadata complicates the integration of data from different sensor systems into a cohesive workflow, increasing project time and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidar Drone Market |
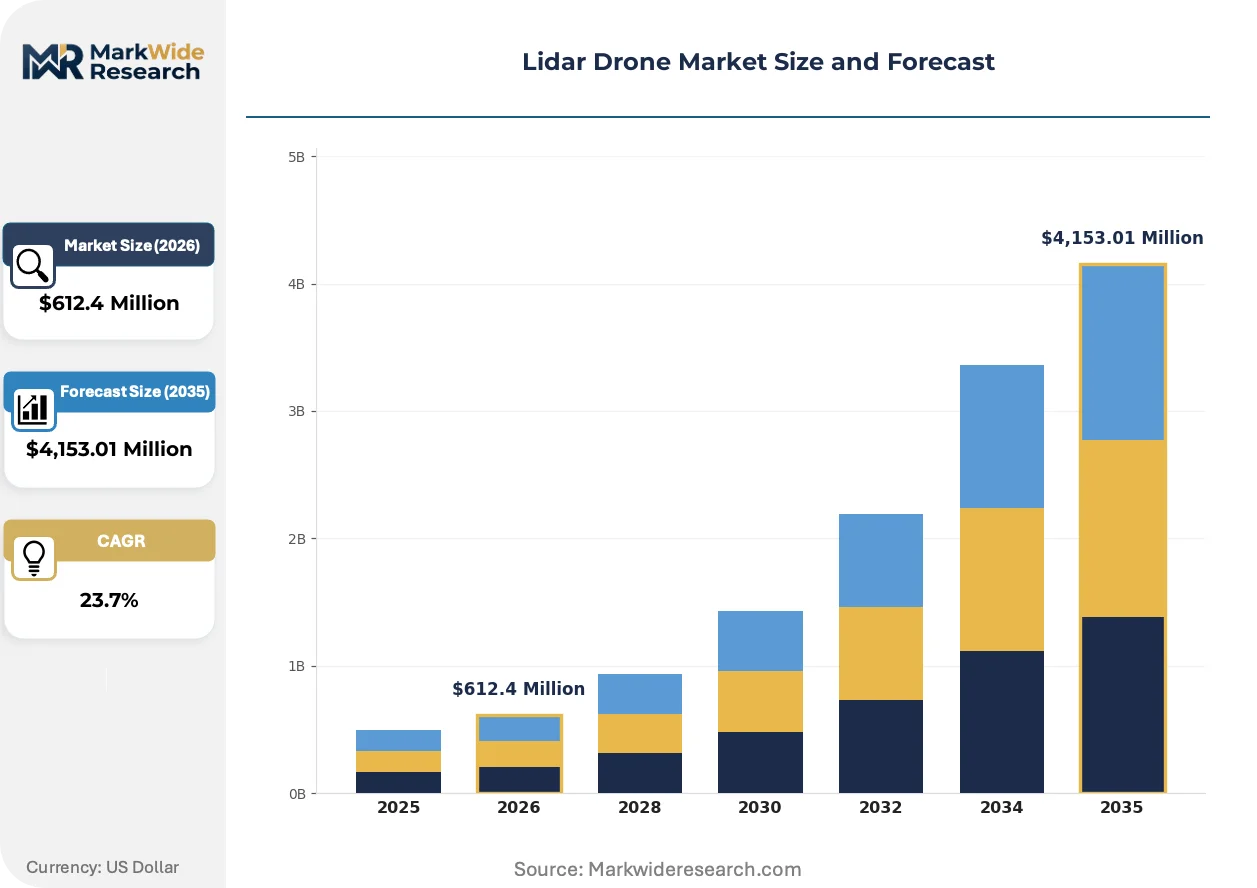
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $4,153.01 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Mapping, Surveying, Forestry, Agriculture End Use Industry: Construction, Transport, Energy, Mining Technology: Terrestrial, Aerial, Mobile, Static Component: LiDAR Sensor, Software, GNSS Receiver, Camera |
| Companies Covered | Velodyne Lidar, Inc., RIEGL Laser Measurement Systems GmbH, Teledyne Optech Inc., Phoenix LiDAR Systems, YellowScan, Leica Geosystems AG, SZ DJI Technology Co., Ltd., Microdrones, GeoCue Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidar Drone Market Strategic Shifts & Innovations
The market's evolution is reshaping around the convergence of sensor physics and cloud-based analytics. This shift moves the center of value from the hardware itself to the actionable intelligence derived from point cloud data, creating new service-based business models.
Solid-state LiDAR technology, which steers laser beams electronically without moving parts, offers superior durability and a smaller form factor. Commercial users in mining and aggregates are adopting these ruggedized sensors for use in harsh operational environments. This trend is consolidating the market's focus away from larger mechanical scanners toward more compact, reliable, and cost-effective drone payloads.
National aviation authorities are implementing remote identification mandates, such as the FAA's Remote ID rule in the US. These regulations enhance airspace security by broadcasting drone identification and location information, which is a prerequisite for enabling more complex operations. Surveying and inspection firms are most affected, as compliance is necessary to conduct legal flights over people or beyond visual line of sight.
A move toward data-as-a-service (DaaS) business models is gaining traction among end-users. This approach disrupts the traditional capital equipment sales cycle by allowing customers to subscribe to aerial data acquisition and analysis without the high upfront cost of owning the drone and sensor. This procurement shift is most apparent in Europe for project-based environmental monitoring and agricultural assessments.
Lidar Drone Market Segmentation
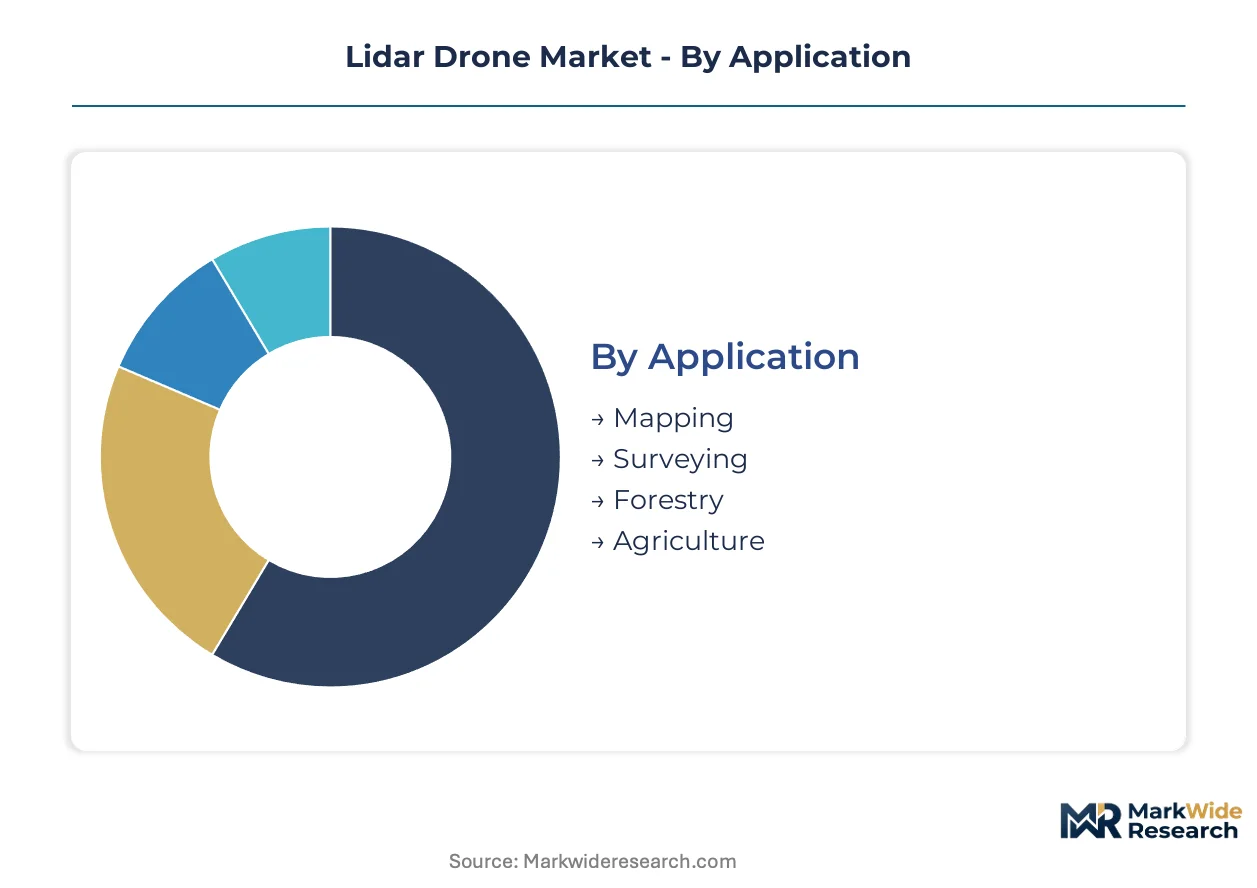
Segmentation within the lidar drone market illuminates the diverse operational contexts and technological demands shaping its expansion. A granular view helps differentiate between established applications and emerging opportunities, guiding strategic development for hardware manufacturers and service providers alike. Understanding these distinctions clarifies where value is created and how procurement decisions are made across various end-user groups.
Application:
The application landscape for lidar drones presents a clear distinction between high-volume, standardized data collection and specialized, premium-tier analytical outputs.
- Mapping:This involves large-area data capture for generating digital terrain and surface models, often used as foundational base maps. Demand for mapping applications is concentrating in infrastructure planning projects within the United States, driven by requirements for accurate spatial data.
- Surveying:Surveying applications focus on creating highly precise elevation models and point clouds for detailed site analysis and measurement. High-accuracy surveying is critical for construction site development in Germany, ensuring compliance with as-built verification standards.
- Forestry:Lidar drones are utilized for biomass estimation, canopy structure analysis, and carbon stock accounting.
- Agriculture:Precision agriculture employs lidar for crop health assessment, field drainage analysis, and yield prediction.
Today's leader: Surveying. Tomorrow's challenger: Forestry.
End Use Industry:
The end-use industry segmentation highlights distinct operational requirements and varying investment scales across different customer types.
- Construction:This sector leverages lidar drones for progress monitoring, volumetric calculations, and as-built verification on large-scale infrastructure projects. Demand from construction firms in the United States is high for efficient project management and quality control throughout the building lifecycle.
- Energy:Energy companies deploy lidar drones for power line inspection, pipeline monitoring, and wind turbine assessment to ensure asset integrity and regulatory compliance. Utility infrastructure projects across Europe require precise data for maintenance planning and fault detection.
- Transport:Lidar drones support corridor mapping for road, rail, and waterway networks, aiding in planning and maintenance.
- Mining:Mining operations use lidar for open-pit volume calculations, stockpile management, and geological mapping.
The Construction sector currently holds the largest share, while Energy is expanding most quickly.
Technology:
Technology segmentation reveals varying levels of complexity and deployment costs, influencing solution accessibility across different user bases.
- Aerial:This technology refers to lidar sensors integrated onto unmanned aerial vehicles for comprehensive large-area data acquisition from above. Aerial lidar is foundational for infrastructure mapping in Germany, offering speed and coverage for extensive projects.
- Mobile:Mobile lidar systems are typically mounted on vehicles or backpacks, enabling rapid data collection along linear features like roads or railways. Mobile solutions support dynamic environment capture for road network development in the United States.
- Terrestrial:Terrestrial lidar involves ground-based static or portable scanners for highly detailed, localized site surveys.
- Static:Static lidar systems are fixed-position scanners used for continuous monitoring of deformation or structural changes over time.
Aerial lidar technology dominates drone-based applications, with Mobile solutions climbing the fastest for specific corridor projects.
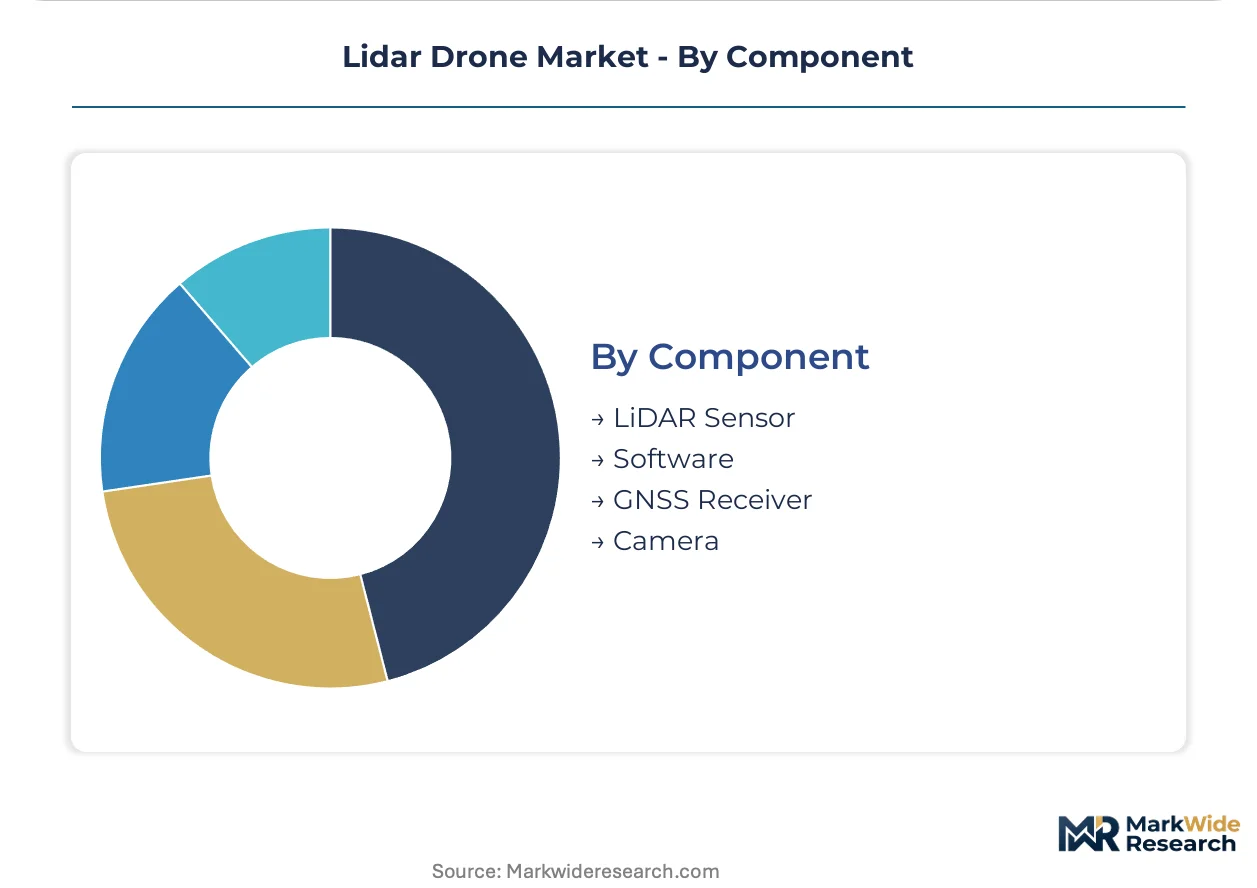
Component:
The component breakdown highlights distinct value propositions, ranging from core data acquisition hardware to intelligence-generating software platforms.
- LiDAR Sensor:This is the core component, emitting and receiving laser pulses to measure distances and generate point clouds, available in solid-state or mechanical configurations. Miniaturization of lidar sensors is critical for integration onto smaller, more agile drone platforms.
- Software:Software encompasses the processing, analysis, and visualization tools required to transform raw point cloud data into actionable intelligence and models. Cloud-based software solutions are gaining traction in Europe for efficient data interpretation and collaborative workflows.
- GNSS Receiver:The Global Navigation Satellite System receiver provides precise positioning data crucial for accurate georeferencing of lidar point clouds.
- Camera:Cameras, including RGB, multispectral, or thermal, are often integrated with lidar for data fusion, providing additional visual context to the point cloud.
LiDAR Sensors remain the foundational component, while Software solutions are gaining share fastest through value-added analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lidar drone market initially scaled in regions where high-accuracy surveying and mapping applications became critical for infrastructure development. Miniaturization of sensor technology further expanded its utility across diverse industries globally. Demand for precise spatial data continues to drive regional market expansion.
United States
The United States exhibits strong demand for lidar drones in infrastructure planning and large-scale construction projects. The FAA's Remote ID rule facilitates more complex drone operations by enhancing airspace security and identification. Major infrastructure initiatives across the Pacific Northwest are leveraging lidar for detailed corridor mapping.
Germany
German construction site development requires highly accurate elevation models for as-built verification and quality control. EASA regulations provide a harmonized framework for drone operations across Europe, supporting broader deployment. Engineering and surveying firms in Bavaria are actively integrating lidar drone solutions for civil engineering projects.
Canada
Canadian forestry management benefits significantly from lidar drones for biomass estimation and carbon stock accounting. Transport Canada regulations are evolving to support beyond-visual-line-of-sight operations, crucial for vast forested areas. Research institutions in British Columbia are pioneering new applications for environmental monitoring.
China
China's extensive infrastructure development projects, including high-speed rail and urban expansion, drive substantial demand for lidar drone mapping. The Civil Aviation Administration of China (CAAC) is progressively establishing rules for commercial drone use. Major drone manufacturing clusters in Shenzhen are also pushing technological advancements.
Japan
Japanese precision agriculture and disaster management applications are increasingly adopting lidar drones for detailed terrain analysis. The Japan Civil Aviation Bureau (JCAB) oversees regulations for unmanned aircraft, ensuring safe integration into national airspace. Robotics and sensor development hubs in Tokyo are contributing to advanced lidar payload designs.
Lidar Drone Market Key Industry Players
Premium-margin players sit above commodity-margin players across solution sophistication and data accuracy. The market structure is characterized by a mix of specialized sensor manufacturers and integrated system providers. Strategic archetypes include high-accuracy specialists, accessible solution providers, and data-as-a-service operators. Dominant competitive moves involve strategic partnerships for software integration and continuous portfolio diversification into new applications.
Specialists in high-accuracy sensor technology, such as RIEGL Laser Measurement Systems GmbH, focus on demanding scientific applications. SZ DJI Technology Co., Ltd. positions its offerings as fully integrated, accessible solutions for broad commercial use, particularly appealing to new entrants. YellowScan, a French company, exemplifies providers specializing in compact and lightweight lidar systems for various drone platforms, emphasizing ease of integration and robust data capture.
| Leading Market Players |
|---|
| Velodyne Lidar, Inc. |
| RIEGL Laser Measurement Systems GmbH |
| Teledyne Optech Inc. |
| Phoenix LiDAR Systems |
| YellowScan |
| Leica Geosystems AG |
| SZ DJI Technology Co., Ltd. |
| Microdrones |
| GeoCue Group |
| Others |
Cost & Logistics Intelligence
Construction firms' demand for high-accuracy data drives a project-based pricing model for lidar drone services and hardware. This procurement pattern concentrates supply chain activity around specialized sensor manufacturers and integrated system providers.
Pricing Analysis
Project-based pricing, often supplemented by subscription models for software, characterizes the market's commercial transactions. Price differentiation stems from sensor accuracy and the sophistication of bundled analytics software. Pricing softness impacts commodity-tier hardware due to miniaturization and increased competition. Small to medium-sized enterprises exhibit higher price sensitivity compared to large infrastructure development firms requiring certified data quality.
Supply Chain Analysis
Regulatory mandates from national aviation authorities, such as the FAA's Remote ID rule, influence component sourcing for compliant drone systems. Supply concentration for advanced LiDAR sensors and drone platforms centers on China, Germany, and the United States. The supply chain sources critical inputs like solid-state LiDAR chips and high-precision GNSS/INS modules. Single-source vulnerability for specialized sensor components presents a structural risk. Distribution runs through a mix of direct sales to large enterprises and a network of specialized value-added resellers for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the FAA's Remote ID rule serving as a key milestone enabling more complex drone operations and driving demand.
For Market Incumbents: Hedge against market modularization by acquiring specialized software analytics firms to maintain integrated value propositions. Deepen R&D investment in compact, solid-state LiDAR sensors to counter emerging low-cost hardware. Consolidate market share through strategic partnerships that expand geographic reach in infrastructure-heavy regions like Southeast Asia.
For New Entrants and Emerging Players: Begin with niche applications like environmental monitoring or precision agriculture, where specialized data products can command premium pricing. The most penetrable segment remains small surveying firms seeking accessible, integrated solutions. A data-as-a-service (DaaS) go-to-market angle allows customers to bypass high initial capital outlays.
For Investors and Strategic Acquirers: Geospatial data analytics firms are the most active acquirer in this space, seeking to enhance their service portfolios. Long-term viability for investments hinges on providers offering integrated hardware-software solutions or highly specialized data processing capabilities. A signal to watch is the continued harmonization of beyond-visual-line-of-sight (BVLOS) regulations across major economies, which will unlock significant operational scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Integration | Integrating advanced analytics software enhances the value proposition for end-users seeking actionable intelligence from point cloud data. |
| Solid-State Sensor R&D | Investing in solid-state LiDAR technology enables smaller, more durable sensors for diverse drone platforms and applications. |
| Data-as-a-Service Expansion | Shifting to DaaS models reduces upfront costs for end-users, expanding market access for surveying and monitoring services. |
| Regulatory Compliance Investment | Ensuring compliance with national aviation authorities, like EASA, facilitates broader operational ranges for commercial drone fleets. |
| Multi-Sensor Payload Development | Combining LiDAR with thermal or hyperspectral cameras creates advanced data products for sectors like precision agriculture. |
Research Approach
Coverage spans the United States, Germany, Canada, China, and Japan, with primary inputs from each key region. The analysis combines in-depth primary interviews with drone operators, sensor engineers, civil aviation authorities, and construction project managers, validated by secondary data. Secondary sources include aviation authority publications, industry association reports, and academic research on LiDAR applications, ensuring bottom-up and top-down triangulation.
The market's granularity was modeled across application, end-use industry, technology, component, and operational environment dimensions. The analytical framework projects market growth across the analysis window, with compound annual growth rates derived from historical trends and projected technological adoption. Key forecast inputs include global infrastructure spending and anticipated regulatory changes for drone operations.
Several conditions sit outside the modeled scope, including micro-drone markets and military applications. Forecasts reflect assumptions concerning market dynamics and technological advancements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Europe Aerostat Systems Market