
 Rotary-Wing Lidar Drone Market | 2026-2036
Rotary-Wing Lidar Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary-Wing Lidar Drone Market Insights
Market Context
Certified drone pilot availability is bifurcating the competitive landscape between scaled operators and regional service providers. Velodyne Lidar leverages its solid-state sensor portfolio to anchor supply relationships with major UAV integrators. RIEGL Laser Measurement Systems GmbH sustains its position through in-house manufacturing of pulse-based lidar engines with survey-grade accuracy. SZ DJI Technology Co., Ltd dominates consumer and prosumer rotary-wing hardware volumes while extending enterprise partnerships for payload integration.
Technical Definition and Segment Structure
Rotary-wing lidar drones combine multi-rotor unmanned aerial vehicles with light detection and ranging sensors to generate three-dimensional point clouds from hovering or low-speed flight profiles, typically achieving point densities exceeding 100 points per square meter at operational altitudes below 120 meters. These systems serve geospatial professionals requiring vertical takeoff capability, obstacle proximity, and repeat-station accuracy in confined or complex terrain. Quadcopter configurations lead unit shipments due to mechanical simplicity and payload flexibility, while solid-state lidar technology captures expanding share as MEMS-based scanners reduce size, weight, and power constraints for smaller airframes. Infrastructure inspection applications command premium pricing cycles tied to regulatory mandates for structural monitoring, whereas precision agriculture represents the fastest-growing application as agronomists adopt variable-rate input management.
Regulatory Environment and Outlook
FAA Part 107 and emerging BVLOS frameworks in the United States, EASA drone regulation harmonization across European member states, and CAAC operational category certifications in China collectively determine where rotary-wing lidar fleets may deploy commercially and what sensor payloads satisfy airworthiness criteria. Compliance with ISO 21384-3 for unmanned aircraft systems and IEC 61508 functional safety standards increasingly filters procurement specifications for lidar-integrated drones in mining and energy sectors. Stakeholders must monitor which regulators relax altitude and line-of-sight restrictions first, as this will reshape route planning software requirements and fleet scale economics for aerial survey operators.
Market Dynamics
Solid-state MEMS lidar is fragmenting sensor procurement patterns as survey-grade accuracy migrates from heavy mechanical scanners to sub-kilogram payloads, compressing airframe size requirements and opening rotary-wing platforms to smaller commercial operators.
Growth Catalysts
- FAA Part 107 BVLOS Pathways:The FAA's evolving waiver framework for beyond-visual-line-of-sight operations is unlocking corridor-scale infrastructure surveys across the United States, enabling single-pilot teams to cover linear assets without visual observers.
- Mining Sector Digital Twins:Open-pit and underground mining engineers are mandating weekly volumetric surveys for stockpile reconciliation, creating recurring demand for rotary-wing lidar with centimeter-grade repeatability in GPS-denied environments.
- Edge Computing Convergence:Onboard NVIDIA Jetson and Qualcomm RB3 platforms now process point cloud denoising in real time, eliminating ground station dependency and compressing survey turnaround from days to hours.
Market Restraints
- Sensor Cost Concentration:High-performance 1550nm fiber lasers and InGaAs detectors remain concentrated among Japanese and German component suppliers, exposing integrators to yen and euro volatility and 12-16 week lead times.
- Altitude Ceiling Friction:EASA's specific category operational limitations and national variations in maximum flight height restrict European operators from capturing optimal point densities above 120 meters without costly risk assessments.
- Photogrammetry Substitution:Structure-from-motion software paired with high-resolution RGB cameras captures adequate 3D data for vegetation-free terrain at one-third the hardware cost, pressuring lidar pricing in price-sensitive cadastral markets.
Strategic Opportunities
- Indian Infrastructure Digitization:The National Highway Authority of India's LiDAR-based highway asset mapping mandate creates immediate demand for rotary-wing platforms capable of low-altitude bridge underside inspection in dense traffic corridors.
- EU Green Deal Methane Monitoring:EISA's proposed mandatory leak detection and repair regulations for oil and gas infrastructure position tunable diode lidar payloads as compliance tools, favoring rotary-wing agility over fixed-wing coverage.
- 5G Network Digital Twins:Telecom infrastructure managers are adopting millimeter-accurate 3D models for line-of-sight verification, creating a new channel through tower maintenance contractors previously outside geospatial procurement.
Industry Challenges
- Multi-Sensor Calibration Expertise:Integrating IMU, GNSS, and lidar streams demands specialized photogrammetrists and navigation engineers, functions scarce outside aerospace clusters in Bavaria, California, and Shenzhen.
- Type Certification Timelines:EASA's drone regulation framework requires extensive flight envelope testing for heavy-lift rotary platforms, extending time-to-revenue for new airframe designs by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary-Wing Lidar Drone Market |
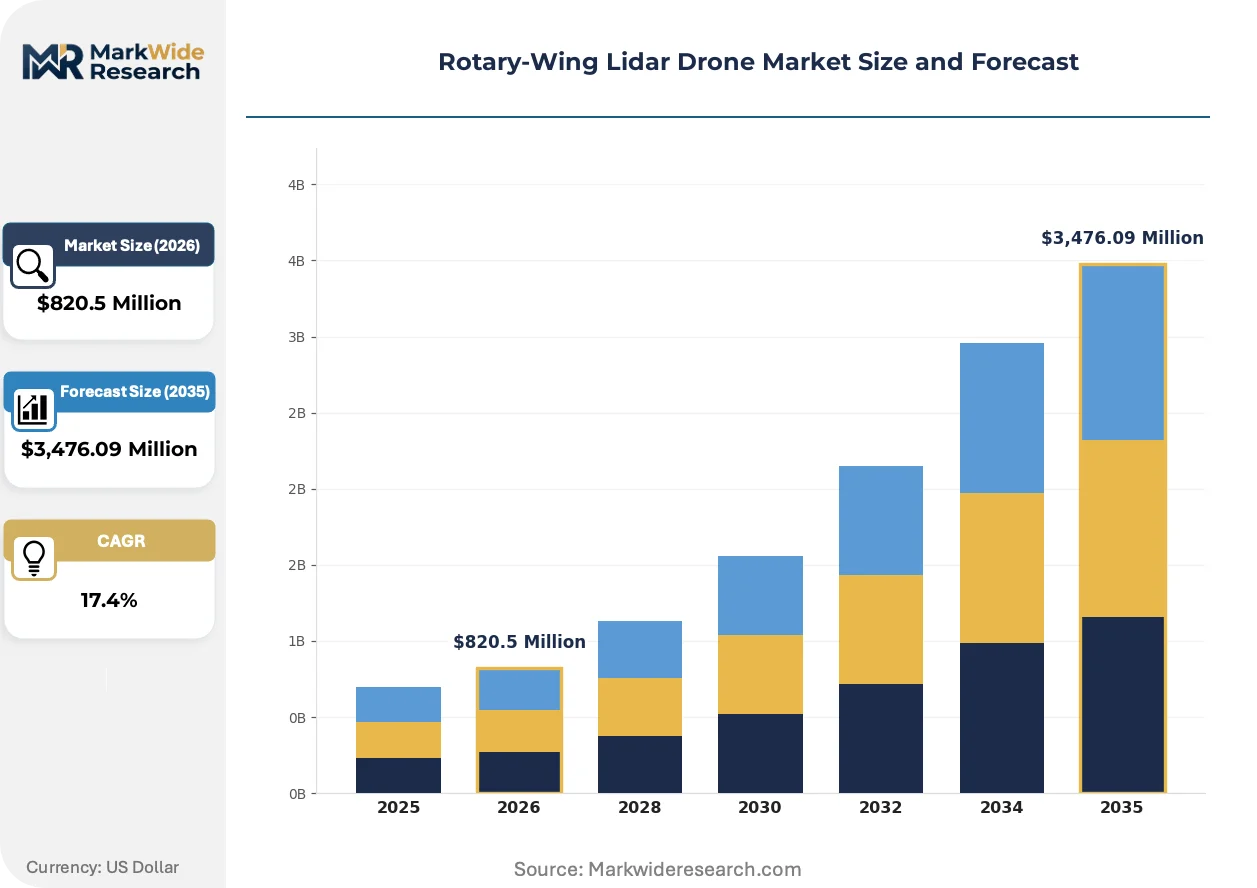
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,476.09 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadcopter, Hexacopter, Octocopter, Single Rotor Technology: TOF Lidar, Pulse-Based Lidar, Frequency Modulated Continuous Wave, Solid State Lidar, MEMS Lidar Application: Topographic Mapping, Forestry Management, Mining Surveying, Precision Agriculture, Infrastructure Inspection End User: Surveyors, Agricultural Scientists, Mining Engineers, Construction Managers, Environmental Consultants |
| Companies Covered | Velodyne Lidar, RIEGL Laser Measurement Systems GmbH, Teledyne Optech, Phoenix LiDAR Systems, YellowScan, SZ DJI Technology Co., Ltd, Leica Geosystems AG, Microdrones, GeoCue Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary-Wing Lidar Drone Market Trends and Innovations
Active developments across sensor physics, regulatory interpretation, and procurement models are compressing deployment cycles and redistributing value capture between hardware manufacturers and flight service operators.
Flash lidar using single-pulse solid-state illumination is fragmenting the traditional scanner market by eliminating mechanical wear components and enabling 30Hz frame rates for dynamic obstacle mapping. Autonomous inspection teams in offshore wind and transmission tower markets are adopting these arrays for close-proximity flight paths where mechanical latency creates collision risk. The technology is compressing maintenance intervals and shifting procurement criteria from point density specifications to system mean-time-between-failure metrics.
EASA's drone regulation harmonization across member states is standardizing operational category boundaries and mutual recognition of remote pilot competency certificates. Industrial operators can now deploy German-certified flight crews in Spanish solar farm surveys without duplicate licensing, compressing cross-border service scaling friction. Mining conglomerates with pan-European asset portfolios are consolidating vendor relationships around operators holding multiple national approvals.
Survey contracting is pivoting from equipment ownership to flight-hour subscriptions as specialized operators aggregate sensor fleets across multiple airframe types. Agricultural cooperatives and regional engineering firms are accessing RIEGL and Velodyne-class capabilities through pay-per-hectare arrangements rather than capital expenditure. This model is most visible in Australia's wheat belt and California's Central Valley, where seasonal demand spikes make owned fleet utilization uneconomical.
Rotary-Wing Lidar Drone Market Segmentation
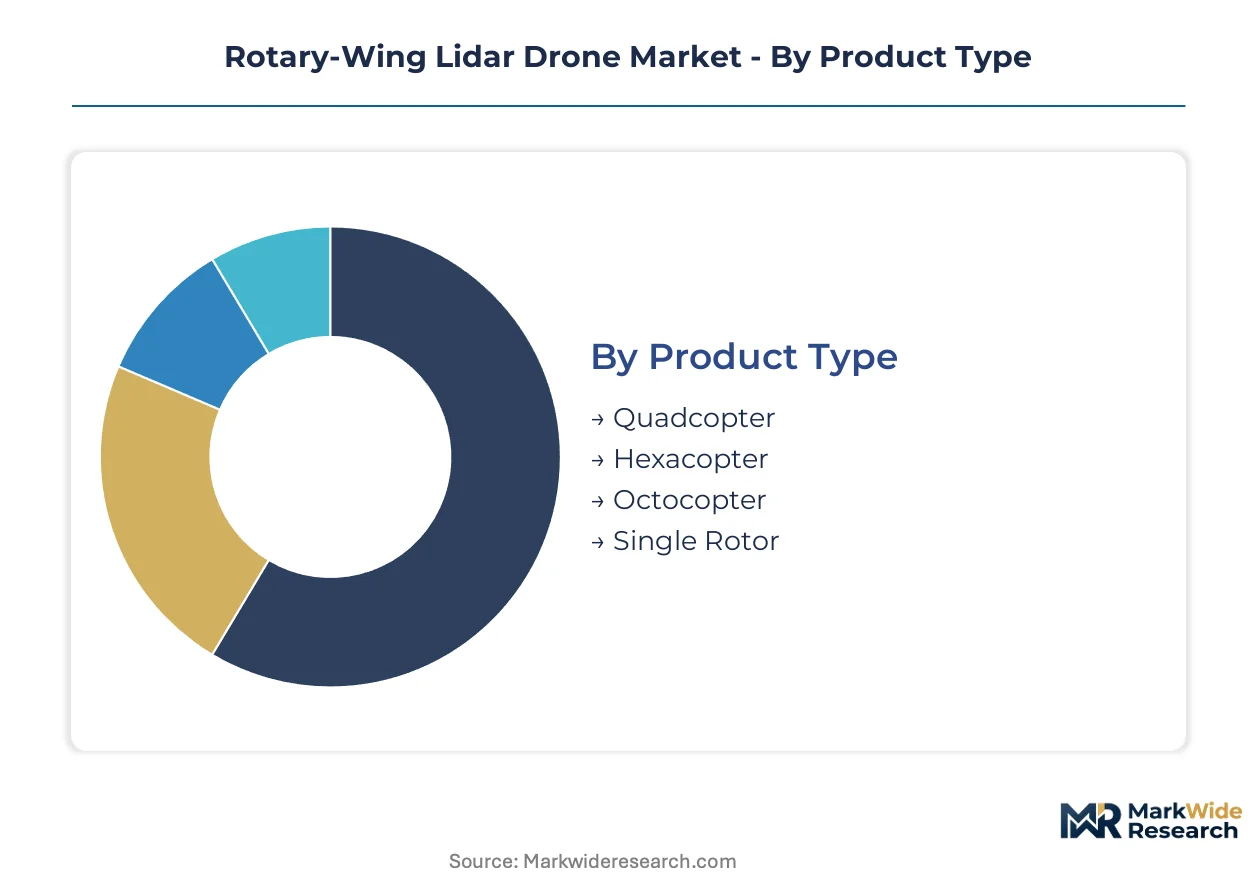
Rotary-wing lidar drone procurement patterns diverge sharply across airframe configurations, sensor physics, and professional end-use requirements. Each segmentation axis carries distinct substitution pressures from photogrammetry, satellite imagery, or ground-based scanning alternatives.
Product Type:
Photogrammetry-equipped fixed-wing platforms and backpack-mounted terrestrial scanners exert the strongest substitution pressure on smaller multi-rotor formats, forcing quadcopter and hexacopter suppliers to defend payload flexibility as their core differentiation.
- Quadcopter:Four-rotor architectures dominate unit economics through mechanical simplicity and rapid field deployment. Mining engineers in Australia and the United States specify these platforms for stockpile volumetrics where flight endurance under 25 minutes suffices.
- Hexacopter:Six-motor redundancy supports heavier lidar payloads in GPS-denied environments. Underground mine surveyors in Germany and Canada favor hexacopter configurations for vertical shaft inspection where single-rotor failure tolerance is mandatory.
- Octocopter:Eight-rotor systems carry dual-sensor arrays for simultaneous RGB and lidar capture.
- Single Rotor:Helicopter-style platforms deliver extended endurance for linear corridor mapping.
Quadcopter configurations retain volume leadership; hexacopter platforms hold the steepest expansion curve as payload demands intensify.
Technology:
Cost tier stratification separates survey-grade mechanical scanners from emerging solid-state alternatives, with price-performance ratios determining which technologies penetrate price-sensitive agricultural markets versus premium infrastructure contracts.
- TOF Lidar:Time-of-flight systems measure distance via laser pulse round-trip timing. Chinese infrastructure inspection contractors deploy TOF payloads for bridge deck surveys where millimeter-grade accuracy justifies sensor investment.
- Pulse-Based Lidar:Discrete pulse emission enables long-range detection with high point density. German and Austrian alpine surveyors specify pulse-based engines for terrain capture through dense canopy.
- Frequency Modulated Continuous Wave:FMCW architectures deliver simultaneous range and velocity data.
- Solid State Lidar:Semiconductor-based illumination eliminates mechanical scanning components.
- MEMS Lidar:Micro-electromechanical mirror systems miniaturize scanning mechanisms for sub-kilogram payloads.
Pulse-based lidar retains volume leadership; solid-state alternatives gain share fastest as MEMS manufacturing scales.
Application:
Customer type fragmentation separates recurring subscription buyers from capital-intensive fleet operators, with agricultural cooperatives and mining conglomerates presenting divergent procurement rhythms and sensor specification tolerances.
- Topographic Mapping:Bare-earth elevation models support civil engineering design and flood risk assessment. Surveyors in the Netherlands and Bangladesh prioritize topographic rotary-wing missions where tidal flat accessibility excludes ground crews.
- Forestry Management:Canopy penetration and biomass estimation drive sensor selection. Swedish and Finnish forest managers contract rotary-wing lidar for annual timber volume audits across inaccessible boreal stands.
- Mining Surveying:Weekly volumetric reconciliation mandates centimeter-grade repeatability.
- Precision Agriculture:Variable-rate input management creates seasonal demand spikes.
- Infrastructure Inspection:Regulatory mandates for structural monitoring command premium pricing.
Infrastructure inspection retains volume leadership; precision agriculture climbs fastest as agronomists adopt variable-rate management.
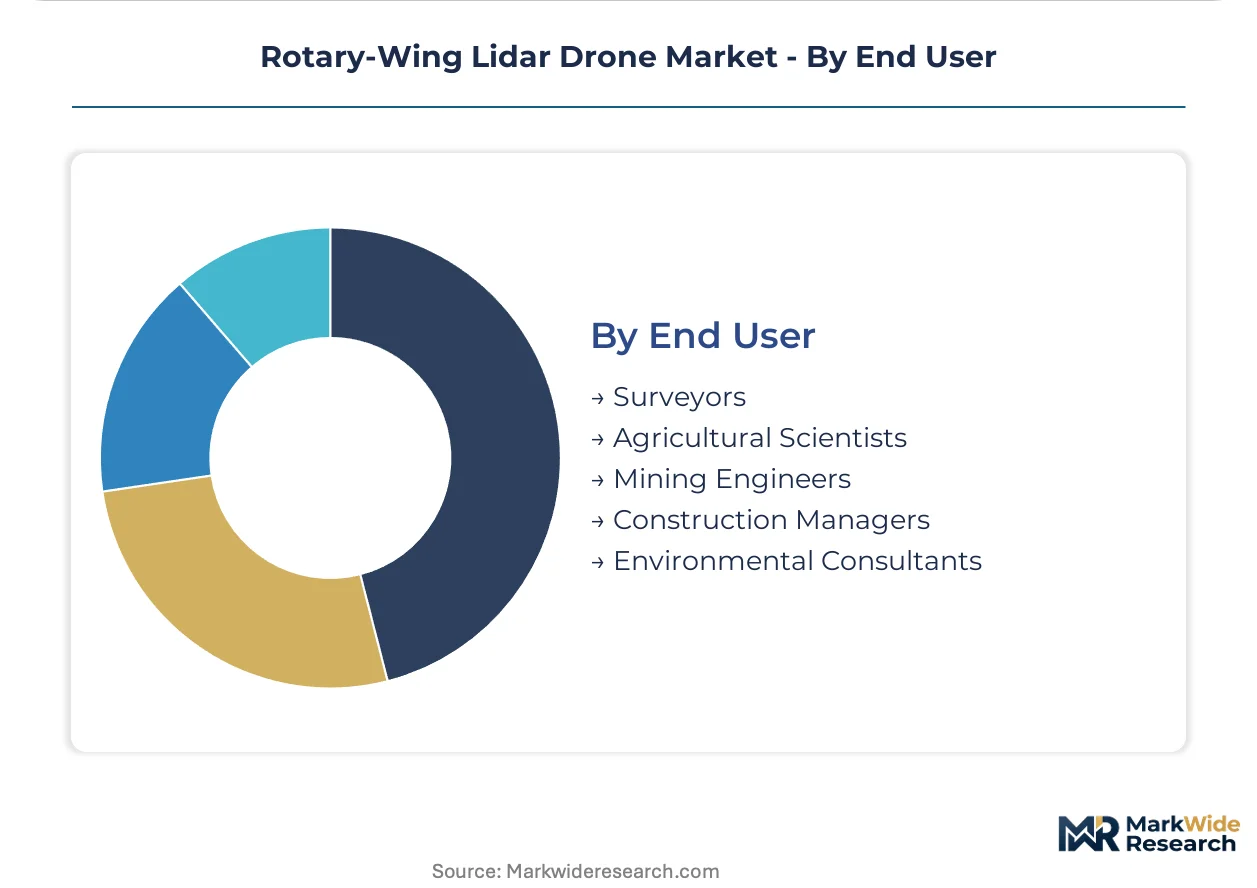
End User:
Geographic procurement concentration clusters around Bavaria, California, and Shenzhen aerospace corridors, with regional service providers competing against scaled operators for certified pilot availability.
- Surveyors:Licensed geospatial professionals deliver contracted point cloud deliverables to construction and utility clients. German surveyors leverage EASA mutual recognition to deploy crews across Spanish and Italian solar farm projects.
- Agricultural Scientists:University extension services and agronomy firms translate lidar-derived crop height models into input prescriptions. Californian agricultural scientists partner with drone service providers on pay-per-hectare terms.
- Mining Engineers:Open-pit and underground operations staff specify survey-grade repeatability.
- Construction Managers:Earthwork volume tracking and as-built verification drive adoption.
- Environmental Consultants:Habitat mapping and erosion monitoring create episodic demand.
Surveyors retain volume leadership; agricultural scientists represent the fastest-expanding customer category as subscription models penetrate cooperative procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Austrian alpine survey markets where pulse-based lidar commands premium rates, while Chinese integrators compress hardware margins through scaled MEMS manufacturing. This asymmetry reshapes where technology leadership and volume production gravitate.
United States
FAA Part 107 BVLOS waiver pathways unlock corridor-scale infrastructure surveys across Texas and California transmission networks. The FAA's evolving beyond-visual-line-of-sight framework enables single-pilot teams to cover linear assets without visual observers. Phoenix LiDAR Systems and corridor-mapping operators cluster in California's Central Valley, where agricultural cooperatives adopt pay-per-hectare subscription models for seasonal crop monitoring.
Germany
EASA drone regulation harmonization standardizes operational category boundaries across member states, compressing cross-border service scaling friction. The EU Green Deal's methane monitoring mandates position tunable diode lidar payloads as compliance tools for oil and gas infrastructure. Bavarian aerospace corridors anchor RIEGL Laser Measurement Systems' in-house manufacturing of pulse-based engines, supplying survey-grade accuracy for underground mine vertical shaft inspection.
China
CAAC operational category certifications determine where rotary-wing lidar fleets deploy commercially and what sensor payloads satisfy airworthiness criteria. National infrastructure digitization programs scale autonomous aerial survey procurement across Yangtze River Delta provinces. SZ DJI Technology's Shenzhen headquarters dominates consumer and prosumer rotary-wing hardware volumes while extending enterprise partnerships for payload integration.
Australia
Weekly volumetric reconciliation mandates from open-pit mining engineers create recurring demand for centimeter-grade repeatability in GPS-denied environments. The country's civil aviation safety authority maintains strict altitude and operational category boundaries that filter procurement specifications. Western Australia's Pilbara region concentrates flight service operators delivering stockpile surveys to iron ore majors through seasonal subscription arrangements rather than owned fleet models.
India
The National Highway Authority's LiDAR-based highway asset mapping mandate generates immediate demand for low-altitude bridge underside inspection in dense traffic corridors. BIS standards and central government procurement guidelines increasingly reference ISO 21384-3 for unmanned aircraft systems compliance. Maharashtra and Gujarat infrastructure contractors are expanding rotary-wing pilot certification programs to capture National Highway digitization contracts.
Rotary-Wing Lidar Drone Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive positioning across the value chain. Solid-state MEMS specialists and mechanical scanner incumbents occupy distinct tiers, with the former compressing airframe size requirements and the latter defending survey-grade accuracy premiums. Three archetypes dominate: sensor-integrated platform manufacturers, pure-play lidar engine suppliers, and flight service operators aggregating third-party hardware. Consolidation pressure concentrates on strategic partnerships between UAV integrators and solid-state sensor portfolios, while geographic expansion through EASA mutual recognition certificates accelerates cross-border service scaling.
Among sensor-integrated platform specialists, Velodyne Lidar and RIEGL Laser Measurement Systems GmbH occupy positions at opposite ends of the technology-cost spectrum, with the former representing solid-state volume strategies and the latter exemplifying precision-engineered mechanical scanner persistence. SZ DJI Technology Co., Ltd anchors the hardware-aggregation archetype through its dominance of rotary-wing airframe volumes and enterprise payload partnership extensions. These three patterns illustrate how competitive positioning bifurcates between accuracy-premium defenders and cost-compression challengers.
| Leading Market Players |
|---|
| Velodyne Lidar |
| RIEGL Laser Measurement Systems GmbH |
| Teledyne Optech |
| Phoenix LiDAR Systems |
| YellowScan |
| SZ DJI Technology Co., Ltd |
| Leica Geosystems AG |
| Microdrones |
| GeoCue Group |
| Others |
Pricing and Supply Chain Analysis
Solid-state MEMS lidar substitution for mechanical scanners redraws supply geography toward Shenzhen and Shenzhen-adjacent MEMS foundries while collapsing payload weight classes and eroding German-engineered scanner premiums. This displacement simultaneously compresses airframe size requirements and shifts pricing power from precision-optics houses to semiconductor-scale manufacturers.
Pricing Analysis
The customization-premium spread separates survey-grade pulse-based systems from configurable solid-state alternatives. Pricing stratifies across premium, standard, and economy tiers defined by point density certification and IMU integration grade. Cost compression in the standard tier intensifies because SZ DJI Technology bundles payload partnerships at volume scale. Mining engineers show lowest price sensitivity where centimeter-grade repeatability justifies investment; agricultural cooperatives exhibit highest sensitivity and drive subscription model adoption.
Supply Chain Analysis
Strait of Malacca transit underwrites Japanese InGaAs detector and German 1550nm fiber laser delivery to assembly facilities in California and Bavaria. Component sourcing draws from Japan, Germany, and China for specialized photonics and MEMS foundry capacity. Single-source vulnerability concentrates in high-performance detector supply where two Japanese suppliers dominate telecom-qualified output. Distribution runs through UAV integrator direct channels and specialized geospatial equipment distributors serving surveyor and mining engineer procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 107 BVLOS pathway maturation constitutes a regulatory inflection accelerating corridor-scale deployment and reshaping fleet economics for single-pilot operations.
For Market Incumbents: Consolidate sensor-airframe integration partnerships before solid-state commoditization erodes mechanical scanner margins. Acquire EASA mutual recognition certificates across multiple member states to compress cross-border scaling friction. Prioritize backward integration into MEMS foundry relationships or captive supply agreements with Shenzhen-area manufacturers. For New Entrants and Emerging Players: CAAC operational category certification fast-tracks unlock immediate deployment rights across Yangtze River Delta infrastructure digitization programs. Target Indian National Highway Authority bridge inspection contracts where pilot certification scarcity constrains incumbent capacity. Pursue pay-per-hectare subscription positioning with Australian agricultural cooperatives to bypass capital-intensive fleet ownership barriers. For Investors and Strategic Acquirers: EASA drone regulation harmonization reshapes the acquisition landscape toward multi-national certification portfolios as scalable competitive moats. Five-to-ten year viability favors flight service operators aggregating third-party hardware over capital-intensive sensor manufacturing. Monitor FAA BVLOS waiver approval velocity as the critical signal for corridor-mapping fleet expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Operational Certification | FAA waiver acquisition enables single-pilot corridor surveys without visual observer cost burden. |
| MEMS Sensor Integration | Solid-state payload partnerships compress airframe size requirements for smaller commercial operators. |
| Multi-National Licensing | EASA mutual recognition certificates accelerate cross-border service scaling for mining conglomerates. |
| Subscription Model Deployment | Pay-per-hectare arrangements reduce seasonal utilization risk for agricultural cooperative clients. |
| Underground Mine Specialization | GPS-denied environment expertise commands premium pricing from open-pit and shaft inspection contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with rotary-wing lidar service operators, mining engineering directors, agricultural cooperative procurement managers, and geospatial survey firm principals. Secondary validation drew from FAA BVLOS waiver filings, EASA operational category guidance documents, CAAC certification registries, and ISO 21384-3 compliance databases. Bottom-up fleet deployment estimates triangulated against top-down sensor shipment data from component manufacturers.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across airframe configuration, sensor physics type, application vertical, and end-user professional category. CAGRs were derived from regression against infrastructure digitization program budgets, mining survey frequency mandates, and agricultural cooperative technology adoption curves. Industry-specific inputs included BVLOS waiver approval rates and seasonal subscription contract penetration in Australian and Californian agricultural markets.
Decision-makers should treat outputs as directional under continued regulatory relaxation assumptions; material deviation in FAA or EASA timeline enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as CAAC operational category expansion and Indian BIS standard adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Drone Jamming System Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Drone Parachute System Market