
 United States Wi-Fi Chipset Market | 2026-2036
United States Wi-Fi Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
United States Wi-Fi Chipset Market Intelligence
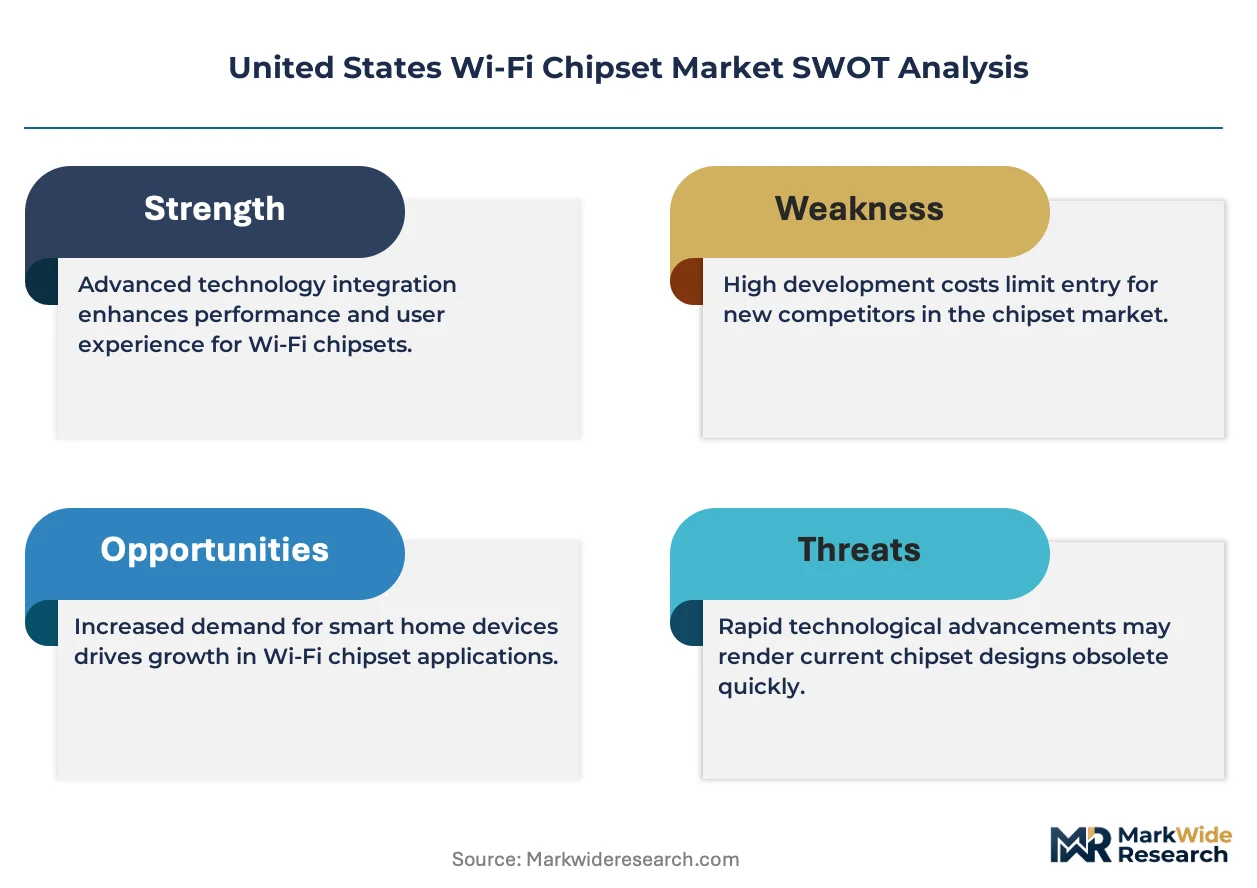
Wi-Fi 7 certification tiers are redrawing competitive positioning in the United States Wi-Fi Chipset Market. Qualcomm Technologies, Inc. leverages its modem-RF system integration to dominate premium smartphone sockets. Broadcom sustains leadership in enterprise access point silicon through backward integration into custom ARM cores. Marvell Technology, Inc. anchors data center and carrier-grade infrastructure with specialized offload architectures.
A Wi-Fi chipset integrates baseband processors, RF transceivers, and power management into a single package, typically fabricated on 12nm to 6nm process nodes, enabling wireless local area network connectivity under IEEE 802.11 protocols. These devices modulate and demodulate radio signals across 2.4 GHz, 5 GHz, and 6 GHz bands to deliver data throughput from hundreds of megabits to tens of gigabits per second for consumer, enterprise, and industrial applications. Dual-band and tri-band chipsets currently occupy the highest volume tiers, though Wi-Fi 6E and Wi-Fi 7 silicon commands disproportionate margin pools as OEMs prioritize latency-sensitive applications in gaming and augmented reality headsets. Networking equipment and smart home devices represent structurally distinct demand curves, with the former emphasizing throughput density and the latter optimizing for standby power and cost.
The FCC governs spectrum allocation and device certification through Part 15 rules, directly shaping which frequency bands and power levels chipset vendors can target, while the EPA's evolving e-waste directives influence packaging and materials compliance for domestic manufacturing. IEEE 802.11be and Wi-Fi Alliance certification programs create interoperability thresholds that determine market access for new entrants versus incumbents. Stakeholders must monitor how the FCC proceeds with additional 6 GHz spectrum expansion and whether the Department of Commerce tightens export controls on advanced node semiconductor manufacturing equipment that could constrain domestic foundry capacity for next-generation designs.
Market Dynamics
The FCC's 6 GHz spectrum allocation has triggered a wholesale architecture shift across American Wi-Fi infrastructure, forcing chipset vendors to retool RF front-ends for tri-band operation while enterprise buyers accelerate refresh cycles to capture lower latency.
Growth Catalysts
- Industrial IoT Gateway Deployment:Manufacturing facilities in Michigan and Ohio are procuring Wi-Fi 6E chipsets to connect automated guided vehicles and predictive maintenance sensors on factory floors.
- FCC Part 15 Rule Expansion:The commission's unlicensed spectrum framework now permits higher power levels in the 6 GHz band, enabling outdoor fixed wireless access points for rural broadband.
- Cloud Infrastructure Co-location:Hyperscale data center operators in Northern Virginia and Oregon are integrating Wi-Fi 7 silicon for internal campus networks and edge compute facilities.
Market Restraints
- Advanced Node Foundry Concentration:Domestic 6nm and 4nm fabrication capacity remains captive to TSMC and Samsung, constraining volume scaling for Wi-Fi 7 baseband processors.
- RF Front-end Material Cost Volatility:Gallium arsenide and silicon germanium substrates face price pressure from defense and 5G base station demand competing for the same supply.
- Legacy 802.11n Device Persistence:Enterprise IT departments maintain extensive installed bases of 2.4 GHz-only equipment, compressing upgrade budgets and extending replacement timelines.
Strategic Opportunities
- Texas and Arizona Semiconductor Clusters:New domestic foundry investments by Intel and Samsung create captive supply opportunities for fabless Wi-Fi designers seeking geographic diversification.
- AR/VR Headset Integration:Meta and Apple hardware roadmaps specify Wi-Fi 7 for wireless tethering, opening high-margin sockets for low-latency chipset variants.
- Inflation Reduction Act Clean Energy Incentives:Smart grid and distributed energy resource management systems qualify for federal tax credits, stimulating Wi-Fi chipset demand in utility-scale deployments.
Industry Challenges
- Wi-Fi Alliance Certification Backlogs:Pre-certification testing queues for 802.11be products extend product launch windows by four to six months, compressing revenue recognition.
- Multi-protocol Integration Complexity:Chipset designers must simultaneously validate coexistence with Bluetooth 5.3, Thread, and Zigbee radios in smart home hub applications.
- RF Engineering Talent Scarcity:Millimeter-wave circuit design expertise concentrates among a small cohort of specialists in California and Massachusetts, inflating compensation and slowing hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Wi-Fi Chipset Market |
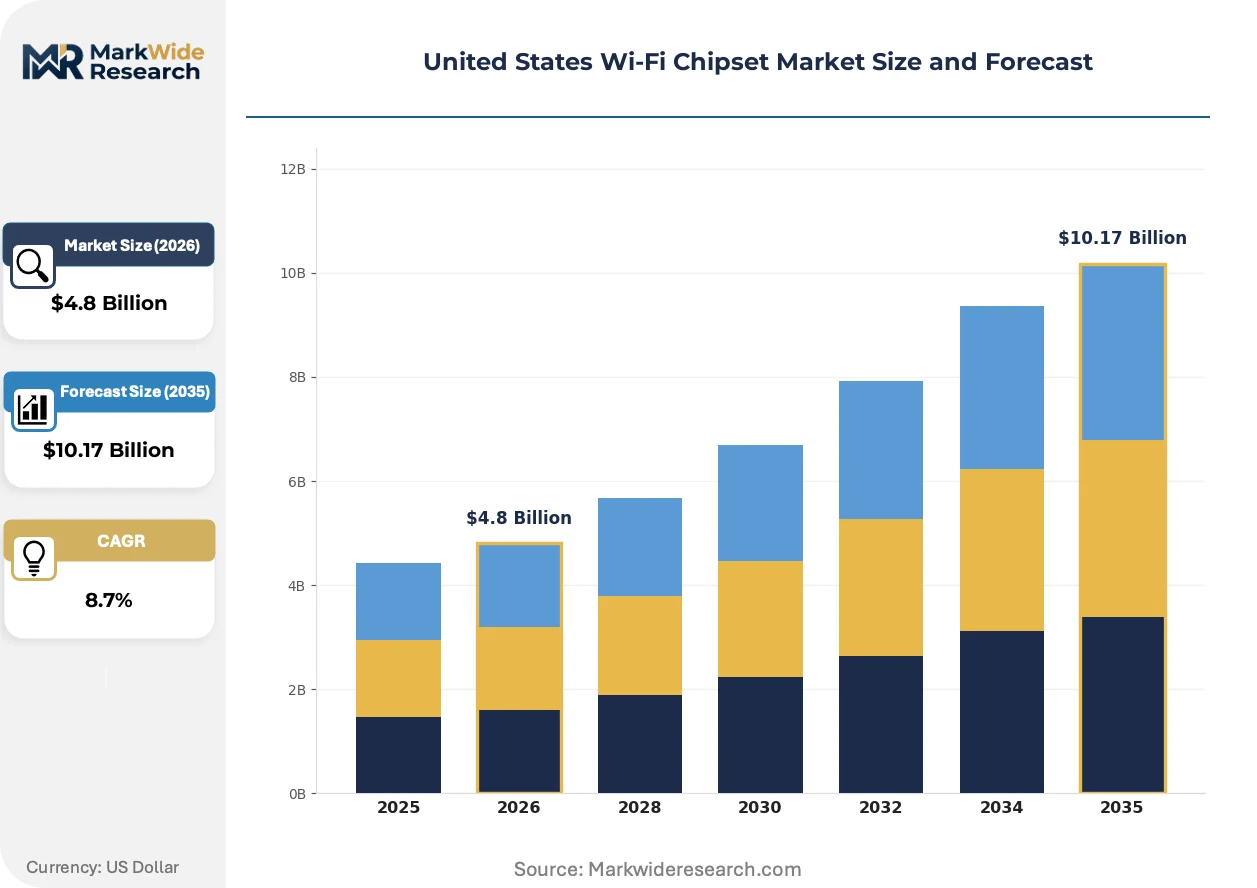
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Band Chipsets, Dual-Band Chipsets, Tri-Band Chipsets, Multi-Band Chipsets Technology: Wi-Fi 4, Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7 Application: Smartphones, Laptops, Smart Home Devices, Wearable Electronics, Networking Equipment End User: Original Equipment Manufacturers, Communication Service Providers, Consumer Electronics Companies, IoT Device Makers |
| Companies Covered | MediaTek, NXP Semiconductors, Qualcomm Technologies, Inc., Marvell Technology, Inc., Texas Instruments Incorporated, Broadcom, Realtek Semiconductor Corp, Semiconductor Components Industries, LLC, Intel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Wi-Fi Chipset Market Strategic Shifts & Innovations
American Wi-Fi chipset development is pivoting from throughput maximization toward deterministic latency guarantees, with architectural choices in the 2024-2025 product generation locking in competitive positioning for the remainder of the decade.
Multi-link operation technology is supplanting single-channel transmission in premium smartphone and laptop designs. Qualcomm and MediaTek have shipped silicon supporting simultaneous 5 GHz and 6 GHz links since late 2023. Enterprise access point vendors are now specifying MLO as mandatory for campus deployments, compressing demand for Wi-Fi 6 generation chipsets.
The FCC's April 2024 Further Notice of Proposed Rulemaking examines additional 6 GHz spectrum for very low power device categories. This proceeding would enable higher power density in wearables and AR glasses without interference to incumbent services. Chipset vendors are pre-positioning RF architectures to exploit any favorable ruling, with California design houses filing extensive technical comments.
Enterprise procurement teams are consolidating vendor relationships and demanding five-year firmware update guarantees as standard contract terms. This behavior shift favors incumbent chipset suppliers with established security response capabilities over new entrants. The phenomenon is most visible in federal government and healthcare verticals, where HIPAA and FISMA compliance requirements extend hardware lifecycle obligations.
United States Wi-Fi Chipset Market Segmentation
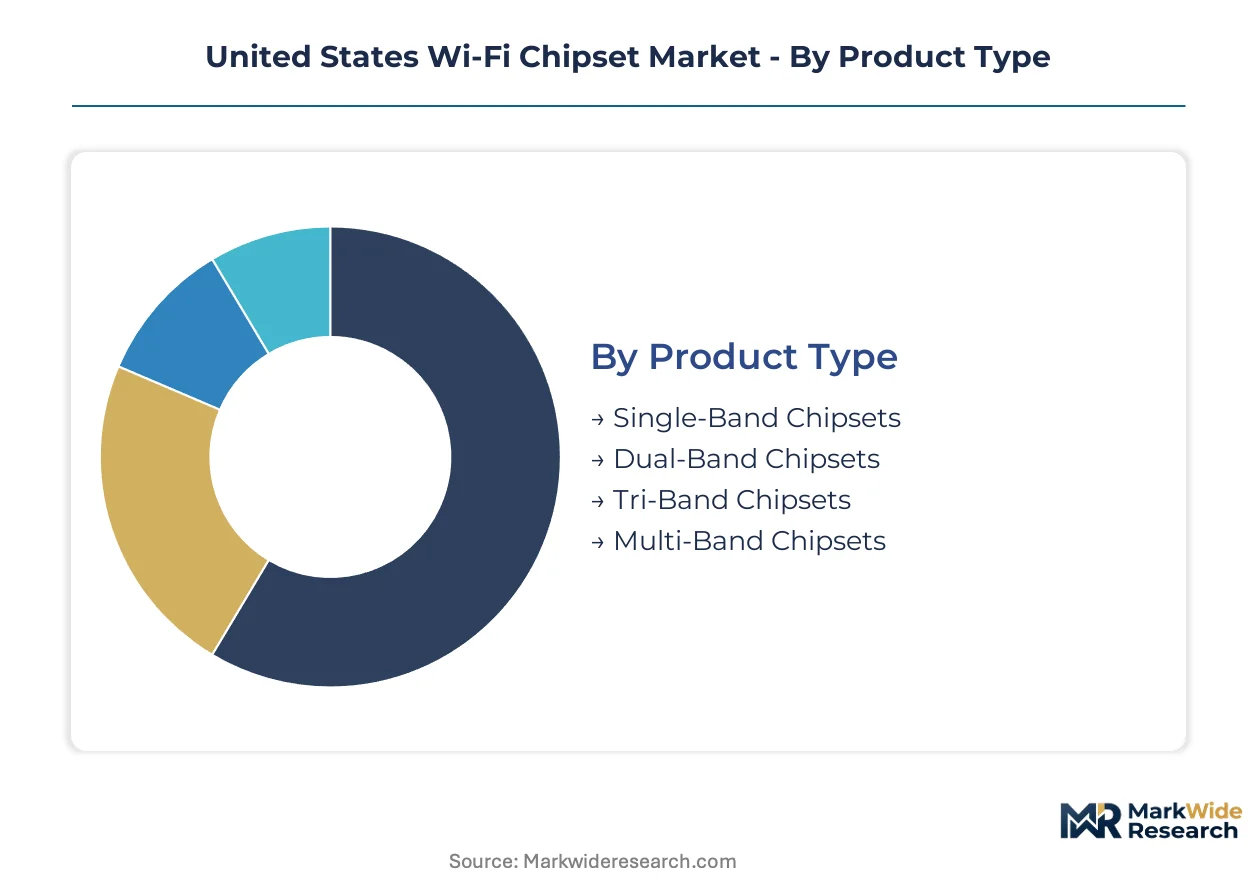
Wi-Fi chipset procurement patterns diverge sharply across product tiers and technology generations, with substitution pressure from cellular and wired alternatives reshaping investment priorities. OEMs now allocate silicon budgets based on latency requirements rather than throughput alone, fragmenting demand across divergent specification bands.
Product Type:
Multi-band architectures face acute substitution pressure from integrated cellular modems in premium mobile devices, while single-band legacy products confront obsolescence from mesh networking standards.
- Single-Band Chipsets:These 2.4 GHz-only devices integrate minimal RF front-end complexity for cost-constrained IoT sensors and legacy industrial controllers. Demand concentrates in Michigan automotive supplier networks where backward compatibility with existing plant infrastructure delays replacement cycles.
- Dual-Band Chipsets:Simultaneous 2.4 GHz and 5 GHz operation dominates mid-tier smartphone and tablet designs through mature 802.11ac silicon. Texas smart home hub manufacturers specify these chipsets for Thread border router applications where cost sensitivity outweighs 6 GHz readiness.
- Tri-Band Chipsets:2.4/5/6 GHz configurations serve enterprise access points and high-end residential mesh nodes. Northern Virginia data center campus networks drive procurement for outdoor fixed wireless backhaul.
- Multi-Band Chipsets:Dynamic frequency selection across four or more channels enables Wi-Fi 7 multi-link operation. Oregon hyperscale operators integrate these for edge compute facilities requiring deterministic latency below 5 milliseconds.
Dual-band chipsets anchor the volume base while multi-band variants gain share at the steepest rate.
Technology:
Generational transitions in this category map directly to margin tier stratification, with newer standards commanding premium positioning despite manufacturing cost convergence.
- Wi-Fi 4:802.11n silicon persists in price-sensitive smart home sensors and legacy enterprise IoT gateways. Ohio manufacturing facilities maintain extensive installed bases of 2.4 GHz predictive maintenance equipment.
- Wi-Fi 5:802.11ac wave 2 dominates mid-range laptop and tablet sockets through proven 1.7 Gbps throughput. Arizona semiconductor test facilities specify these chipsets for equipment calibration networks.
- Wi-Fi 6:OFDMA and 1024-QAM modulation improve spectral efficiency for dense enterprise deployments. California healthcare systems procure these for HIPAA-compliant clinical device networks.
- Wi-Fi 6E:Full 6 GHz spectrum access enables 160 MHz channel bonding with minimal interference. Massachusetts AR hardware startups specify these for wireless VR tethering prototypes.
- Wi-Fi 7:320 MHz channels and 4K-QAM deliver multi-gigabit throughput for gaming and immersive computing. Washington state cloud infrastructure operators deploy these for campus backbone upgrades.
Wi-Fi 6 silicon anchors current procurement volumes while Wi-Fi 7 expands most quickly among latency-sensitive applications.
Application:
Device category requirements fragment along power-consumption versus throughput axes, with no single application dominating procurement value.
- Smartphones:Premium handsets integrate Wi-Fi 7 basebands with cellular modem co-packaging for seamless carrier aggregation. California design houses prioritize modem-RF system integration for flagship socket wins.
- Laptops:Enterprise notebook refresh cycles concentrate procurement in Q3-Q4 corporate IT budgets. Texas enterprise procurement teams demand five-year firmware update guarantees as standard terms.
- Smart Home Devices:Thermostats, cameras, and voice assistants optimize for standby power below 50 milliwatts. Illinois utility smart grid pilots stimulate demand for Wi-Fi 6E in distributed energy resource management.
- Wearable Electronics:Fitness trackers and smartwatches require ultra-low-power 2.4 GHz-only silicon. FCC very low power 6 GHz proceedings could unlock tri-band architectures for AR glasses.
- Networking Equipment:Enterprise access points and residential mesh nodes prioritize throughput density and thermal management. Virginia federal government contracts mandate FISMA-compliant security update lifecycles.
Smartphones generate the highest unit volumes while networking equipment commands the steepest technology premium.
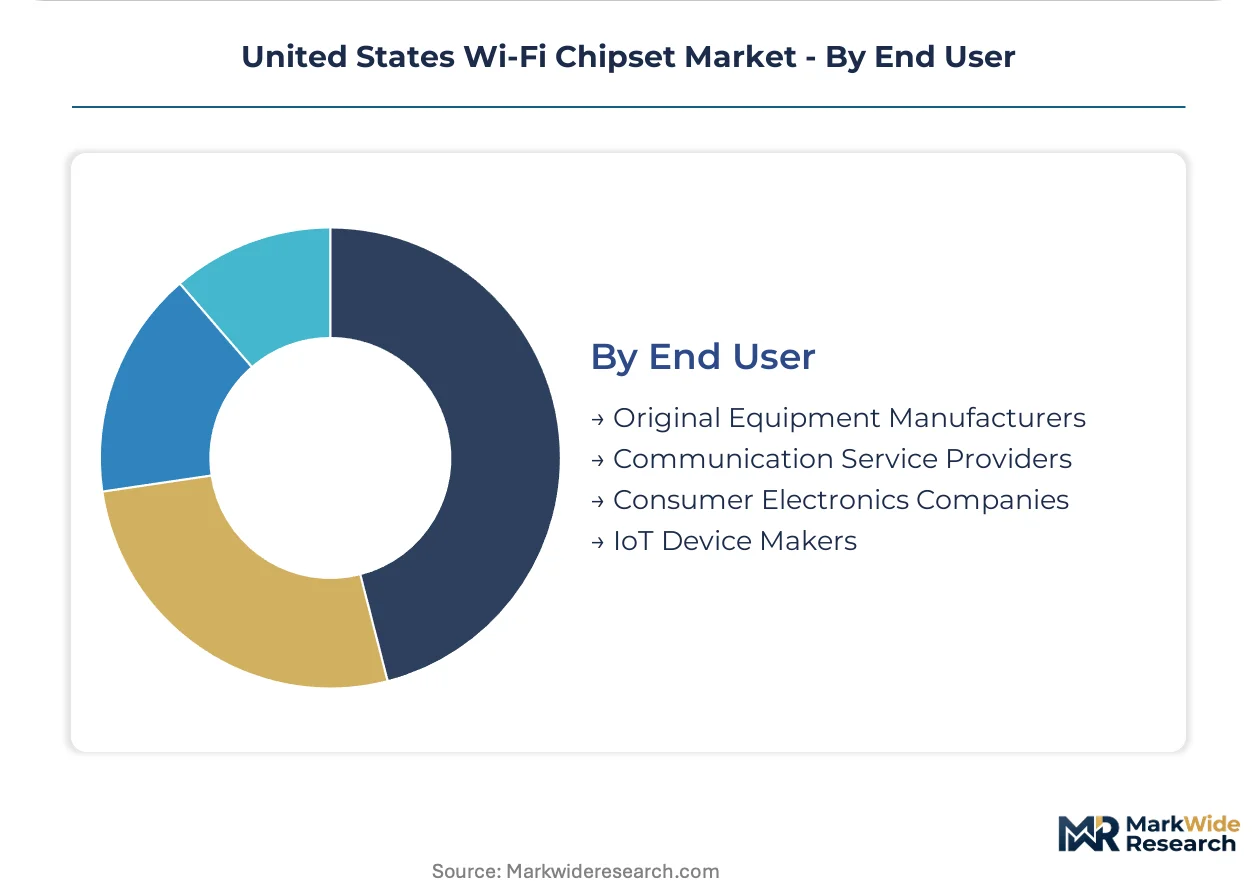
End User:
Customer type determines procurement sophistication, with direct OEM relationships favoring incumbent suppliers and service providers driving interoperability certification requirements.
- Original Equipment Manufacturers:Smartphone and laptop OEMs specify chipsets 18-24 months ahead of product launch. California and Texas design teams co-locate with semiconductor vendors for joint architecture development.
- Communication Service Providers:Fixed wireless access deployments drive outdoor-rated 6 GHz silicon procurement. Rural broadband initiatives in Montana and Idaho specify carrier-grade temperature tolerances.
- Consumer Electronics Companies:Smart TV and streaming device manufacturers prioritize cost-optimized dual-band solutions. Content protection requirements from major studios influence security subsystem selection.
- IoT Device Makers:Industrial sensor vendors demand 10-year availability guarantees for single-band legacy silicon. Automotive Tier 1 suppliers in Detroit specify AEC-Q100 qualified variants for connected vehicle gateways.
Original equipment manufacturers anchor design-in volumes while communication service providers drive the steepest certification and testing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic foundry capacity concentrates in Texas and Arizona, where Intel and Samsung have committed multi-billion dollar investments. These facilities will process 6nm and 4nm wafers for next-generation baseband processors. Regional procurement patterns track closely to semiconductor design clusters and hyperscale data center footprints.
California
Silicon Valley design houses drive premium Wi-Fi 7 development for smartphone and AR headset applications. The California Air Resources Board enforces strict e-waste regulations that influence packaging material selection for fabless vendors. San Jose and Santa Clara host co-located engineering teams from Qualcomm and Broadcom working on modem-RF integration.
Texas
Austin and Dallas semiconductor clusters attract backend testing and packaging operations for Wi-Fi chipset vendors. The Texas Enterprise Fund provides incentives for advanced manufacturing facilities serving the domestic supply chain. Samsung's Taylor foundry will produce 4nm silicon for wireless baseband processors starting in 2025.
Arizona
Intel's Ocotillo campus in Chandler anchors the most advanced domestic logic fabrication for Wi-Fi chipsets. The state tax credit program for semiconductor equipment investment reduces capital intensity for new foundry entrants. Phoenix-area facilities will supply 6nm process nodes for enterprise access point silicon.
Virginia
Northern Virginia data center corridors generate concentrated demand for tri-band chipsets in campus backbone networks. The Commonwealth's broadband expansion program funds fixed wireless access deployments using 6 GHz outdoor-rated equipment. Loudoun County hyperscale operators specify Wi-Fi 7 for edge compute facilities requiring sub-5ms latency.
Oregon
Portland-area semiconductor test facilities validate RF performance for Wi-Fi 6E and Wi-Fi 7 product generations. The Oregon Business Development Department coordinates workforce training for millimeter-wave engineering talent. Hillsboro infrastructure supports pre-certification testing that compresses product launch timelines for fabless designers.
United States Wi-Fi Chipset Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the United States Wi-Fi Chipset Market. Premium-tier suppliers dominate smartphone and enterprise access point sockets through modem-RF integration and custom ARM core architectures. Mid-tier vendors compete on price-performance for smart home and IoT gateway applications. Strategic moves concentrate on foundry partnerships for advanced node access and multi-protocol certification to capture smart home hub sockets.
Among Taiwan-based semiconductor designers, MediaTek and Realtek Semiconductor Corp occupy positions serving cost-optimized consumer electronics and networking equipment segments. Qualcomm Technologies, Inc. exemplifies the premium-tier archetype through its dominance in smartphone modem-RF system integration. These three companies represent the primary competitive anchors shaping procurement dynamics across dual-band, tri-band, and multi-band product tiers.
| Leading Market Players |
|---|
| MediaTek |
| NXP Semiconductors |
| Qualcomm Technologies, Inc. |
| Marvell Technology, Inc. |
| Texas Instruments Incorporated |
| Broadcom |
| Realtek Semiconductor Corp |
| Semiconductor Components Industries, LLC |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with domestic foundries lock in wafer access for fabless Wi-Fi designers while providing price visibility across multi-year procurement cycles. These arrangements concentrate pricing power among buyers with sufficient volume commitments to secure allocation at Intel's Arizona and Samsung's Texas facilities.
Pricing Analysis
FCC Part 15 rules dictate the pricing tier structure across unlicensed spectrum device categories. Certification-grade Wi-Fi 7 silicon commands premium positioning over uncertified pre-production samples, while volume scale separates enterprise procurement from consumer electronics orders. Cost compression in dual-band legacy tiers intensifies because smartphone OEMs are consolidating socket awards to fewer suppliers. IoT gateway manufacturers exhibit the highest price sensitivity, whereas hyperscale data center operators prioritize latency performance over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced node Wi-Fi baseband processors, while the United States supplies specialty RF front-end materials. Gallium arsenide substrates and silicon germanium wafers feed into power amplifier modules. Single-source vulnerability concentrates in 4nm EUV lithography capacity. Distribution runs through direct OEM partnerships and authorized component distributors serving the electronics manufacturing services sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Wi-Fi Chipset Market is entering a cyclical recovery phase as enterprise refresh cycles accelerate following the FCC's 6 GHz allocation completion. Foundry capacity expansion in Texas and Arizona provides the supply-side foundation for this upturn.
For Market Incumbents: Secure captive foundry allocation at Intel's Ocotillo campus and Samsung's Taylor facility to defend against supply-constrained new entrants. Deepen backward integration into custom ARM core architectures for enterprise access point silicon. Prioritize Wi-Fi Alliance certification investments to maintain interoperability leadership against emerging fabless competitors. For New Entrants and Emerging Players: Lead with industrial IoT gateway applications in Michigan and Ohio manufacturing corridors where legacy 802.11n replacement cycles create white-space demand. Target single-band sensor markets where cost-optimized designs face minimal incumbent saturation. Establish joint development partnerships with Arizona semiconductor test facilities to compress pre-certification timelines. For Investors and Strategic Acquirers: Fabless design houses with established RF engineering teams in California and Massachusetts represent the most attractive acquisition archetype for portfolio diversification. Monitor FCC proceedings on additional 6 GHz spectrum allocation as the inflection indicator for Wi-Fi 7 volume scaling. Long-term viability hinges on multi-protocol integration capabilities spanning Thread, Zigbee, and Bluetooth coexistence.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Partnership | Secures 4nm wafer allocation at Intel's Arizona facility for Wi-Fi 7 baseband production. |
| Multi-Link Operation Certification | Enables simultaneous 5 GHz and 6 GHz transmission for premium smartphone socket wins. |
| RF Front-End Vertical Integration | Captures gallium arsenide substrate supply for power amplifier margin control. |
| Industrial IoT Gateway Expansion | Captures Michigan automotive supplier demand for predictive maintenance connectivity. |
| FCC Regulatory Engagement | Positions architectures for favorable 6 GHz very low power device rulings. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FCC rulemaking dockets, IEEE 802.11 standards documentation, and SEC semiconductor company filings. Semiconductor design executives, RF engineering directors, enterprise IT procurement managers, and foundry operations leads provided qualitative input. Bottom-up unit shipment estimates triangulate against top-down wafer consumption data from domestic fabrication facilities.
Segmentation dimensions modeled include product architecture, IEEE protocol generation, device application category, and end-user procurement sophistication across the projection horizon. CAGRs derive from regression analysis of historical chipset shipment patterns against foundry capacity expansion schedules. Forecast inputs incorporate FCC spectrum allocation timelines and Wi-Fi Alliance certification program throughput constraints.
Forecasts assume regulatory continuity in FCC Part 15 unlicensed device rules and EPA e-waste directives; material policy shifts would require re-modeling. Specific risks include export control tightening on advanced node manufacturing equipment and gallium arsenide supply disruption from defense sector demand spikes. Recalibration cycles align with material shifts in foundry utilization rates and spectrum allocation proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Car Chip Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Tablet Application Processor Market